
 Solid State Array Market | 2026-2036
Solid State Array Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Array Market Outlook
Leasing and asset-light infrastructure models are narrowing the capital barrier for mid-tier cloud providers to deploy enterprise-grade solid state arrays. Samsung Electronics leverages captive NAND fabrication to sustain cost advantages across high-density storage tiers. SK hynix anchors supply continuity through vertical control over advanced memory processes. Micron Technology differentiates via R&D intensity in 3D NAND architectures for data-intensive workloads.
A solid state array is an integrated assembly of solid-state memory cells—typically NAND flash organized in 3D layers with charge-trap or floating-gate cell designs—engineered for persistent data storage without mechanical moving parts. These arrays deliver sub-millisecond latency and terabyte-scale density for enterprise data centers, edge computing nodes, and high-performance computing clusters. Embedded arrays occupy the mature volume tier where standardization compresses margins, while configurable arrays capture premium pricing through firmware-defined adaptability for signal processing and control systems. Application-specific arrays represent the fastest-expanding segment as aerospace and industrial automation buyers demand radiation-hardened and temperature-extreme variants.
FDA cybersecurity guidance for connected medical devices indirectly shapes solid state array specifications in healthcare IT infrastructure, while EPA energy efficiency standards constrain data center power budgets that storage procurement must satisfy. NHTSA automotive safety regulations are accelerating solid-state storage adoption for autonomous vehicle sensor logging and black-box recorders. Stakeholders must monitor how evolving ISO data integrity standards and sector-specific certification requirements will reshape supplier qualification timelines and product roadmaps.
Market Dynamics
Hyperscale data center operators in the United States are expanding procurement of solid state arrays for AI training workloads, compressing supplier lead times and concentrating volume with vertically integrated NAND fabricators.
Growth Catalysts
- AI Training Infrastructure:Hyperscale data center operators are expanding procurement of high-density solid state arrays for machine learning model training, concentrating demand with vertically integrated NAND fabricators.
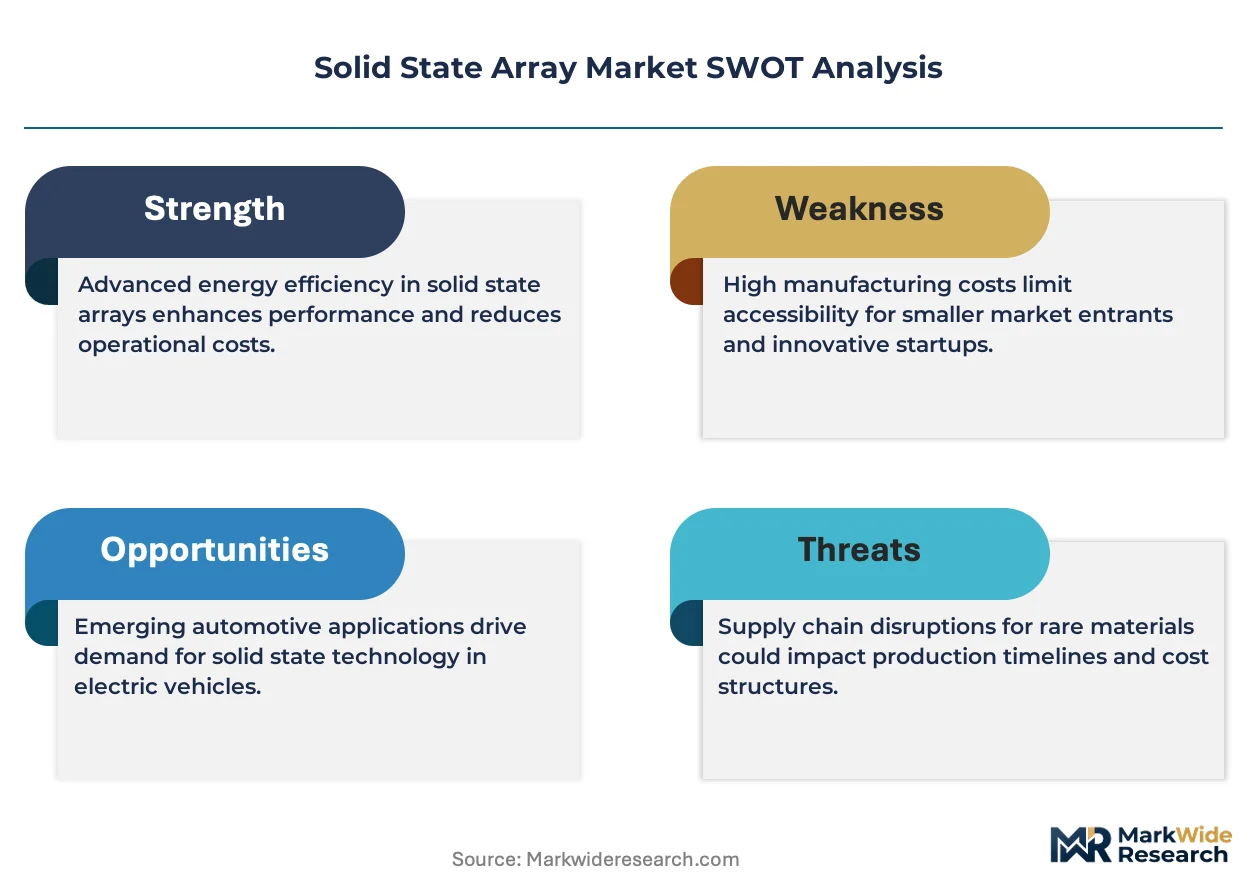
- EU Green Deal:The EU Green Deal and emerging e-waste directives are tightening energy efficiency standards, accelerating replacement cycles for legacy mechanical storage in European enterprise data centers.
- Automotive Sensor Logging:NHTSA automotive safety regulations are mandating solid-state storage adoption for autonomous vehicle black-box recorders and sensor data logging systems.
Market Restraints
- NAND Flash Supply Concentration:Advanced fabrication capacity concentrates in South Korea, creating geographic single-point-of-failure risk for downstream array assemblers.
- Energy Efficiency Standards:EPA energy efficiency standards constrain data center power budgets, limiting storage procurement flexibility for facility operators.
- Mechanical Storage Substitution:Tape and hard disk drive archives retain cost advantages for cold data tiers, compressing solid state array addressable volume in long-term retention applications.
Strategic Opportunities
- Edge Computing Deployment:Industrial automation and aerospace buyers are demanding radiation-hardened and temperature-extreme solid state array variants for distributed edge nodes.
- Leasing Models:Asset-light infrastructure models are narrowing capital barriers for mid-tier cloud providers to deploy enterprise-grade solid state arrays without direct ownership.
- Healthcare IT Expansion:FDA cybersecurity guidance for connected medical devices is indirectly shaping solid state array specifications in hospital infrastructure procurement.
Industry Challenges
- Firmware Talent Scarcity:Qualified engineers for signal processing and control system integration remain scarce, extending product development timelines for configurable array tiers.
- ISO Certification Complexity:Evolving ISO data integrity standards are reshaping supplier qualification timelines and forcing roadmap recalibration across embedded array manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Array Market |
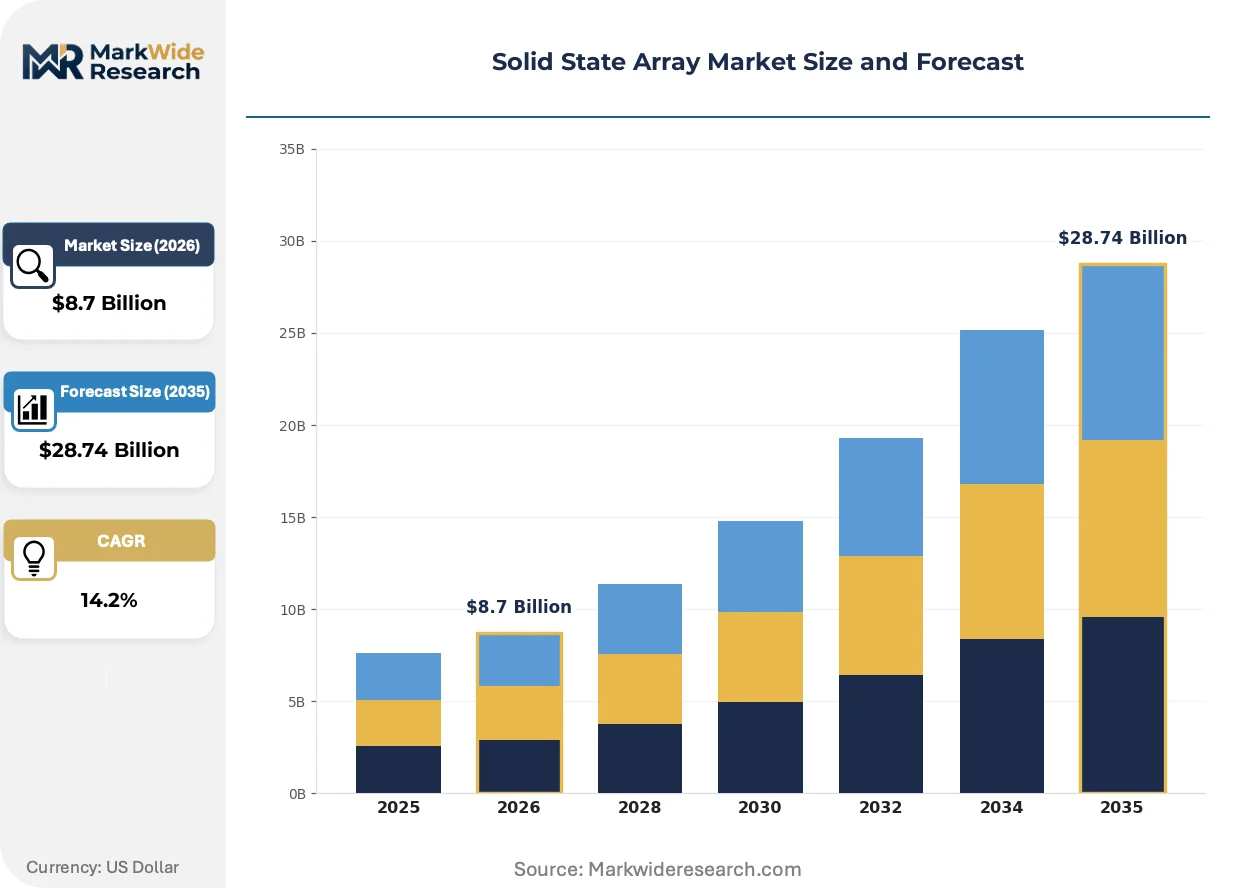
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Arrays, Configurable Arrays, Digital Arrays, Application-Specific Arrays Technology: Charge-Coupled Devices, Voltage-Controlled Oscillators, Capacitive Sensors, Photodiodes End User: Telecommunications, Consumer Electronics, Aerospace, Industrial Automation Application: Data Storage, Signal Processing, Imaging, Control Systems |
| Companies Covered | Kioxia, Solidigm, Samsung Electronics, ADATA Technology, Kingston Technology, SK hynix, Western Digital, Seagate Technology, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Array Market Strategic Shifts
Storage architecture is hybridizing across charge-trap and floating-gate cell designs as buyers demand firmware-defined adaptability for signal processing workloads.
3D NAND with charge-trap cell architecture is displacing floating-gate designs in high-density tiers, delivering superior endurance for data-intensive workloads. Hyperscale operators are adopting these arrays at compressed procurement cycles, prioritizing terabyte-scale density over legacy cost-per-gigabyte metrics. The technology is hybridizing storage and compute boundaries, enabling in-array processing for AI inference at the edge.
EU Green Deal e-waste directives are tightening recyclability standards for semiconductor storage devices, forcing design-for-disassembly into product roadmaps. Array manufacturers must now certify material recovery rates and eliminate hazardous substances under REACH constraints. European enterprise buyers are prioritizing suppliers with documented circular economy compliance, shifting procurement weight toward vertically integrated fabricators with captive recycling infrastructure.
Leasing and subscription-based consumption models are displacing capital purchase cycles among mid-tier cloud providers. Channel partners are unbundling hardware ownership from operational support, offering firmware-managed capacity as a metered service. This shift concentrates most visibly in United States colocation markets where facility operators seek to preserve balance-sheet flexibility for AI infrastructure expansion.
Solid State Array Market Segmentation

Solid state array procurement patterns diverge sharply across product architectures and deployment contexts. Understanding these divides reveals where firmware customization, density premiums, and regulatory compliance reshape supplier selection criteria.
Product Type:
After-sales firmware support intensity separates embedded from configurable tiers, with application-specific variants demanding the most intensive field engineering engagement.
- Configurable Arrays:Firmware-defined adaptability enables signal processing workload optimization through programmable control planes. Hyperscale data center operators in the United States concentrate procurement here for AI training infrastructure, prioritizing terabyte-scale density over legacy cost metrics.
- Application-Specific Arrays:Radiation-hardened and temperature-extreme variants serve aerospace and industrial automation buyers deploying distributed edge nodes. This segment captures premium pricing through qualification timelines that generic arrays cannot satisfy.
- Embedded Arrays:Standardized designs compress margins in mature volume tiers where charge-trap cell architectures dominate.
- Digital Arrays:Binary-state cell configurations address cost-sensitive cold storage applications with reduced endurance requirements.
By volume, Embedded Arrays leads. By growth pace, Application-Specific Arrays is climbing the fastest.
Technology:
Cell design selection directly determines endurance specifications and power consumption profiles across deployment environments.
- Charge-Coupled Devices:Signal transfer efficiency enables high-fidelity imaging pipelines in medical and scientific instrumentation. South Korean fabrication clusters anchor supply continuity for these precision-tier components.
- Photodiodes:Light-to-current conversion sensitivity supports optical data link architectures in telecommunications infrastructure. European enterprise buyers prioritize suppliers with documented circular economy compliance under EU Green Deal directives.
- Voltage-Controlled Oscillators:Frequency modulation precision serves timing-critical control systems in automotive sensor logging applications.
- Capacitive Sensors:Proximity detection capabilities integrate into touch-enabled consumer electronics interfaces with stringent power budgets.
Charge-Coupled Devices dominates revenue contribution. Photodiodes posts the steepest expansion trajectory driven by optical networking buildouts.
End User:
Regulatory exposure intensity varies dramatically across buyer categories, from FDA cybersecurity guidance in healthcare-adjacent telecommunications to NHTSA mandates in automotive-adjacent industrial automation.
- Telecommunications:5G infrastructure deployment concentrates demand for low-latency storage tiers in baseband processing units. EPA energy efficiency standards constrain facility power budgets that storage procurement must satisfy.
- Aerospace:Radiation-hardened qualification requirements extend supplier timelines but lock in multi-year sole-source relationships. ISO data integrity standards reshape product roadmaps for mission-critical flight systems.
- Industrial Automation:Temperature-extreme variants serve distributed edge nodes in manufacturing environments with limited climate control.
- Consumer Electronics:Cost compression dominates procurement, with standard NAND flash configurations meeting volume price points.
Telecommunications generates the largest absolute demand. Aerospace commands the highest unit margins through qualification barriers.
Application:
Workload characteristics dictate whether density, latency, or computational proximity determines array specification priorities.
- Data Storage:Persistent retention without mechanical parts serves enterprise data centers and edge computing nodes. Leasing models are narrowing capital barriers for mid-tier cloud providers in United States colocation markets.
- Signal Processing:In-array compute capabilities enable AI inference at the edge, hybridizing storage and processing boundaries. Firmware talent scarcity extends development timelines for these configurable tiers.
- Imaging:High-throughput data pipelines demand charge-coupled device architectures with minimal read noise.
- Control Systems:Deterministic latency requirements serve autonomous vehicle black-box recorders under NHTSA safety regulations.
Data Storage anchors volume shipment. Signal Processing gains share fastest as edge AI deployment accelerates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators and automotive electronics manufacturers concentrate procurement across four distinct national markets. Each geography presents unique regulatory constraints and fabrication cluster dynamics that reshape supplier selection criteria.
United States
Hyperscale AI training infrastructure drives procurement concentration among cloud operators in Northern Virginia and Dallas-Fort Worth metroplexes. EPA energy efficiency standards constrain data center power budgets, forcing storage procurement to satisfy strict thermal thresholds. San Jose anchors NAND flash design engineering while Phoenix hosts advanced packaging facilities serving defense-aerospace buyers.
South Korea
Captive NAND fabrication clusters in Pyeongtaek and Icheon supply vertically integrated array manufacturers serving global hyperscale demand. The country's national semiconductor regulator enforces supply chain security protocols under the K-Semiconductor Belt initiative. Samsung Electronics and SK hynix dominate advanced memory process control, compressing supplier lead times for downstream assemblers.
Germany
Automotive sensor logging mandates under KBA safety regulations accelerate solid-state storage adoption for autonomous vehicle black-box systems. EU Green Deal e-waste directives enforce recyclability standards that reshape design-for-disassembly roadmaps. Dresden's Silicon Saxony cluster concentrates wafer fabrication serving industrial automation and medical device manufacturers.
Japan
Industrial automation and robotics manufacturers in Aichi and Kanagawa prefectures demand temperature-extreme array variants for factory floor deployment. METI semiconductor strategy documents prioritize domestic supply chain resilience for critical memory components. Yokohama hosts system integrators qualifying radiation-hardened arrays for aerospace satellite programs.
China
Domestic cloud operators and telecom infrastructure builders in Yangtze River Delta cities expand procurement of locally fabricated NAND modules. MIIT standards mandate data localization for government and financial sector storage deployments. Wuhan and Hefei anchor emerging memory fabrication clusters competing on cost-adjusted density metrics.
Solid State Array Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered pricing bands defined by firmware customization depth and qualification timeline intensity. The vendor base separates into three strategic archetypes: vertically integrated fabricators with captive NAND supply, modular array assemblers sourcing merchant memory, and application-specific specialists serving radiation-hardened niches. M&A activity concentrates on firmware engineering talent acquisition, while capacity expansion focuses on advanced packaging facilities for high-density tiers.
Among vertically integrated fabricators, Samsung Electronics, SK hynix, and Micron Technology exemplify the scale-driven archetype that anchors global supply continuity. These South Korea and US-based entities occupy positions where captive control over advanced memory processes determines competitive positioning in hyperscale procurement cycles. Their market presence represents the benchmark against which merchant memory assemblers calibrate cost and density specifications.
| Leading Market Players |
|---|
| Kioxia |
| Solidigm |
| Samsung Electronics |
| ADATA Technology |
| Kingston Technology |
| SK hynix |
| Western Digital |
| Seagate Technology |
| Micron Technology |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese NAND fabrication is compressing spot pricing for commodity-grade modules while tightening margins for merchant assemblers. This utilization imbalance concentrates pricing power with vertically integrated South Korean fabricators who control advanced process nodes.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO data integrity and REACH-compliant variants commanding substantial premiums over generic embedded arrays. Three-tier pricing structure across premium, standard, and economy levels reflects firmware customization depth and qualification timeline intensity. Pricing pressure stems from Chinese cost-adjusted density competition flooding the merchant memory tier. Mid-tier cloud providers exhibit highest price sensitivity through leasing model adoption, while aerospace buyers prioritize qualification certainty over unit economics.
Supply Chain Analysis
Upstream silicon wafer supply draws from South Korean, Taiwanese, and Japanese fabrication clusters serving the NAND flash substrate tier. Advanced lithography equipment and specialty gases represent critical input dependencies with limited qualified suppliers. Single-source vulnerability concentrates in extreme ultraviolet lithography systems where ASML holds effective monopoly. Distribution runs through direct hyperscale procurement contracts and channel partners serving mid-market colocation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid state array demand tracks the semiconductor capital expenditure cycle, with AI infrastructure buildouts extending the current upswing beyond typical three-year patterns.
For Market Incumbents: Harden supply continuity through captive advanced packaging capacity in Phoenix and Pyeongtaek against geopolitical disruption risks. Deepen firmware engineering benches to address talent scarcity extending development timelines for configurable array tiers. Prioritize REACH certification maintenance to defend European enterprise procurement relationships under tightening EU Green Deal enforcement.
For New Entrants and Emerging Players: Radiation-hardened aerospace variants with multi-year qualification barriers represent the most penetrable entry point for specialists without hyperscale scale requirements. Industrial automation temperature-extreme edge nodes in Japan and Germany offer secondary white-space with less incumbent concentration. Partner with system integrators in Yokohama and Dresden to bypass direct qualification timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-managed capacity providers offering metered service models to United States colocation operators. Long-term viability favors acquisition targets with demonstrated circular economy compliance and captive recycling infrastructure under EU directives. Monitor hyperscale capex disclosure patterns as the inflection indicator for procurement cycle turns.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Engineering Acquisition | Addresses talent scarcity compressing development timelines for configurable array tiers. |
| Advanced Packaging Facility Expansion | Captures density premiums from 3D NAND stacking demand in Phoenix and Pyeongtaek clusters. |
| REACH Compliance Certification | Secures European enterprise procurement preference under EU Green Deal e-waste directives. |
| Leasing Model Infrastructure Buildout | Converts capital-sensitive mid-tier cloud providers to recurring revenue relationships. |
| Radiation-Hardened Qualification Investment | Locks in multi-year sole-source aerospace contracts with mission-critical flight systems. |
Study Parameters
Cross-validation between hyperscaler procurement disclosures and NAND flash wafer output data anchors the qualitative findings. Primary interviews with data center infrastructure directors, storage procurement officers, and firmware engineering leads informed demand-side dynamics. Secondary sources include SEC 10-K filings, EPA energy efficiency compliance databases, and EU ECHA substance restriction registers. Bottom-up shipment estimates triangulate against top-down fabrication capacity utilization reported by South Korean and Taiwanese equipment suppliers.
Calibration against historical cyclical patterns and AI training infrastructure deployment schedules shapes the projection framework. Segmentation dimensions span product architecture, cell design technology, end-user industry vertical, and regional regulatory cluster. CAGRs derive from slope analysis across the modeling period with sensitivity testing for NAND flash price elasticity and hyperscale capex volatility. Forecast inputs incorporate EU Green Deal implementation timelines and NHTSA automotive safety mandate phase-ins.
Stress conditions across NAND flash oversupply scenarios, geopolitical trade restriction intensification, and AI demand deceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology transition pacing and regulatory enforcement consistency. Cross-checking against SEMI equipment billings and hyperscaler earnings call commentary is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
All Flash Storage Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Universal Flash Storage Market
Data Storage
Storage Virtualization Market
Data Storage
Australia Data Center Storage Market
Data Storage
Data Storage Market
Data Storage
Ireland Data Center Storage Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Americas Flash Memory Market
Data Storage
NAND Flash Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Flash Memory Market
Data Storage
Ethernet Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Data Center Ssds Market
Data Storage
SSD Controller Market