
 Hardware Storage Market | 2026-2036
Hardware Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware Storage Market Intelligence
The FIPS 140-3 cryptographic module validation standard is redrawing the competitive landscape for secure storage solutions in government and financial sectors. Seagate Technology Holdings plc leverages its manufacturing scale in hard disk drives to serve hyperscale clients. Dell Technologies differentiates through its integrated server and storage area network solutions. Pure Storage specializes in all-flash arrays, targeting high-performance computing and enterprise database workloads.
Hardware storage encompasses physical media devices designed for the persistent retention and retrieval of digital data. These devices utilize technologies ranging from magnetic platters in Hard Disk Drives (HDDs) to NAND flash memory cells in Solid State Drives (SSDs). Solid State Drives lead in performance-critical applications, while Hard Disk Drives offer superior economics for bulk storage in data centers. The NVMe technology interface shows the highest growth, displacing legacy protocols like SATA in new system designs.
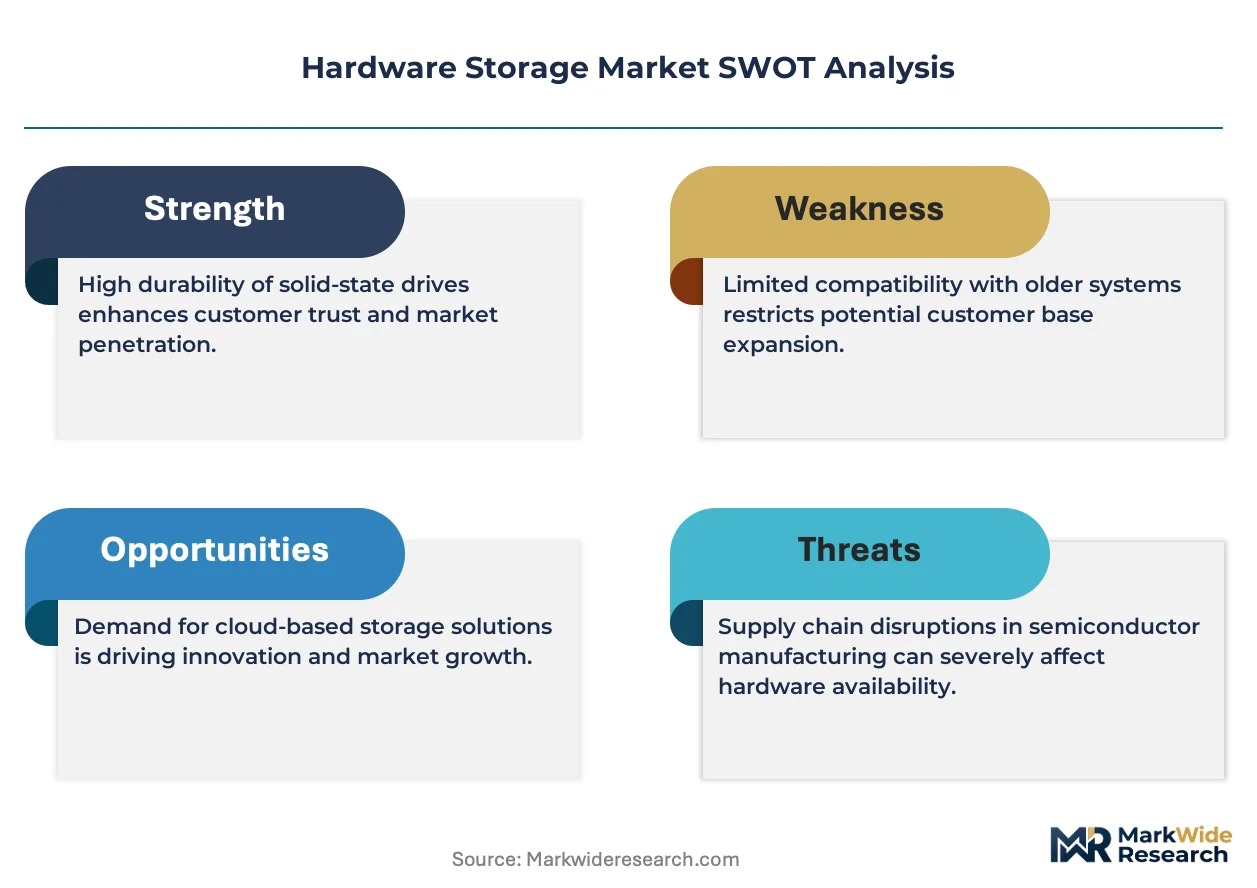
Data sovereignty and privacy mandates, including Europe's GDPR and the US HIPAA, compel localized storage infrastructure deployments for regulated industries. Concurrently, hardware-level specifications like China's GB standards and the EU's RoHS directive govern material composition and e-waste management for storage devices. Vendors must now navigate a complex decision matrix balancing performance requirements against regional regulatory compliance and supply chain security.
Market Dynamics
The architectural divergence between high-performance and high-capacity storage solutions defines market dynamics. This split is driven by the simultaneous demands for real-time data processing using NVMe technology and the economic imperative for mass data archiving on traditional hard disk drives.
Growth Catalysts
- Artificial Intelligence Workloads:The proliferation of AI and machine learning applications requires massive, high-throughput datasets for model training, directly fueling demand for all-flash arrays and NVMe-based storage systems.
- China's Digital Infrastructure:Government-led initiatives in China to build out national data centers and enforce data localization policies are creating a concentrated pool of demand for all types of hardware storage.
- Hyperscale Cloud Expansion:Major cloud service providers are continuously expanding their global data center footprints to reduce latency and comply with data sovereignty rules, representing a primary source of volume demand for both SSDs and HDDs.
Market Restraints
- NAND Price Volatility:The cyclical nature of NAND flash memory pricing creates significant cost uncertainty for SSD manufacturers and enterprise buyers, impacting procurement cycles and gross margins.
- Power and Cooling Constraints:High-density flash storage arrays generate substantial heat, posing significant power consumption and thermal management challenges for data center operators, which can limit deployment scale.
- Component Supply Concentration:The manufacturing of critical HDD components, such as read/write heads and media platters, is highly concentrated in a few facilities in Southeast Asia, exposing the supply chain to geopolitical and logistical risks.
Strategic Opportunities
- Edge Computing Storage:The growth of industrial IoT and autonomous systems creates an opportunity for ruggedized, small-form-factor storage devices designed for data capture and processing at the network edge, outside traditional data centers.
- Archival Storage Innovation:Developing novel, ultra-long-term storage media, such as synthetic DNA or glass-based technologies, presents a future opportunity to address the archival needs of scientific research and cultural preservation.
- FIPS 140-3 Certification:Obtaining FIPS 140-3 validation for storage devices with hardware-based encryption opens access to high-margin contracts within the US government, defense, and regulated financial sectors.
Industry Challenges
- Regulatory Compliance Fragmentation:Vendors must manage a complex web of regional environmental regulations, including the EU's RoHS directive on hazardous substances and China's GB standards for electronics, increasing design and logistics costs.
- Legacy System Integration:Enterprises face significant technical hurdles and costs when integrating modern NVMe-oF storage fabrics with their existing investments in legacy Fibre Channel and iSCSI storage area networks.
- Firmware Security Talent:A persistent shortage of engineers with dual expertise in low-level hardware programming and modern cybersecurity practices complicates the development of verifiably secure storage controllers and firmware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware Storage Market |
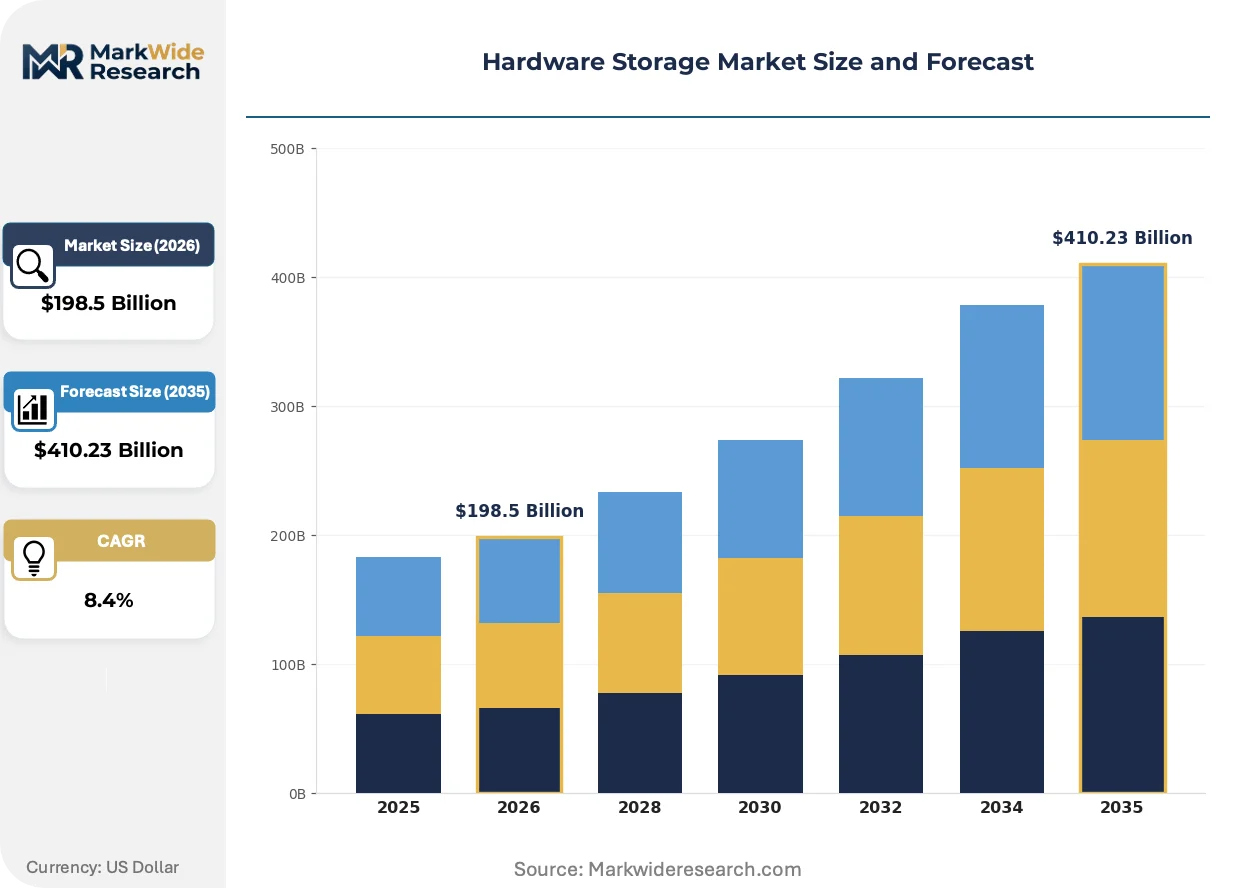
| Market Size in 2026 | $198.5 Billion |
| Market Size in 2035 | $410.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Network Attached Storage, Storage Area Network, Optical Drives, Tape Drives Technology: SATA, SAS, NVMe, Fibre Channel, iSCSI, Thunderbolt Application: Data Centers, Cloud Infrastructure, Media & Entertainment, Telecommunications, Government Facilities, Scientific Research End User: Telecom Operators, Financial Institutions, Educational Institutions, Manufacturing Firms, Energy Providers, Public Sector Agencies |
| Companies Covered | Seagate Technology Holdings plc, NetApp, Dell Technologies, Hitachi Vantara, Pure Storage, Hewlett Packard Enterprise, Western Digital Corporation, VMware, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware Storage Market Strategic Shifts & Innovations
The hardware storage market is being reshaped by software-defined architectures that abstract physical devices, enabling more flexible and efficient resource pooling. This allows infrastructure to be tailored to specific application performance profiles, from latency-sensitive databases to capacity-oriented analytics.
Computational Storage Drives (CSDs) embed processing units like FPGAs or ASICs directly within the storage device. Hyperscale cloud operators and scientific computing clusters are early adopters, using CSDs to accelerate tasks like compression, encryption, and database queries. This technology is bifurcating the market into commodity drives and specialized, intelligent storage that offloads tasks from host servers.
Data sovereignty regulations, including Europe's GDPR and various national data protection acts, are a powerful force. These rules require organizations to maintain data on citizens within specific geographic borders, preventing unrestricted data flows. The cloud infrastructure segment is most impacted, responding by building a greater number of in-country data centers across Germany, France, India, and Brazil.
A transition toward consumption-based procurement for on-premises hardware is accelerating among enterprise customers. This as-a-service model replaces large capital outlays for storage arrays with a recurring operational subscription that often includes management and capacity scaling. This pattern is most pronounced in the North American and European mid-market, which seeks cloud-like financial models for its private infrastructure.
Hardware Storage Market Segmentation
The hardware storage market exhibits diverse requirements across its value chain, necessitating a detailed segmentation analysis. Understanding these distinct segments allows vendors to tailor product development, sales strategies, and regulatory compliance efforts effectively for varied market demands.
Product Type:
Regulatory compliance, such as China's GB standards for electronics or the EU's RoHS directive on material composition, influences the design and market availability of various hardware storage product types.
- Hard Disk Drives:These devices utilize magnetic platters for persistent data retention. Hyperscale cloud providers in the US and Europe demand HDDs for massive archival storage due to their superior cost-per-gigabyte economics.
- Solid State Drives:NAND flash memory cells offer high-speed data access and durability. AI workloads in countries like Japan and Germany drive demand for SSDs, requiring massive, high-throughput datasets for model training.
- Network Attached Storage:NAS devices provide file-level data access, commonly used by small and medium-sized businesses for shared storage.
- Storage Area Network:SAN solutions offer block-level data storage for high-performance enterprise applications, often in financial institutions.
- Optical Drives:Optical drives, like Blu-ray, find niche applications in long-term archival for media and entertainment sectors.
- Tape Drives:Tape drives remain a cost-effective solution for cold data storage and disaster recovery in large data centers.
Established volume favors Hard Disk Drives; emerging adoption favors Solid State Drives.
Technology:
The choice of storage technology directly impacts application performance, with different interfaces optimized for specific workload requirements across the market.
- NVMe:Non-Volatile Memory Express provides a high-speed interface for flash storage, bypassing legacy protocols. Data centers in China and the US increasingly adopt NVMe to accelerate real-time data processing and AI workloads.
- Fibre Channel:Fibre Channel is a high-speed network technology primarily for Storage Area Networks. Enterprises in Europe and North America rely on Fibre Channel for mission-critical applications requiring low-latency, high-bandwidth block storage.
- SATA:Serial ATA is a common interface for consumer and enterprise HDDs and lower-performance SSDs.
- SAS:Serial Attached SCSI offers higher performance and reliability than SATA, favored in enterprise HDD and SSD deployments.
- iSCSI:Internet Small Computer System Interface enables block-level storage over standard Ethernet networks, providing flexibility.
- Thunderbolt:Thunderbolt offers high-speed data transfer for external storage devices, popular in media production and creative industries.
Performance differentiation is stark, with NVMe leading for low-latency needs and iSCSI offering network flexibility.
Application:
Different customer types drive distinct storage application requirements, from massive data centers to specialized scientific research facilities.
- Data Centers:Hyperscale and enterprise data centers require vast storage capacity and performance for diverse workloads. Cloud service providers in Germany and India expand data center footprints, driving demand for both SSDs and HDDs.
- Cloud Infrastructure:Cloud platforms leverage hardware storage for scalable, on-demand services for global customers. Data sovereignty mandates in regions like the EU compel localized cloud infrastructure deployments, impacting storage demand.
- Media & Entertainment:This sector demands high-capacity, high-throughput storage for video editing, rendering, and archival.
- Telecommunications:Telecom operators use storage for network data, billing systems, and edge computing deployments.
- Government Facilities:Government agencies require secure, compliant storage for sensitive data, often under FIPS 140-3 standards.
- Scientific Research:Scientific research generates massive datasets, needing high-performance and archival storage solutions.
Data Centers represent the largest volume consumers, while Scientific Research often drives demand for specialized, high-value solutions.
End User:
Supply chain configurations often adapt to the distinct procurement patterns and compliance needs of various end-user segments.
- Telecom Operators:These entities require robust, distributed storage for network operations and edge computing infrastructure. 5G infrastructure build-outs in South Korea and the US are accelerating storage deployments at the network edge.
- Financial Institutions:Financial institutions demand highly secure, compliant storage for transactional data and regulatory archives. FIPS 140-3 validated storage is critical for banks in the US and UK to meet stringent data protection mandates.
- Educational Institutions:Educational institutions utilize storage for academic records, research data, and digital learning platforms.
- Manufacturing Firms:Manufacturing firms deploy storage for operational data, IoT sensor data, and design archives.
- Energy Providers:Energy providers use storage for grid management data, sensor readings, and operational analytics.
- Public Sector Agencies:Public sector agencies require secure, localized storage for citizen data and government operations, often influenced by GDPR or HIPAA.
Financial Institutions exhibit mature procurement cycles, while Manufacturing Firms are experiencing evolving storage needs driven by Industry 4.0 initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy-driven data localization mandates and government initiatives are shaping hardware storage demand. These regulations compel organizations to maintain data within specific geographic borders. This directly influences infrastructure investments across key global markets.
China
China's government-led initiatives for digital infrastructure drive significant hardware storage demand. The country's GB standards for electronics influence device design and material composition. Data localization policies in major urban centers like Beijing and Shanghai necessitate local data center build-outs. This creates a concentrated pool of demand for all storage types.
United States
Hyperscale cloud expansion and government facilities propel hardware storage procurement in the United States. FIPS 140-3 cryptographic module validation is critical for secure storage solutions in the public sector. Major technology hubs such as Silicon Valley and Northern Virginia continue to expand data center capacity for cloud services. HIPAA mandates also influence data storage compliance for healthcare.
Germany
Germany's robust enterprise sector and expanding cloud infrastructure require substantial hardware storage investments. The GDPR and RoHS directive significantly impact storage device design and data handling practices. Frankfurt remains a central hub for data center operations, driven by financial services and cloud providers. This ensures localized data processing capabilities.
Japan
Japan's focus on AI workloads and high-performance computing fuels demand for advanced storage solutions. The Ministry of Economy, Trade and Industry (METI) promotes digital transformation across industries. Tokyo's technology sector drives demand for NVMe-based SSDs. This supports intensive research and development activities.
India
India's rapidly expanding cloud infrastructure and enterprise data centers generate substantial storage needs. Data localization policies influence the deployment strategies of global cloud service providers. Major IT hubs like Bangalore and Hyderabad are seeing rapid data center expansion. This supports the country's digital economy.
Hardware Storage Market Key Industry Players
Player mix skews toward established technology conglomerates and specialized storage solution providers. The market structure exhibits a tiered consolidation, with large enterprises dominating high-volume segments and niche players serving specialized performance requirements. Strategic archetypes include hyperscale volume suppliers, integrated infrastructure providers, and all-flash array specialists. Dominant competitive moves involve capacity expansion and strategic partnerships to address diverse workload demands.
At the scale-driven end, Seagate Technology Holdings plc exemplifies a focus on manufacturing scale in hard disk drives, primarily serving hyperscale clients with massive archival needs. Dell Technologies occupies a position as an integrated enterprise solution provider, differentiating through its comprehensive server and storage area network offerings for diverse business applications. Pure Storage represents the specialized all-flash array segment, targeting high-performance computing and enterprise database workloads requiring extreme speed. These companies collectively anchor significant portions of the hardware storage market by addressing distinct performance and capacity requirements.
| Leading Market Players |
|---|
| Seagate Technology Holdings plc |
| NetApp |
| Dell Technologies |
| Hitachi Vantara |
| Pure Storage |
| Hewlett Packard Enterprise |
| Western Digital Corporation |
| VMware |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
SSD lead-times, often fluctuating with NAND price volatility, directly influence procurement cycles and pricing power for enterprise buyers. Data center days-of-inventory for HDDs also shape long-term contract pricing.
Pricing Analysis
FIPS 140-3 validation creates the primary pricing spread for secure storage solutions in government and financial sectors. The dominant pricing model for enterprise storage arrays is a hybrid of per-unit transactional sales and consumption-based subscriptions. Brand premium and after-sales service bundles also drive price differentiation; pricing softness in commodity HDDs stems from oversupply and intense competition among hyperscale clients. Small and medium-sized businesses exhibit the highest price sensitivity, while government agencies prioritize security compliance over cost.
Supply Chain Analysis
The concentration of critical HDD component manufacturing in Southeast Asia underwrites the global supply chain for magnetic storage. Production centers in China, Taiwan, and South Korea supply NAND flash memory cells and controller ICs for SSDs. The industry relies on rare earth elements for magnetic platters and specialized silicon wafers for flash memory, exposing it to geopolitical and logistical risks in Southeast Asia. Distribution runs through a mix of direct sales to hyperscalers and channel partners for enterprise and consumer markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hardware storage market is experiencing an early-cycle expansion, driven by accelerating NVMe technology penetration in data centers. This foundational shift supports new application demands.
For Market Incumbents: Secure long-term supply agreements for NAND flash memory to mitigate price volatility and protect margins against new entrants. Expand manufacturing capacity for HDDs in diverse geographies outside Southeast Asia to reduce geopolitical risk and maintain volume leadership. Invest in FIPS 140-3 certification for secure storage solutions, leveraging this regulatory advantage against less compliant offerings. Control over firmware development remains a critical lever against cybersecurity threats.
For New Entrants and Emerging Players: A FIPS 140-3 certification fast-track offers a clear entry point into high-margin government and financial sectors. Target edge computing storage solutions, leveraging ruggedized designs for industrial IoT applications in North America. Develop specialized computational storage drives (CSDs) for scientific research facilities, focusing on offloading data processing tasks. The most penetrable segment involves niche high-performance computing applications with specific data processing requirements, where a direct-to-developer go-to-market angle can build early adoption.
For Investors and Strategic Acquirers: Carve-out targets emerge from large technology conglomerates divesting non-core storage divisions to streamline operations. The long-term viability of data infrastructure remains robust over the next 5-10 years, supporting sustained investment. Seek out specialized all-flash array providers with strong intellectual property in NVMe-oF fabrics, or niche players offering hardware-level encryption. Watch for increasing enterprise adoption of consumption-based storage models as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in NAND Manufacturing | Increases control over critical component supply, stabilizing costs for SSD production. |
| FIPS 140-3 Certification Investment | Unlocks access to high-margin government and financial sector contracts in the US. |
| Development of Computational Storage Drives | Offloads data processing from host servers, accelerating AI workloads for hyperscalers. |
| Expansion of Edge Storage Solutions | Captures demand from industrial IoT and autonomous systems at the network edge. |
| Strategic Partnership for NVMe-oF Integration | Facilitates seamless integration of high-performance NVMe storage into legacy SAN environments. |
Research Approach
A standing panel of data center architects, IT procurement officers, and storage engineers provided ongoing calibration for this study. Primary interviews with these industry stakeholders were validated against extensive secondary research. Secondary sources included SEC filings from major hardware vendors, government digital infrastructure reports from China, and cloud service provider capital expenditure disclosures. This approach ensured robust bottom-up and top-down triangulation of market data.
Market outputs were consistently validated against external benchmarks from leading industry associations and government statistics over the projection horizon. The analytical framework modeled hardware storage by product type, technology, application, and regional regulatory compliance. Compound annual growth rates were derived from historical data trends and projected technology adoption curves. Key forecast inputs included projected hyperscale cloud expansion rates and NVMe interface penetration.
Underlying assumptions cover current geopolitical stability and technology development trajectories, with deviation risk concentrated in NAND price volatility and supply chain disruptions. Forecasts reflect these assumptions. Practitioners should keep alternative scenarios live as global trade policies and component availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
NAND Flash Memory Market
Data Storage
Channel Storage Systems Market
Data Storage
Ceph Storage Solutions Market
Data Storage
All Flash Storage Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Recordable Optical Disc Market
Data Storage
Tape Storage Market
Data Storage
NAND Flash Market
Data Storage
Germany Data Center Storage Market
Data Storage
Ethernet Storage Market
Data Storage
AI Powered Storage Market
Data Storage
Europe Flash Memory Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Distributed Storage System Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Next Generation Data Storage Market