
 Global Personal and Entry Level Storage (PELS) Market | 2026-2036
Global Personal and Entry Level Storage (PELS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal and Entry Level Storage (PELS) Market Intelligence
Consolidation in NAND flash memory manufacturing across South Korea and Taiwan is repositioning the supply base for solid-state drives. Western Digital Corporation leverages its in-house production of flash memory to secure cost advantages. Seagate Technology competes by focusing on high-capacity HDD solutions for archival needs. Toshiba Corporation sustains its market presence through a broad portfolio spanning both SSD and HDD technologies.
Personal and Entry Level Storage encompasses portable devices designed for user-managed data backup, transport, and archival. These products utilize either magnetic platters or NAND flash memory, connecting to host systems via interfaces like USB-C and Thunderbolt. Solid-State Drives (SSD) represent the fastest-growing product type, displacing traditional HDDs due to superior speed. While the consumer end-user segment is mature, demand from small businesses for reliable backup solutions is accelerating.
Product design and market access are shaped by multiple regulatory frameworks. The EU's RoHS directive restricts hazardous substances in electronic equipment, while its WEEE directive governs end-of-life disposal. In the United States, devices must comply with FCC standards for electromagnetic compatibility. Navigating the trade-off between increasing storage capacity, faster data transfer speeds, and manufacturing cost remains the central challenge for vendors.
Market Dynamics
The fundamental transition from Hard Disk Drives (HDD) to Solid-State Drives (SSD) is the central structural force in the PELS market. This shift, underpinned by NAND flash memory innovation, redefines performance benchmarks and reshapes supply chain dependencies.
Growth Catalysts
- Creative Professional Demand:Concentrated demand from media and entertainment professionals in hubs like London and Tokyo for high-speed storage to manage large video and graphics files fuels market expansion.
- Small Business Backup Adoption:An expanding user base of small businesses is adopting entry-level storage for critical data backup and archival, moving beyond consumer-grade cloud solutions for greater control.
- Interface Standardization:The widespread adoption of high-bandwidth interfaces like USB-C and Thunderbolt on host devices enables the full performance potential of modern SSDs, making them practical for everyday use.
Market Restraints
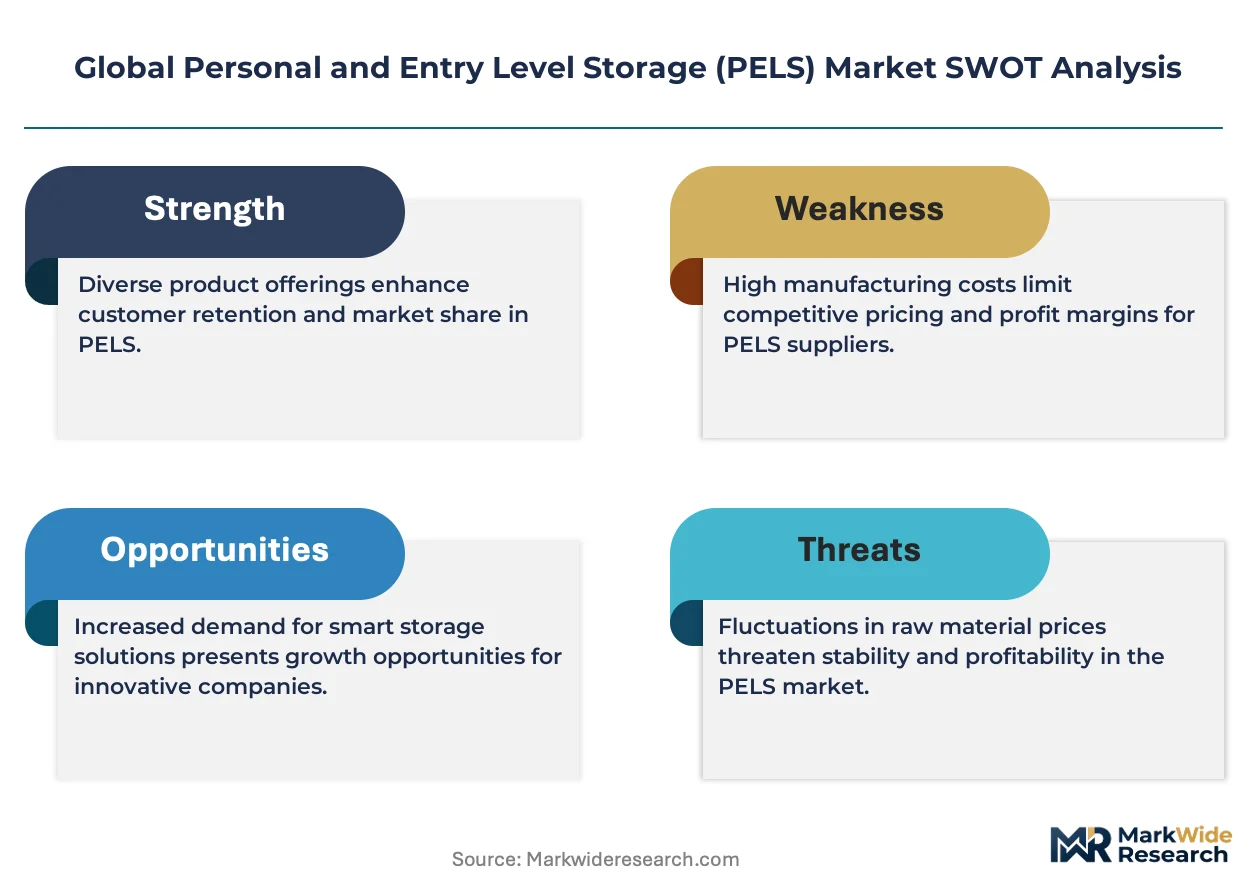
- NAND Flash Price Volatility:The cost structure for SSDs is subject to significant fluctuations in the NAND flash memory market, creating margin pressure and unpredictable component pricing for manufacturers.
- Supply Base Concentration:Heavy reliance on NAND flash memory production centered in South Korea and Taiwan introduces geopolitical and supply chain risks for the entire SSD segment of the market.
- HDD Performance Ceiling:The physical limitations of magnetic platters in traditional Hard Disk Drives impose a ceiling on data transfer speeds, restricting their use in performance-sensitive applications.
Strategic Opportunities
- Purpose-Built Small Business Devices:Developing storage solutions with integrated backup software and enhanced security features specifically tailored to the needs of small and home office (SOHO) users represents a key growth vector.
- Expansion into Gaming Storage:Targeting the console and PC gaming market with high-speed external SSDs designed to reduce game load times offers a significant opportunity in a specialized consumer vertical.
- Ruggedized Devices for Fieldwork:Creating durable, weather-resistant storage products for professionals in fields like construction, geology, and field journalism opens a niche market less sensitive to price.
Industry Challenges
- Regulatory Compliance Complexity:Vendors must navigate a fragmented landscape of electronic waste and hazardous substance regulations, including the EU's WEEE and RoHS directives, alongside FCC rules in the United States.
- Managing Technology Transitions:Balancing investment in next-generation SSD technology while managing the lifecycle and profitability of legacy HDD product lines presents a significant portfolio management challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal and Entry Level Storage (PELS) Market |
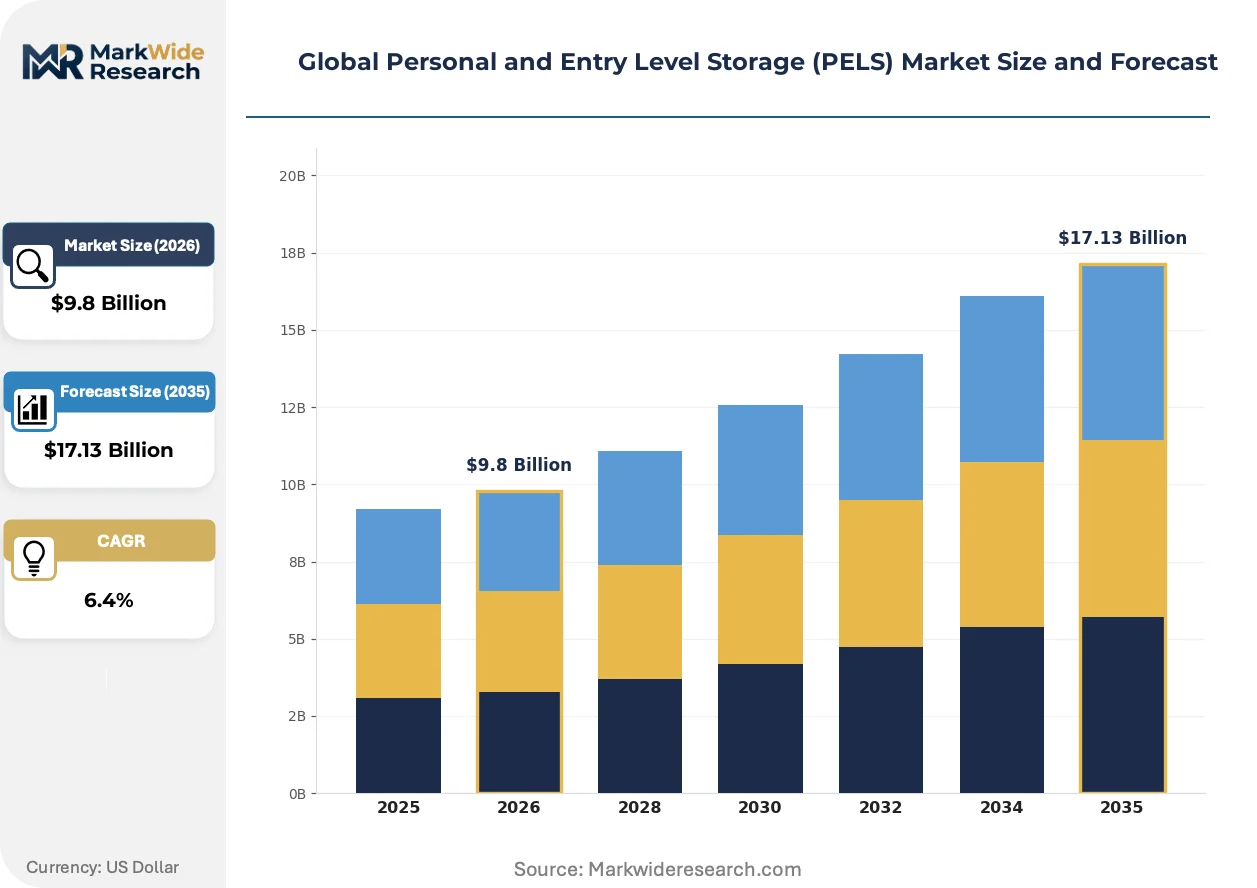
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, USB Flash Drive, External Storage End User: Consumers, Small Businesses, Educational Institutions, IT Departments Distribution Channel: Online Retail, Brick-and-Mortar Stores, Distributors, Direct Sales Capacity: 1TB, 2TB, 4TB, 8TB |
| Companies Covered | Western Digital Corporation, Seagate Technology, Dell Inc., EMC Corporation, IBM Corporation, Cisco Systems Inc., NetApp Inc., Hewlett-Packard Company, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal and Entry Level Storage (PELS) Market Strategic Shifts & Innovations
Product development in personal storage is shifting focus from pure capacity increases toward enhancements in data transfer speed and on-device intelligence. Concurrently, global environmental regulations are increasingly influencing product design and end-of-life management, reshaping vendor responsibilities.
Technology Evolution
Advanced SSD controllers now incorporate dedicated processing cores for managing NAND flash memory. Prosumers and creative professionals rapidly adopt devices using this technology for sustained performance in demanding workflows. This embedded intelligence is automating background tasks like garbage collection and wear-leveling, which optimizes drive longevity and speed independently of the host system.
Regulatory Shift
The European Union's Restriction of Hazardous Substances (RoHS) directive directly impacts material choices in PELS manufacturing. This regulation forces a redesign of circuit boards and casings to eliminate substances like lead and cadmium. Consequently, the entire supply chain must adapt, with vendors sourcing compliant components to maintain access to the significant EU market.
Demand-Side Shift
Buyer preference is evolving from a pure focus on price-per-gigabyte to an evaluation of the total software and service ecosystem. This change challenges the commodity-focused sales model, particularly within the prosumer and small business segments. This pattern is most pronounced in developed markets like the United States and Germany, where ease-of-use and integrated security software influence purchasing decisions.
Global Personal and Entry Level Storage (PELS) Market Segmentation
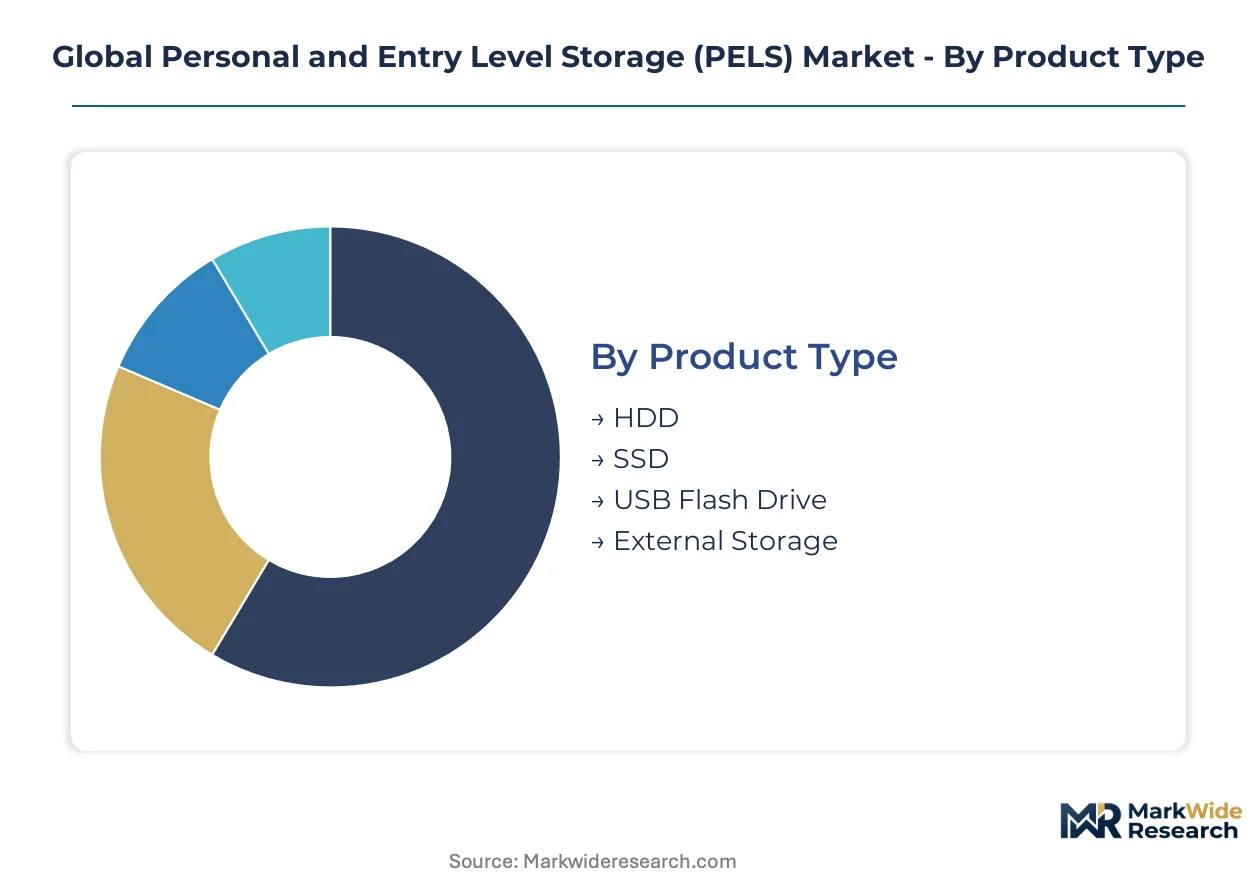
Market segmentation for Personal and Entry Level Storage (PELS) provides a granular view of demand drivers and product preferences. It illuminates how different product technologies, end-user applications, and distribution strategies shape competitive dynamics. Analyzing capacity tiers further refines insights into evolving consumer and business requirements.
Product Type:
The Personal and Entry Level Storage market exhibits a clear split between high-performance, premium solutions and cost-effective, high-volume options for data management.
- HDD:Hard Disk Drives utilize spinning magnetic platters to store data, offering high capacity at a lower cost per gigabyte. Small businesses increasingly adopt HDDs for cost-efficient, large-scale archival and critical data backup needs.
- SSD:Solid-State Drives leverage NAND flash memory for data storage, providing superior speed, durability, and shock resistance over mechanical drives. Demand concentrates among creative professionals in media hubs like London for demanding video and graphics workflows.
- USB Flash Drive:These portable devices offer convenient, small-capacity data transport via integrated NAND flash memory.
- External Storage:This broad category encompasses portable devices designed for user-managed data backup, transport, and archival.
Today's leader: HDD. Tomorrow's challenger: SSD.
End User:
End-user segmentation highlights how specific application requirements and data management needs drive purchasing decisions across diverse user groups.
- Small Businesses:These entities require reliable, often integrated, backup solutions for critical operational data, moving beyond basic cloud storage for enhanced control. Their demand is accelerating for secure data retention.
- Consumers:This mature segment seeks personal data backup, media storage, and portable solutions for everyday digital life. Ease of use and affordability significantly influence purchasing for personal media libraries.
- Educational Institutions:These organizations procure storage for student data, administrative records, and research projects.
- IT Departments:Enterprise IT departments manage large-scale data storage and backup infrastructure for organizational operations.
Small businesses are driving the most significant expansion in user adoption, while consumer demand remains foundational.
Distribution Channel:
Distribution channels reflect the diverse purchasing behaviors and preferred access points for personal and entry-level storage solutions among various customer types.
- Online Retail:E-commerce platforms offer broad product selections, competitive pricing, and direct-to-consumer convenience. This channel captures a large share of individual consumer and small business purchases due to accessibility.
- Brick-and-Mortar Stores:Physical retail outlets provide immediate availability, in-person advice, and hands-on product experience. These stores remain relevant for impulse buys and customers preferring physical interaction.
- Distributors:These intermediaries supply products to various resellers and system integrators.
- Direct Sales:Manufacturers engage directly with large clients or specialized professional segments.
Online retail dominates in market reach and volume, while direct sales cater to specialized procurement needs.
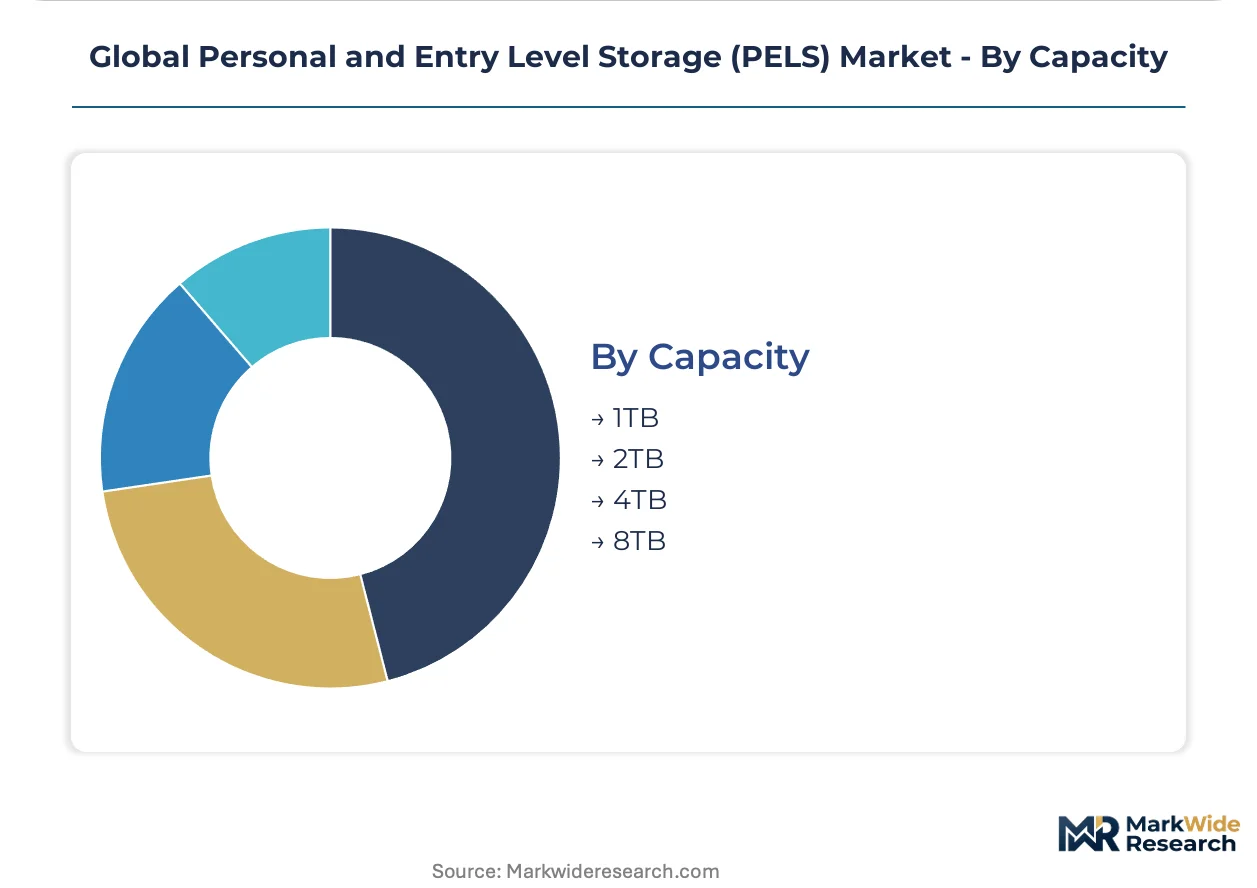
Capacity:
Capacity tiers illustrate the balance between storage volume, manufacturing cost, and typical use cases for different user segments, influencing purchasing decisions.
- 4TB:This capacity tier balances substantial storage with reasonable cost, serving prosumers and small businesses for comprehensive backup and media libraries. It provides ample space for large file collections.
- 2TB:Offering a balance of capacity and portability, this tier is popular among general consumers and students for everyday data backup and transport. It suits users with moderate storage requirements.
- 1TB:Entry-level personal storage often falls within this capacity for basic document, photo, and small project backup.
- 8TB:High-capacity solutions cater to creative professionals and power users requiring extensive storage for large datasets.
The 4TB segment currently meets diverse user needs effectively, with demand for 8TB and higher capacities steadily growing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Personal and Entry Level Storage market experiences regional variations driven by differing regulatory environments and manufacturing cost structures. Production often migrates to areas offering more favorable compliance costs or established supply chains. This dynamic creates a competitive landscape where regional policies influence investment and operational decisions.
United States
United States demand for high-speed SSDs concentrates among creative professionals in media hubs. Devices must comply with FCC standards for electromagnetic compatibility before market entry. Silicon Valley also drives innovation in storage controller technology and interface development.
South Korea
South Korea serves as a critical hub for NAND flash memory production, influencing global SSD supply. Government industrial policies actively support semiconductor manufacturing and related R&D initiatives. Major fabrication plants around Seoul contribute significantly to the worldwide supply base.
Japan
Japanese creative professionals in Tokyo generate substantial demand for high-capacity, high-performance storage solutions. The METI actively supports research and development in advanced memory technologies. Yokohama hosts significant R&D facilities for storage device manufacturers.
Germany
Germany exhibits strong demand from small businesses seeking reliable backup solutions and prosumers requiring high-performance storage. The EU's RoHS directive directly influences material choices in PELS manufacturing. Industrial clusters in Bavaria drive adoption for specialized data management needs.
China
China represents a vast consumer market and a growing segment for small business storage solutions. Domestic manufacturers must adhere to stringent GB standards for product quality and safety. Shenzhen's electronics ecosystem drives significant production and innovation in entry-level storage devices.
Global Personal and Entry Level Storage (PELS) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized high-performance segments with advanced controller technologies. The market structure features a mix of large diversified technology conglomerates and dedicated storage solution providers. Key archetypes include vertically integrated memory manufacturers, pure-play storage device assemblers, and system integrators offering bundled solutions. Companies often engage in strategic partnerships for component sourcing, pursue portfolio diversification across HDD and SSD technologies, and invest in R&D for next-generation interfaces.
Among the vertically integrated memory manufacturers, Western Digital Corporation exemplifies a strategy of in-house flash memory production, leveraging captive supply for cost advantages in the SSD segment. Seagate Technology anchors the high-capacity HDD segment, focusing on robust archival solutions essential for small businesses and data centers. Toshiba Corporation occupies a position as a diversified player, sustaining its market presence through a broad portfolio spanning both SSD and HDD technologies. These players collectively address diverse market needs from performance-driven creative professionals to cost-efficient archival for small businesses.
| Leading Market Players |
|---|
| Western Digital Corporation |
| Seagate Technology |
| Dell Inc. |
| EMC Corporation |
| IBM Corporation |
| Cisco Systems Inc. |
| NetApp Inc. |
| Hewlett-Packard Company |
| Toshiba Corporation |
| Others |
Cost & Logistics Intelligence
Creative professionals' concentrated demand for high-performance storage influences a per-unit transactional pricing model, reflecting specialized feature sets. This dynamic balances raw capacity costs with performance premiums across the market.
Pricing Analysis
Retailer markup significantly influences the final pricing of personal and entry-level storage devices. The dominant pricing model remains per-unit transactional, where brand premium and performance tier heavily differentiate offerings. Cost compression in consumer-grade HDDs stems from intense commoditization, driving pricing softness. Creative professionals exhibit lower price sensitivity for high-speed SSDs, while general consumers prioritize affordability for basic storage.
Supply Chain Analysis
Workforce availability and specialized engineering talent in South Korea and Taiwan underpin the global NAND flash memory supply. This critical component, alongside magnetic platters and SSD controllers, forms the core raw material dependency for personal storage. Geopolitical risks and commodity price volatility for NAND flash memory represent a significant structural risk. Downstream distribution runs predominantly through online retail channels and specialized distributors for business customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Personal and Entry Level Storage market acts as a stable compounder, driven by the expanding small business adoption for critical data backup. This sustained demand provides a consistent foundation for market expansion.
For Market Incumbents: Anchor existing market share by diversifying product portfolios across both SSD and HDD technologies. Incumbents should invest in R&D for advanced SSD controllers to mitigate margin pressure from NAND flash price volatility. Leveraging in-house flash memory production also secures cost advantages against supply chain risks. Navigating regulatory compliance complexity, like the EU's RoHS directive, requires proactive material sourcing strategies.
For New Entrants and Emerging Players: A significant price-point gap exists between premium enterprise storage and basic consumer options, creating entry opportunities. New entrants should target specialized consumer verticals like gaming with high-speed external SSDs to reduce load times. Developing purpose-built small business devices with integrated backup software and enhanced security features offers another penetrable segment. Focusing on ruggedized, weather-resistant products for fieldwork professionals also opens niche markets less sensitive to price.
For Investors and Strategic Acquirers: Technology conglomerates are the most active acquirers in this space, seeking to bolster their data management ecosystems. The market offers long-term viability, driven by sustained demand from small businesses and creative professionals over the coming decade. Investors should target specialized storage solution providers excelling in integrated software or with strong penetration in niche verticals. Advancements in SSD controller technology, delivering significant performance gains, serve as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures long-term component supply and mitigates price volatility for SSD manufacturers. |
| Portfolio Diversification | Addresses diverse end-user needs from archival to performance-driven professional workflows. |
| Software Integration | Enhances product value proposition for small businesses and prosumers, moving beyond commodity sales. |
| Ruggedized Product Development | Captures niche markets in fieldwork and industrial applications less sensitive to price. |
| Interface Technology R&D | Ensures products leverage full performance potential and maintain compatibility with host devices. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. The approach combined primary interviews with storage device engineers, IT procurement managers, creative professionals, and small business owners. Secondary validation drew from industry reports, company financial filings, and technology whitepapers. This triangulation ensures robust data accuracy and comprehensive market understanding.
Historical trendline analysis, coupled with a deep understanding of market dynamics, underpinned the forecast framework. Segmentation dimensions modeled included product type, end-user, distribution channel, capacity tiers, and regional adoption patterns. Compound Annual Growth Rates were derived from historical data and projected market shifts across the analysis window. Key forecast inputs included NAND flash memory pricing and interface bandwidth evolution.
Caveats apply where geopolitical events or rapid technological obsolescence could materially shift the outlook. Forecasts reflect assumptions regarding supply chain stability and consumer technology adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Enterprise Flash Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Storage Virtualization Market
Data Storage
Channel Storage Systems Market
Data Storage
Next-Generation Storage Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Blu-Ray Drive Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Distributed Storage System Market
Data Storage
HDD Head Assembly Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Enterprise Storage System Market
Data Storage
Transparent Cache Market
Data Storage
Flash Memory Market