
 Glass Coatings Market | 2026-2036
Glass Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Coatings Market Analytics
Automotive OEM procurement is consolidating around fewer Tier 1 glass suppliers with integrated coating capabilities. PPG Industries leverages its automotive refinish heritage to anchor coated glass relationships with Detroit and Stuttgart OEMs. Saint-Gobain sustains manufacturing scale across European architectural glass channels. NSG Group competes through specialization in thin-film sputtered coatings for transportation glazing.
Glass coatings comprise thin functional layers deposited onto silica-based substrates to modify optical, thermal, or surface properties, typically ranging from nanometers to micrometers in thickness depending on deposition method. Sol-gel formulations and magnetron-sputtered oxide stacks serve primarily to manage solar heat gain, reduce reflectance, or impart self-cleaning functionality in built environments and vehicles. Hydrophobic and anti-reflective product types command premium positioning in consumer electronics and aerospace applications where optical clarity and durability specifications are stringent. Architectural application volumes dominate current consumption, though automotive and electronics end-use segments attract disproportionate R&D investment for next-generation electrochromic and thermochromic transitions.
EPA regulations on volatile organic compound emissions constrain solvent-based coating formulations in the United States, while REACH and the EU Green Deal mandate substitution of hazardous substances in European architectural products. China's MEE enforces emission caps on chemical vapor deposition facilities in the Yangtze River Delta glass manufacturing belt. Japan's METI efficiency standards for building envelopes indirectly drive low-emissivity coated glass specifications. Stakeholders must monitor evolving carbon border adjustment mechanisms and material passport requirements that will reshape supplier qualification criteria and regional cost structures.
Market Dynamics
Automotive OEM consolidation around integrated glass-coating suppliers is compressing vendor margins while elevating technical qualification barriers. Tier 1 suppliers now self-perform sputtering and sol-gel deposition to capture thermal management value previously retained by coating specialists.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon propellants accelerates waterborne and UV-cured coating formulation adoption across European architectural glass channels.
- Electrochromic glazing:Transportation OEMs specify active tinting layers for cabin thermal comfort, pulling incremental coating volume into automotive bill-of-materials.
- Yangtze River Delta:China's solar glass manufacturing corridor concentrates demand for anti-reflective coatings on photovoltaic cover plates.
Market Restraints
- Silver volatility:Magnetron-sputtered low-emissivity stacks depend on silver thin-film layers; London Metal Exchange price swings compress coating gross margins unpredictably.
- MEE emission caps:China's Ministry of Ecology and Environment enforces chemical vapor deposition facility closures, constraining regional coating capacity expansion.
- Technical limitation:Current self-cleaning photocatalytic formulations degrade under prolonged UV exposure in high-altitude installations, limiting warranty terms.
Strategic Opportunities
- India building codes:Bureau of Indian Standards energy conservation guidelines for commercial envelopes create first-mover positioning for low-emissivity coated glass specification.
- Flexible electronics:Roll-to-roll coating of polymer substrates for foldable display cover windows merges glass coating expertise with polymer surface engineering.
- US Inflation Reduction Act:Domestic content bonuses for solar module assembly incentivize anti-reflective coating production reshoring to Arizona and Ohio manufacturing zones.
Industry Challenges
- Magnetron sputtering expertise:Thin-film deposition engineering talent concentrates in Germany and Japan, creating recruitment bottlenecks for emerging market facility ramp-ups.
- REACH compliance timelines:Substance of very high concern dossier preparation extends product reformulation cycles by 18-24 months, delaying new coating introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Coatings Market |
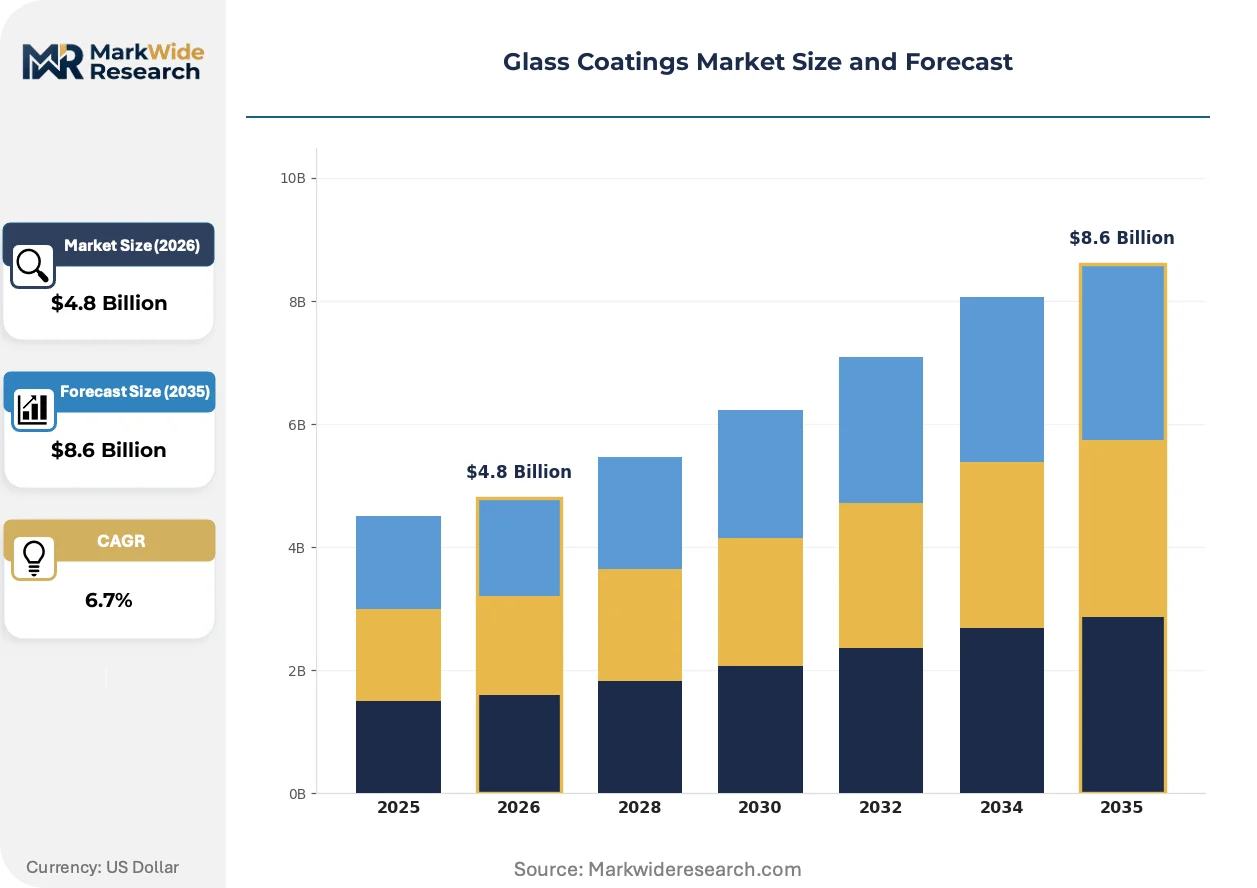
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic, Anti-Reflective, Self-Cleaning, UV-Resistant Application: Automotive, Architectural, Aerospace, Consumer Electronics Technology: Sol-Gel, Chemical Vapor Deposition, Magnetron Sputtering, Plasma Spraying End User: Manufacturers, Construction, Automotive OEMs, Electronics Producers |
| Companies Covered | PPG Industries, NSG Group, Saint-Gobain, Corning Inc., The Sherwin-Williams Company, Arkema Inc., 3M, Fenzi Spa, Henkel A.G., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Coatings Market Evolving Landscape
Deposition process hybridization and active glazing functionality are redrawing competitive boundaries between glass manufacturers, coating material suppliers, and systems integrators. Technical differentiation now resides in stack architecture rather than single-layer performance.
Sol-gel-derived silica-titania nanocomposites are converging with roll-to-roll coating lines to enable flexible glass and polymer substrate processing at architectural scale. Display cover manufacturers in South Korea and Taiwan pilot these hybrid deposition systems for foldable device cover plates. The convergence is compressing equipment supplier margins while elevating process chemistry IP value in coating formulation houses.
EPA volatile organic compound emission standards for architectural coatings tighten solvent-based formulation permissible limits on a rolling three-year compliance schedule. Coating producers reformulate toward waterborne and powder deposition systems, shifting capital allocation from solvent recovery to curing oven infrastructure. US flat glass fabricators in the Southeast and Midwest face the steepest compliance cost curves due to legacy solvent-based line concentration.
Automotive glazing procurement now bundles coating specification with structural glass supply contracts, displacing standalone coating vendor relationships. European OEMs in Stuttgart and Munich lead this bundling, followed by Detroit-based manufacturers consolidating supplier panels. Tier 1 glass integrators capture coating value previously retained by material specialists, compressing independent coating chemical producers to specialty aftermarket and repair channels.
Glass Coatings Market Segmentation
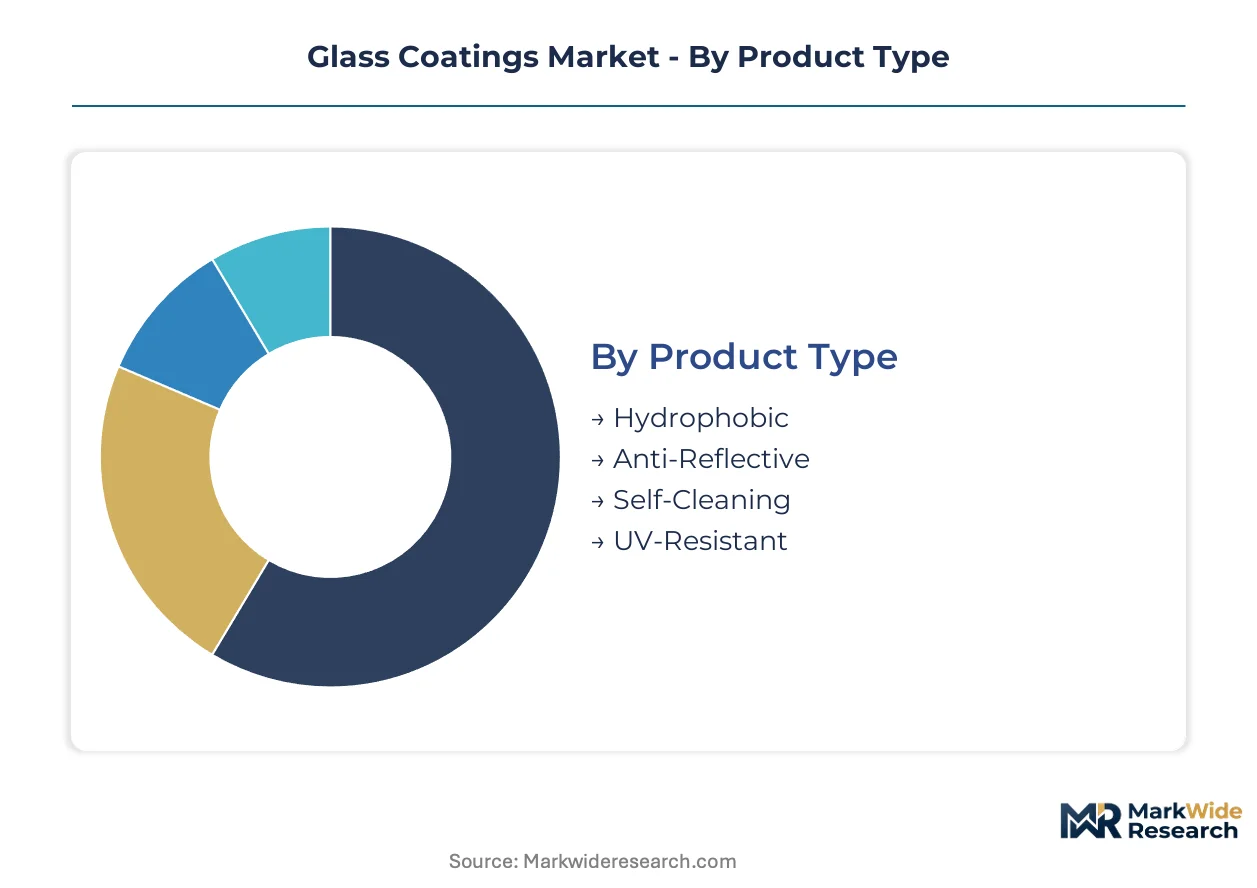
Glass coatings segment along four functional dimensions that determine manufacturing investment, margin structure, and customer access. Product chemistry dictates equipment requirements. Application end-use shapes warranty terms and regulatory exposure. Technology selection locks in capital intensity and geographic labor availability.
Product Type:
Supply concentration clusters around hydrophobic and anti-reflective formulations where PPG Industries and Saint-Gobain have anchored proprietary chemistry platforms.
- Hydrophobic:Fluoropolymer or silicone-based surface treatments that reduce water contact angle below 10 degrees for automotive windshields and architectural facades. Demand concentrates in Germany's automotive glass cluster where OEMs specify self-draining properties for aerodynamic efficiency. Rain-sensing wiper integration and reduced washer fluid consumption drive specification.
- Anti-Reflective:Multi-layer interference coatings, typically silica-titania stacks, that suppress surface reflectance below 1% across visible wavelengths. China's solar glass manufacturing corridor in the Yangtze River Delta pulls volume for photovoltaic cover plates where transmission gains directly boost module efficiency. MEE emission caps constrain regional CVD capacity expansion.
- Self-Cleaning:Photocatalytic titania layers that decompose organic contaminants under UV exposure.
- UV-Resistant:Absorptive or reflective formulations that block ultraviolet transmission for museum display cases and aircraft cabin windows.
Today's leader: Hydrophobic. Tomorrow's challenger: Anti-Reflective.
Application:
Cost tier separation runs deepest in automotive versus architectural, where warranty periods and performance testing regimes diverge by an order of magnitude.
- Automotive:Thermal management and weight reduction priorities pull coated glass into laminated windshield and side-lite assemblies. Stuttgart and Munich OEMs bundle coating specification with structural glass supply contracts, compressing standalone coating vendor margins. Electrochromic active tinting layers represent the steepest expansion trajectory for cabin comfort applications.
- Architectural:Low-emissivity and solar control coatings dominate facade and curtain wall specifications. Germany's Passivhaus standards and California's Title 24 building codes mandate thermal performance thresholds that only sputtered silver stacks reliably achieve. Silver price volatility compresses coating gross margins unpredictably.
- Aerospace:Optical clarity and durability specifications for cockpit displays and passenger windows command premium positioning.
- Consumer Electronics:Anti-reflective and anti-fingerprint coatings for foldable display cover windows merge glass expertise with polymer surface engineering.
Architectural commands current volume. Automotive captures R&D investment intensity.
Technology:
Volume scale and capital recovery timelines separate batch sol-gel lines from continuous sputtering systems.
- Sol-Gel:Liquid-phase deposition of metal alkoxide precursors followed by thermal curing, suited to complex geometries and moderate throughput. US Southeast and Midwest fabricators face steep EPA VOC compliance cost curves due to legacy solvent-based line concentration. Waterborne reformulation shifts capital toward curing oven infrastructure.
- Magnetron Sputtering:Physical vapor deposition of metal and oxide thin films in vacuum chambers, enabling precise optical stack architecture. Thin-film deposition engineering talent concentrates in Germany and Japan, creating recruitment bottlenecks for emerging market facility ramp-ups.
- Chemical Vapor Deposition:Gas-phase precursor reactions for conformal coating of complex substrates.
- Plasma Spraying:High-velocity thermal spray of ceramic coatings for thick functional layers.
Sputtering owns precision. Sol-gel retains flexibility.
End User:
Customer type determines technical qualification depth and contract duration, with automotive OEMs imposing the most exhaustive validation protocols.
- Manufacturers:Flat glass and container producers applying coatings at the float line or post-forming stage.
- Construction:Specifiers and fabricators selecting coated glass for commercial envelope projects. India's Bureau of Indian Standards energy conservation guidelines create first-mover positioning for low-emissivity specification in commercial construction.
- Automotive OEMs:Vehicle assemblers consolidating supplier panels around Tier 1 glass integrators with captive coating capability. Detroit-based manufacturers follow Stuttgart and Munich in bundling coating specification with structural supply contracts.
- Electronics Producers:Display and device manufacturers sourcing coated cover glass and polymer substrates. South Korean and Taiwanese display cover manufacturers pilot hybrid deposition systems for foldable device applications.
OEMs concentrate procurement power. Electronics producers drive substrate diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's solar glass corridor pulls anti-reflective coating volume at industrial scale, while Germany's automotive cluster concentrates precision sputtering expertise for cabin glazing. These two markets anchor contrasting demand profiles across the forecast window.
United States
Domestic solar module assembly incentives under the Inflation Reduction Act drive anti-reflective coating production toward Arizona and Ohio manufacturing zones. EPA volatile organic compound standards tighten solvent-based formulation limits on rolling three-year schedules. Southeast and Midwest flat glass fabricators face steep compliance cost curves due to legacy solvent-based line concentration.
Germany
Stuttgart and Munich automotive OEMs bundle coating specification with structural glass supply contracts, consolidating procurement around integrated Tier 1 suppliers. EU F-Gas Regulation phase-down of hydrofluorocarbon propellants accelerates waterborne and UV-cured formulation adoption. The Passivhaus standard and national energy codes mandate thermal performance thresholds that sputtered silver stacks reliably achieve.
China
The Yangtze River Delta solar glass manufacturing corridor concentrates demand for anti-reflective coatings on photovoltaic cover plates where transmission gains directly boost module efficiency. Ministry of Ecology and Environment emission caps enforce chemical vapor deposition facility closures, constraining regional coating capacity expansion. Dual carbon goals intensify pressure on glass manufacturing belt decarbonization timelines.
India
Bureau of Indian Standards energy conservation guidelines for commercial envelopes create first-mover positioning for low-emissivity coated glass specification in construction. Central Electricity Authority building efficiency mandates indirectly drive thermal performance glazing adoption. Maharashtra and Gujarat commercial construction corridors attract initial coating technology licensing agreements.
Japan
METI efficiency standards for building envelopes indirectly drive low-emissivity coated glass specifications in commercial retrofits. Thin-film deposition engineering talent concentrates in Kansai and Chubu industrial zones, creating recruitment bottlenecks for facility expansion. Display cover manufacturers in Kanto pilot hybrid deposition systems for foldable device applications.
Glass Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating formulation and deposition equipment segments. The market structure tilts toward consolidation as automotive OEM procurement compresses vendor panels around fewer Tier 1 glass integrators with captive coating capability. Three archetypes dominate: integrated glass-coating conglomerates, independent formulation houses, and deposition equipment specialists. M&A activity concentrates on backward integration into coating material supply, while capacity expansion targets solar glass corridor proximity.
Among diversified material conglomerates, PPG Industries and Saint-Gobain exemplify integrated coating-glass positioning. PPG leverages automotive refinish heritage to anchor coated glass relationships with Detroit and Stuttgart OEMs. Saint-Gobain sustains manufacturing scale across European architectural glass channels. NSG Group occupies a specialist position in thin-film sputtered coatings for transportation glazing, representing the focused technical archetype competing against integrated rivals.
| Leading Market Players |
|---|
| PPG Industries |
| NSG Group |
| Saint-Gobain |
| Corning Inc. |
| The Sherwin-Williams Company |
| Arkema Inc. |
| 3M |
| Fenzi Spa |
| Henkel A.G. |
| Others |
Value Network & Pricing Analysis
Magnetron sputtering engineering talent concentration in Germany and Japan feeds labor-cost differentials that widen pricing spreads between precision sputtered stacks and commodity sol-gel formulations. Buyers in Stuttgart and Munich absorb premium positioning for thermal management glazing, while Southeast Asian fabricators compete on waterborne sol-gel cost curves.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for anti-reflective photovoltaic coatings. Three-tier pricing structure across premium, standard, and economy levels separates sputtered silver low-emissivity stacks from waterborne sol-gel solar control and basic hydrophobic treatments. Pricing pressure stems from silver volatility on the London Metal Exchange compressing coating gross margins. Automotive OEMs in Detroit and Stuttgart exhibit lowest price sensitivity due to bundled procurement contracts, while independent architectural fabricators face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements from European automotive OEMs mandate multi-supplier qualification for magnetron sputtering feedstock and coating precursors. Supply concentrates in Germany, Japan, and China for deposition equipment and silver thin-film materials. Raw material dependencies center on silver bullion, metal alkoxide precursors, and fluoropolymer resins. Single-source vulnerability runs through German sputtering equipment engineering talent. Distribution runs through Tier 1 glass integrators capturing coating value previously retained by standalone formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass coatings function as a geographic-arbitrage play where EPA VOC compliance costs in the US Southeast and Midwest exceed waterborne reformulation savings available in India's emerging commercial construction corridor.
For Market Incumbents: Deepen captive sputtering capability in Germany's automotive cluster to defend against Tier 1 glass integrators absorbing coating value. Backward integration into silver thin-film supply hedges London Metal Exchange volatility. Waterborne sol-gel reformulation investment in legacy solvent-based lines preserves Southeast and Midwest fabricator positioning against EPA emission standard tightening. For New Entrants and Emerging Players: Capture first-mover positioning in India's Bureau of Indian Standards low-emissivity specification window before incumbent licensing agreements solidify. Maharashtra and Gujarat commercial construction corridors offer penetrable white-space for sol-gel thermal performance glazing. License deposition technology from Japanese equipment specialists to bypass German engineering talent recruitment bottlenecks. For Investors and Strategic Acquirers: Tier 1 automotive glass integrators are the most active acquirer in this space as OEM procurement consolidation accelerates. Long-term viability hinges on electrochromic active glazing transition timelines. Watch electrochromic layer yield rates at South Korean and Taiwanese display cover manufacturers as inflection indicator for automotive cabin comfort adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Thin-Film Supply | Hedges London Metal Exchange price volatility for sputtered low-emissivity stack producers. |
| Waterborne Sol-Gel Reformulation Investment | Preserves EPA compliance positioning for legacy solvent-based Southeast and Midwest fabricators. |
| Electrochromic Deposition Capability Buildout | Captures cabin thermal comfort specification from Stuttgart and Munich automotive OEMs. |
| India Market Licensing Agreement | Secures Bureau of Indian Standards first-mover positioning in Maharashtra and Gujarat corridors. |
| Hybrid Roll-to-Roll Deposition Partnership | Merges glass coating expertise with polymer substrate engineering for foldable electronics. |
Research Methodology
Direct dialogue with flat glass plant managers, automotive OEM procurement leads, coating formulation R&D directors, and architectural specifier networks grounded qualitative assessment. Secondary validation drew from EPA emission standard filings, REACH substance dossiers, SEC 10-K disclosures from diversified material conglomerates, and Yangtze River Delta MEE enforcement records. Bottom-up coating volume modeling triangulated against top-down end-use consumption estimates.
Segment-level value outputs across the analysis window reflect product chemistry, application end-use, technology selection, and customer type dimensions. CAGRs derived from regression against solar glass manufacturing corridor expansion rates, automotive glazing content per vehicle trajectories, and building code thermal performance mandate adoption curves. Silver price volatility and electrochromic yield improvement timelines fed scenario-weighted projections.
Silver bullion price spikes, MEE emission cap enforcement intensity, and REACH substance of very high concern listing decisions are the dominant revision risks. Deviation in electrochromic layer manufacturing yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Coated Casing Market
Coatings
Textile Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Waterproof Coating Market
Coatings
Process Pipe Coating Market
Coatings
Global Graphite Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Global Plastic Coatings Market