
 Coated Casing Market | 2026-2036
Coated Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Casing Market Analysis
API 5CT certification and NACE TM0177 sour-service qualification is redrawing competitive boundaries among suppliers. Viscofan Group leverages its polymer science heritage to extend barrier-coating formulations into oilfield applications. Kalle GmbH anchors European supply through controlled manufacturing of regenerated cellulose substrates. Devro PLC competes by specializing in collagen-based edible and technical casing platforms.
Coated casing comprises steel tubulars engineered with bonded polymer, metal, or composite layers to prevent corrosion, abrasion, and chemical degradation in aggressive downhole environments. Wall thickness typically ranges from 0.2 to 0.5 inches with coating adhesion strengths exceeding 3,000 psi per ASTM D4541 pull-off testing, serving primarily to extend well integrity lifecycles and reduce workover frequency. Polymer-coated products dominate current procurement volumes across North American shale plays where H2S and CO2 partial pressures accelerate substrate attack. Composite casing variants represent the fastest-growing segment as operators pursue weight reduction and thermal insulation in extended-reach drilling. Metal-coated configurations retain margin concentration in offshore and deepwater contracts where cladding integrity carries the highest failure cost.
EPA underground injection control regulations and API 5CRA/5CT standards govern material selection, testing protocols, and traceability requirements across US oilfield supply chains. The EU F-Gas Regulation and REACH chemical restrictions are reshaping coating chemistry development for European deployment, forcing reformulation of certain epoxy and phenolic resin systems. Stakeholders must monitor evolving methane performance standards from EPA and state-level regulators that will increasingly tie casing specification to full-well lifecycle emissions accounting.
Market Dynamics
API 5CT certification and NACE TM0177 sour-service qualification requirements are redrawing competitive boundaries among suppliers, forcing capital retooling and disqualifying legacy coating operations that cannot meet revised adhesion and permeability thresholds.
Growth Catalysts
- EPA underground injection control regulations:Operators in the Permian Basin and Gulf of Mexico must replace unprotected casing strings to meet revised well integrity standards, accelerating replacement cycles for corrosion-susceptible assets.
- Deepwater drilling expansion:Composite-coated tubulars are penetrating pre-salt and ultra-deepwater projects where thermal insulation and weight reduction extend reach capability beyond conventional steel limits.
- H2S and CO2 partial pressure thresholds:Sour gas formations across North American shale plays are forcing specification upgrades to polymer-barrier systems that prevent sulfide stress cracking.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol-A and specialty hardener supply concentration in East Asian petrochemical corridors creates margin compression for coating applicators without captive chemical sourcing.
- API 5CRA qualification timelines:New corrosion-resistant alloy substrates require 18-24 month testing protocols before commercial deployment, delaying product line extensions.
- Thermoplastic composite substitution:Spoolable reinforced thermoplastic pipe is capturing certain onshore gathering applications that previously specified coated steel casing.
Strategic Opportunities
- Carbon capture and storage well construction:CO2 injection specifications are creating demand for ultra-high-barrier coatings that prevent supercritical fluid permeation through casing walls.
- Geothermal energy expansion:High-temperature polymer-ceramic hybrid systems are penetrating enhanced geothermal systems where thermal cycling exceeds conventional coating limits.
- EU F-Gas Regulation reformulation services:Coating chemistry providers can capture value by reformulating epoxy and phenolic systems to eliminate restricted fluorinated compounds before 2030 phase-down deadlines.
Industry Challenges
- NACE TM0177 testing capacity:Qualified sour-service certification laboratories face 6-9 month backlogs, delaying product launches and customer qualification programs.
- Multi-layer coating integration:Bonding dissimilar polymer, metal, and ceramic layers without delamination under thermal shock requires process engineering capabilities scarce outside integrated tubular manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Casing Market |
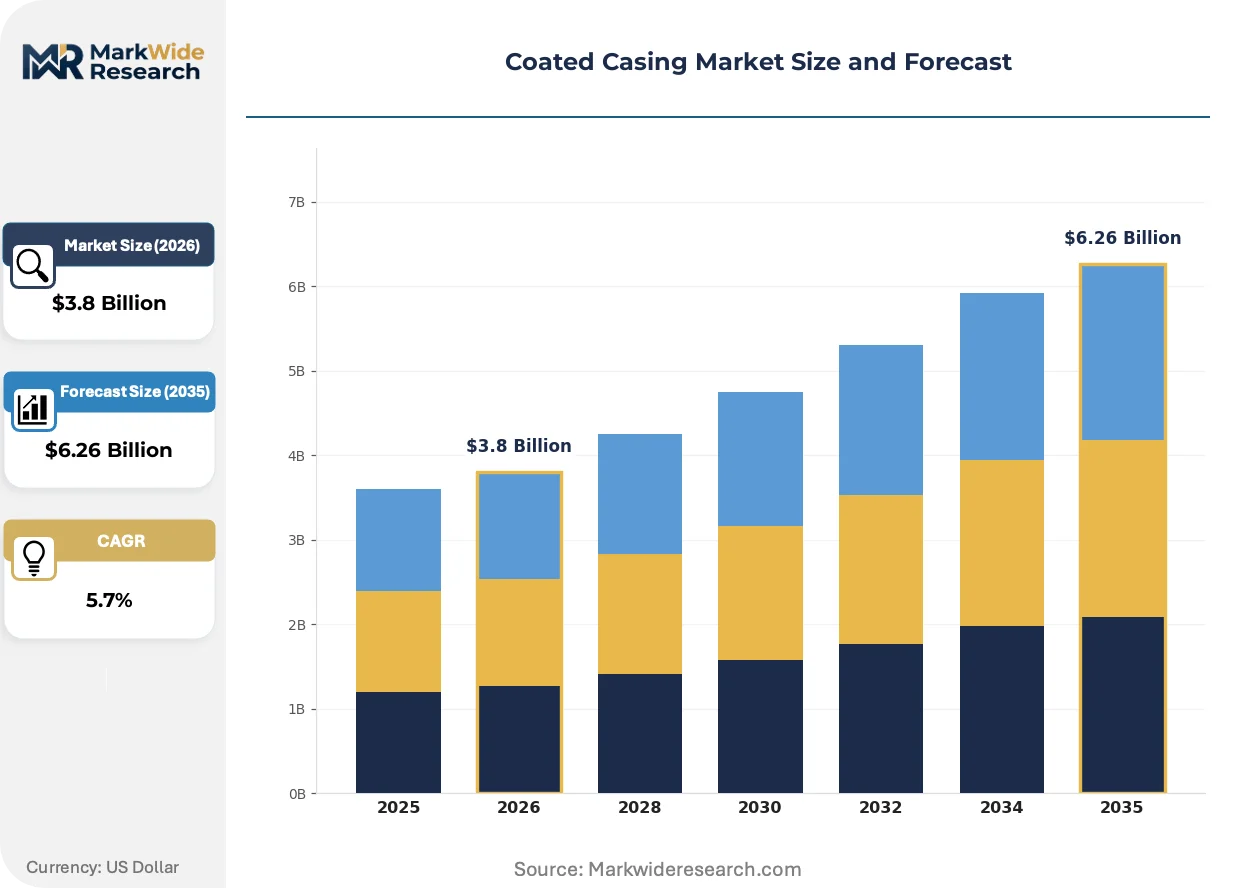
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coated, Metal Coated, Composite Casing, Rubber Coated Application: Oil & Gas, Water Well, Industrial, Mining End User: Energy Sector, Water Utilities, Manufacturing, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Viscofan Group, Kalle GmbH, Devro PLC, Nitta Casings Inc., Viskase Companies, DAT-Schaub Group, Elshazly Casings Company, FABIOS S.A., Oversea Casing Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Casing Market Emerging Trajectories
Material science convergence and regulatory chemistry restrictions are actively reshaping how coating formulations are developed, tested, and deployed across oilfield service tiers.
Polymer-ceramic nanocomposite barrier coatings are displacing conventional fusion-bonded epoxy in high-temperature steam-assisted gravity drainage applications. Canadian oil sands operators are specifying these systems for thermal wells where 250°C operating temperatures degrade standard polymer matrices. The shift is compressing addressable market share for single-layer epoxy suppliers without ceramic loading capabilities.
EU F-Gas Regulation restrictions on hydrofluorocarbon propellants and certain epoxy curing agents are forcing coating manufacturers to reformulate solvent systems and hardener chemistries. Industrial consequence includes extended curing cycles and modified application equipment requirements. European coating applicators are responding by qualifying waterborne and high-solids alternatives ahead of 2030 phase-down milestones.
Integrated casing-and-coating procurement contracts are consolidating vendor relationships around full-well tubular packages rather than commodity coating services. Major independents in the Permian Basin are negotiating multi-year supply agreements that bundle threading, inspection, and coating application under single-source accountability. This pattern is most visible among operators pursuing EPA methane performance certifications that require traceable material documentation across the entire casing string.
Coated Casing Market Segmentation
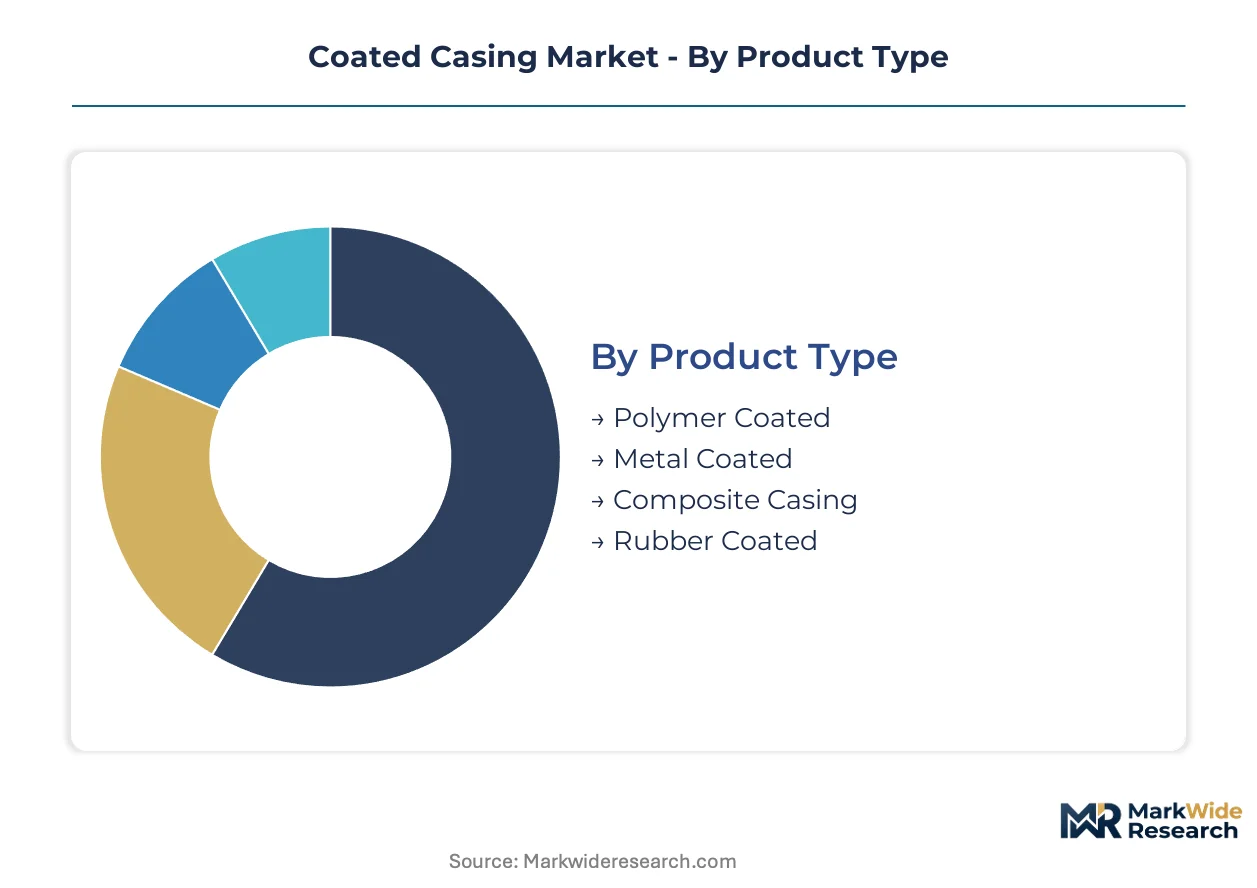
Coated casing procurement patterns diverge sharply between integrated energy majors and fragmented water utility buyers. Channel economics and technical qualification requirements create distinct competitive arenas across each segment boundary.
Product Type:
Direct sales channels dominate polymer and metal coated volumes through mill-direct contracts with Permian and Gulf of Mexico operators. Distributor networks capture composite and rubber variants for smaller water well and industrial accounts lacking in-house metallurgical expertise.
- Polymer Coated:Fusion-bonded epoxy and multi-layer polyolefin systems bond to steel substrates at 3,000+ psi adhesion per ASTM D4541. Permian Basin shale operators specify these for H2S service after EPA underground injection control revisions forced replacement of unprotected strings. By volume, polymer coated leads. By growth pace, composite casing is ahead.
- Metal Coated:Clad or metallurgically bonded overlays—typically stainless steel or nickel alloy—deliver impermeable barriers for ultra-deepwater pre-salt projects. Gulf of Mexico contractors concentrate procurement here where failure costs exceed $50 million per well.
- Composite Casing:Glass or carbon fiber-reinforced thermoset matrices reduce weight 40-60% versus steel while providing thermal insulation for extended-reach drilling.
- Rubber Coated:Elastomeric linings address abrasion in mining slurry transport and certain water well applications with moderate chemical exposure.
Cost tiers separate these categories: metal coated commands premium pricing for offshore contracts, polymer coated occupies the mid-market volume position, while composite and rubber variants compete on specialized performance metrics rather than price.
Application:
Oil and gas applications absorb the majority of qualified coating capacity due to NACE TM0177 sour-service certification requirements. Water well and industrial segments flow through distributor channels with less stringent material traceability demands.
- Oil & Gas:Exploration, production, and injection wells across conventional, unconventional, and deepwater formations. North American shale plays and Brazilian pre-salt developments anchor demand concentration as operators replace corrosion-susceptible assets.
- Water Well:Municipal and agricultural groundwater extraction systems. Water utilities in the Ogallala Aquifer region specify polymer barriers to prevent casing degradation from saline intrusion and bacterial corrosion.
- Industrial:Process water, cooling systems, and chemical containment infrastructure. Manufacturing facilities with captive well fields drive specification for epoxy-coated strings in the US Rust Belt.
- Mining:Dewatering, slurry transport, and heap leach operations. Copper and gold producers in the Southwest specify abrasion-resistant rubber linings for high-solids groundwater pumping.
Application maturity varies: oil and gas represents the established revenue base, while geothermal energy expansion is accelerating industrial segment specification for high-temperature polymer-ceramic hybrids.
End User:
Energy sector buyers consolidate procurement through integrated casing-and-coating contracts with single-source accountability. Water utilities and manufacturing accounts fragment across regional distributors with limited technical specification capability.
- Energy Sector:Integrated majors, independents, and national oil companies operating exploration and production assets. Permian Basin independents negotiate multi-year supply agreements bundling threading, inspection, and coating application.
- Water Utilities:Municipal water departments, rural water districts, and agricultural cooperatives managing groundwater infrastructure. Smaller districts rely on distributor technical support for material selection.
- Manufacturing:Process industries with captive water supply needs—paper, chemicals, food processing. These accounts prioritize lead time and local inventory over customized coating formulations.
- Construction:Geotechnical, dewatering, and foundation contractors with temporary or semi-permanent well installations. Price sensitivity here favors standard polymer coatings through reseller channels.
Customer concentration differs markedly: energy sector procurement clusters among 200-300 qualified buyers globally, while water utilities fragment across thousands of municipal and cooperative entities.
Distribution Channel:
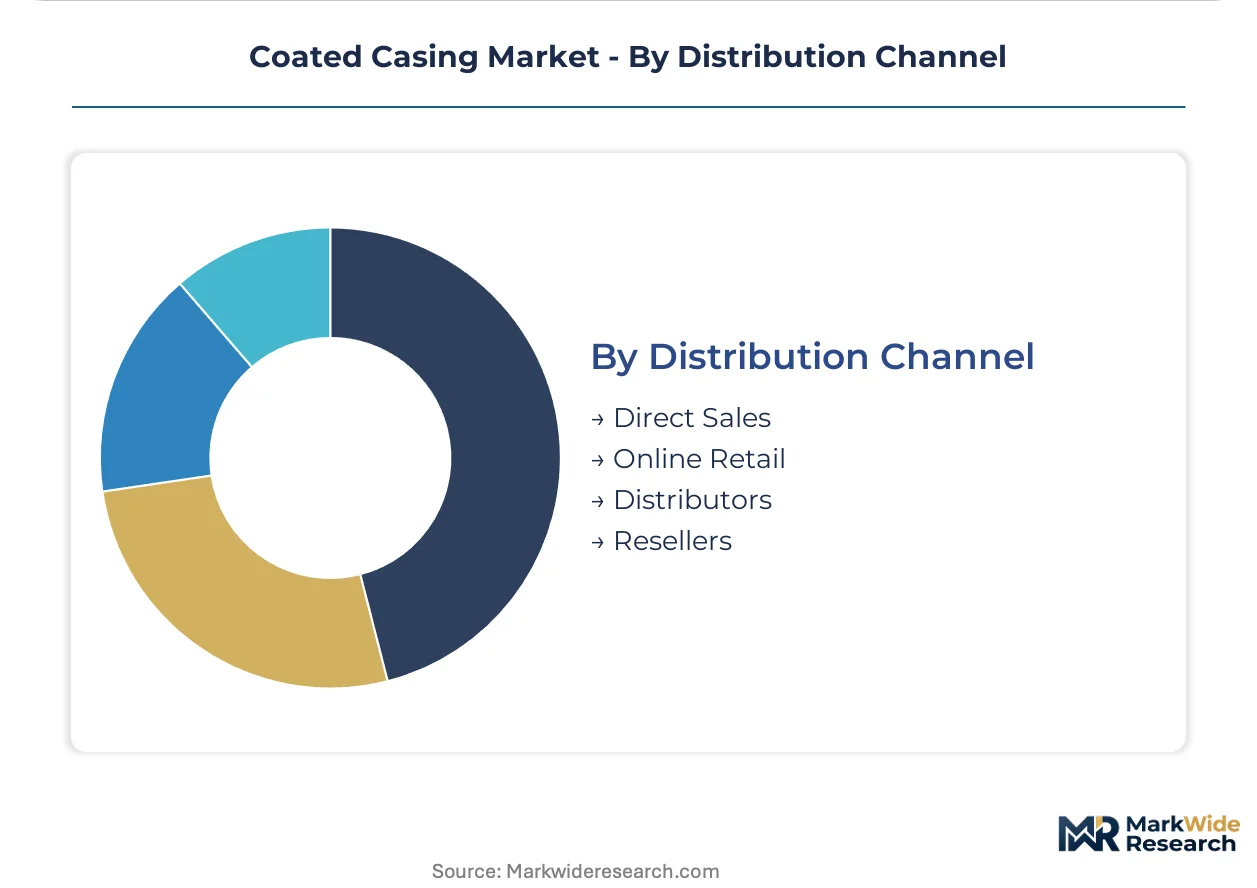
Channel selection correlates directly with technical complexity and contract scale. Direct sales capture high-value oilfield business; distributors and resellers serve price-sensitive, specification-simple segments.
- Direct Sales:Mill-direct contracts between coating applicators and end users with in-house metallurgical expertise. Gulf of Mexico deepwater projects and Permian Basin shale programs flow through this channel exclusively.
- Distributors:Regional and national industrial supply houses carrying inventoried standard grades. Water well contractors and smaller mining operators source polymer-coated strings through this channel for availability and credit terms.
- Online Retail:Emerging platform for standard dimensions and commodity specifications. Construction dewatering contractors increasingly specify coated casing through digital channels for project-based procurement.
- Resellers:Independent agents and brokers facilitating spot purchases and non-standard sizes. This channel captures emergency replacement demand and geographically dispersed small-volume accounts.
Channel economics favor consolidation: direct sales generate highest margin per ton but require qualification investment, while online and reseller channels expand addressable market reach at compressed returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA underground injection control revisions and EU F-Gas Regulation phase-down timelines are redrawing procurement patterns across major oilfield service corridors. National regulators in producing regions are tightening material traceability requirements that favor qualified coating applicators with certified laboratory partnerships.
United States
Permian Basin independents and Gulf of Mexico deepwater contractors anchor North American demand concentration. EPA methane performance standards and revised API 5CT qualification protocols are forcing replacement cycles for corrosion-susible casing strings. Houston-area coating applicators are consolidating threading, inspection, and barrier application services under single-source contracts to meet traceability requirements.
Brazil
Pre-salt development programs in the Santos Basin are specifying composite-coated tubulars for ultra-deepwater reach extension. ANP local content regulations and Petrobras technical specifications govern material qualification timelines for foreign coating suppliers. Rio de Janeiro state clusters are expanding metallurgical bonding capacity to serve pre-salt drilling campaigns.
Norway
North Sea mature field redevelopment and Barents Sea frontier drilling are sustaining premium metal-coated procurement volumes. PSA well integrity regulations and OSPAR chemical restrictions are reshaping coating chemistry approval processes for subsea installations. Stavanger-area engineering houses are qualifying polymer-ceramic hybrids for high-pressure high-temperature gas condensate service.
China
Sichuan Basin shale gas development and South China Sea deepwater programs are expanding domestic coating application capacity. MEE environmental compliance inspections and GB/T petroleum equipment standards are tightening quality documentation requirements. Tianjin and Qingdao port clusters are integrating coating services with seamless tubular manufacturing for export contract competitiveness.
Saudi Arabia
Marjan and Zuluf field expansion projects are specifying sour-service qualified casing strings for high-H2S carbonate reservoirs. Saudi Aramco engineering standards and in-kingdom total value add requirements are localizing coating application services. Eastern Province industrial cities are attracting joint-venture investments in corrosion-resistant alloy cladding facilities.
Coated Casing Market Vendor Landscape
Player mix skews toward integrated tubular manufacturers with captive coating capabilities and specialized polymer science heritage companies extending formulations into oilfield applications. Market structure concentrates procurement decisions among 200-300 qualified energy sector buyers globally, compressing addressable vendor relationships around certified suppliers. Two strategic archetypes dominate: integrated steel mills with in-house fusion-bonded epoxy lines, and independent coating applicators with NACE TM0177 laboratory partnerships. Competitive moves center on API 5CRA qualification investments and multi-year supply agreement consolidation with Permian and Gulf of Mexico operators.
Within the polymer science heritage tier, Viscofan Group exemplifies barrier-coating formulation extension from food packaging into oilfield service applications. Kalle GmbH anchors European supply positioning through regenerated cellulose substrate manufacturing capabilities. Devro PLC occupies a specialist position bridging collagen-based technical and edible casing platforms. These three entities represent divergent material science origins converging on downhole barrier performance requirements.
| Leading Market Players |
|---|
| Viscofan Group |
| Kalle GmbH |
| Devro PLC |
| Nitta Casings Inc. |
| Viskase Companies |
| DAT-Schaub Group |
| Elshazly Casings Company |
| FABIOS S.A. |
| Oversea Casing Company LLC |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification backlogs at NACE TM0177 laboratories concentrate pricing power among certified applicators with captive testing partnerships, compressing margins for second-tier coating operations without integrated sour-service validation. This lead-time asymmetry rewards Houston and Stavanger clusters with multi-year contract premiums while forcing uncertified competitors toward spot-market commodity pricing.
Pricing Analysis
Certification level (API 5CT/NACE TM0177-qualified versus uncertified) creates the primary spread, with sour-service validated strings commanding substantial premiums over standard fusion-bonded epoxy alternatives. Three-tier pricing structure separates ultra-deepwater metal-clad configurations from mid-market polymer-barrier systems and economy-grade rubber-lined products for water well applications. Cost compression in standard polymer coatings is intensifying because East Asian epoxy resin feedstock concentration exposes applicators to bisphenol-A supply volatility. Water utilities and construction dewatering contractors exhibit highest price sensitivity, while Gulf of Mexico deepwater operators prioritize failure-cost mitigation over unit economics.
Supply Chain Analysis
Forty-five to sixty days of coated tubular inventory sits at Houston and Qingdao port clusters, with mill-direct contracts bypassing distributor stockholding for Permian Basin shale programs. Geographic supply concentration centers on the United States, China, and Germany, with seamless tubular manufacturing drawing from integrated steel mills in each corridor. Raw material dependencies rest on East Asian petrochemical corridors for epoxy resin systems, European specialty chemical producers for high-performance hardeners, and domestic steel substrates for North American contract fulfillment. Single-source vulnerability in NACE-certified laboratory capacity creates qualification bottlenecks that propagate through downstream scheduling. Distribution runs through mill-direct channels for energy sector procurement and regional industrial distributors for water well and mining accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spoolable reinforced thermoplastic pipe substitution threatens coated steel casing in onshore gathering applications, forcing incumbents to defend position through qualification barriers and integrated service bundling.
For Market Incumbents: Fortify API 5CRA qualification investments and captive NACE laboratory partnerships to extend certification backlogs into competitive moats. Deepen backward integration into epoxy resin formulation to offset East Asian feedstock volatility and secure margin control. Bundle threading, inspection, and coating application under single-source accountability contracts that thermoplastic substitutes cannot replicate. For New Entrants and Emerging Players: Geothermal energy high-temperature polymer-ceramic hybrid specifications represent the most penetrable white-space where incumbent qualification investments lag application demand. Target EU F-Gas Regulation reformulation services ahead of 2030 phase-down deadlines, offering waterborne and high-solids alternatives to established epoxy systems. Pursue qualification partnerships with Stavanger or Rio de Janeiro engineering houses to bypass NACE laboratory capacity constraints. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EPA methane performance standards and API specification evolution continuously raise entry barriers for uncapitalized competitors. Acquisition target archetype: independent coating applicators with NACE TM0177 laboratory partnerships and established Permian or Gulf of Mexico operator relationships. Watch NACE testing capacity expansion announcements as the inflection signal for competitive qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| API 5CRA Qualification Investment | Establishes sour-service certification moats that disqualify legacy coating operations from Permian Basin contracts. |
| Backward Integration into Resin Formulation | Captures margin control over epoxy chemistry and insulates against East Asian bisphenol-A supply volatility. |
| Integrated Casing-and-Coating Contracts | Bundles threading, inspection, and barrier application under single-source accountability for EPA traceability requirements. |
| EU F-Gas Reformulation Services | Captures value from coating chemistry providers eliminating restricted fluorinated compounds before 2030 deadlines. |
| Geothermal High-Temperature Hybrid Development | Penetrates enhanced geothermal systems where thermal cycling exceeds conventional polymer coating limits. |
Methodological Framework
Desk research of API specification documentation, EPA regulatory filings, and NACE technical standards preceded structured interviews with coating applicator operations managers, Permian Basin procurement directors, Gulf of Mexico drilling engineers, and NACE laboratory certification leads. Secondary validation drew from customs trade data, tubular manufacturer SEC disclosures, and ANP local content regulations. Bottom-up volume estimates triangulated against top-down energy sector capex allocations across the analysis window.
Variance decomposition across product type, application, end user, and distribution channel dimensions informed segment-level growth trajectories throughout the forecast period. Modeled inputs included well completion counts by basin, sour-service specification penetration rates, and coating application capacity utilization at Houston-area facilities. CAGRs derived from regression against historical replacement cycle data and regulatory-driven upgrade mandates.
Underlying assumptions cover sustained EPA enforcement of underground injection control standards and continued deepwater drilling expansion in Brazilian pre-salt formations, with deviation risk concentrated in thermoplastic pipe substitution rates and NACE laboratory capacity expansion timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Anti-Friction Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Coating Pre-Treatment Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Insulation Coating Market
Coatings
United States Floor Coatings Market
Coatings
France Protective Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
China Marine Coatings Market