
 Vinyl Surface Coatings Market | 2026-2036
Vinyl Surface Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Surface Coatings Market Intelligence
New production capacity in China is narrowing the technology gap with established European and North American producers. BASF SE leverages its extensive chemical integration to control raw material costs. AkzoNobel N.V. specializes in performance coatings for industrial applications. The Sherwin-Williams Company dominates the architectural coatings channel in North America.
Vinyl surface coatings are polymer-based films applied to substrates for protection and aesthetic enhancement. These formulations, often derived from polyvinyl chloride, provide chemical resistance and weatherability. The construction and automotive segments command the largest share of applications. A technology shift from solvent-based to water-based and UV-cured systems is accelerating due to environmental pressures.
Regulatory frameworks like Europe's REACH directive and VOC limits set by the US EPA directly influence formulation chemistry. In parallel, China's GB standards for building materials and consumer goods impose strict performance and safety requirements. Suppliers must therefore navigate this complex compliance landscape while managing raw material volatility to maintain profitability.
Market Dynamics
The central structural force shaping the market is the stringent regulatory push to lower volatile organic compound (VOC) emissions. This is compelling a market-wide technology transition from traditional solvent-based formulations toward water-based and UV-cured systems, altering both production processes and raw material supply chains.
Growth Catalysts
- Automotive Sector Demand:The expansion of the automotive industry drives consumption of vinyl coatings for both interior and exterior components, where they provide essential weatherability, chemical resistance, and aesthetic finishes.
- Regulatory Modernization:Europe's REACH directive incentivizes the development and use of vinyl coatings with improved safety profiles, creating a clear market pull for innovative, compliant formulations that replace legacy chemicals.
- Asian Construction Boom:Large-scale infrastructure and residential construction projects, particularly in China, fuel significant volume demand for vinyl coatings, supported by national GB standards that mandate specific performance criteria for building materials.
Market Restraints
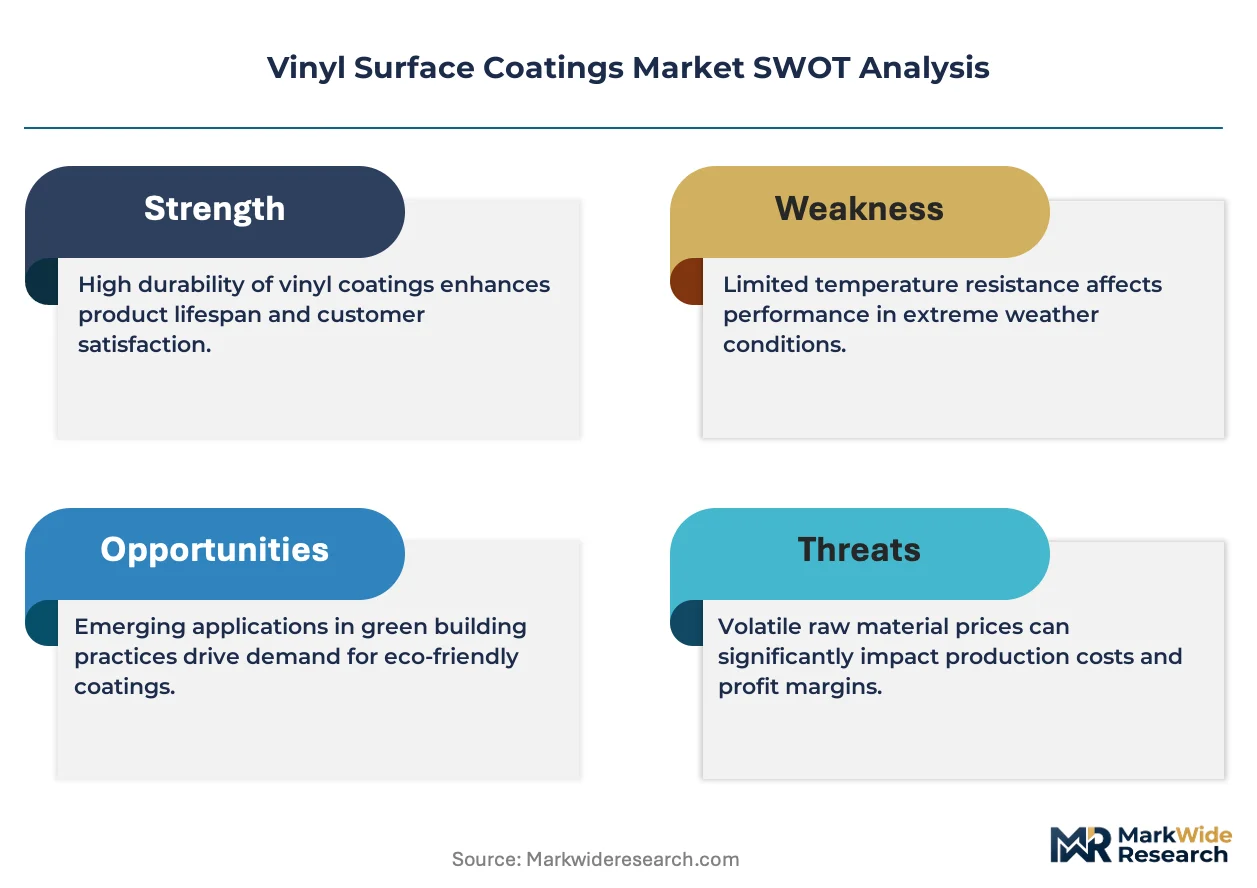
- Raw Material Volatility:The price of key precursors, such as vinyl chloride monomer (VCM) and various plasticizers, is directly linked to fluctuating petrochemical and energy markets, creating significant margin uncertainty for coating manufacturers.
- Threat of Substitution:In demanding applications like industrial flooring and protective equipment, alternative coating technologies such as polyurethanes and epoxies offer superior abrasion resistance and hardness, limiting vinyl's market penetration.
- Complex Regulatory Landscape:Manufacturers face increased compliance costs and complexity navigating disparate VOC regulations between regions, such as the US EPA's national rules versus stricter, state-level mandates in California.
Strategic Opportunities
- Bio-Based Formulations:Developing vinyl polymers from renewable, bio-based feedstocks instead of traditional petrochemicals offers a pathway to meet corporate sustainability targets and appeal to environmentally conscious market segments.
- Functional Coating Development:Integrating additives like antimicrobial agents or nanoparticles to create functional vinyl surfaces for healthcare, public transport, and electronics opens high-value, specialized application areas.
- Expansion in Southeast Asia:As manufacturing and construction activity grows in countries like Vietnam and Indonesia, these markets represent a significant growth frontier for vinyl coatings outside of the more mature North American and European markets.
Industry Challenges
- Formulation Skills Gap:A persistent shortage of formulation chemists with deep expertise in developing stable and high-performing water-based and UV-cured systems slows the industry's transition away from well-understood solvent-based technologies.
- Lengthy OEM Certification:The extensive and time-consuming testing and validation processes required by original equipment manufacturers, especially in the automotive and aerospace sectors, create long lead times for the commercialization of new coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Surface Coatings Market |
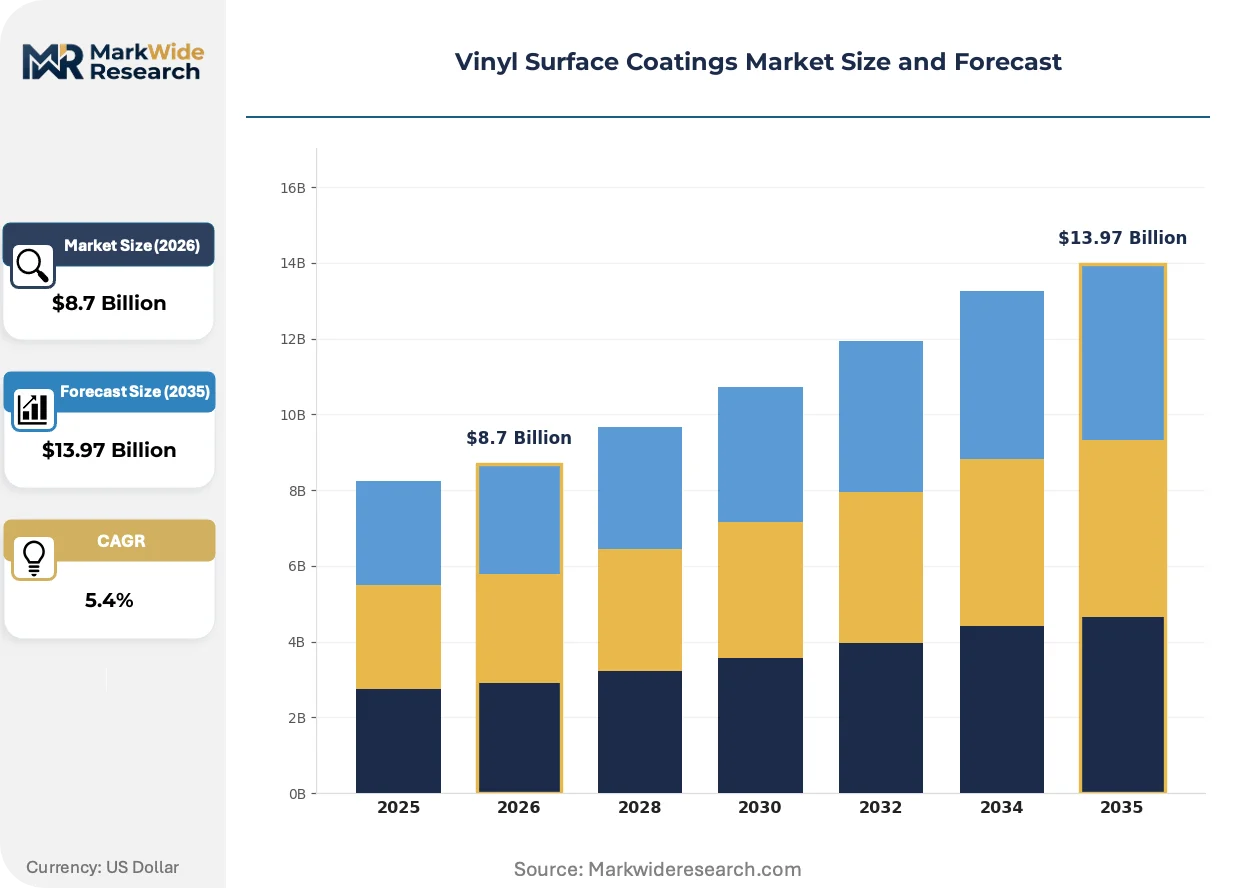
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, PVC Application: Automotive, Flooring, Furniture, Construction End User: Manufacturers, Contractors, Distributors, Retailers Technology: Water-Based, Solvent-Based, UV-Cured, Electrostatic |
| Companies Covered | BASF SE, AkzoNobel N.V., PPG Industries, Inc., Sherwin-Williams Company, RPM International Inc., Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Henkel AG & Co. KGaA, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Surface Coatings Market Strategic Shifts & Innovations
Formulation chemistry is undergoing a significant transformation. The industry is responding to dual pressures for higher performance in demanding applications and stricter environmental regulations, accelerating innovation in both polymer science and curing technologies. This shift prioritizes efficiency and compliance.
UV-cured vinyl coatings provide near-instantaneous polymerization when exposed to ultraviolet light, dramatically shortening production cycle times. High-volume manufacturing sectors, including electronics and automotive components, are adopting this technology for its efficiency. The speed and smaller footprint of UV systems is rendering obsolete the large, energy-intensive thermal ovens required for traditional solvent-based coating lines.
China's stringent GB standards for materials used in construction, furniture, and vehicles impose strict limits on VOCs and hazardous substances. This regulatory framework directly influences formulation choices for any company selling products into the Chinese domestic market. Consequently, coating suppliers are reformulating products to meet these specific local requirements, often accelerating their global transition to water-based systems.
A clear shift in industrial procurement is evident, with buyers increasingly specifying coatings based on lifecycle durability and documented environmental impact. This new evaluation criterion disrupts traditional sales models focused purely on cost per volume, favoring suppliers who can validate performance claims. The trend is most visible in the European architectural sector, where sustainability reporting under frameworks like the CSRD is becoming mandatory.
Vinyl Surface Coatings Market Segmentation
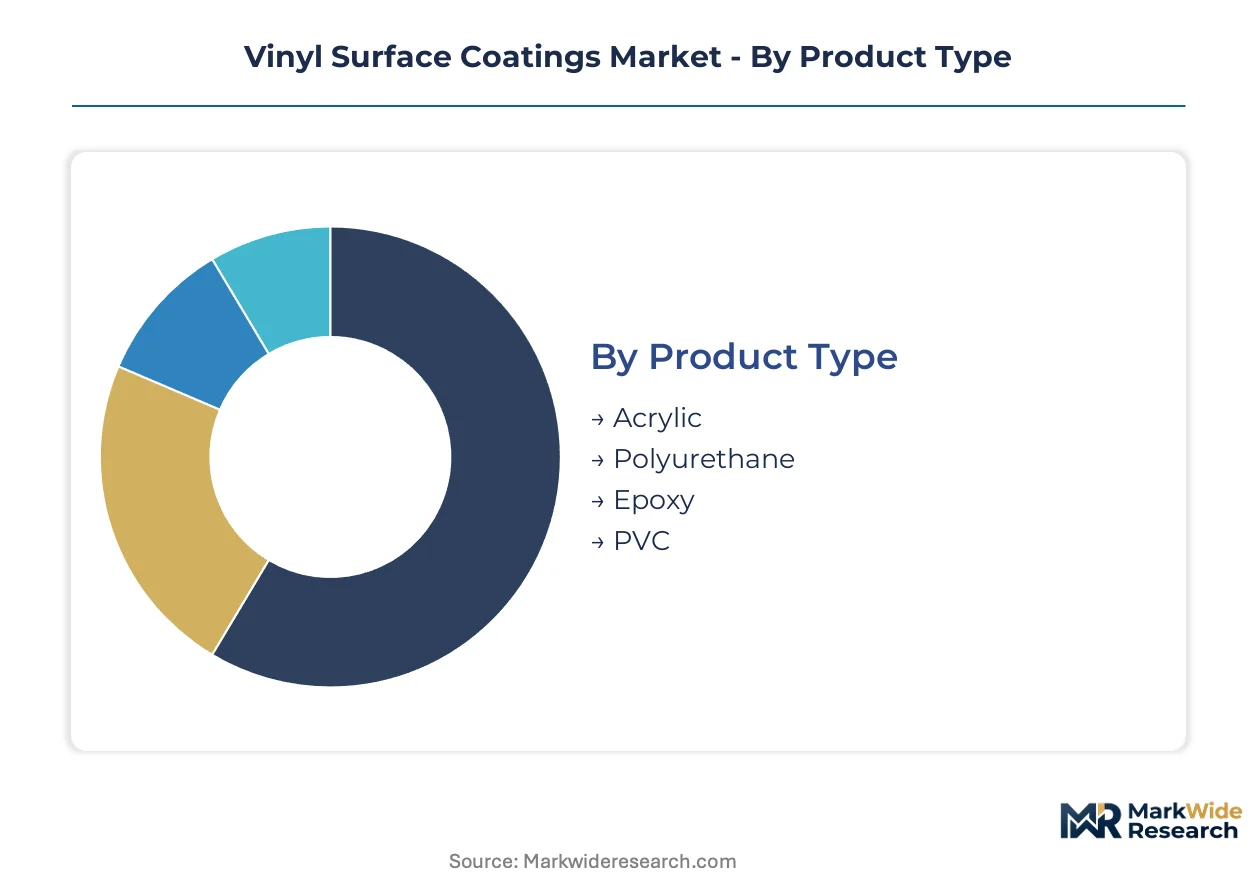
The Vinyl Surface Coatings market serves diverse industrial requirements, necessitating a granular understanding of its component segments. Segment analysis reveals critical variations in material properties, application methods, and end-user procurement channels. This detailed breakdown helps stakeholders identify specific growth vectors and navigate evolving regulatory demands across different product formulations.
Product Type:
The use-case spectrum for vinyl surface coatings spans various material compositions, each offering distinct performance characteristics for protection and aesthetic enhancement.
- PVC:Polyvinyl chloride formulations provide exceptional chemical resistance and weatherability, making them ideal for durable outdoor applications and industrial infrastructure in Germany and China. Demand concentrates in construction materials and automotive underbody protection, driven by stringent performance standards like China's GB standards.
- Acrylic:Acrylic-based coatings offer excellent UV stability and color retention, frequently employed in exterior architectural finishes and automotive topcoats across North America and Europe. This segment sees significant demand from the automotive refinish market and residential construction, supported by aesthetic durability requirements.
- Polyurethane:These coatings are prized for their abrasion resistance and flexibility, commonly used in flooring systems and protective equipment where mechanical stress is high.
- Epoxy:Epoxy formulations deliver superior adhesion and hardness, making them suitable for heavy-duty industrial floors and protective linings in chemical processing plants.
Established volume favors PVC; emerging adoption favors Acrylic.
Application:
The application focus within the vinyl surface coatings market highlights distinct performance requirements and volume consumption patterns across key industrial sectors.
- Automotive:Vinyl coatings protect interior and exterior automotive components from wear, chemicals, and UV radiation, enhancing vehicle longevity and appearance for manufacturers in Japan and South Korea. OEM specifications for durability and aesthetic integration, alongside strict US EPA VOC regulations, drive demand.
- Construction:This segment utilizes vinyl coatings for roofing membranes, siding, and flooring, providing weather protection and aesthetic finishes for large-scale infrastructure projects in India and Brazil. Large-scale infrastructure development and residential building booms in emerging economies are primary demand drivers.
- Flooring:Specialized vinyl formulations deliver durable and easy-to-maintain surfaces for commercial, industrial, and residential flooring installations.
- Furniture:Coatings for furniture provide scratch resistance, color stability, and a decorative finish, meeting consumer aesthetic preferences and durability expectations.
Volume is concentrated in Automotive; innovation targets Construction.
End User:
Customer type segmentation reveals varied procurement strategies and service requirements across the vinyl surface coatings value chain.
- Manufacturers:Large industrial manufacturers integrate vinyl coatings directly into their production processes for finished goods like automotive parts or building materials in Germany and the United States. Their procurement emphasizes consistent quality, bulk supply, and technical support for seamless integration into high-volume assembly lines.
- Contractors:Construction and renovation contractors purchase vinyl coatings for on-site application in commercial, residential, and infrastructure projects across Europe and the Middle East. These buyers prioritize ease of application, fast curing times, and compliance with local building codes, such as those enforced by regional authorities in France.
- Distributors:These entities manage inventory and supply chains, providing a wide range of vinyl coating products to smaller businesses and specialized applicators.
- Retailers:Retail channels cater to individual consumers and small-scale professional users, offering ready-to-use vinyl coating products for DIY projects and minor repairs.
Procurement patterns center on Manufacturers; specialized services define Contractors.
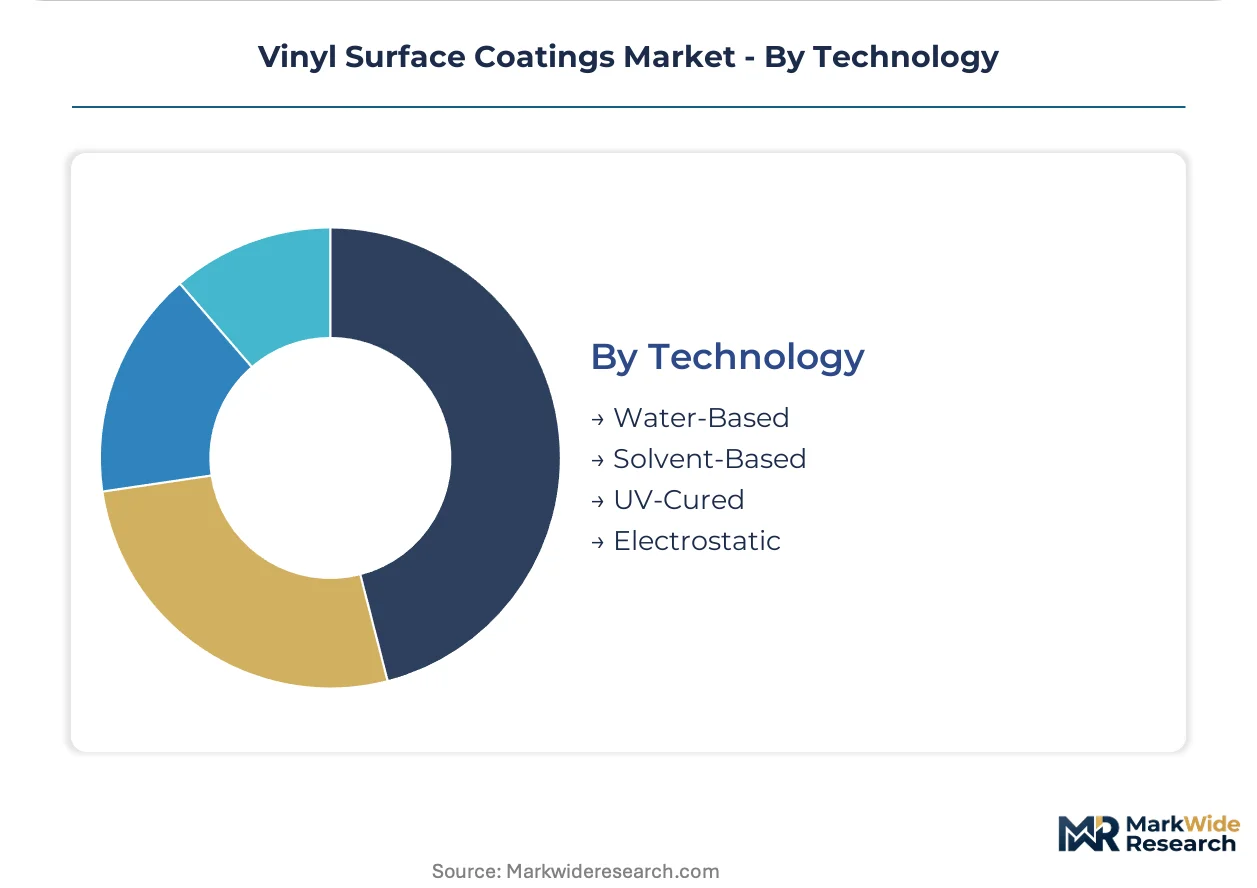
Technology:
The maturity of coating technologies influences production processes and environmental compliance, driving innovation across various formulation approaches.
- Water-Based:These systems utilize water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions, aligning with Europe's REACH directive and US EPA standards. Demand is accelerating due to stringent environmental regulations and corporate sustainability initiatives, particularly in architectural and automotive interior applications.
- UV-Cured:UV-cured coatings polymerize rapidly under ultraviolet light, offering fast processing speeds and high durability for applications in electronics and automotive components. This technology is gaining traction in high-volume manufacturing due to its efficiency, reduced energy consumption, and minimal VOC release.
- Solvent-Based:Traditional solvent-based systems provide excellent film formation and durability but face increasing regulatory pressure due to their higher VOC content.
- Electrostatic:This application method uses electrostatic attraction to achieve high transfer efficiency and uniform coating thickness, minimizing material waste in industrial settings.
Market share consolidates around Water-Based systems; future growth hinges on UV-Cured innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's demand for vinyl surface coatings is heavily skewed towards construction and automotive production, while European and North American markets prioritize lower VOC formulations and aesthetic durability. This divergence influences regional product development and regulatory compliance. Different end-user requirements shape regional market dynamics.
China
China's extensive infrastructure development and booming automotive sector significantly drive vinyl coating consumption. National GB standards for building materials impose strict performance and safety requirements. Manufacturing hubs in the Yangtze River Delta actively reformulate products to meet these local regulations.
Germany
Germany's robust industrial manufacturing, particularly in automotive and durable goods, generates consistent demand for high-performance vinyl coatings. Europe's REACH directive incentivizes compliant, safer formulations across the country. Industrial centers in Bavaria integrate these advanced coatings directly into high-volume assembly lines.
United States
United States automotive production and architectural sector expansion consume significant volumes of vinyl coatings. The US EPA sets national VOC limits, with stricter state-level mandates in California impacting formulation choices. Automotive manufacturing clusters in Michigan increasingly specify durable, low-VOC coatings for vehicle longevity.
India
India's rapid urbanization and extensive infrastructure development fuel substantial demand for vinyl coatings in construction applications. The Bureau of Indian Standards (BIS) mandates specific quality and performance criteria for building materials. Major construction hubs and industrial corridors require large volumes of weather-protective and aesthetic finishes.
Japan
Japanese automotive manufacturers and electronics producers drive demand for high-performance vinyl coatings, prioritizing durability and aesthetic integration. Japanese Industrial Standards (JIS) influence material specifications for industrial products. Major automotive OEM facilities in industrial cities specify advanced UV-cured systems for efficiency.
Vinyl Surface Coatings Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the vinyl surface coatings market. The industry exhibits a tiered structure, with large chemical conglomerates and specialized performance coating manufacturers. Strategic archetypes include diversified chemical giants, focused industrial coating specialists, and regional architectural coating leaders. Companies primarily engage in capacity expansion and strategic partnerships to secure raw material supply, broaden application reach, and navigate evolving regulatory pressures.
Diversified chemical giants like BASF SE exemplify the broad integration of raw material production with advanced chemical formulations, leveraging extensive chemical integration for cost control. AkzoNobel N.V. represents a focused approach, specializing in performance coatings for industrial applications globally, emphasizing innovation in specific end-use segments. The Sherwin-Williams Company anchors the North American architectural coatings channel, demonstrating strong regional market penetration and distribution capabilities. These entities collectively shape the competitive dynamics through their distinct operational models and market focus on compliance and performance.
| Leading Market Players |
|---|
| BASF SE |
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| Sherwin-Williams Company |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Henkel AG & Co. KGaA |
| Hempel |
| Others |
Cost & Logistics Intelligence
Manufacturing hubs within China's Yangtze River Delta, with their expanding production capacity, increasingly dictate global vinyl coating pricing power. This concentration shapes downstream cost structures for manufacturers worldwide.
Pricing Analysis
Regional price spreads for vinyl surface coatings reflect diverse regulatory and quality demands. The dominant pricing model involves contract-based long-term offtake for large manufacturers, with price differentiation driven by compliance with REACH or GB standards and customization. Pricing pressure intensifies due to raw material volatility. Automotive manufacturers show lower price sensitivity, prioritizing performance, while smaller contractors and retailers remain highly cost-conscious.
Supply Chain Analysis
Upstream feedstock for vinyl surface coatings, primarily derived from petrochemicals, originates heavily from industrial centers in China, the United States, and Germany. The supply chain relies on key inputs like vinyl chloride monomer (VCM) and various plasticizers. A significant structural risk involves commodity price volatility for these petrochemical precursors. Downstream distribution typically involves direct sales to large industrial manufacturers and through specialized distributors for contractors and retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vinyl surface coatings market necessitates a strong substitution defense, as incumbents must strategically navigate the persistent threat from alternative technologies like polyurethanes and epoxies. These alternatives offer superior performance in demanding applications.
For Market Incumbents:Insulate core market share by accelerating R&D into high-performance water-based and UV-cured formulations. This counters the regulatory shift from solvent-based systems. Deepen backward integration for key raw materials to mitigate petrochemical price volatility. Invest in OEM certification processes to secure long-term contracts.
For New Entrants and Emerging Players:Establish a beachhead in specialized functional coatings, such as antimicrobial vinyl surfaces for healthcare environments. This represents a high-value, underpenetrated segment. Target expanding construction markets in Southeast Asia, leveraging demand for compliant building materials. A go-to-market angle focused on bio-based formulations offers differentiation.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-driven materials science play because environmental compliance and performance demands will reshape formulation chemistry. Target acquisition profiles should favor mid-sized companies specializing in advanced water-based or UV-cured technologies with strong OEM track records. The signal to watch is widespread adoption of bio-based feedstocks in high-volume applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for UV-Cured Systems | Supports high-volume manufacturing sectors like electronics and automotive components with faster cycle times. |
| Backward Integration into VCM Production | Mitigates raw material volatility for coating manufacturers and secures supply for PVC formulations. |
| Green Manufacturing Transition | Addresses stringent environmental regulations like Europe's REACH directive and US EPA VOC limits. |
| Joint Venture in Southeast Asia | Penetrates new construction and manufacturing markets in countries like Vietnam and Indonesia. |
| Functional Coating Development | Creates high-value application areas in healthcare and public transport using antimicrobial agents. |
Research Approach
Desk research of regulatory filings, industry association reports, and company financial statements preceded structured interviews with R&D chemists, automotive OEM procurement leads, and distributors. This approach combined primary insights with secondary validation. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy across market segments.
Assumptions regarding regulatory stability and raw material price trends were held constant across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, and technology. Compound annual growth rates were derived from historical data and projected growth drivers, with automotive production volumes serving as a key forecast input.
Sensitivities concentrate around sudden shifts in global petrochemical prices and the introduction of new, stricter VOC regulations. Forecasts reflect these documented assumptions. Cross-checking against major industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Qatar Protective Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Global Performance Coating Market
Coatings
Global Nanocoatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Russia Protective Coatings Market
Coatings
E-Coat Market
Coatings
Hard Coating Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Germany Automotive OEM Coatings Market