
 Global Laser Cladding Service Market | 2026-2036
Global Laser Cladding Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laser Cladding Service Market Foresight
Germany is rewriting the competitive map for laser cladding services through its dense network of TRUMPF-equipped job shops and metallurgy research institutes. IPG Photonics Corporation leverages its fiber laser dominance to anchor high-power cladding contracts across North American energy infrastructure. Höganäs AB sustains powder supply agreements that control material consistency for European aerospace repair networks. Jenoptik specializes in optical systems that differentiate German service providers on deposition precision.
Laser cladding service applies concentrated laser energy to melt metallic powder onto a substrate, achieving bond strengths exceeding 400 MPa with minimal dilution for dimensional restoration and surface protection. The process serves primarily to extend component life in high-wear environments where replacement costs dwarf refurbishment expenditure. Metal alloy coatings occupy the largest share of product type revenue due to their versatility across aerospace and power generation repair contracts. Ceramic coatings represent the fastest-growing product segment as gas turbine operators seek thermal barrier performance beyond conventional superalloy limits. Wear resistance services command premium pricing in oilfield tool refurbishment where downtime costs escalate rapidly.
EPA emissions standards and OSHA workplace exposure limits constrain powder handling protocols at US cladding facilities, while REACH registration requirements govern chemical composition disclosure for European powder suppliers. The EU AI Act introduces documentation burdens for automated cladding path planning systems that machine learning algorithms now guide. Stakeholders must monitor how ISO 9001 and AS9100 certification requirements evolve for additive repair processes entering regulated aerospace supply chains.
Market Dynamics
The laser cladding service market pivots on a supply-side consolidation where high-power fiber laser availability concentrates among German and North American equipment networks, creating capacity bottlenecks for aerospace repair contracts requiring AS9100 certification.
Growth Catalysts
- EU F-Gas Regulation:Mandates for reduced fluorinated gas emissions push gas turbine operators toward laser cladding refurbishment rather than new component manufacturing, tightening circular economy loops in power generation.
- Aerospace blade restoration:Turbine operators facing extended maintenance intervals favor cladding over replacement for nickel superalloy airfoils, particularly where single-crystal casting supply chains stretch 18-24 months.
- Powder recycling infrastructure:German metallurgy clusters now capture and reclassify spent Inconel and cobalt-chrome powders, cutting material costs for job shops serving automotive tool repair.
Market Restraints
- Helium and argon price volatility:Shielding gas costs comprise 15-25% of cladding job pricing, with supply disruptions from Qatar and Russia squeezing European service margins unpredictably.
- Optics supply concentration:High-purity fused silica for laser delivery fibers concentrates among Japanese and German suppliers, creating single-source risk for North American cladding facilities.
- Plasma spray substitution:Thermal spray coatings retain cost advantage for non-critical wear surfaces, limiting cladding penetration in general industrial maintenance.
Strategic Opportunities
- Indian nuclear component repair:BIS certification pathways for indigenous pressurized heavy water reactor maintenance open captive demand for cobalt-free cladding alloys.
- Directed energy deposition convergence:Hybrid machine tools integrating milling spindles with cladding heads enable near-net-shape repair of large forging dies, collapsing separate process steps.
- US Inflation Reduction Act:Domestic content bonuses for renewable energy components incentivize onshore cladding capacity for wind turbine bearing seats and hydropower runner refurbishment.
Industry Challenges
- Multi-axis path programming expertise:Complex freeform geometries require CAM specialists fluent in powder feed rate modulation and thermal management, with training pipelines lagging demand in both Europe and North America.
- AS9100D audit timelines:Aerospace certification for additive repair processes stretches 14-18 months, freezing job shops out of OEM-approved supplier lists despite technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laser Cladding Service Market |
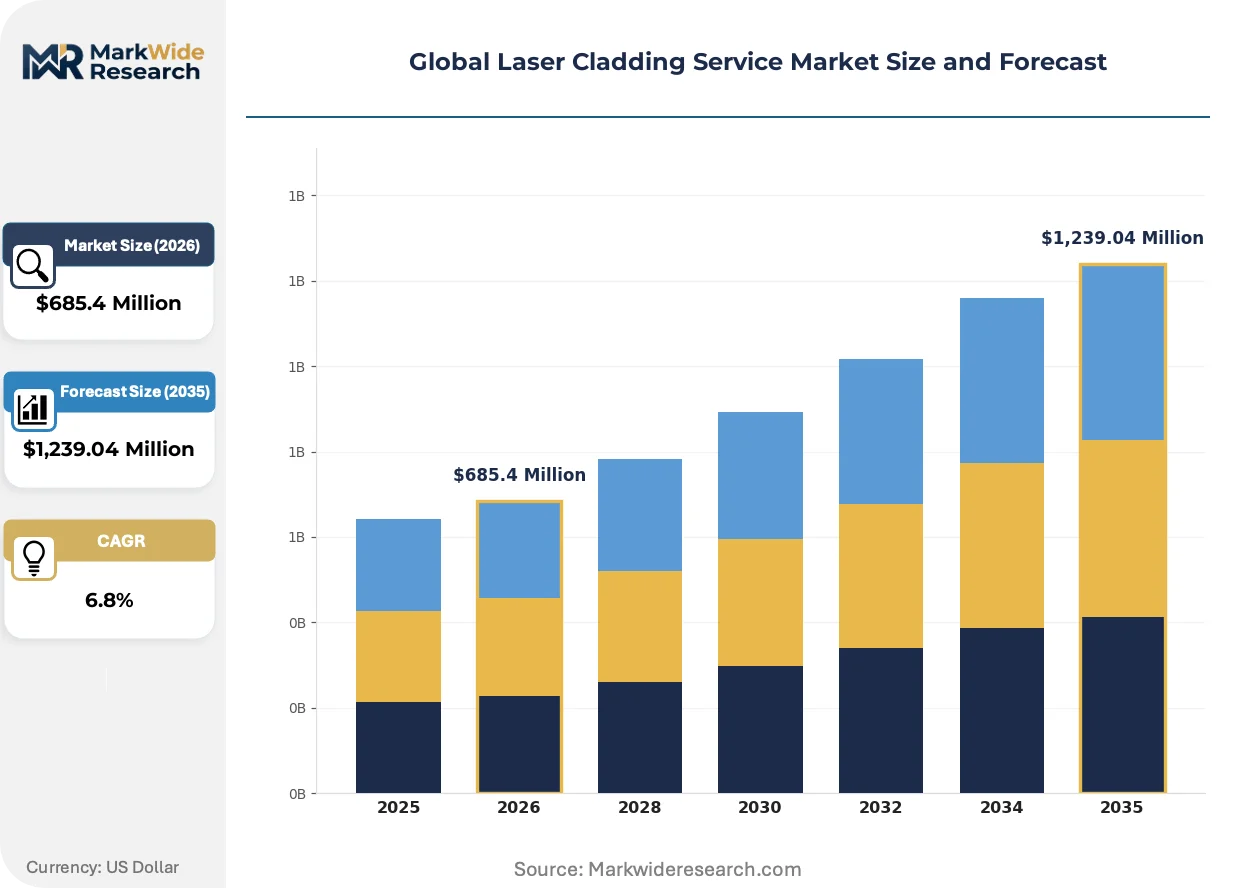
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Repair Coating, Surface Enhancement, Corrosion Resistance, Wear Resistance, Thermal Barrier, Customized Solutions Application: Aerospace Components, Power Generation Equipment, Oil & Gas Tools, Industrial Machinery, Marine Vessels, Hydraulic Systems Product Type: Metal Alloy Coatings, Ceramic Coatings, Composite Coatings, Carbide Coatings, Stainless Steel Cladding, Titanium Cladding End User Industry: Energy Sector, Aerospace Manufacturers, Oilfield Services, Heavy Manufacturing, Shipbuilding, Industrial Equipment Providers |
| Companies Covered | IPG Photonics Corporation, Höganäs AB, TRUMPF, Laser Cladding Technology Ltd, Jenoptik, OC Oerlikon Management AG, TWI Ltd, Topclad B.V., Coherent Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laser Cladding Service Market Shifts & Advancements
Ultrafast laser sources and in-situ monitoring systems are compressing the precision gap between cladding and competing additive methods, while regulatory disclosure requirements reshape how service providers document process parameters.
Ultrashort pulse lasers are collapsing the heat-affected zone in cladding operations to sub-50 micron depths, enabling repair of thin-walled turbine shrouds previously deemed uncladdable. Rolls-Royce and Siemens Energy are qualifying these processes for hot-section components at accelerated schedules. The structural consequence is collapsing the minimum wall thickness threshold that separates cladding from full replacement economics.
REACH registration requirements now mandate full chemical composition disclosure for nickel-based superalloy powders, forcing European suppliers to requalify batches previously sold on elemental ranges. ECHA enforcement has eliminated several Chinese powder sources from aerospace supply chains. German service providers respond by integrating in-house gas atomization or captive supply agreements with Höganäs and Praxair.
Performance-based maintenance contracts now tie cladding service payments to component operational hours rather than deposited weight. Oilfield tool lessors in the Permian Basin and North Sea drive this shift, transferring wear-risk from operators to cladding shops. The model compresses quoting cycles and demands real-time wear-rate prediction capabilities that few mid-size job shops possess.
Global Laser Cladding Service Market Segmentation
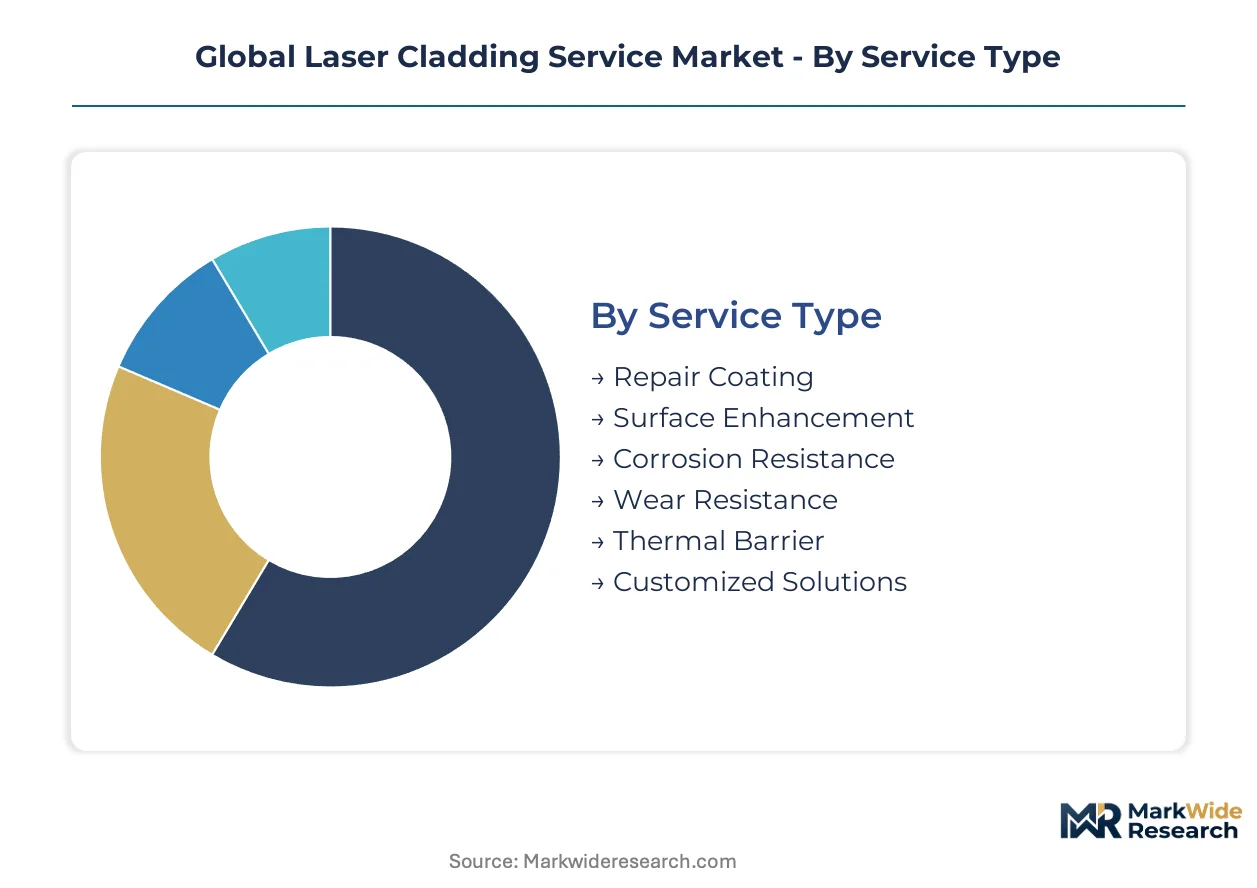
Laser cladding service procurement splits across technical specifications, operational environments, and regulatory compliance tiers. Understanding these fault lines clarifies why aerospace contracts command premiums while general industrial maintenance tolerates price compression.
Service Type:
Cost tier stratification separates commodity refurbishment from certified repair processes governed by AS9100 and ISO 9001 protocols.
- Repair Coating:Dimensional restoration of worn substrates using nickel superalloy or cobalt-chrome deposits. Demand concentrates in German aerospace clusters where single-crystal turbine blade supply chains stretch 18-24 months, forcing operators toward refurbishment.
- Wear Resistance:Hardfacing applications for oilfield tools and mining equipment subjected to abrasive conditions. Permian Basin and North Sea operators now structure performance-based contracts tying payments to operational hours rather than deposited weight.
- Surface Enhancement:Property modification without dimensional change for precision tooling.
- Corrosion Resistance:Protective layers for chemical processing and marine exposure environments.
- Thermal Barrier:Ceramic-metallic gradient coatings for gas turbine hot-section components.
- Customized Solutions:Application-specific process development for novel geometries or material combinations.
Repair Coating holds installed capacity. Wear Resistance is rotating up the share rankings.
Application:
Application focus tracks capital intensity of underlying equipment and downtime cost exposure across end-use sectors.
- Aerospace Components:Turbine airfoil, combustor, and compressor blade restoration requiring bond strengths exceeding 400 MPa with minimal dilution. Rolls-Royce and Siemens Energy are qualifying ultrashort pulse processes for hot-section components at accelerated schedules.
- Power Generation Equipment:Gas turbine buckets, steam turbine shafts, and valve components subjected to creep and thermal fatigue. EU F-Gas Regulation mandates push operators toward refurbishment rather than new manufacturing.
- Oil & Gas Tools:Drill collars, stabilizers, and mud motor components for directional drilling.
- Industrial Machinery:General repair of gears, shafts, and bearing surfaces in manufacturing equipment.
- Marine Vessels:Propeller shaft sealing surfaces and pump impellers for corrosion protection.
- Hydraulic Systems:Cylinder rod reclamation and valve body restoration for fluid power equipment.
Aerospace Components commands certification premiums. Power Generation Equipment is climbing the fastest on regulatory tailwinds.
Product Type:
Material chemistry determines deposition parameters, dilution control, and final property profiles achievable through laser cladding.
- Metal Alloy Coatings:Nickel, cobalt, and iron-based systems offering versatile property tuning for diverse substrate compatibility. German metallurgy clusters now capture and reclassify spent Inconel and cobalt-chrome powders, cutting material costs for job shops.
- Ceramic Coatings:Yttria-stabilized zirconia and alumina systems for thermal barrier performance beyond conventional superalloy limits. Gas turbine operators in Germany and the US are driving qualification programs for ceramic-metallic gradients.
- Composite Coatings:Metal-ceramic layered or gradient structures combining toughness and thermal protection.
- Carbide Coatings:Tungsten and chromium carbide dispersions for extreme abrasion resistance.
- Stainless Steel Cladding:Corrosion-resistant overlays for chemical processing and marine applications.
- Titanium Cladding:Biocompatible and high strength-to-weight deposits for medical and aerospace specialty applications.
Metal Alloy Coatings dominates current throughput. Ceramic Coatings is gaining share fastest on thermal management demands.
End User Industry:
Customer type segmentation reveals divergent procurement sophistication, with aerospace OEMs imposing qualification burdens that freeze mid-size job shops from approved supplier lists.
- Energy Sector:Gas turbine operators, nuclear utilities, and renewable energy asset owners requiring life extension for high-value rotating equipment. US Inflation Reduction Act domestic content bonuses incentivize onshore cladding capacity for wind turbine bearing seats.
- Aerospace Manufacturers:OEMs and tier-one suppliers with AS9100D audit timelines stretching 14-18 months for additive repair process approval. TRUMPF-equipped German job shops anchor this segment through dense equipment networks and metallurgy research institute partnerships.
- Oilfield Services:Tool lessors and operators transferring wear-risk to cladding shops through outcome-based maintenance contracts.
- Heavy Manufacturing:Steel, cement, and mining equipment producers with lower qualification barriers.
- Shipbuilding:Classification society-certified repair for propulsion and cargo handling systems.
- Industrial Equipment Providers:OEM aftermarket service networks and independent repair specialists.
Energy Sector holds committed capacity. Aerospace Manufacturers is rotating up the share rankings on blade restoration volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes laser cladding services differently from other geographies, prioritizing precision-engineered aerospace repair over commodity hardfacing, while the United States emphasizes energy infrastructure refurbishment and India builds nuclear component capabilities.
United States
Gas turbine operators in Texas and Louisiana drive demand for thermal barrier refurbishment as EPA emissions standards tighten replacement economics. The Inflation Reduction Act domestic content bonuses accelerate onshore cladding capacity for wind turbine bearing seats. Houston-area job shops cluster around energy sector maintenance corridors, capturing Permian Basin tool repair contracts.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg prioritize single-crystal turbine blade restoration where casting supply chains stretch 18-24 months. EU F-Gas Regulation mandates push power generation operators toward refurbishment over new component manufacturing. The Aachen-Dortmund metallurgy corridor operates powder recycling infrastructure that cuts material costs for automotive tool repair networks.
China
State-owned power utilities in the Yangtze River Delta contract cladding services for steam turbine shafts and valve components under MIIT efficiency mandates. GB standards for additive manufacturing processes increasingly govern repair procedure qualification. Shanghai and Shenyang host equipment-integrated service providers serving heavy machinery and aerospace subcontractor tiers.
India
BIS certification pathways for indigenous pressurized heavy water reactor maintenance open captive demand for cobalt-free cladding alloys. The country's national atomic energy regulator frames material specifications for nuclear component repair. Gujarat and Maharashtra job shops develop capability for heavy forging die refurbishment serving domestic capital goods manufacturers.
Japan
Precision equipment manufacturers in the Nagoya-Chubu corridor contract surface enhancement for tooling subjected to high-cycle wear conditions. METI industrial technology roadmaps guide laser-based repair process adoption in automotive supply chains. Osaka-area service providers specialize in thin-walled component restoration for semiconductor manufacturing equipment.
Global Laser Cladding Service Market Competitive Landscape
Capability concentration sits with equipment-integrated German specialists; scale advantage sits with North American powder and laser source suppliers. The market structures around three tiers: fiber laser equipment networks, captive powder supply agreements, and independent job shops seeking AS9100 certification. Consolidation pressures concentrate among aerospace-qualified facilities where audit timelines stretch 14-18 months. Dominant competitive moves include captive powder supply agreements and hybrid machine tool integration.
Within the equipment-integrated tier, TRUMPF and IPG Photonics Corporation anchor regional competitive positioning through fiber laser dominance and dense job shop networks. Höganäs AB occupies a position controlling material consistency for European aerospace repair supply chains. These three exemplify how laser source availability and powder chemistry governance determine contract access in regulated end-use segments.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Höganäs AB |
| TRUMPF |
| Laser Cladding Technology Ltd |
| Jenoptik |
| OC Oerlikon Management AG |
| TWI Ltd |
| Topclad B.V. |
| Coherent Corp |
| Others |
Supply & Pricing Matrix
Undercapacity in German aerospace-qualified job shops tightens pricing power for AS9100-certified repair coating services while pushing uncertified facilities toward commodity wear resistance contracts with thinner margins. This utilization split concentrates premium pricing among equipment-integrated specialists and compresses returns for independent operators lacking metallurgy research institute partnerships.
Pricing Analysis
Long-term offtake agreements dominate aerospace blade restoration contracts, locking in volume commitments against spot-market volatility in shielding gas and superalloy powder inputs. Price differentiation hinges on AS9100D certification tier and captive powder supply agreements with Höganäs or Praxair. Cost compression in general industrial hardfacing intensifies as plasma spray substitutes retain cost advantage for non-critical surfaces. Oilfield tool lessors exhibit lowest price sensitivity due to performance-based contract structures, while automotive tool repair networks face acute margin pressure from powder recycling infrastructure competition.
Supply Chain Analysis
Export-control regimes on high-power fiber laser technology limit equipment flows from German and North American networks to Chinese and Indian service providers, constraining capacity expansion in emerging markets. Supply concentrates in Germany, the United States, and Japan for laser delivery fibers, beam shaping optics, and ultrafast laser sources. Raw material dependencies include helium and argon shielding gases, nickel-based superalloy powders, and high-purity fused silica. Single-source vulnerability concentrates in Japanese and German optics suppliers for North American cladding facilities. Distribution runs through equipment-integrated job shop networks and OEM-approved supplier lists with 14-18 month qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser cladding service providers face sustained substitution pressure from thermal spray coatings and directed energy deposition systems that collapse process steps for large forging die repair. Incumbents must defend repair coating margins through certification barriers while managing powder cost volatility.
For Market Incumbents: Pre-empt plasma spray substitution by accelerating ultrashort pulse laser qualification for thin-walled turbine shrouds previously deemed uncladdable. Lock in captive powder supply agreements with gas atomization partners to offset REACH-driven Chinese supplier elimination. Prioritize hybrid machine tool integration to capture near-net-shape repair contracts collapsing separate milling and cladding steps.
For New Entrants and Emerging Players: Indian nuclear component repair represents the most penetrable entry point, with BIS certification pathways for cobalt-free cladding alloys creating captive demand outside established aerospace supply chains. Target US wind turbine bearing seat refurbishment incentivized by Inflation Reduction Act domestic content bonuses. Pursue directed energy deposition convergence as a go-to-market angle, offering hybrid process capabilities that incumbent job shops lack.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aerospace-qualified facilities due to AS9100D audit timelines and in-house gas atomization investments. Acquisition targets should combine TRUMPF or IPG equipment networks with established metallurgy research institute partnerships. Watch for shielding gas price volatility as an inflection indicator forcing consolidation among margin-stressed independent job shops.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Unlocks OEM-approved supplier status for Rolls-Royce and Siemens Energy blade restoration contracts. |
| Captive Powder Supply Agreement | Secures Höganäs or Praxair batch consistency against REACH-driven Chinese supplier disqualification. |
| Hybrid Machine Tool Integration | Enables near-net-shape repair of large forging dies, collapsing separate milling and cladding process steps. |
| In-house Gas Atomization | Eliminates powder cost volatility and ECHA compliance exposure for European aerospace repair networks. |
| Performance-Based Contract Structuring | Transfers wear-risk from Permian Basin oilfield operators to cladding shops with real-time prediction capabilities. |
Research Methodology
A standing panel of maintenance directors at gas turbine operators, powder metallurgy procurement leads, laser equipment service heads, and aerospace aftermarket managers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from ECHA REACH registration databases, EPA emissions compliance filings, SEC equipment manufacturer disclosures, and EU F-Gas Regulation implementation reports. Bottom-up job shop capacity estimates triangulated against top-down OEM repair spend analysis.
Scenario-bracketing framed demand projections across the analysis window, modeling service type segmentation by repair coating, wear resistance, and thermal barrier applications alongside end-user industry splits in energy, aerospace, and oilfield services. CAGRs derived from equipment installation rates, powder consumption trends, and certified facility capacity expansion. Forecast inputs incorporated shielding gas price trajectory assumptions and AS9100D audit completion rates.
Practitioners should monitor regulatory enforcement intensity at ECHA, EPA, and BIS for early signals of powder supply chain disruption or certification pathway modification. Forecasts reflect assumptions about helium and argon supply stability, ultrafast laser source commercialization timelines, and plasma spray substitution elasticity in general industrial maintenance. Material shifts in EU AI Act documentation burdens for automated cladding path planning would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Clear Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Waterproof Coating Market
Coatings
Superhydrophobic Coatings Market
Coatings
Silicone Coating Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
OEM Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Global Floor Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Trim Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Waterborne Wood Coatings Market