
 Italy Automotive OEM Coatings Market | 2026-2036
Italy Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive OEM Coatings Market Foresight
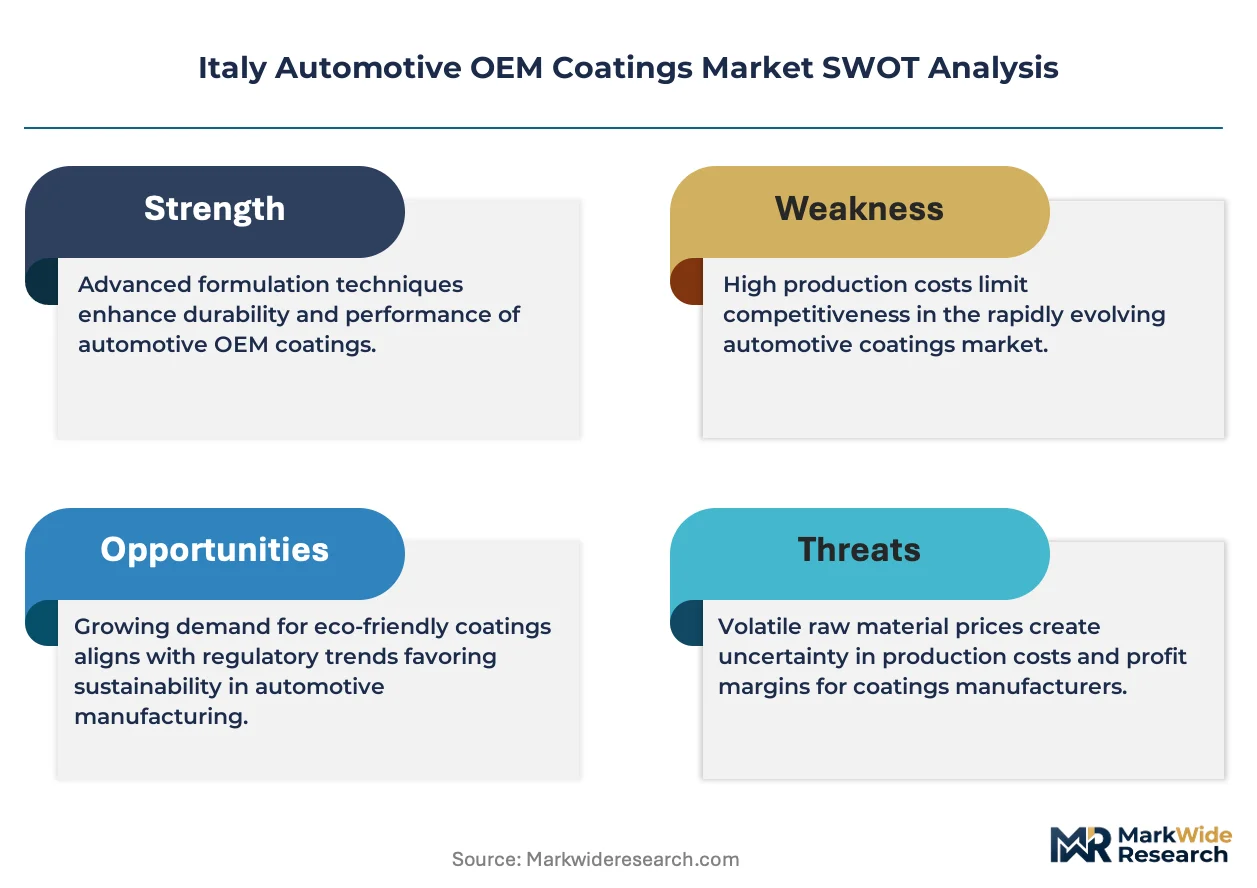
ISO 14001 environmental management certification is rotating supplier eligibility for Italian OEM coating contracts, effectively filtering the competitive field. PPG Industries Inc. leverages its electrodeposition coating expertise to anchor relationships with Fiat and Stellantis assembly plants in Piedmont. AkzoNobel N.V. sustains a strong position through its specialized base coat formulations for premium Italian marques. Axalta Coatings Systems differentiates via powder coating technology leadership for commercial vehicle applications in Lombardy.
Automotive OEM coatings comprise multi-layer systems of primers, base coats, and clear coats applied through electrodeposition, spray, or powder processes to vehicle body panels, with film thickness typically ranging from 15 to 150 microns depending on layer function and substrate protection requirements. These coatings provide corrosion resistance, UV durability, and aesthetic finish for vehicle exteriors while meeting OEM specifications for chip resistance and color matching. Clear coat and base coat formulations command the deepest margin pools due to their complexity and brand-critical visual properties, while electrodeposition coating maintains volume dominance as the foundational corrosion barrier applied to every unibody structure. Electric vehicle applications represent the fastest-growing segment as Italian OEMs redesign thermal management and battery enclosure coating protocols.
Italy's Ministry of Enterprise and Made in Italy (MIMIT) enforces REACH-aligned chemical restrictions through national implementing decrees, while EU F-Gas Regulation limits solvent-based coating emissions in automotive finishing operations. The Italian National Institute for Insurance against Accidents at Work (INAIL) mandates workplace exposure controls that push facilities toward automated spray systems and enclosed coating lines. Stakeholders must monitor how pending EU industrial emissions directive revisions will reshape capital allocation between liquid and powder coating infrastructure across Italian OEM supply chains.
Market Dynamics
Waterborne coating technology adoption is compressing solvent-based system margins across Italian OEM supply chains, as Turin and Milan electric vehicle manufacturers renegotiate long-term procurement contracts to prioritize low-VOC formulations.
Growth Catalysts
- PNRR Sustainable Industrial Incentives:Italy's National Recovery and Resilience Plan redirects capital toward waterborne electrodeposition systems, accelerating facility retrofits across Piedmont and Lombardy assembly plants.
- ISO 14001 Certification Rotation:Environmental management certification requirements are filtering supplier eligibility for Fiat and Stellantis coating contracts, elevating certified coating houses in Modena and Bologna.
- Battery Enclosure Thermal Management:Electric vehicle battery pack redesigns are creating specialized coating protocols for thermal conductivity and fire resistance, opening specification windows for advanced ceramic-filled formulations.
Market Restraints
- Raw Material Concentration Risk:Titanium dioxide and epoxy resin supply chains concentrate in Asian chemical manufacturing clusters, exposing Italian formulators to input cost volatility and freight disruption.
- REACH-Aligned Chemical Restrictions:Italy's MIMIT enforcement of EU chemical limitations is eliminating legacy solvent-based primer chemistries before waterborne alternatives achieve equivalent corrosion performance on aluminum-intensive vehicle architectures.
- Capital Intensity of Enclosed Coating Lines:INAIL-mandated workplace exposure controls require automated spray booth investments that smaller regional coating facilities cannot finance without consortium structures.
Strategic Opportunities
- Southern Italy Industrial Corridor:Underpenetrated automotive assembly in Campania and Apulia offers first-mover positioning for powder coating specialists targeting commercial vehicle expansion.
- EU F-Gas Regulation Compliance Services:Technical consulting and retrofit engineering for solvent recovery systems represent recurring revenue streams as smaller Tier-2 suppliers face 2027 compliance deadlines.
- Digital Color Matching Convergence:Integration of spectrophotometry with AI-driven formulation databases is reducing batch-to-batch variation, enabling just-in-time coating delivery to lean-manufacturing assembly lines.
Industry Challenges
- Electrocoat Chemistry Specialization Gap:Formulation chemists with cathodic electrodeposition expertise remain concentrated at multinational headquarters, constraining Italian coating houses from developing proprietary anolyte systems.
- Legacy Paint Shop Integration Complexity:Waterborne base coat conversion requires humidity-controlled spray environments incompatible with 1990s-era Fiat and Stellantis facility infrastructure, forcing phased capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive OEM Coatings Market |
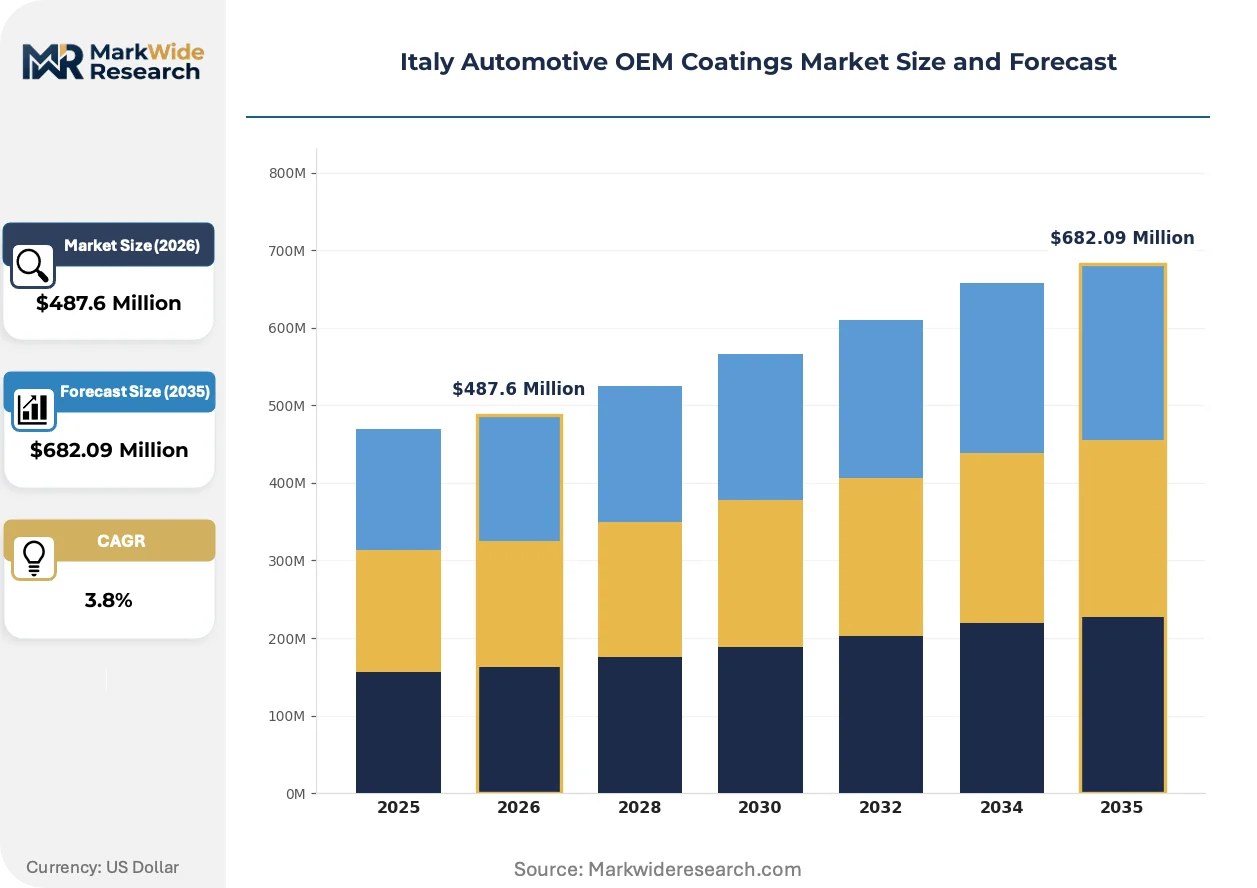
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $682.09 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Clear Coat, Primer, Electrodeposition Coating Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Spray Coating, Powder Coating, Liquid Coating, UV Coating |
| Companies Covered | BASF SE, Nippon Paint Holdings Co., Ltd., RPM International Inc., Beckers Group, The Sherwin-Williams Company, AkzoNobel N.V., PPG Industries Inc., Mankiewicz, Axalta Coatings Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive OEM Coatings Market Shifts & Advancements
Coating specification authority is migrating from OEM engineering departments to sustainability compliance officers, compressing traditional technical performance hierarchies in favor of carbon-footprint metrics and circular material certifications.
Self-healing clear coat technology utilizing microencapsulated polymer repair agents is fragmenting the premium vehicle finishing segment. Maserati and Ferrari specification teams are piloting these formulations for stone-chip recovery on exposed carbon fiber body panels. The technology is fragmenting established supplier relationships as specialty chemical firms bypass incumbent coating houses to secure direct OEM validation contracts.
EU F-Gas Regulation phase-down schedules are forcing solvent-based coating emissions reductions across Italian automotive finishing operations. MIMIT enforcement through national implementing decrees is accelerating capital allocation toward enclosed spray systems and carbon adsorption recovery units. Northern Italian OEM assembly plants in Turin and Milan are responding with compressed retrofit timelines that favor turnkey equipment suppliers over component vendors.
Buyer consolidation among Stellantis group brands is compressing coating specification diversity across Alfa Romeo, Fiat, and Maserati production lines. Tier-1 suppliers are consolidating formulation approvals into unified global platforms, displacing regionally optimized Italian coating chemistries. This concentration is most visible in the Mirafiori and Cassino assembly complexes, where single-source base coat supply agreements now span multiple marques previously served by distinct formulators.
Italy Automotive OEM Coatings Market Segmentation
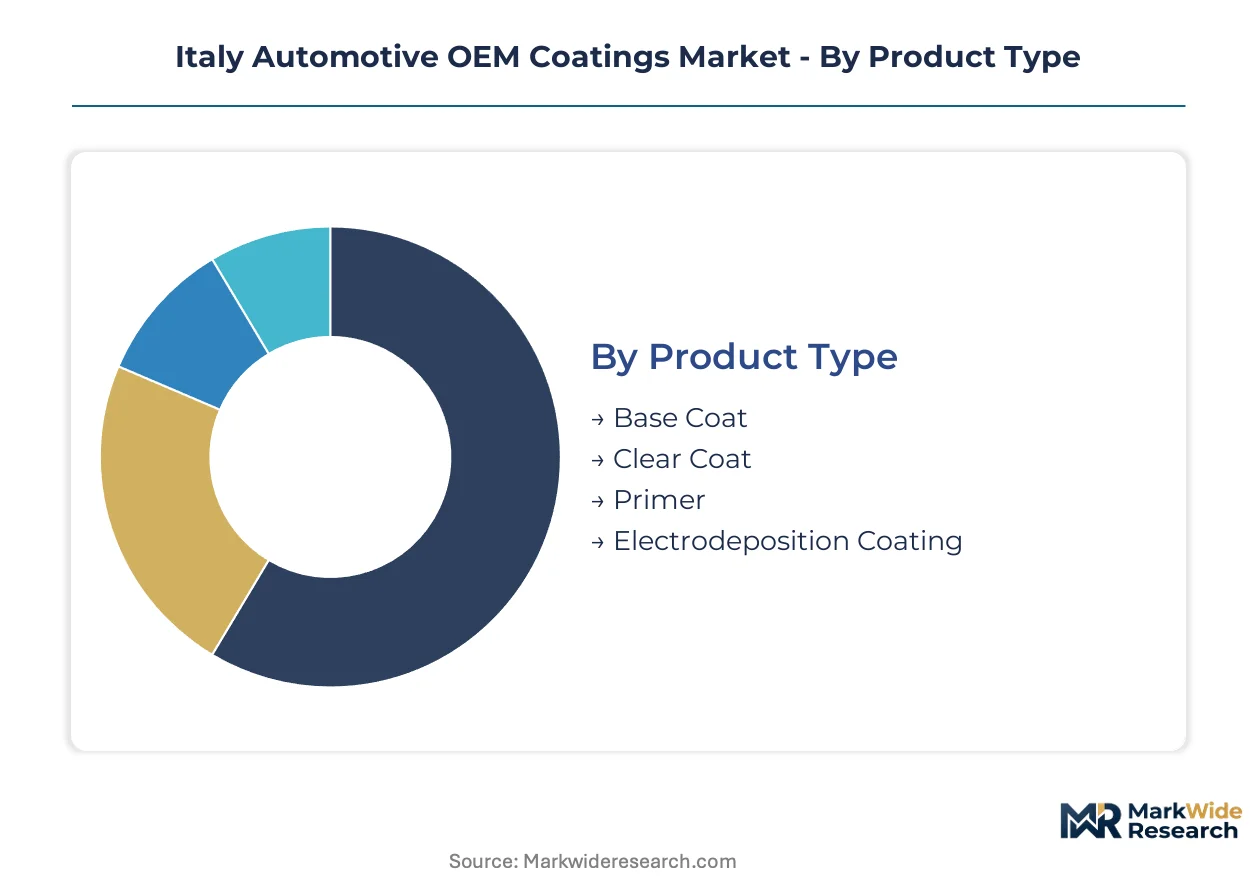
Coating specification authority in Italy is fragmenting across multiple technical and commercial dimensions. Understanding how demand concentrates within each segment reveals where formulation investments generate the highest returns.
Product Type:
Waterborne formulations are displacing solvent-based chemistries across every product layer, though substitution pressure varies sharply by functional requirement and corrosion performance thresholds.
- Base Coat:Pigmented formulations delivering color, opacity, and visual depth through controlled resin-pigment dispersion. Turin and Milan electric vehicle manufacturers are renegotiating procurement contracts to prioritize low-VOC base coat systems that meet MIMIT enforcement timelines.
- Clear Coat:Unpigmented top layers providing gloss retention, UV protection, and scratch resistance through cross-linked polymer networks. Maserati and Ferrari specification teams are piloting self-healing microencapsulated formulations for stone-chip recovery on carbon fiber panels.
- Primer:Intermediate adhesion promoters filling substrate imperfections and enhancing topcoat bonding.
- Electrodeposition Coating:Cathodic epoxy systems applied to every unibody structure as the foundational corrosion barrier.
Electrodeposition Coating anchors the volume base while Clear Coat gains share at the steepest rate.
Application:
Vehicle electrification is redrawing coating performance specifications across all application categories, with thermal management requirements creating new formulation windows.
- Passenger Vehicles:High-volume production lines serving Fiat and Stellantis brands in Piedmont and Lombardy. Buyer consolidation across Alfa Romeo, Fiat, and Maserati marques is compressing specification diversity into unified global platforms.
- Electric Vehicles:Battery enclosure and thermal management systems requiring specialized ceramic-filled formulations for fire resistance and conductivity. Turin and Milan manufacturers are expanding orders for low-VOC coating systems under PNRR incentive alignment.
- Commercial Vehicles:Heavy-duty finishing protocols emphasizing chip resistance and extended weathering durability.
- Luxury Vehicles:Low-volume, high-customization production with premium visual specifications and extended color-matching tolerances.
Passenger Vehicles carry the largest absolute volume while Electric Vehicles expand most quickly.
End User:
Procurement centralization is elevating Tier-1 suppliers and consolidating aftermarket influence, reshaping how coating houses structure sales relationships.
- OEMs:Fiat and Stellantis assembly plants in Piedmont specifying multi-layer systems through centralized engineering departments. ISO 14001 certification rotation is filtering supplier eligibility for direct coating contracts.
- Tier-1 Suppliers:Component integrators managing coating application for body panels, bumpers, and structural assemblies. These intermediaries are consolidating formulation approvals into single-source agreements spanning multiple marques.
- Aftermarket Providers:Refinish and repair operations serving collision centers and dealer networks.
- Vehicle Assemblers:Contract manufacturing facilities without full OEM status requiring flexible coating procurement.
OEMs dominate specification authority while Tier-1 Suppliers capture the fastest-growing procurement volume.
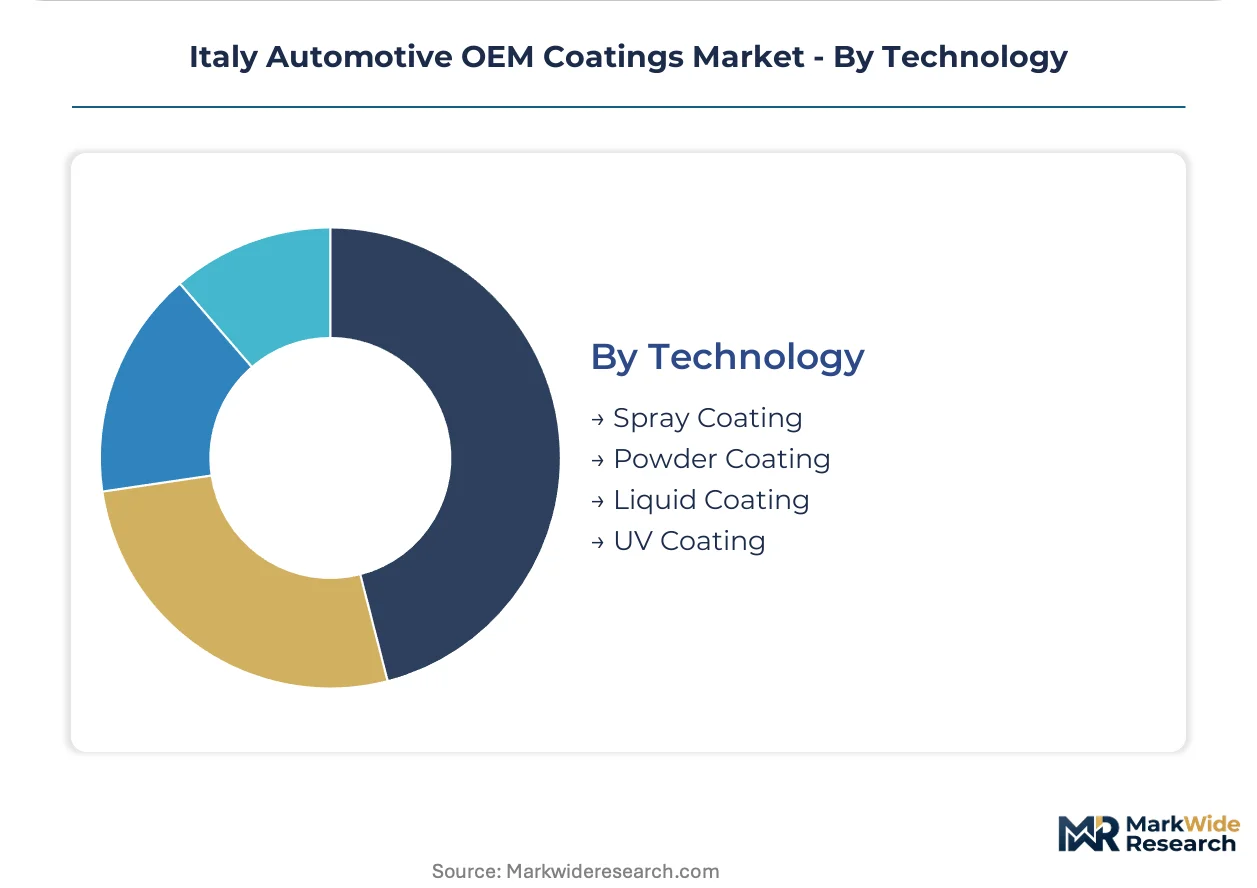
Technology:
Capital allocation between coating technologies is diverging sharply as INAIL-mandated workplace exposure controls and EU F-Gas Regulation reshape facility investment decisions.
- Spray Coating:Atomized liquid application through robotic or manual systems enabling complex geometries and color effects. Automated spray booth investments are accelerating across northern Italian facilities to meet enclosed line mandates.
- Powder Coating:Electrostatically applied thermoset powders cured through thermal fusion. Axalta maintains technology leadership for commercial vehicle applications in Lombardy, with southern Italy corridors offering expansion positioning.
- Liquid Coating:Conventional solvent-borne and waterborne systems requiring humidity-controlled environments.
- UV Coating:Rapid-cure formulations polymerized through ultraviolet exposure, reducing energy consumption and footprint.
Spray Coating retains the largest installed base while Powder Coating climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's National Recovery and Resilience Plan redirects capital toward sustainable coating infrastructure, concentrating procurement power in northern industrial corridors while southern regions present expansion frontiers for specialized technologies.
Piedmont
Turin anchors Italy's automotive coating demand through Fiat and Stellantis assembly complexes. MIMIT enforcement of REACH-aligned chemical restrictions is accelerating waterborne system adoption across Mirafiori facility retrofits. Electrodeposition coating volume concentrates in this northwestern cluster as OEMs consolidate specification authority.
Lombardy
Milan electric vehicle manufacturers are expanding orders for low-VOC coating systems under PNRR incentive alignment. INAIL-mandated workplace exposure controls push facilities toward automated spray booth investments. Commercial vehicle applications in this northern region favor powder coating technology leadership.
Emilia-Romagna
Bologna and Modena host ISO 14001-certified coating houses elevated by certification rotation for premium marque contracts. EU F-Gas Regulation phase-down schedules compress solvent-based system margins. The region's precision manufacturing heritage supports specialized base coat formulation capabilities.
Campania
Underpenetrated automotive assembly in this southern corridor offers first-mover positioning for powder coating specialists. PNRR sustainable industrial incentives extend to facility greenfield investments below Rome. Commercial vehicle expansion targets in Naples metro area remain nascent relative to northern saturation.
Veneto
Industrial coating demand diversifies across component manufacturing rather than final assembly in this northeastern region. REACH-aligned restrictions filter supplier eligibility for Tier-1 contracts serving Stellantis supply chains. Padua and Verona clusters specialize in humidity-controlled spray environment engineering.
Italy Automotive OEM Coatings Market Competitive Landscape
Player mix skews toward multinational chemical conglomerates with integrated electrodeposition expertise, creating a consolidated top tier above fragmented regional formulators. Three strategic archetypes dominate: integrated resin-to-coating multinationals, specialized automotive finish specialists, and regional coating houses leveraging ISO certification proximity. Competitive intensity centers on M&A-driven technology acquisition and PNRR-aligned capacity retrofit partnerships.
Among Netherlands-based chemical conglomerates, AkzoNobel N.V. exemplifies the integrated multinational archetype through specialized base coat positioning. PPG Industries Inc. represents the electrodeposition-focused tier with established OEM anchoring relationships. Axalta Coatings Systems occupies the technology-differentiated specialist position. German-origin BASF SE and Japan-registered Nippon Paint Holdings Co., Ltd. round out the multinational tier with broad coating portfolio coverage.
| Leading Market Players |
|---|
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Beckers Group |
| The Sherwin-Williams Company |
| AkzoNobel N.V. |
| PPG Industries Inc. |
| Mankiewicz |
| Axalta Coatings Systems |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Stellantis assembly plants and electrodeposition coating suppliers lock in multi-year supply access while capping price volatility exposure for both parties across the Turin-Milan corridor.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with ISO 14001-certified formulators commanding premium positioning against uncertified regional competitors. Three-tier pricing structure separates premium waterborne systems from standard solvent-borne formulations and economy-grade powder coatings. Pricing pressure stems from raw material cost volatility in titanium dioxide and epoxy resin feedstocks. Tier-1 suppliers exhibit lowest price sensitivity due to consolidated procurement power, while smaller regional coating houses face acute margin compression.
Supply Chain Analysis
Asian chemical manufacturing clusters anchor titanium dioxide and specialty resin supply, creating transit-dependent vulnerability for Italian formulators. Raw material procurement draws from China, South Korea, and Japan for cathodic electrodeposition chemistries. Single-source vulnerability concentrates in epoxy resin intermediates where European domestic capacity has contracted. Distribution runs through Rotterdam-Antwerp chemical hubs before rail transfer to Piedmont and Lombardy coating facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH-aligned MIMIT enforcement and ISO 14001 certification rotation constructs formidable defensive moats for established suppliers, as switching costs escalate for OEMs validating alternative coating houses.
For Market Incumbents: Consolidate formulation approvals across Stellantis marques into unified supply agreements spanning Mirafiori and Cassino complexes. Deepen backward integration into waterborne resin production to offset Asian feedstock volatility. Prioritize cathodic electrodeposition R&D investment to maintain technical differentiation against emerging ceramic-filled competitors.
For New Entrants and Emerging Players: Differentiate on battery enclosure thermal management coatings for Turin and Milan electric vehicle manufacturers. Target underpenetrated Campania and Apulia commercial vehicle corridors where powder coating specifications remain open. Pursue direct OEM validation contracts for self-healing clear coat technology, bypassing incumbent coating house intermediation.
For Investors and Strategic Acquirers: Capital is best deployed toward ISO 14001-certified regional coating houses with established Stellantis relationships and retrofit-ready infrastructure. Long-term viability hinges on PNRR incentive alignment and waterborne technology transition completion. Monitor EU F-Gas Regulation phase-down enforcement velocity as the critical inflection signal for solvent-based asset strandedness.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne System Retrofit | PNRR capital allocation accelerates facility conversion across Piedmont assembly plants. |
| Backward Integration into Resin Production | Captive epoxy supply reduces exposure to Asian chemical manufacturing concentration. |
| Battery Enclosure Coating Development | Ceramic-filled formulations address thermal conductivity requirements for Milan EV manufacturers. |
| ISO 14001 Certification Investment | Environmental management credentials filter supplier eligibility for Fiat direct contracts. |
| Southern Italy Geographic Expansion | Campania commercial vehicle growth offers first-mover positioning for powder coating specialists. |
Research Methodology
Cross-validation between primary interviews with OEM procurement officers, Tier-1 supplier technical directors, and coating house plant managers anchors the qualitative findings against secondary validation. Regulatory filings from Italy's MIMIT and EU ECHA chemical restriction databases complement customs trade data and SEC disclosures from multinational coating suppliers. Bottom-up volume modeling triangulates against top-down market sizing across electrodeposition, base coat, and clear coat product tiers.
Sensitivity analysis around raw material cost assumptions and PNRR incentive disbursement timelines informs projection robustness. Segmentation dimensions span coating layer function, vehicle propulsion architecture, application technology, and regional production cluster. CAGRs derive from trend extrapolation moderated by regulatory enforcement schedules and OEM platform standardization timelines. Electric vehicle penetration rates and waterborne technology substitution curves constitute critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained PNRR funding commitment or accelerated EU F-Gas Regulation enforcement would require recalibration. Practitioners should keep alternative scenarios live as Stellantis procurement centralization and Asian supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vinyl Surface Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
France Automotive OEM Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Global Powder Coating Market
Coatings
Global Flat Glass Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
ASEAN Protective Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Conductive Polymer Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market