

Abrasive Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasive Grains Market Insights
ISO 9001:2015 quality management certification is reorganizing supplier eligibility across the abrasive grains value chain, particularly for aerospace and precision engineering contracts. Saint-Gobain Abrasives leverages integrated fused alumina mining and refining operations across multiple continents. 3M sustains technology leadership in precision-shaped ceramic grain architectures. Carborundum Universal Limited anchors South Asian supply through captive bauxite processing and downstream bonded abrasive manufacturing.
Abrasive grains are hard, crystalline particles engineered for cutting, grinding, polishing, or surface conditioning through mechanical friction, typically manufactured via electric arc fusion, chemical precipitation, or high-temperature sintering to achieve controlled hardness, friability, and particle size distribution. The product type dimension shows aluminum oxide maintaining volume dominance in general metalworking while ceramic alumina captures margin expansion in high-performance aerospace applications. The application dimension reveals electronics manufacture and aerospace component finishing as the fastest-growing demand poles, driven by sub-micron surface finish requirements and automated process control.
EPA particulate matter standards under the Clean Air Act and REACH chemical registration requirements in Europe constrain traditional brown fused alumina production economics, redirecting investment toward closed-loop recycling and engineered grain geometries. OSHA silica exposure limits and MEE air quality directives in China further tighten operational parameters for raw fusion plants. Stakeholders must monitor how regulatory differentiation between conventional and engineered grain categories reshapes procurement qualification timelines and capital allocation priorities.
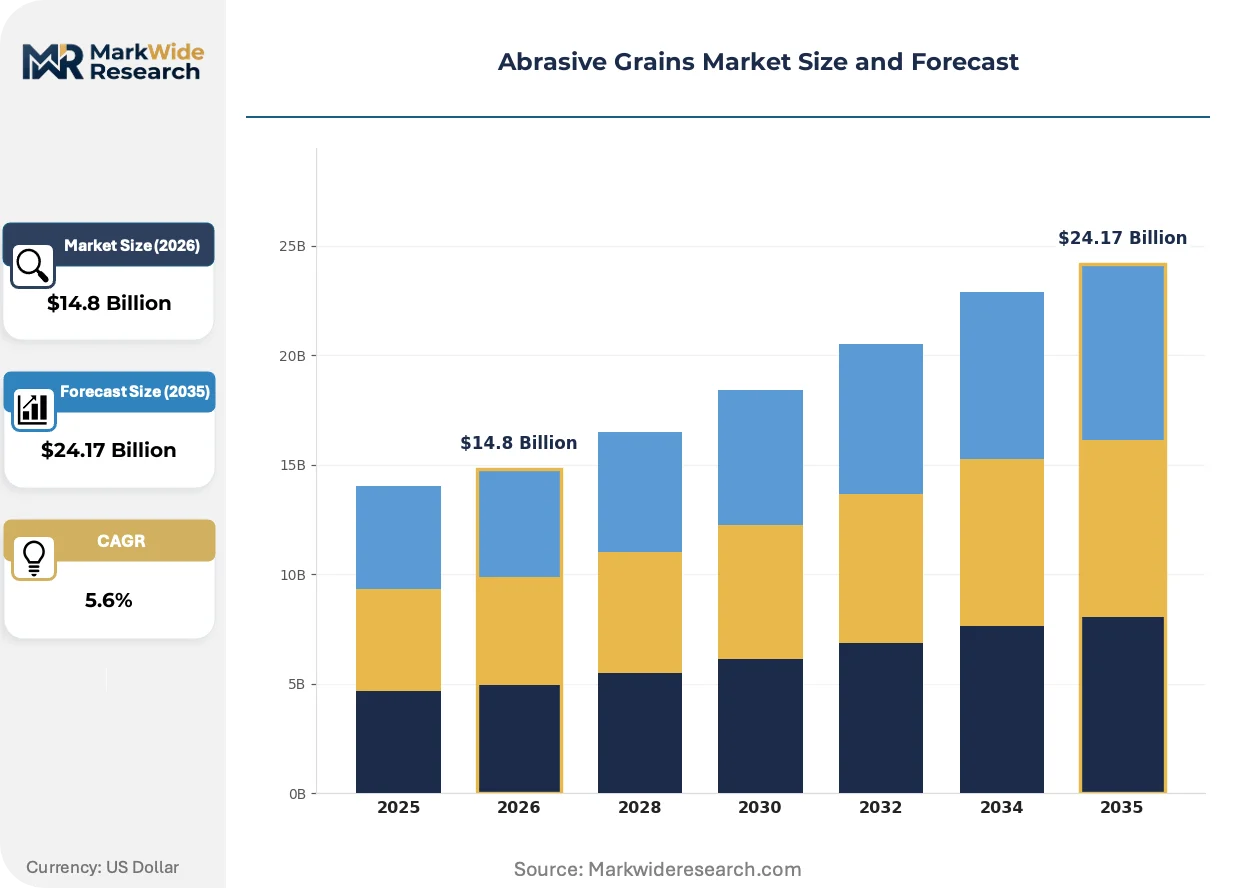
Market Dynamics
Engineered ceramic grain architectures are displacing conventional fused alumina in precision aerospace finishing, compressing supplier margins while elevating qualification barriers for Tier-2 and Tier-3 producers.
Growth Catalysts
- Sub-micron surface specifications:Aerospace OEMs now mandate Ra 0.1 μm finishes on turbine blade root surfaces, forcing supply chain upgrades to seeded-gel ceramic alumina.
- EPA Clean Air Act enforcement:Stricter particulate standards for brown fused alumina smelters in the United States are accelerating capital flows toward closed-loop grain recycling infrastructure.
- China-India-Germany capacity triad:New ceramic alumina fusion and sintering installations across these three markets are expanding global engineered grain availability.
Market Restraints
- Bauxite supply concentration:Guinean and Australian ore dominates feedstock for fused alumina, exposing processors to freight volatility and geopolitical disruption.
- REACH registration costs:European Chemicals Agency compliance for conventional abrasive formulations consumes 18-24 month qualification timelines and six-figure dossier preparation expenses.
- Silicon carbide substitution:Harder SiC grains capture share in glass and stone grinding where surface finish tolerance permits coarser cutting action.
Strategic Opportunities
- Indian electronics manufacturing:Semiconductor packaging and PCB depaneling operations present unmet demand for precision-shaped grains in cleanroom environments.
- EU Green Deal carbon border adjustments:CBAM implementation favors low-carbon grain production methods, rewarding European and renewable-powered Asian suppliers.
- Additive manufacturing post-processing:Metal 3D-printed component support removal and surface refinement opens a greenfield application segment for specialized grain geometries.
Industry Challenges
- ISO 9001:2015 certification backlog:Aerospace prime contractors now require certified grain suppliers, disqualifying smaller fusion plants lacking documented quality management systems.
- Fused alumina furnace rebuild cycles:Chinese and Indian operators face compressed maintenance windows as MEE air quality directives mandate emission control retrofits during planned outages.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasive Grains Market Trends and Innovations
Grain engineering and process automation are converging to redefine performance benchmarks across metalworking, electronics, and aerospace finishing segments.
Precision-shaped ceramic grain technology is bifurcating the abrasive market into commodity fused alumina and premium engineered tiers. Aerospace turbine manufacturers now specify seeded-gel microstructures for critical surface conditioning operations. This bifurcation is compressing margins for conventional brown and white fused alumina while expanding addressable premium volume.
REACH chemical registration requirements in Europe are elevating operational transparency mandates across the value chain. Suppliers must now document full substance composition and toxicological profiles for grain formulations. Brown fused alumina producers with legacy furnace configurations face the steepest compliance cost escalation.
Automated grinding cell integration is reshaping buyer technical specifications and supplier engagement models. Tier-1 automotive and aerospace contractors now procure grains through direct specification rather than distributor recommendation. This pattern is most pronounced in German and Japanese precision engineering clusters where machine tool OEMs control process parameter selection.
Abrasive Grains Market Segmentation
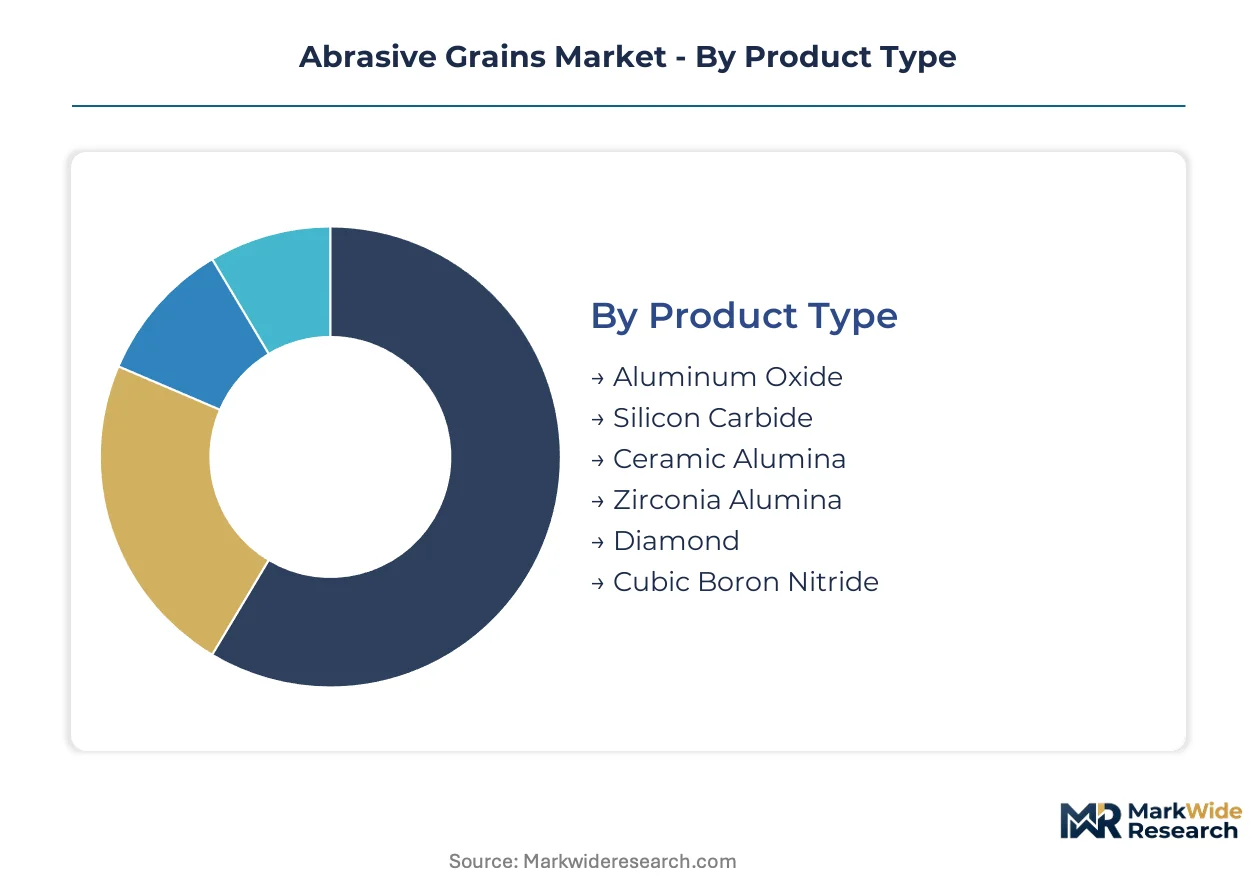
Abrasive grains fragment across four dimensions that determine qualification timelines and margin capture. Product chemistry dictates performance ceilings; form and application define regulatory exposure; end-user concentration shapes distribution economics.
Product Type:
REACH registration tiers in Europe and EPA particulate thresholds in the United States split this category into regulated commodity grains and exempt engineered variants.
- Aluminum Oxide:Fused crystalline alumina manufactured via electric arc reduction of bauxite ore. Brown fused variants dominate construction grinding in India and China; white fused grades serve precision metalworking in Germany and Japan. EPA Clean Air Act enforcement on smelter emissions is compressing margins for legacy producers.
- Ceramic Alumina:Seeded-gel microstructures engineered via sol-gel synthesis for controlled friability and self-sharpening. Aerospace turbine blade finishing in the United States and semiconductor wafer conditioning in South Korea concentrate demand. ISO 9001:2015 certification now gates supplier eligibility for Tier-1 aerospace contracts.
- Silicon Carbide:Harder than alumina; captures glass and stone grinding where surface tolerance permits aggressive cutting action.
- Zirconia Alumina:Alumina-zirconia eutectic structures for heavy stock removal in foundry and weld preparation.
- Diamond:Superabrasive for ultra-hard materials; concentrated in optical lens polishing and gemstone processing.
- Cubic Boron Nitride:Second-hardest known material; serves hardened steel grinding in automotive transmission manufacturing.
Aluminum Oxide handles the majority of throughput; Ceramic Alumina is the fastest mover on share.
Form:
Cost-to-performance stratification separates furnace-fused commodities from chemically engineered and bonded structures.
- Brown Fused:Titanium-doped alumina from bauxite-coke fusion in tilting arc furnaces. Construction grinding and shipyard metal preparation in China and India absorb volume. MEE air quality directives in China mandate emission control retrofits during rebuild cycles.
- White Fused:High-purity alumina from calcined Bayer process feedstock. Precision engineering in Stuttgart and Nagoya clusters specifies this grade for dimensional accuracy.
- Electrocorundum:Synthetic corundum variants with controlled chromium oxide doping for specific hardness profiles.
- Resinoid:Phenolic or polyimide resin-bonded grains for cut-off and grinding wheels requiring shock resistance.
- Vitrified:Glass-ceramic bonded structures for precision grinding wheels in tool room applications.
- Others:Rubber-bonded and shellac-bonded specialty forms for niche surface conditioning.
Brown Fused anchors volume throughput; Resinoid bonded forms are expanding most quickly in automated grinding cell integration.
Application:
Surface finish specifications and automation penetration differentiate margin tiers across end-use segments.
- Metalworking:General machinery, automotive components, and structural steel fabrication. German and Japanese machine tool OEMs now specify grains directly rather than through distributor channels.
- Aerospace Component Finishing:Turbine blade root conditioning and landing gear surface preparation. Sub-micron Ra specifications mandate seeded-gel ceramic alumina; qualification barriers exclude uncertified suppliers.
- Electronics Manufacture:Semiconductor packaging, PCB depaneling, and wafer back-grinding. Cleanroom requirements in South Korean and Taiwanese fabs favor precision-shaped grain geometries.
- Construction:Concrete surface preparation and masonry cutting. Price-sensitive procurement in emerging markets sustains brown fused alumina dominance.
- Woodworking:Furniture finishing and engineered panel sizing. Silicon carbide variants capture hardwood sanding applications.
- Tool Sharpening:Cutting tool reconditioning for machine shops and mobile sharpening services.
Metalworking absorbs the largest volume share; Electronics Manufacture is climbing the fastest on specification intensity.
End User:
Procurement sophistication and quality system requirements stratify the customer base.
- Precision Engineering Firms:Stuttgart, Nagoya, and Hartford clusters demand documented grain provenance and ISO-certified quality management. Direct specification relationships with Saint-Gobain and 3M bypass traditional distribution.
- Electronics Manufacturers:Semiconductor fabs and contract assemblers in Hsinchu, Pyeongtaek, and Chandler impose cleanroom-compatible packaging and lot traceability.
- Fabrication Workshops:Job shops and metal service centers purchasing through industrial distributors on price and availability.
- Construction Contractors:Project-based procurement with minimal technical specification; volume buyers in China and India.
- Aircraft Maintenance:MRO facilities with OEM-approved process specifications; AS9100 quality requirements.
- Tool Manufacturers:Cutting tool producers integrating grains into bonded and coated abrasive products.
Fabrication Workshops represent the broadest installed base; Precision Engineering Firms are gaining share fastest on specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao and Shanghai port complexes handle the bulk of bauxite imports that feed fused alumina smelters across Shandong and Henan provinces. Containerized grain exports from these terminals reach precision engineering clusters in Germany and Japan within 21 days.
China
MEE air quality directives are forcing emission control retrofits during furnace rebuild cycles in Zhengzhou and Luoyang. The dual carbon goals mandate energy efficiency upgrades at brown fused alumina plants. Yangtze River Delta electronics manufacturers are absorbing precision-shaped ceramic grains for semiconductor packaging operations.
Germany
EU Green Deal carbon border adjustments favor low-carbon grain imports from renewable-powered Asian suppliers. Stuttgart and Aachen precision engineering clusters specify ISO 9001:2015 certified grains through direct procurement. REACH registration requirements exclude uncertified conventional alumina from Tier-1 aerospace contracts.
United States
EPA Clean Air Act enforcement on particulate emissions is accelerating capital flows toward closed-loop recycling infrastructure. Aerospace OEMs in Hartford and Wichita mandate seeded-gel ceramic alumina for sub-micron surface finishes. OSHA silica exposure limits constrain legacy furnace operations in Arkansas and New York.
India
PLI scheme incentives for electronics manufacturing are expanding demand for cleanroom-compatible grains in Bengaluru and Chennai. Captive bauxite processing in Kerala and Odisha anchors South Asian supply security. CDSCO quality mandates for medical device grinding are elevating certification barriers for bonded abrasive imports.
Japan
METI technology roadmaps prioritize engineered grain architectures for automotive transmission manufacturing. Nagoya and Toyota City machine tool OEMs now specify grains directly rather than through distributor channels. JIS standards for precision grinding wheels gate market access for foreign suppliers.
Abrasive Grains Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers and geographic coverage. The vendor base stratifies into integrated mining-to-grain operators, precision ceramic specialists, and regional fused alumina processors. Three archetypes dominate: captively integrated bauxite-to-abrasive conglomerates, sol-gel technology licensors, and furnace-based commodity producers. M&A activity concentrates on ceramic alumina technology acquisitions and Southeast Asian distribution assets.
Within the integrated tier, Saint-Gobain Abrasives exemplifies multi-continent mining and refining operations. 3M occupies a position in precision-shaped ceramic grain architectures. Carborundum Universal Limited anchors South Asian supply through captive bauxite processing. These three represent the spectrum from commodity scale to engineered premium positioning.
| Leading Market Players |
|---|
| Saint-Gobain Abrasives |
| 3M |
| Carborundum Universal Limited |
| Asahi Diamond Industrial |
| Fujimi Incorporated |
| Washington Mills |
| Noritake |
| Tyrolit |
| Henkel |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between bauxite processors and aerospace prime contractors lock in both supply access and price visibility across volatile freight corridors. These arrangements insulate Tier-1 grain suppliers from spot market swings while compressing margins for uncertified competitors excluded from direct procurement relationships.
Pricing Analysis
Certification level creates the primary spread between commodity and premium grain tiers. Three-tier pricing structure across aerospace-certified, industrial-grade, and construction-economy levels reflects ISO 9001:2015 compliance costs and REACH dossier preparation expenses. Pricing pressure stems from EPA Clean Air Act enforcement on brown fused alumina smelters, which is forcing legacy producers to absorb emission control retrofit costs. Fabrication workshops purchasing through industrial distributors exhibit highest price sensitivity, while precision engineering firms in Stuttgart and Nagoya clusters prioritize documented provenance over unit cost.
Supply Chain Analysis
China, Guinea, and Australia anchor bauxite-to-fused-alumina production through integrated mining and electric arc fusion operations. The supply chain draws from Guinean ore deposits, Australian calcined Bayer process feedstock, and Indian captive bauxite processing in Kerala and Odisha. Single-source vulnerability concentrates in maritime freight corridors connecting Qingdao and Shanghai to German and Japanese precision engineering clusters. Distribution runs through direct specification relationships with machine tool OEMs for aerospace and electronics segments, while construction-grade volumes flow via industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grain specification standardization across aerospace OEMs is creating platform-economics dynamics where certified suppliers capture interoperability premiums and uncertified producers face systematic exclusion.
For Market Incumbents: Compound technology leadership in seeded-gel ceramic alumina architectures through R&D investment in sol-gel synthesis automation. Defend against silicon carbide substitution in glass and stone grinding by locking in long-term offtake contracts with German and Japanese machine tool OEMs. Prioritize backward integration into captive bauxite processing to offset Guinean ore freight volatility. For New Entrants and Emerging Players: ISO 9001:2015 fast-track certification opens procurement eligibility for Indian electronics manufacturing expansion under PLI scheme incentives. Target semiconductor packaging and PCB depaneling operations in Bengaluru and Chennai with cleanroom-compatible packaging capabilities. Pursue joint development agreements with Yangtze River Delta fabs to establish lot traceability credentials. For Investors and Strategic Acquirers: Sol-gel technology licensors with aerospace qualification track records represent the highest-conviction acquisition archetype for premium segment exposure. Long-term viability hinges on differentiation from commodity fused alumina through engineered grain geometries. Watch for CBAM implementation acceleration as the signal for low-carbon production method premiums to widen.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Processing | Captive ore supply from Kerala and Odisha insulates against Guinean freight volatility and geopolitical disruption. |
| Ceramic Alumina Capacity Expansion | New sintering installations in China, Germany, and India expand global engineered grain availability for aerospace applications. |
| Closed-Loop Recycling Infrastructure | EPA Clean Air Act enforcement redirects capital toward particulate recovery systems in Arkansas and New York operations. |
| Direct Specification Relationships | Tier-1 automotive and aerospace contractors now procure grains through machine tool OEM channels rather than distributor recommendation. |
| REACH Compliance Investment | ECHA registration for conventional formulations consumes 18-24 month timelines and excludes uncertified suppliers from European aerospace contracts. |
Research Methodology
Desk research of customs and trade databases, SEC filings from listed abrasive manufacturers, and MEE air quality directive documentation preceded structured interviews with plant managers at fused alumina smelters, procurement leads at German machine tool OEMs, and technical R&D directors at ceramic grain specialists. Bottom-up volume modeling triangulated against top-down value estimates derived from bauxite import flows and bonded abrasive production data.
Variance decomposition across product chemistry, form, application, and end-user concentration dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including aerospace production cycles and electronics capital expenditure patterns. Forecast inputs incorporated REACH registration timeline assumptions and EPA enforcement intensity scenarios.
Underlying assumptions cover sustained aerospace OEM specification upgrading and MEE directive compliance timelines, with deviation risk concentrated in bauxite freight corridor disruptions and CBAM implementation acceleration. Recalibration cycles align with material shifts in regulatory enforcement intensity and engineered grain technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.