
 Tungsten Carbide Powder Market | 2026-2036
Tungsten Carbide Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Carbide Powder Market Outlook
Asset-light toll-processing arrangements is reconfiguring competitive entry in tungsten carbide powder production, lowering capital barriers for specialty-grade entrants. H.C. Starck GmbH leverages its captive reduction furnaces to sustain premium powder consistency across European aerospace supply chains. Xiamen Tungsten Co., Ltd. anchors downstream integration from ore concentrate through finished carbide, dominating cost structures in Asian markets. Sandvik AB competes through in-house recycling loops that control tungsten scrap flows across its cutting-tool networks.
Tungsten carbide powder consists of a binary compound of tungsten and carbon, typically produced through carburization of tungsten metal or direct reduction of tungsten oxides in carbon atmospheres at temperatures exceeding 1,400°C, yielding hardness values near 2,400 HV for cemented carbide applications. Fine powder grades for cutting tools command the widest volume base, while nanopowder formulations for additive manufacturing represent the fastest-expanding margin pool as binder-jet printing of wear parts scales. Spray-dried granules remain the dominant form for automated pressing operations, though spherical plasma-atomized powders are displacing conventional morphology in thermal spray coatings for oil and gas drilling components.
EPA NESHAP standards for hardmetal production facilities restrict hexavalent chromium and cobalt particulate emissions, forcing powder producers to retrofit baghouse systems or relocate finishing operations. REACH registration requirements in Europe mandate full substance dossiers for nano-scale tungsten carbide, creating compliance asymmetries between established EU suppliers and import-dependent processors. China's GB standards through SAMR impose mandatory purity certifications on domestic powder grades, tightening market access for uncertified foreign shipments. Stakeholders must monitor evolving classification thresholds for nanomaterials under OECD testing guidelines, as regulatory reclassification would trigger new toxicity assessment burdens across formulation portfolios.
Market Dynamics
Asset-light toll-processing arrangements are reconfiguring competitive entry in tungsten carbide powder production, lowering capital barriers for specialty-grade entrants while established producers defend through captive reduction infrastructure and recycling loops.
Growth Catalysts
- REACH nano-registration mandates:ECHA substance dossier requirements for nano-scale tungsten carbide are creating compliance asymmetries that favor established EU suppliers with existing registration portfolios.
- Aerospace thermal barrier coatings:Turbine blade coating specifications from Rolls-Royce and GE Aviation are pulling fine-grade powder demand toward 0.5-1.0 micron consistency thresholds.
- Zhuzhou cluster concentration:China's cemented carbide manufacturing agglomeration in Hunan province is concentrating downstream demand within 200 kilometers of powder reduction facilities.
Market Restraints
- Tungsten concentrate supply concentration:Over 80% of global tungsten ore originates from Chinese mines, exposing non-Chinese processors to concentrate price volatility and export quota fluctuations.
- EPA NESHAP retrofit costs:Hexavalent chromium and cobalt particulate emission limits for hardmetal production facilities are forcing powder producers to install baghouse systems or relocate finishing operations.
- Ceramic cutting tool substitution:Silicon nitride and silicon carbide inserts are displacing tungsten carbide in high-speed dry machining applications above 1,000 surface meters per minute.
Strategic Opportunities
- India PLI scheme for machine tools:Production-linked incentive allocations for precision manufacturing equipment are stimulating domestic cemented carbide demand in Bangalore and Pune industrial corridors.
- Binder-jet additive manufacturing:Nanopowder formulations for wear part printing are opening margin pools in oil and gas component remanufacturing where near-net-shape geometries reduce material waste.
- Dual carbon policy alignment:China's MEE carbon intensity targets are incentivizing tungsten scrap recycling investments that bypass virgin ore energy consumption.
Industry Challenges
- Reduction furnace operator scarcity:Carburization process expertise at 1,400°C+ operating temperatures requires specialized metallurgical training that outpaces vocational pipeline output in European and North American manufacturing regions.
- OECD nanomaterial reclassification risk:Pending toxicity assessment guideline updates for tungsten carbide nanoparticles could trigger mandatory new substance testing across formulation portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Carbide Powder Market |
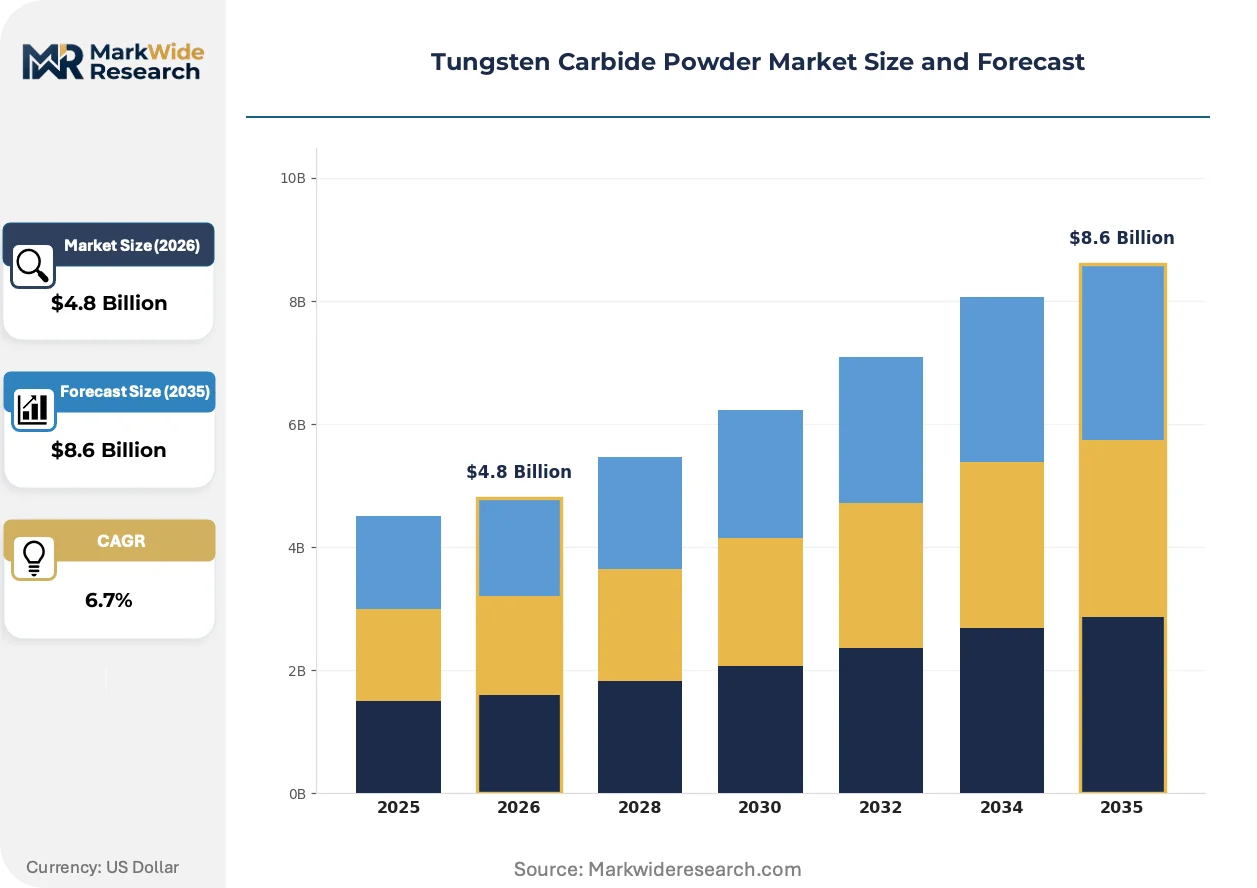
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Powder, Fine Powder, Ultra-Fine Powder, Nanopowder End User: Aerospace, Mining, Manufacturing, Oil & Gas Application: Cutting Tools, Abrasives, Wear Parts, Metalworking Form: Spray-Dried, Spherical, Granulated, Mixed |
| Companies Covered | H.C. Starck GmbH, Xiamen Tungsten Co., Ltd., Sandvik AB, Hyperion Materials & Technologies, Japan New Metal Co., Ltd., Kennametal Inc., Umicore, Global Tungsten & Powders, Ceratizit S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Carbide Powder Market Strategic Shifts
Plasma atomization and spray-drying process lines are converging to serve diverging end-use specifications, with morphology control becoming the primary axis of product differentiation rather than purity alone.
Spherical plasma-atomized powders are hybridizing thermal spray coating performance for oil and gas drilling components, with Baker Hughes and Schlumberger procurement specifications now requiring 45-106 micron spherical fractions for high-velocity oxy-fuel deposition. The morphology shift is compressing conventional angular powder margins in wear-resistant coating applications while opening premium pricing tiers for controlled sphericity grades.
EPA NESHAP standards for hardmetal production facilities are tightening hexavalent chromium emission thresholds, forcing powder producers serving US aerospace supply chains to retrofit baghouse filtration or consolidate finishing operations into purpose-built facilities. The compliance burden falls disproportionately on toll-processors without captive environmental infrastructure, accelerating consolidation among mid-scale independent producers.
Specification-driven purchasing is consolidating procurement authority at OEM central engineering functions, displacing decentralized plant-level buying for cemented carbide feedstock. Sandvik Coromant and Kennametal direct-account structures are capturing specification-setting influence earlier in design cycles, with tool geometry CAD integration now preceding powder grade selection in automotive powertrain programs across Stuttgart and Detroit manufacturing regions.
Tungsten Carbide Powder Market Segmentation
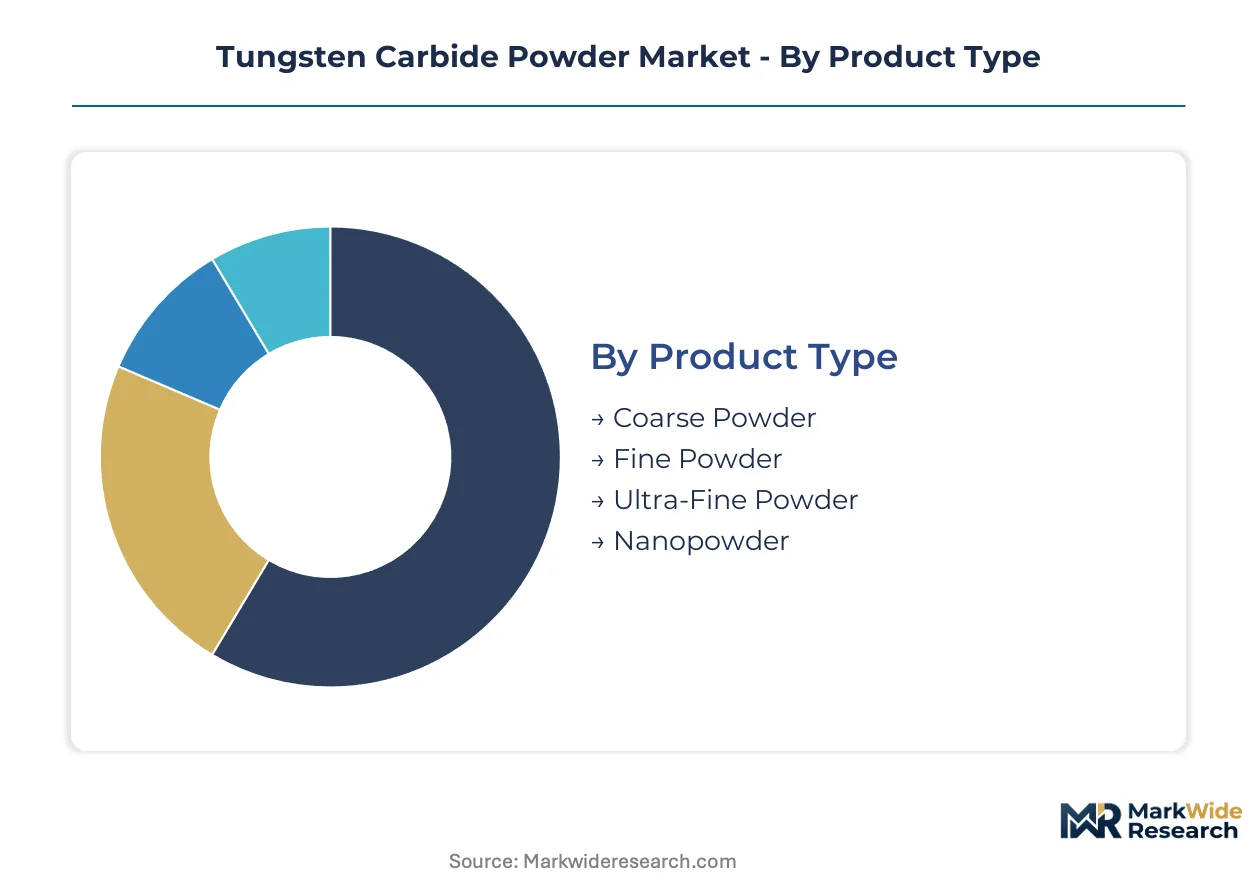
Tungsten carbide powder specifications diverge sharply across end-use performance thresholds, with particle size distribution and morphology dictating pricing tiers and supply chain qualification requirements. Segmentation clarity enables producers to align furnace reduction parameters with downstream certification demands.
Product Type:
Use-case spectrum spans from bulk wear-resistant matrices to precision-engineered thermal barriers, with particle size thresholds determining furnace operating temperatures and post-processing intensity.
- Fine Powder:Particle sizes of 1-5 microns dominate cemented carbide cutting tool production, with 0.5-1.0 micron consistency thresholds now mandatory for Rolls-Royce and GE Aviation turbine blade coating specifications. Demand concentrates in European aerospace supply chains where REACH nano-registration creates compliance asymmetries favoring established EU suppliers.
- Nanopowder:Sub-100 nanometer formulations enable binder-jet additive manufacturing of near-net-shape wear parts for oil and gas component remanufacturing. The fastest-expanding margin pool sits in thermal spray applications where spherical morphology requirements from Baker Hughes and Schlumberger procurement specifications command premium pricing tiers.
- Coarse Powder:10-50 micron grades serve mining drill bit matrices and heavy-duty earthmoving equipment where fracture toughness outweighs edge retention requirements.
- Ultra-Fine Powder:0.5-1.0 micron fractions bridge conventional fine grades and nanopowder specifications for high-precision metalworking inserts.
The dominant share belongs to Fine Powder, while Nanopowder is closing the gap fastest.
End User:
Customer concentration patterns reflect regional manufacturing agglomeration and regulatory stringency, with specification authority migrating toward OEM central engineering functions.
- Aerospace:Thermal barrier coating specifications from turbine manufacturers drive purity requirements exceeding standard cemented carbide grades, with EPA NESHAP hexavalent chromium emission thresholds forcing powder producers to retrofit baghouse filtration systems.
- Manufacturing:Automotive powertrain programs across Stuttgart and Detroit manufacturing regions now integrate tool geometry CAD selection ahead of powder grade procurement, consolidating specification-setting influence at Sandvik Coromant and Kennametal direct-account structures.
- Mining:Drill bit and earthmoving equipment demand concentrates in China's cemented carbide manufacturing clusters, particularly around Zhuzhou in Hunan province.
- Oil & Gas:High-velocity oxy-fuel deposition specifications require 45-106 micron spherical fractions for drilling component coatings, compressing conventional angular powder margins in wear-resistant applications.
Manufacturing commands the largest volume position, though Aerospace exhibits the steepest expansion trajectory on specification-driven premiumization.
Application:
Functional performance requirements segment powder morphology investment, with automated pressing operations demanding spray-dried flow characteristics distinct from thermal spray deposition needs.
- Cutting Tools:Fine powder grades for indexable inserts and solid carbide end mills represent the widest volume base, with silicon nitride and silicon carbide ceramic substitution threatening displacement above 1,000 surface meters per minute in high-speed dry machining.
- Wear Parts:Oil and gas drilling components, pump seals, and valve trim applications specify controlled sphericity grades for plasma-transferred arc and high-velocity oxy-fuel deposition processes.
- Metalworking:Drawing dies, stamping tools, and extrusion mandrels require consistent grain size distribution for uniform wear resistance across production runs.
- Abrasives:Grinding wheel matrices and lapping compounds utilize angular fracture morphology distinct from spherical coating specifications.
Cutting Tools retains the volume leadership position, while Wear Parts gains share fastest on additive manufacturing qualification.
Form:
Physical conditioning determines handling economics and deposition efficiency, with morphology control displacing purity as the primary axis of product differentiation.
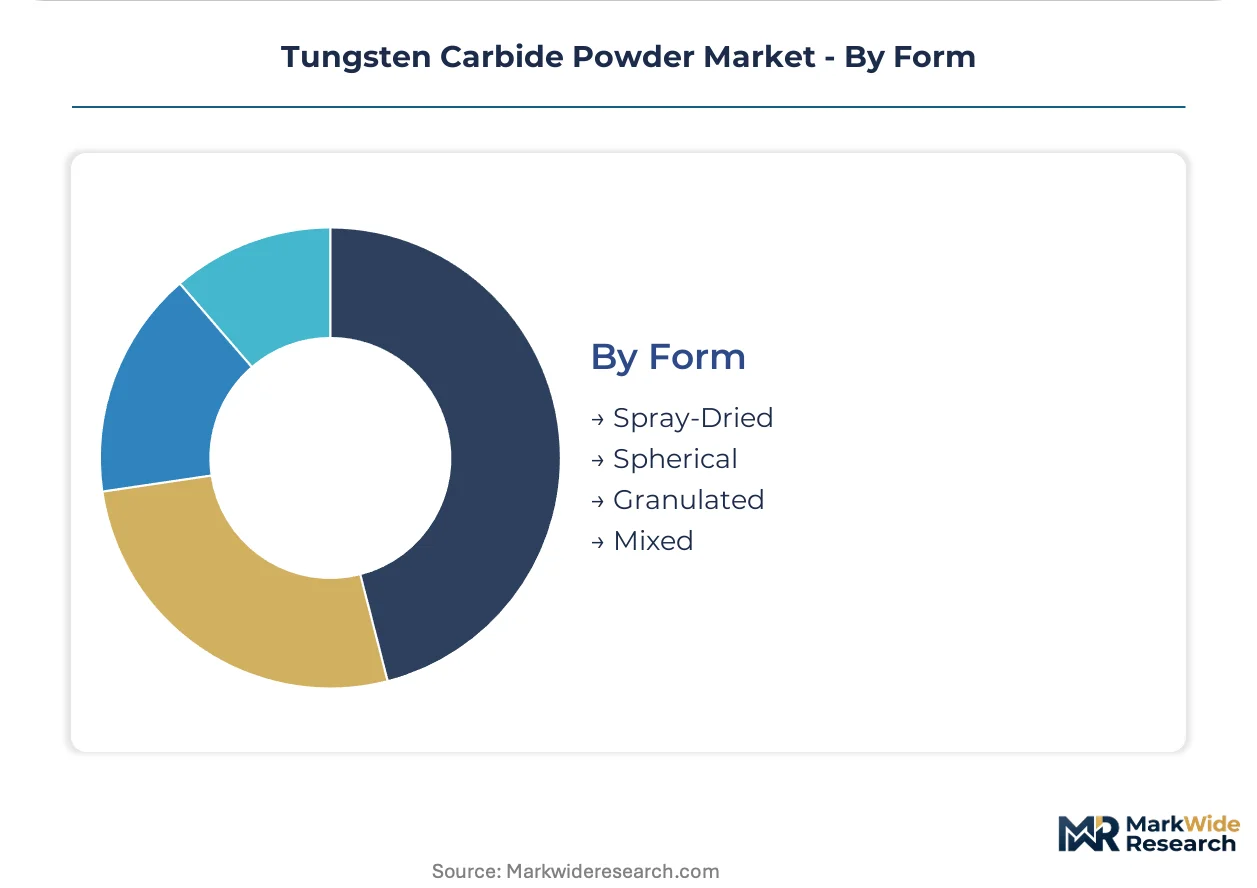
- Spray-Dried:Granular agglomerates with organic binders dominate automated pressing operations for cemented carbide preforms, offering flow characteristics essential for high-speed die filling.
- Spherical:Plasma-atomized morphology serves thermal spray coating applications where consistent feeding through HVOF guns requires controlled particle sphericity and narrow size distribution.
- Granulated:Sintered pre-agglomerates reduce dust exposure during handling and improve green strength prior to final densification.
- Mixed:Custom blends of multiple size fractions enable tailored packing density for specific pressing or infiltration processes.
Spray-Dried holds the dominant share, while Spherical is expanding most quickly on coating specification migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tungsten concentrate exports shape import dependency for processors across Germany, the United States, and Japan, creating asymmetric supply security calculations that regional manufacturers address through scrap recycling investments and strategic ore stockpiling.
China
Zhuzhou's cemented carbide cluster in Hunan province concentrates downstream demand within 200 kilometers of reduction facilities, while SAMR's GB standards impose mandatory purity certifications that tighten market access for uncertified foreign shipments. Xiamen Tungsten Co., Ltd. anchors backward integration from ore concentrate through finished carbide, dominating regional cost structures.
Germany
REACH nano-registration mandates from ECHA create compliance asymmetries favoring established EU suppliers with existing substance dossiers for sub-100 nanometer formulations. H.C. Starck GmbH leverages captive reduction furnaces to sustain premium powder consistency across aerospace supply chains serving Rolls-Royce and MTU Aero Engines specifications.
United States
EPA NESHAP standards restrict hexavalent chromium and cobalt particulate emissions, forcing powder producers to retrofit baghouse systems or relocate finishing operations. Kennametal Inc. and Hyperion Materials & Technologies operate direct-account structures that consolidate specification-setting influence with automotive OEMs in Detroit manufacturing corridors.
Japan
Japan New Metal Co., Ltd. serves precision cutting tool manufacturers in Nagoya and Osaka industrial zones where JIS standards govern grain size distribution consistency. METI's critical materials designation for tungsten stimulates strategic stockpile maintenance that buffers concentrate price volatility from Chinese export fluctuations.
Tungsten Carbide Powder Market Competitive Environment
On the supply side, the industry is bifurcated between integrated ore-to-powder conglomerates and asset-light toll processors, with furnace capacity scarcity creating tiered entry barriers that favor incumbents with captive reduction infrastructure. Strategic archetypes span backward-integrated Chinese mining groups, European specialty chemical houses with REACH registration portfolios, and Scandinavian engineering conglomerates with closed-loop recycling networks. Dominant competitive moves include vertical consolidation of tungsten scrap flows and geographic expansion of toll-processing partnerships to bypass capital-intensive furnace construction.
Among European specialty chemical houses, H.C. Starck GmbH exemplifies the REACH-registered archetype, while Xiamen Tungsten Co., Ltd. represents the fully integrated model spanning concentrate extraction through finished powder. Sandvik AB occupies a distinctive position through its captive recycling infrastructure that controls scrap tungsten flows across cutting-tool networks, creating circular supply advantages distinct from virgin ore dependence.
| Leading Market Players |
|---|
| H.C. Starck GmbH |
| Xiamen Tungsten Co., Ltd. |
| Sandvik AB |
| Hyperion Materials & Technologies |
| Japan New Metal Co., Ltd. |
| Kennametal Inc. |
| Umicore |
| Global Tungsten & Powders |
| Ceratizit S.A. |
| Others |
Value Chain & Pricing Dynamics
Underutilized reduction furnace capacity in Eastern European toll-processing facilities is compressing spot pricing for standard-grade powders while tightening availability for aerospace-qualified nano-formulations. This utilization asymmetry rewards incumbents with captive furnace infrastructure and REACH-registered portfolios, while forcing asset-light processors toward volume-driven commodity tiers or exit.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium REACH-registered nano-grades, standard SAMR-certified intermediates, and economy spot-market coarse powders. Price differentiation rests on certification tier and furnace consistency rather than purity alone, with EPA NESHAP compliance costs intensifying margin pressure on non-captive processors serving US aerospace supply chains. Cemented carbide cutting tool manufacturers exhibit highest price sensitivity due to ceramic substitution threats above 1,000 surface meters per minute, while thermal barrier coating specifications from Rolls-Royce and GE Aviation tolerate premium positioning for 0.5-1.0 micron consistency thresholds.
Supply Chain Analysis
Extended payment terms from Zhuzhou cluster buyers now stretch to 120 days for non-integrated processors, compressing working capital for toll-operators without supply-chain finance facilities. Raw material sourcing draws from Chinese tungsten concentrate, Vietnamese intermediate oxides, and Russian ferrotungsten scrap, with over 80% of global ore originating from Chinese mines exposing non-Chinese processors to export quota volatility. Distribution runs through direct-account structures at Sandvik Coromant and Kennametal that consolidate specification-setting authority with automotive OEM central engineering functions, displacing decentralized plant-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tungsten carbide powder market is recovering from a cyclical trough driven by depressed mining capital expenditure and aerospace production rate adjustments. Normalization of GE Aviation and Rolls-Royce turbine blade coating procurement volumes provides the cyclical justification for strategic repositioning.
For Market Incumbents: Build captive recycling moats that control scrap tungsten flows across cutting-tool networks, bypassing virgin ore energy consumption and Chinese concentrate price volatility. Defend through furnace capacity additions in European REACH-registered jurisdictions to capture aerospace specification migration toward nano-grade consistency thresholds, while monitoring silicon nitride ceramic substitution in high-speed dry machining above 1,000 surface meters per minute. For New Entrants and Emerging Players: Toll-processing partnerships with underutilized Eastern European reduction facilities represent the most penetrable entry point for specialty-grade qualification without capital-intensive furnace construction. Target India's PLI-stimulated machine tool demand in Bangalore and Pune corridors through technical service partnerships with domestic cemented carbide formulators, leveraging asset-light arrangements to bypass SAMR certification barriers for uncertified foreign shipments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across toll-processing sub-segments as furnace operator scarcity forces outsourcing of carburization expertise. Long-term viability favors acquisition targets with established REACH nano-registration portfolios and aerospace supply chain qualifications, with OECD nanomaterial reclassification risk serving as the critical signal to monitor for toxicity assessment burden inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Scrap Recycling | Sandvik's closed-loop networks bypass virgin ore energy consumption and Chinese export quota exposure. |
| REACH Nano-Registration Portfolio Investment | ECHA substance dossiers for sub-100 nanometer formulations create compliance asymmetries favoring established EU suppliers. |
| Toll-Processing Partnership Expansion | Asset-light arrangements with Eastern European furnace operators lower entry barriers for specialty-grade entrants. |
| India PLI Corridor Market Development | Production-linked incentive allocations for precision manufacturing equipment stimulate domestic cemented carbide demand. |
| Spherical Powder Morphology Capacity Addition | Plasma atomization lines serve Baker Hughes and Schlumberger HVOF deposition specifications for oil and gas drilling components. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cemented carbide plant managers, aerospace coating procurement leads at Rolls-Royce and GE Aviation, toll-processing furnace operators, and SAMR certification specialists. Secondary validation drew from ECHA substance dossier databases, EPA NESHAP compliance filings, Chinese customs tungsten concentrate trade data, and SEC 10-K disclosures from listed hardmetal producers. Bottom-up segment sizing across fine, nanopowder, coarse, and ultra-fine grades was triangulated against top-down macroeconomic intensity models.
Calibration against historical capacity utilization rates at Zhuzhou cluster facilities and European toll-processing operators anchored volume projections across the analysis window. Segmentation dimensions modeled include particle size distribution tiers, morphology specifications, end-use industry verticals, and regional regulatory compliance clusters. CAGRs were derived from elasticity-adjusted intensity curves tied to aerospace production rates, mining capital expenditure cycles, and automotive powertrain machining content per vehicle.
Practitioners should monitor OECD nanomaterial reclassification proceedings and Chinese tungsten export quota announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Metal Abrasives Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Abrasive Base Paper Market
Abrasives
Polishing Chemicals Market
Abrasives
Chemical Deflasher Market
Abrasives
Calcined Shale Market
Abrasives
Grinding Wheels Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
New Zealand Abrasives Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Tungsten Carbide Market
Abrasives
Super Abrasives Market
Abrasives
Boron Carbide Bulletproof Plate Market
Abrasives
Polishing Powder Market
Abrasives
Rare Earth Polishing Materials Market