
 Metal Abrasives Market | 2026-2036
Metal Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Abrasives Market Intelligence
China is narrowing the quality gap with European steel shot producers through automated casting investments in Shandong and Jiangsu provinces. W Abrasives leverages its French manufacturing heritage to sustain premium positioning in aerospace peening applications. Ervin Industries anchors North American supply through vertically integrated melt facilities in Ohio and Georgia. Grindwell Norton Ltd competes across South Asian construction and metalworking channels with localized blending operations.
Metal abrasives are hard, granular materials—predominantly cast steel, aluminum oxide, and silicon carbide—manufactured through controlled atomization or fusion processes to achieve precise hardness ratings between 40 and 65 HRC for surface treatment applications. These materials function by kinetic impact or frictional removal to clean, texture, or strengthen metallic substrates across industrial workflows. Steel shot dominates volume flows in automotive and aerospace shot peening due to its recyclability and consistent peening intensity, while aluminum oxide garners margin premiums in precision finishing for medical device and electronics substrates where contamination control is paramount. Garnet and silicon carbide segments occupy narrower positions, with garnet sustaining demand in waterjet cutting auxiliary markets and silicon carbide retaining specialty traction for superalloy grinding where thermal stability requirements exclude conventional alternatives.
EPA air quality standards and OSHA permissible exposure limits for respirable crystalline silica are reshaping product formulation priorities among US-based metal abrasive suppliers, forcing migration toward pre-conditioned or low-dust steel shot variants. In Europe, REACH substance restrictions and the F-Gas Regulation indirectly tighten environmental accountability across the abrasive supply chain, while BIS certification mandates in India filter import competition. Stakeholders must monitor evolving hazardous substance thresholds across these jurisdictions to align product portfolios with compliance-driven procurement specifications.
Market Dynamics
REACH and RoHS compliance in Europe is collapsing the addressable market for high-free-silica abrasives, forcing foundries and automotive OEMs to reformulate procurement specifications around pre-conditioned steel shot and engineered aluminum oxide alternatives with certified low-dust profiles.
Growth Catalysts
- Shot peening intensity:Automotive OEMs in Germany and China are expanding surface treatment operations for lightweight alloy chassis components, driving specification-grade steel shot consumption.
- REACH substance restrictions:European foundries face mandatory migration away from crystalline silica-bearing abrasives, creating replacement demand for compliant steel and ceramic alternatives.
- Waterjet cutting expansion:Precision manufacturing clusters in India and Southeast Asia are adopting garnet abrasives for composite material processing in aerospace subcontracting.
Market Restraints
- Scrap steel price volatility:Electric arc furnace feedstock costs fluctuate with regional scrap availability, compressing margins for cast steel abrasive producers in North America and Europe.
- Supply concentration in Shandong:Chinese automated casting investments have consolidated global steel shot capacity in a single province, exposing buyers to logistics disruption and trade policy uncertainty.
- Technical limitation in superalloy grinding:Silicon carbide retains necessary thermal stability for nickel-based aerospace alloys where aluminum oxide degrades, restricting substitution pathways in this premium segment.
Strategic Opportunities
- Medical device finishing:BIS-certified aluminum oxide grades command procurement preference in India's Pune and Rajkot metalworking clusters for implant surface preparation.
- EPA air quality standards:OSHA permissible exposure limits for respirable crystalline silica are accelerating US demand for pre-conditioned low-dust steel shot variants.
- Recyclability service models:Closed-loop abrasive recovery systems are penetrating automotive OEM contracts in Germany, shifting revenue from product sales to consumption-based contracts.
Industry Challenges
- Metallurgical specification expertise:Shot peening intensity calibration requires specialized technicians, creating hiring bottlenecks for service providers expanding into aerospace certification.
- BIS certification timelines:Indian import competition faces 12-18 month approval cycles for new abrasive grades, delaying market entry for European and Chinese suppliers.
- Legacy equipment retrofit costs:Dust collection and pneumatic delivery systems in older foundries require capital investment to handle low-dust abrasive formulations without clogging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Abrasives Market |
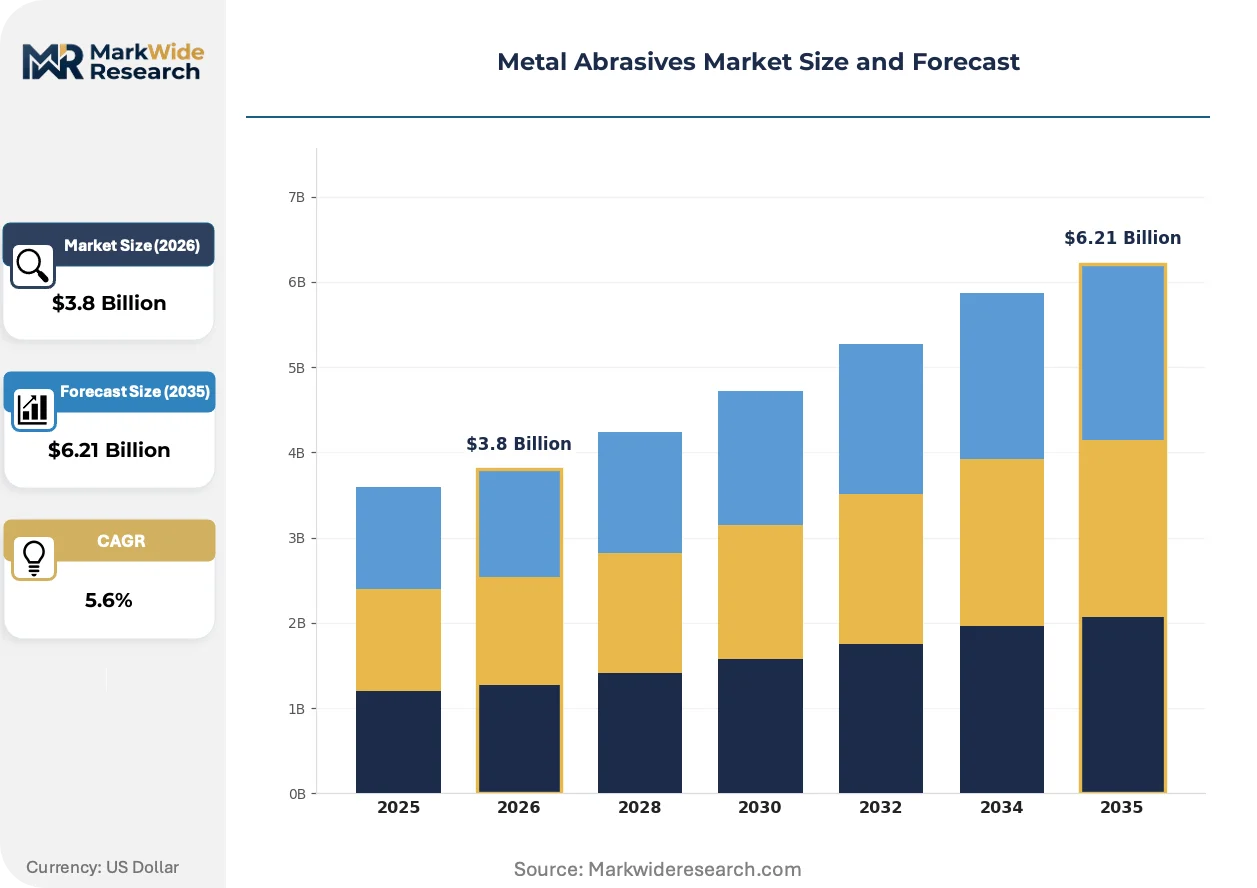
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Oxide, Silicon Carbide, Garnet, Steel Shot Application: Surface Preparation, Finishing, Polishing, Cleaning End User: Aerospace, Automotive, Metalworking, Construction Grade: Coarse, Medium, Fine, Super Fine |
| Companies Covered | Abrasives Inc., Vulkan INOX GmbH, Ervin Industries, Abrasive Shot, 3M India Ltd., Macro Group International, Metaltec Steel Abrasive, W Abrasives, Grindwell Norton Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Abrasives Market Strategic Shifts & Innovations
Automation in abrasive casting and peening control systems is compressing quality variation between regional producers, while regulatory pressure on workplace silica exposure is eliminating product categories faster than replacement technologies can achieve cost parity.
Pre-conditioned low-dust steel shot is collapsing the traditional trade-off between operator safety and process economics in foundry cleaning rooms. Automotive OEMs in Germany and the US are mandating these formulations in new equipment specifications. The technology is collapsing resistance to silica-free operations among cost-sensitive job shops that previously deferred capital investment.
REACH substance restrictions and the EU F-Gas Regulation are tightening environmental accountability across the European abrasive supply chain. Foundries face mandatory documentation of abrasive composition and end-of-life handling. Steel shot with certified recycled content and closed-loop logistics is capturing specification preference in aerospace peening contracts subject to CSRD disclosure requirements.
Buyer consolidation among tier-one automotive suppliers is compressing supplier qualification cycles and unbundling after-sales technical service from material supply contracts. Procurement teams at German and Chinese OEMs now separate abrasive specification from peening process optimization, awarding the former to commodity distributors and the latter to specialized service integrators. This bifurcation is most visible in powertrain component manufacturing where shot peening intensity data must integrate directly with statistical process control systems.
Metal Abrasives Market Segmentation
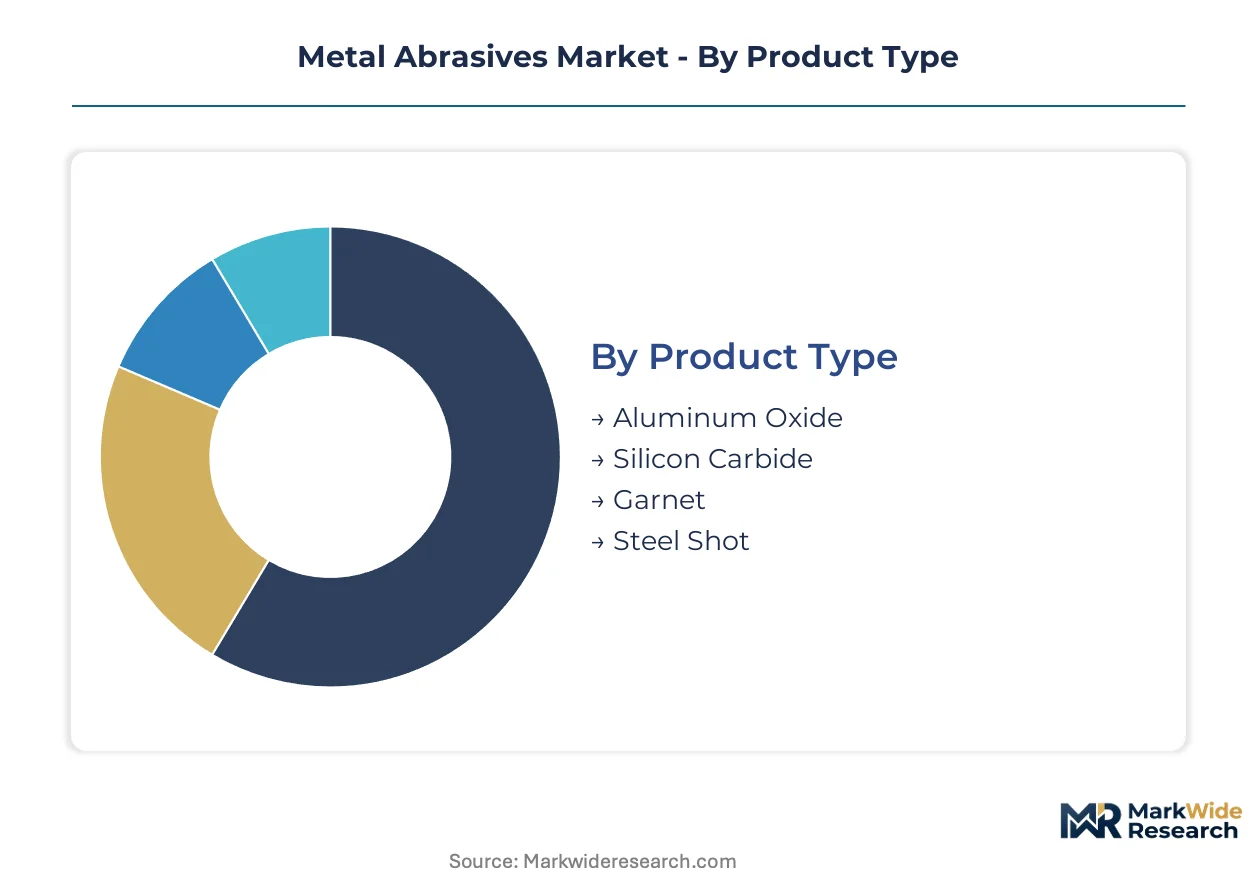
Metal abrasives serve divergent functional requirements across kinetic impact and precision finishing workflows. Segmentation reveals how specification-grade materials command procurement premiums in regulated end-uses while commodity grades compete on recyclability and unit economics.
Product Type:
Material composition determines recyclability profiles, thermal stability thresholds, and contamination risk in surface-sensitive applications.
- Steel Shot:Cast through controlled atomization to achieve 40-65 HRC hardness ratings with consistent sphericity. Automotive OEMs in Germany and China specify this grade for shot peening intensity calibration on lightweight alloy chassis components, driven by recyclability economics and process repeatability requirements.
- Aluminum Oxide:Fused bauxite processed into angular grains with Mohs hardness near 9. Medical device manufacturers in India prefer BIS-certified fine grades for implant surface preparation where metallic contamination must be eliminated, with REACH compliance in Europe accelerating substitution away from silica-bearing alternatives.
- Silicon Carbide:Synthesized through Acheson process to deliver extreme hardness for superalloy grinding where thermal degradation excludes aluminum oxide. Retains necessary stability for nickel-based aerospace alloys.
- Garnet:Naturally occurring almandine mineral crushed to precise mesh sizes. Waterjet cutting operations in Southeast Asian aerospace subcontracting clusters favor this segment for composite material processing.
Established volume favors steel shot; emerging adoption favors aluminum oxide.
Application:
Process intensity separates commodity cleaning from specification-critical surface engineering.
- Surface Preparation:Aggressive material removal through kinetic impact or abrasive blasting to achieve substrate cleanliness grades prior to coating adhesion. Foundries in Europe face mandatory migration from crystalline silica-bearing abrasives under REACH, creating replacement demand for pre-conditioned steel shot.
- Finishing:Controlled texture generation with tight roughness tolerances for functional or aesthetic specifications. Precision electronics manufacturers specify aluminum oxide to prevent metallic contamination on sensitive substrates.
- Polishing:Fine-grade abrasive action to achieve mirror surfaces or precise dimensional tolerances. Medical device finishing contracts require certified grain size distributions.
- Cleaning:Removal of oxides, scale, or contaminants without dimensional change to base material. Legacy foundry equipment retrofit costs constrain adoption of low-dust formulations in cost-sensitive operations.
Surface preparation commands the largest volume footprint; finishing generates the steepest margin expansion.
End User:
Certification requirements and process automation levels fragment demand across industrial maturity tiers.
- Automotive:OEM shot peening operations for powertrain and chassis components with statistical process control integration. Procurement teams separate abrasive specification from peening optimization, awarding materials to distributors and process control to service integrators.
- Aerospace:Peening intensity data must integrate directly with SPC systems for flight-critical component certification. CSRD disclosure requirements in Europe favor steel shot with certified recycled content and closed-loop logistics.
- Metalworking:Job shops and production facilities across India's Pune and Rajkot clusters where BIS-certified grades command procurement preference.
- Construction:Surface preparation for structural steel coating adhesion with price-sensitive procurement and minimal specification enforcement.
Automotive and aerospace concentrate specification-grade demand; metalworking bridges commodity and certified segments.
Grade:
Particle size distribution determines kinetic energy transfer and surface roughness outcomes.
- Coarse:Large grain fractions for aggressive stock removal and heavy-scale descaling in primary metal processing.
- Medium:Balanced cutting action for general-purpose surface preparation across automotive and construction applications.
- Fine:Controlled material removal for finishing operations with moderate roughness requirements.
- Super Fine:Precision grades for polishing and medical device surface engineering where contamination control and dimensional tolerance are paramount.
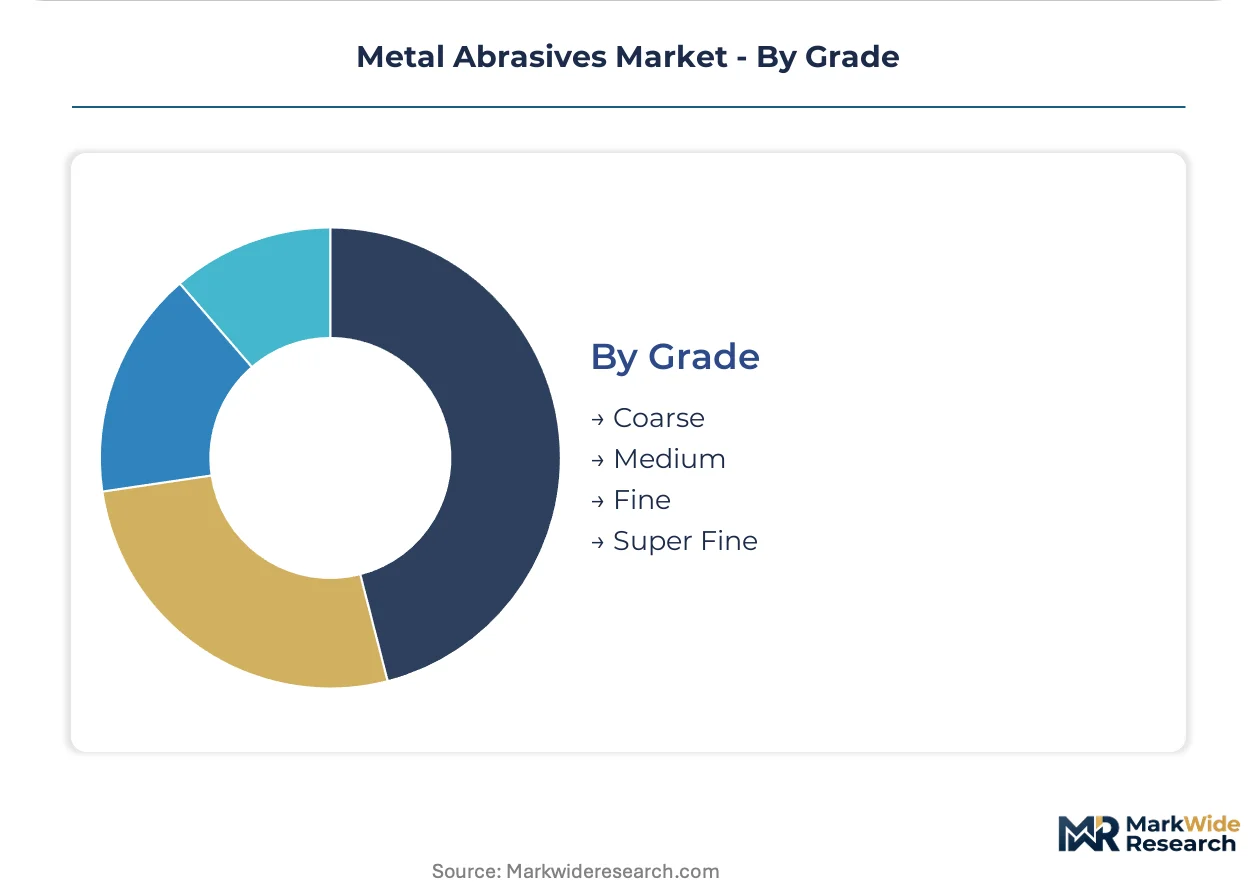
Medium grades dominate volume throughput; super fine commands the narrowest supply base and steepest certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cast steel abrasive capacity clusters in Shandong province expose buyers to concentrated logistics risk, while regulatory divergence across major economies fragments procurement specifications.
China
Automated casting investments in Shandong and Jiangsu provinces are narrowing quality gaps with European steel shot producers. MIIT industrial upgrading guidelines favor high-recyclability abrasives in automotive supply chains. Foundries in the Yangtze River Delta are adopting specification-grade steel shot for lightweight alloy chassis processing.
Germany
Automotive OEMs are expanding shot peening operations for powertrain components with statistical process control integration. REACH substance restrictions mandate migration from crystalline silica-bearing abrasives. Metalworking clusters in Bavaria and Baden-Württemberg specify pre-conditioned low-dust steel shot for foundry cleaning operations.
United States
EPA air quality standards and OSHA permissible exposure limits are accelerating demand for pre-conditioned low-dust steel shot variants. Electric arc furnace feedstock costs fluctuate with regional scrap availability. Vertically integrated melt facilities in Ohio and Georgia anchor North American supply for automotive and aerospace peening contracts.
India
BIS certification mandates filter import competition and command procurement preference in metalworking clusters. Pune and Rajkot production facilities specify certified aluminum oxide grades for medical device surface preparation. CDSCO medical device regulations tighten contamination control requirements for implant finishing operations.
Metal Abrasives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies between premium-positioned heritage manufacturers and scale-driven commodity producers. Three archetypes dominate: vertically integrated melt-to-blast operators, regional blending specialists with local certification access, and technology licensors exporting process expertise. Competitive moves concentrate on capacity expansion in automated casting and strategic partnerships for closed-loop abrasive recovery systems.
Among European heritage manufacturers, W Abrasives occupies a position exemplifying premium-tier aerospace peening specialization, while Vulkan INOX GmbH represents German-engineered precision in stainless steel abrasive formulations. Ervin Industries anchors North American supply through captive melt capacity. Grindwell Norton Ltd exemplifies the regional blending specialist archetype with localized operations across South Asian construction and metalworking channels.
| Leading Market Players |
|---|
| Abrasives Inc. |
| Vulkan INOX GmbH |
| Ervin Industries |
| Abrasive Shot |
| 3M India Ltd. |
| Macro Group International |
| Metaltec Steel Abrasive |
| W Abrasives |
| Grindwell Norton Ltd |
| Others |
Cost & Logistics Intelligence
Shandong province's automated casting investments have consolidated global steel shot capacity, granting Chinese producers outsized leverage in contract negotiations with automotive OEMs in Germany and China. This geographic concentration compresses margin buffers for European heritage manufacturers while amplifying price volatility exposure for buyers dependent on single-source supply.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across the European metal abrasives market, separating premium pre-conditioned low-dust steel shot from commodity-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with BIS-certified aluminum oxide commanding procurement premiums in India's medical device clusters. Cost compression in standard-grade steel shot is intensifying because scrap steel feedstock volatility feeds directly into electric arc furnace economics. Construction end-users exhibit the highest price sensitivity, while aerospace peening contracts demonstrate inelastic demand for specification-grade materials with closed-loop logistics documentation.
Supply Chain Analysis
Export-control regimes on precision casting equipment limit technology transfer to emerging producers, constraining capacity expansion outside established manufacturing hubs. Supply concentrates in China, Germany, and the United States, with raw material flows drawing from regional scrap steel markets, fused bauxite sources, and petroleum coke for silicon carbide synthesis. Single-source vulnerability in Shandong province exposes buyers to logistics disruption and trade policy uncertainty. Distribution runs through commodity distributors for standard grades and specialized service integrators for specification-critical peening applications with process control integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among tier-one automotive suppliers has shifted procurement power toward centralized sourcing teams, fragmenting supplier relationships and compressing qualification cycles for abrasive vendors.
For Market Incumbents: Entrench specification-grade positioning through captive melt capacity expansion in Ohio and Georgia, mirroring Ervin Industries' vertically integrated model. Invest in automated casting technology to match Shandong quality consistency while accelerating BIS certification timelines for Indian market access. Defend against commodity erosion by bundling closed-loop abrasive recovery services with material supply contracts. For New Entrants and Emerging Players: Mid-market metalworking job shops in Southeast Asia represent the most penetrable entry point, underserved by specification-grade suppliers focused on automotive and aerospace certification. Target waterjet cutting subcontracting clusters adopting garnet abrasives for composite material processing. Pursue localized blending operations with regional certification access, following Grindwell Norton Ltd's South Asian channel strategy. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized abrasive divisions lacking standalone scale. Long-term viability hinges on regulatory compliance infrastructure and captive recycling logistics rather than commodity volume positioning. Watch for EPA enforcement acceleration on respirable crystalline silica exposure as the inflection signal for pre-conditioned low-dust formulation adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Steel Supply | Captive melt facilities in Ohio and Georgia insulate Ervin Industries from regional feedstock volatility. |
| Automated Casting Technology Deployment | Shandong and Jiangsu province investments narrow quality gaps with European heritage producers. |
| Closed-Loop Abrasive Recovery Systems | German automotive OEMs shift revenue from product sales to consumption-based service contracts. |
| BIS Certification Investment | Twelve-to-eighteen-month approval cycles filter import competition in India's Pune and Rajkot clusters. |
| Pre-Conditioned Low-Dust Formulation Development | REACH compliance mandates in Europe collapse addressable market for high-free-silica alternatives. |
Research Approach
Cross-validation between trade association capacity data and customs import records anchors the qualitative findings on supply concentration and regional demand patterns. Primary interviews with foundry operations managers, automotive OEM procurement leads, aerospace peening technicians, and abrasive distribution channel partners were synthesized with secondary validation from MIIT industrial upgrading guidelines, EPA air quality enforcement databases, BIS certification registries, and SEC filings from publicly traded abrasive manufacturers. Bottom-up modeling of end-use consumption and top-down reconciliation with production capacity estimates ensured triangulation integrity.
Calibration against historical price elasticity responses and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition grade, application intensity tier, end-user certification requirements, and regional regulatory cluster. CAGRs were derived from slope analysis of demand drivers against capacity expansion schedules, with specific inputs from scrap steel price volatility indices and REACH substance restriction phase-in calendars.
Stress conditions across scrap steel availability, logistics disruption probability, and regulatory enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology adoption curves and buyer consolidation trajectories. Abrasive substitution elasticity in superalloy grinding and silica-free formulation cost parity timelines represent specific risk factors that could revise projections. Cross-checking against ECHA substance restriction announcements and MIIT capacity utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Polishing Powder Market
Abrasives
Polishing Chemicals Market
Abrasives
Abrasive Rolls Market
Abrasives
Anthracite Fines Market
Abrasives
Australia Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Chemical Deflasher Market
Abrasives
Synthetic Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Abrasive Cloth Market
Abrasives
New Zealand Abrasives Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Artificial Abrasives Market