
 Fine Sandpaper Market | 2026-2036
Fine Sandpaper Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Sandpaper Market Insights
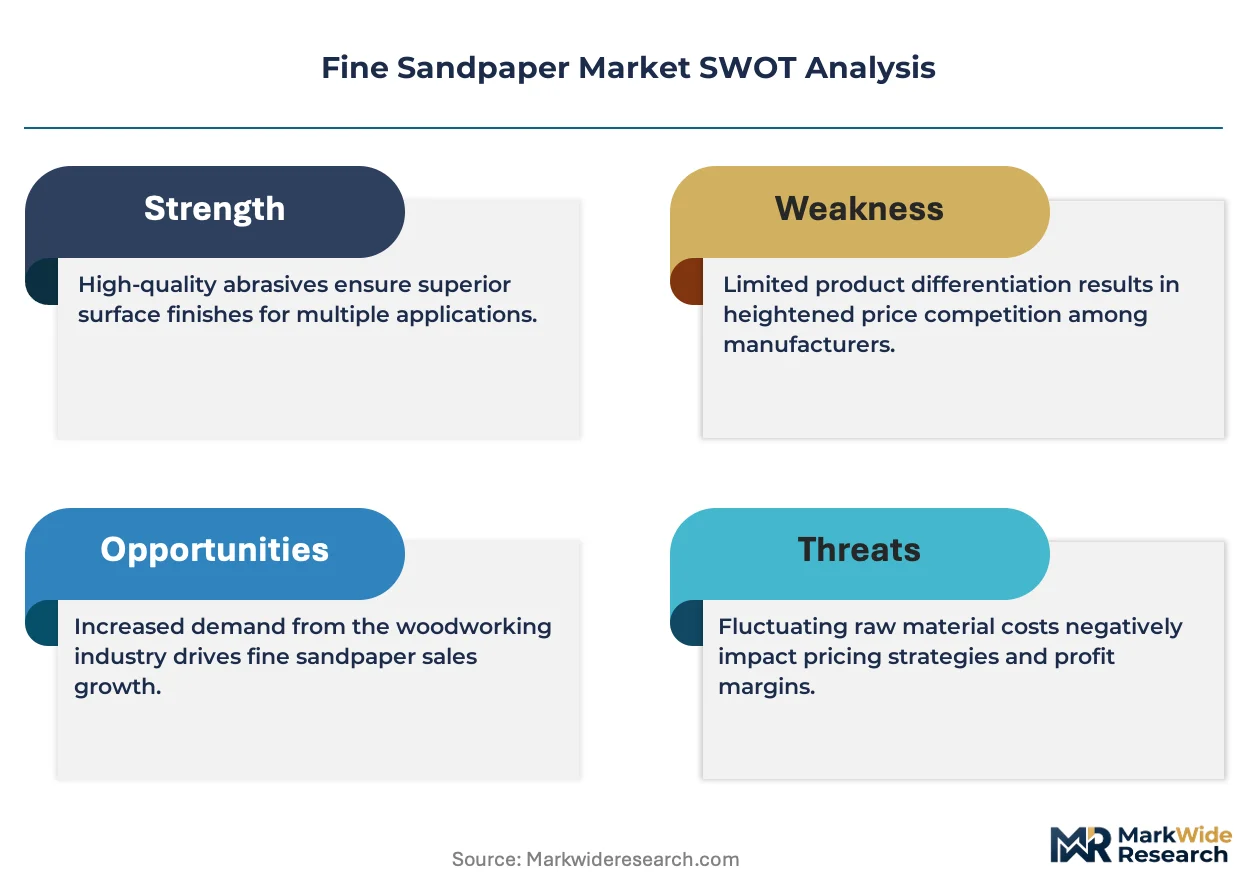
Finnish coated abrasives capacity is pivoting toward dust-free sanding systems for professional contractors. 3M leverages its resin-bonding patents to sustain premium positioning in automotive repair channels. Saint-Gobain anchors European supply through its Norton and SIA Abrasives brands, competing across woodworking and metal finishing segments. Deerfos dominates Asian roll stock production, extending its reach into Middle Eastern distribution networks.
Fine sandpaper consists of abrasive grains—typically aluminum oxide, silicon carbide, or ceramic—bonded to paper, cloth, or film backings in grit ranges from P240 to P2500, engineered for material removal without substrate damage. Wet and dry formulations use waterproof latex-saturated paper to enable water-borne lubrication during automotive color sanding and marine varnish leveling. Abrasive sheets lead volume in furniture manufacturing, where robotic sanding lines consume standardized dimensions, while specialty sheets command margin pools in aerospace turbine blade polishing. Roll stock sustains industrial metal finishing through continuous-feed operations, though discs are displacing sheets in automated automotive repair environments.
EPA oversees workplace silica exposure limits that shape permissible abrasive formulations for US industrial users, while REACH restricts specific resin hardeners in European imports. China's GB standards mandate labeling of backing material composition, affecting export compliance costs for foreign suppliers. California's South Coast Air Quality Management District enforces the strictest volatile organic compound thresholds, forcing reformulation of pressure-sensitive adhesives used in disc production. Stakeholders must monitor evolving regional chemical restrictions and decide whether to regionalize binder chemistry or absorb cross-border certification overhead.
Market Dynamics
Water-based stearate coatings and low-emission binders are forcing wholesale reformulation across the supply base, as REACH in Europe and California's South Coast Air Quality Management District impose incompatible chemistry requirements on manufacturers serving multiple jurisdictions.
Growth Catalysts
- Automotive Repair Channel Expansion:Precision abrasives consumption is accelerating in collision repair shops for clear-coat finishing and primer sanding operations.
- Yangtze River Delta Cluster Density:Furniture export manufacturing and automotive OEM supply chains concentrate procurement in China's eastern seaboard, creating localized demand pull.
- REACH Compliance Migration:European chemical restrictions on resin hardeners are redirecting technical investment toward compliant waterborne formulations.
Market Restraints
- Alumina Price Volatility:Input cost swings for aluminum oxide abrasive grains compress margin stability for mid-tier producers.
- Roll Stock Supply Concentration:Asian substrate manufacturers dominate continuous-feed backing material, creating geographic single-source exposure.
- Silicon Carbide Substitution Pressure:Ceramic grain technologies threaten silicon carbide positioning in high-precision metal finishing applications.
Strategic Opportunities
- Dust-Free Sanding Systems:Professional contractor segments in Nordic markets present underpenetrated demand for integrated extraction-abrasive combinations.
- Robotic Sanding Line Integration:Furniture manufacturing automation creates specification opportunities for dimensionally standardized sheet products.
- IRA Clean Manufacturing Credits:US domestic production incentives support capital investment in low-emission coating facilities.
Industry Challenges
- Multi-Jurisdiction Certification Overhead:Manufacturers face divergent GB standard labeling, REACH substance restrictions, and EPA silica exposure limits requiring parallel compliance tracks.
- Automotive Color Sanding Skill Shortage:Wet sanding technique proficiency gaps in collision repair labor markets constrain premium product uptake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Sandpaper Market |
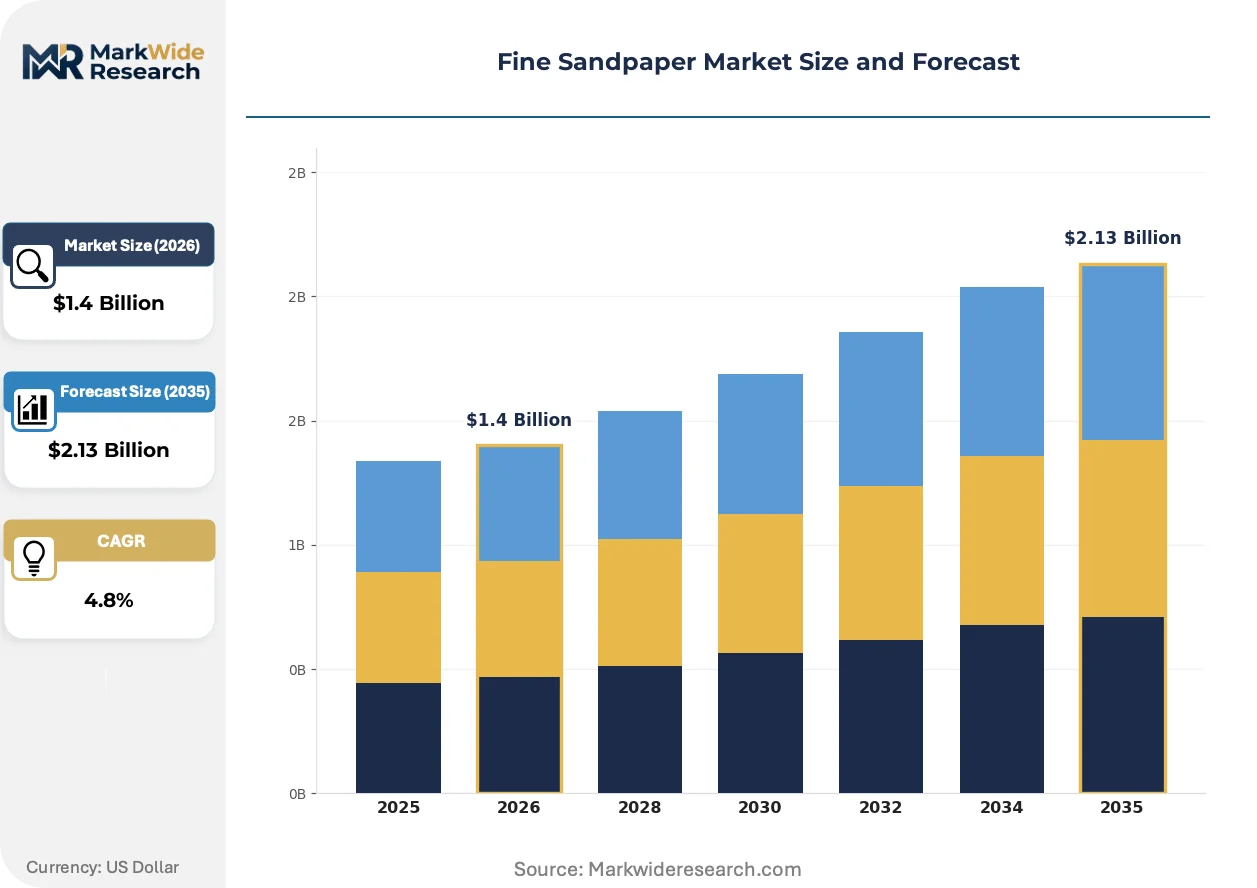
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet & Dry, Abrasive Sheets, Roll Stock, Specialty Sheets Application: Woodworking, Metal Finishing, Automotive Repair, Surface Preparation Form: Sheet, Roll, Discs, Tapered End User: DIY Enthusiasts, Professional Contractors, Industrial Users, Furniture Manufacturers |
| Companies Covered | Mirka, Deerfos, 3M, Riken, SIA Abrasives, Saint-Gobain, Klingspor, STARCKE MATADOR, Norton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Sandpaper Market Trends and Innovations
Ceramic abrasive grain technology, waterborne coating chemistry, and automated sanding system integration are compressing traditional competitive boundaries between commodity and specialty product tiers.
Ceramic alumina grains with self-sharpening microstructure are decentralizing performance advantages once exclusive to premium-priced imports. Automotive OEM paint shops and high-volume collision repair chains in Germany and Japan are adopting these grains for robotic clear-coat sanding at accelerating rates. The technology is decentralizing market power from established resin-bonding patent holders toward substrate and grain suppliers with ceramic formulation expertise.
California's South Coast Air Quality Management District volatile organic compound thresholds are forcing pressure-sensitive adhesive reformulation for disc production. Manufacturers serving aerospace and marine finishing segments must validate new low-emission chemistries without compromising bond strength under wet sanding conditions. Disc product lines destined for California distribution face the strictest compliance timeline, with reformulation costs concentrated in specialty aerospace turbine blade polishing grades.
Buyer consolidation among national automotive repair chains is compressing supplier negotiation cycles and unbundling after-sales technical support from product pricing. Independent distributors serving regional collision repair networks are losing share to direct procurement arrangements between abrasives manufacturers and multi-location repair groups. This pattern is most visible in US Sun Belt markets where private equity consolidation of repair facilities has accelerated since 2022.
Fine Sandpaper Market Segmentation
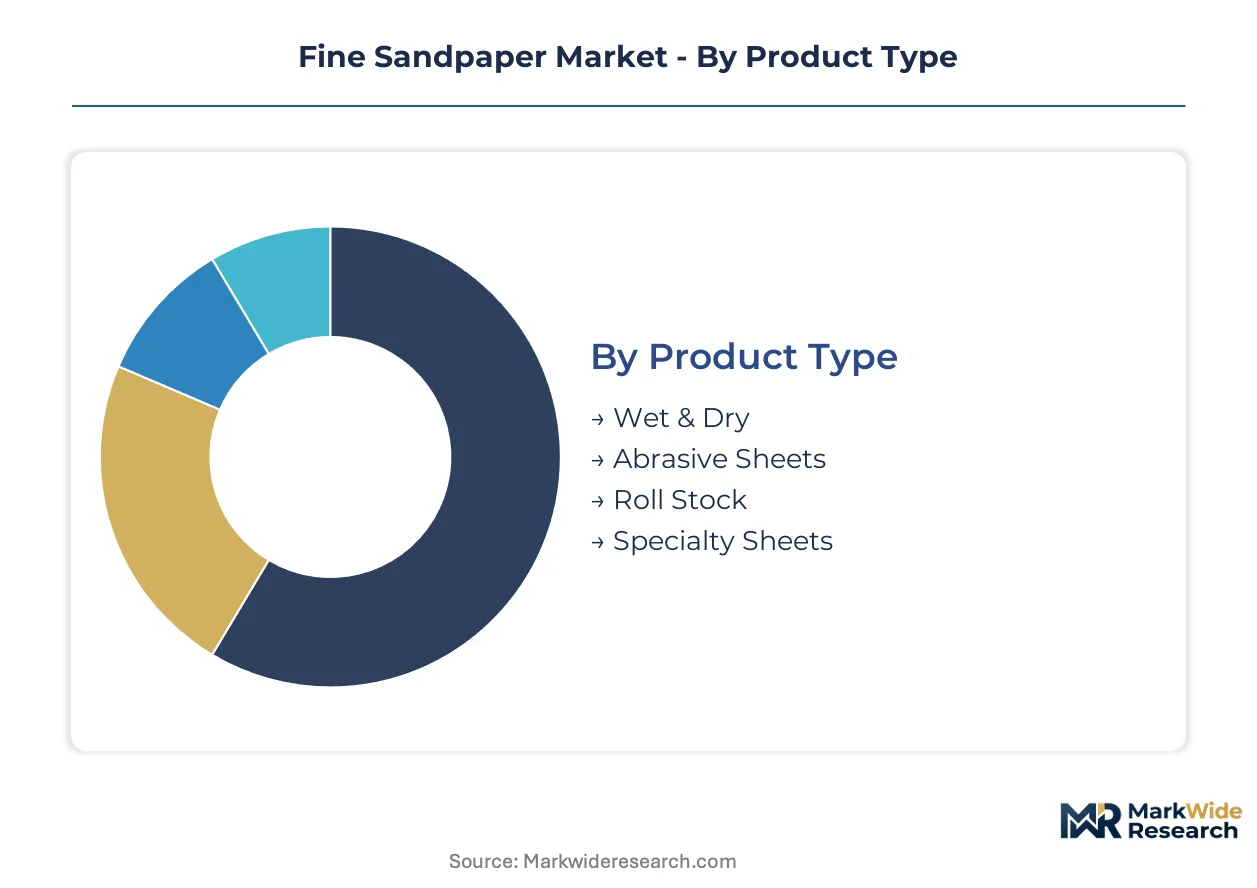
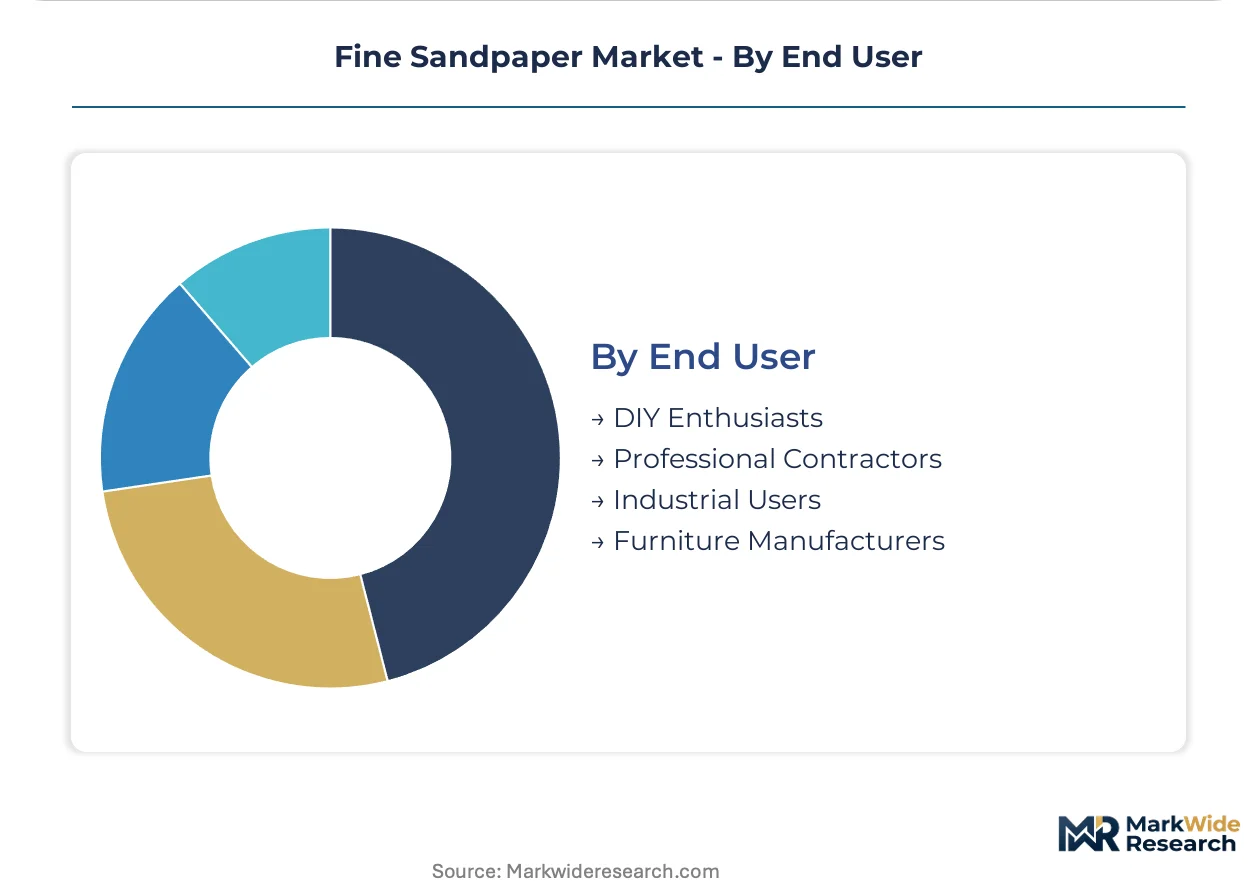
Fine sandpaper purchasing decisions split across technical performance requirements, application environment, and automation compatibility. Buyers in collision repair and furniture manufacturing prioritize different form factors and backing specifications, creating distinct procurement patterns within each segment category.
Product Type:
Buyers select product types based on lubrication needs, substrate protection requirements, and integration with automated sanding equipment.
- Wet & Dry:Waterproof latex-saturated paper enables water-borne lubrication during automotive color sanding and marine varnish leveling. Collision repair shops in California's South Coast Air Quality Management District jurisdiction favor these formulations for reduced dust exposure compliance.
- Abrasive Sheets:Standardized dimensions feed robotic sanding lines in furniture manufacturing, with P240-P800 grit ranges dominating volume. China's Yangtze River Delta export clusters specify these sheets for automated finishing operations.
- Roll Stock:Continuous-feed backing sustains industrial metal finishing operations.
- Specialty Sheets:Engineered for aerospace turbine blade polishing with ultra-fine P1500-P2500 grits.
Volume sits with Abrasive Sheets; growth tilts toward Wet & Dry.
Application:
End-use environment dictates grain selection, backing flexibility, and coating chemistry requirements.
- Woodworking:Aluminum oxide grains on A-weight paper backings handle hardwood and softwood sanding with controlled cut rates. German and Austrian cabinet manufacturers specify ceramic alumina variants for robotic sanding of engineered wood panels.
- Metal Finishing:Silicon carbide and ceramic grains address ferrous and non-ferrous substrate preparation. Japanese automotive OEM paint shops adopt self-sharpening ceramic microstructures for robotic clear-coat sanding at accelerating rates.
- Automotive Repair:Precision abrasives for clear-coat finishing and primer sanding in collision repair networks.
- Surface Preparation:Aggressive cutting grades for coating removal and substrate conditioning.
Metal Finishing commands the steepest expansion trajectory; Woodworking holds installed base dominance.
Form:
Equipment compatibility and labor efficiency drive form selection across manual and automated operations.
- Sheet:Dominates furniture manufacturing with standardized dimensions for robotic line integration.
- Roll:Sustains continuous-feed metal finishing operations with minimal changeover downtime.
- Discs:Displacing sheets in automated automotive repair environments through quick-change systems. Pressure-sensitive adhesive reformulation for California compliance adds cost concentration in specialty grades.
- Tapered:Contour sanding applications in marine and aerospace finishing.
Discs are gaining share fastest; Rolls retain industrial metal finishing anchorage.
End User:
Procurement sophistication and technical support requirements separate buyer tiers.
- DIY Enthusiasts:Price-sensitive retail channel purchasers with limited grit specification knowledge.
- Professional Contractors:Nordic markets present underpenetrated demand for dust-free sanding system integration. Finnish contractors specify extraction-compatible abrasives for silica exposure compliance.
- Industrial Users:High-volume automated operations with standardized specification requirements. EPA workplace silica exposure limits shape permissible abrasive formulations for US industrial facilities.
- Furniture Manufacturers:Robotic sanding line integration demands dimensional precision and lot consistency. China's export clusters concentrate procurement volume with direct manufacturer arrangements.
Furniture Manufacturers anchor volume concentration; Professional Contractors offer the sharpest growth angle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum oxide feedstock availability in China's Henan Province anchors the geographic foundation for fine sandpaper manufacturing. Regional demand patterns diverge sharply between automotive repair densification in mature economies and furniture export manufacturing clusters in emerging production hubs.
United States
Collision repair chain consolidation across the Sun Belt drives precision abrasive procurement through direct manufacturer arrangements. EPA workplace silica exposure limits and California's South Coast Air Quality Management District volatile organic compound thresholds force dual-track compliance for suppliers serving multiple state jurisdictions. Detroit's automotive OEM supply corridor and Houston's petrochemical equipment maintenance sector concentrate industrial-grade consumption.
Germany
Automotive OEM paint shops in Stuttgart and Munich adopt ceramic alumina grains for robotic clear-coat sanding at accelerating rates. REACH restrictions on resin hardeners redirect technical investment toward waterborne formulations across Baden-Württemberg's coated abrasives fabricators. The country's central bank financing programs support capital equipment upgrades in dust-free sanding system manufacturing.
China
Furniture export manufacturing and automotive OEM supply chains in the Yangtze River Delta concentrate procurement volume with direct manufacturer arrangements. GB standards mandate labeling of backing material composition, affecting export compliance costs for foreign suppliers. Shanghai's robotic sanding line integrators and Ningbo's marine varnish finishing yards anchor regional demand.
Japan
High-precision metal finishing applications in Nagoya's automotive component sector drive ceramic grain substitution away from silicon carbide. METI industrial standards shape permissible abrasive formulations for automated manufacturing environments. Osaka's shipbuilding maintenance clusters and Yokohama's collision repair networks sustain wet-and-dry specialty consumption.
Finland
Professional contractor segments present underpenetrated demand for dust-free sanding system integration in Nordic construction markets. Finnish silica exposure compliance requirements specify extraction-compatible abrasives for professional contractor procurement. Helsinki-based distributors anchor regional supply chains for dust-free system rollouts across the Baltic states.
Fine Sandpaper Market Competitive Landscape
Global majors compete with regional champions across resin-bonding technology and substrate formulation capabilities. The vendor base splits between consolidated patent holders in automotive channels and fragmented specialty suppliers in aerospace finishing segments. Three archetypes dominate: technology licensors with resin-bonding patent portfolios, substrate specialists with roll stock manufacturing scale, and integrated system providers bundling abrasives with extraction equipment. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into ceramic grain formulations.
Within the technology licensor tier, 3M and Saint-Gobain occupy positions anchored by resin-bonding intellectual property and multi-brand portfolio architecture. Deerfos exemplifies the substrate specialist archetype with Asian roll stock manufacturing concentration. Mirka represents the integrated system provider model, bundling precision abrasives with dust extraction compatibility for professional contractor segments. These three companies illustrate the competitive vectors shaping procurement negotiations across automotive repair, furniture manufacturing, and industrial metal finishing channels.
| Leading Market Players |
|---|
| Mirka |
| Deerfos |
| 3M |
| Riken |
| SIA Abrasives |
| Saint-Gobain |
| Klingspor |
| STARCKE MATADOR |
| Norton |
| Others |
Pricing and Supply Chain Analysis
Captive control over ceramic grain formulation anchors Saint-Gobain's and 3M's pricing power in automotive repair channels, while outsourced substrate sourcing leaves mid-tier competitors exposed to Henan Province alumina price swings. This integration choice separates premium resin-bonding patent holders from commodity roll stock assemblers across collision repair and furniture manufacturing procurement.
Pricing Analysis
After-sales technical support unbundling from product pricing is compressing negotiation cycles for independent distributors serving regional collision repair networks. Three-tier pricing structure across premium ceramic alumina, standard silicon carbide, and economy aluminum oxide grades reflects grit precision and backing durability differentiation. Cost compression in mid-tier abrasive sheets is intensifying because buyer consolidation among national automotive repair chains demands volume discounts. DIY enthusiasts exhibit highest price sensitivity; aerospace turbine blade polishers show least sensitivity due to specification rigidity.
Supply Chain Analysis
Aluminum oxide feedstock rests on Henan Province mining operations, waterproof latex backing draws from Yangtze River Delta paper mills, and ceramic grain production hinges on Japanese and German specialty abrasive manufacturers. Raw material dependencies span bauxite ore, latex-saturated paper substrates, and phenolic resin binders. Single-source vulnerability concentrates in Asian roll stock backing where Deerfos dominates continuous-feed production. Distribution runs through direct manufacturer arrangements with furniture export clusters and automotive OEM supply chains, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fine sandpaper market is becoming a vertical-integration race where ceramic grain formulation capability determines who captures margin from robotic sanding automation. Players are pursuing backward integration into abrasive grain production to escape substrate cost volatility.
For Market Incumbents: To counter ceramic grain technology decentralization, 3M and Saint-Gobain should deepen in-house production of self-sharpening microstructure formulations while securing captive supply of Yangtze River Delta backing material through long-term offtake agreements with Deerfos. Patent defense in resin-bonding chemistry remains essential as Chinese competitors develop compliant waterborne alternatives. For New Entrants and Emerging Players: Nordic professional contractor segments present the most penetrable white-space for dust-free sanding system integration, where extraction-compatible abrasives command specification premiums. Target collision repair chains in US Sun Belt markets through direct procurement pitches emphasizing California South Coast Air Quality Management District compliance. Partner with robotic sanding line integrators in China's Yangtze River Delta to secure furniture manufacturing specification slots. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by automotive OEM supply chain consolidators seeking vertical integration into precision finishing materials. Long-term viability favors substrate specialists with ceramic grain formulation expertise and REACH-compliant coating capabilities. Watch ceramic alumina adoption rates in German and Japanese automotive OEM paint shops as the inflection signal for technology substitution away from silicon carbide.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Production | Saint-Gobain's Norton brand secures supply independence from Japanese specialty abrasive producers. |
| REACH-Compliant Waterborne Coating Transition | Reformulation investments satisfy ECHA restrictions while opening California South Coast Air Quality Management District market access. |
| Robotic Sanding Line Partnership | Direct specifications with Yangtze River Delta furniture manufacturers lock in volume through automation integration. |
| Dust-Free System Bundling | Mirka's extraction-compatible abrasives capture Nordic professional contractor procurement for silica exposure compliance. |
| Direct Procurement Channel Development | Bypassing distributors to national collision repair chains compresses margin leakage and accelerates payment cycles. |
Research Methodology
Trade association filings, customs export records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with coated abrasives plant managers, collision repair chain procurement directors, furniture manufacturing automation engineers, and distribution channel partners. Bottom-up and top-down triangulation validated volume estimates across product type, application, and regional production hub segmentation.
Bottom-up modeling built from grit-grade consumption rates in automotive repair shops and robotic sanding line throughput specifications, while top-down analysis anchored aggregate market size to bauxite processing capacity and backing material production volumes. CAGRs derived from regression against automotive OEM paint shop automation indices and furniture export manufacturing growth across the projection horizon. Modeled dimensions included wet versus dry formulation, ceramic versus silicon carbide grain chemistry, and dust-free system compatibility.
Caveats apply where REACH substance restriction expansions, EPA silica exposure limit revisions, or ceramic grain technology cost breakthroughs could materially shift the outlook. A small set of named triggers—including alumina price volatility spikes and California volatile organic compound threshold enforcement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Abrasive Grains Market
Abrasives
Abrasive Rolls Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Australia Abrasives Market
Abrasives
Sandblaster Market
Abrasives
Abrasive Base Paper Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Coated Abrasives Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Bonded Abrasive Market
Abrasives
North America Abrasives Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Polishing Chemicals Market