
 Synthetic Abrasives Market | 2026-2036
Synthetic Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Abrasives Market Analytics
The capital-intensity divergence between integrated refractory producers and specialized abrasive finishers is redrawing competitive boundaries in this market. Saint-Gobain Abrasives leverages captive fused alumina capacity across European and North American kiln networks. Fujimi Incorporated anchors its position through precision grading technology serving semiconductor wafer polishing requirements. Robert Bosch GmbH competes via direct channel control into professional power tool ecosystems, locking in recurring coated abrasive demand.
Synthetic abrasives are engineered crystalline or ceramic materials—aluminum oxide, silicon carbide, cubic boron nitride, and synthetic diamond—produced through electric arc fusion, chemical vapor deposition, or high-pressure high-temperature synthesis, then graded to precise mesh or micron sizes for controlled material removal. These materials serve primary industrial functions of dimensioning, surface preparation, and finishing across metalworking, electronics, and construction workflows. Alumina formulations occupy the largest volume position due to cost-performance balance in general grinding and cutting applications, while cubic boron nitride and synthetic diamond command premium margin pools in superhard precision machining. Coated abrasives sustain faster growth trajectories than bonded forms, driven by consumable replacement cycles in automated sanding and polishing lines across automotive and electronics end uses.
EPA particulate matter standards and OSHA permissible exposure limits for respirable crystalline silica directly constrain conventional abrasive formulation and workplace deployment in the United States. REACH registration requirements and ECHA substance restrictions in Europe accelerate substitution toward engineered ceramic grains with lower toxicity profiles. Stakeholders must monitor evolving MEE air quality enforcement in China and align product portfolios with tightening regional hazard classifications.
Market Dynamics
REACH compliance in Europe is compressing permissible silica content in conventional abrasives, forcing manufacturers toward engineered ceramic alternatives and redrawing raw material sourcing patterns across the value chain.
Growth Catalysts
- Electric vehicle powertrain finishing:Automotive OEMs require precision abrasives for electric motor laminations and battery housing surfaces. This demand concentrates in Germany's automotive manufacturing belt.
- Semiconductor wafer polishing:Advanced logic and memory chip fabrication drives consumption of sub-micron graded alumina and ceria formulations. Taiwan's foundry cluster anchors this pull.
- China's Yangtze River Delta expansion:Toolmaking and electronics fabrication clusters in Shanghai, Suzhou, and Ningbo expand bonded and coated abrasive consumption for precision machining workflows.
Market Restraints
- Fused alumina energy costs:Electric arc furnace operations consume 3,000-4,500 kWh per ton of brown fused alumina. European electricity pricing volatility threatens margin stability at integrated refractory producers.
- Bauxite supply concentration:High-grade calcined bauxite for white fused alumina production concentrates in Guizhou and Shanxi provinces. Geopolitical friction or export licensing shifts disrupt feedstock security.
- Synthetic diamond HPHT capacity limits:High-pressure high-temperature synthesis requires specialized cubic press fleets. Chinese equipment makers control 70% of global press manufacturing, creating equipment access bottlenecks.
Strategic Opportunities
- India's PLI-linked manufacturing:Production-linked incentive schemes for electronics and automotive components expand precision machining capacity in Tamil Nadu and Karnataka. Abrasive suppliers can anchor local grading and coating operations.
- Recyclable engineered ceramic grains:Regenerable sol-gel ceramic abrasives reduce lifetime cost for automated grinding lines. Japanese machine tool builders are piloting closed-loop abrasive recovery systems.
- MEE air quality enforcement:China's Ministry of Ecology and Environment tightens particulate emissions standards for abrasive manufacturing. First-movers with wet classification and baghouse filtration capture licensing advantages.
Industry Challenges
- Precision grading talent scarcity:Sub-micron particle size distribution control requires specialized metrology and process engineering. Germany's technical universities and Japan's abrasive research institutes produce limited graduate pipelines.
- ISO 9001 and IATF 16949 certification timelines:Automotive supplier qualification cycles extend 18-24 months for new abrasive formulations. Smaller finishers struggle to fund parallel certification tracks for multiple OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Abrasives Market |
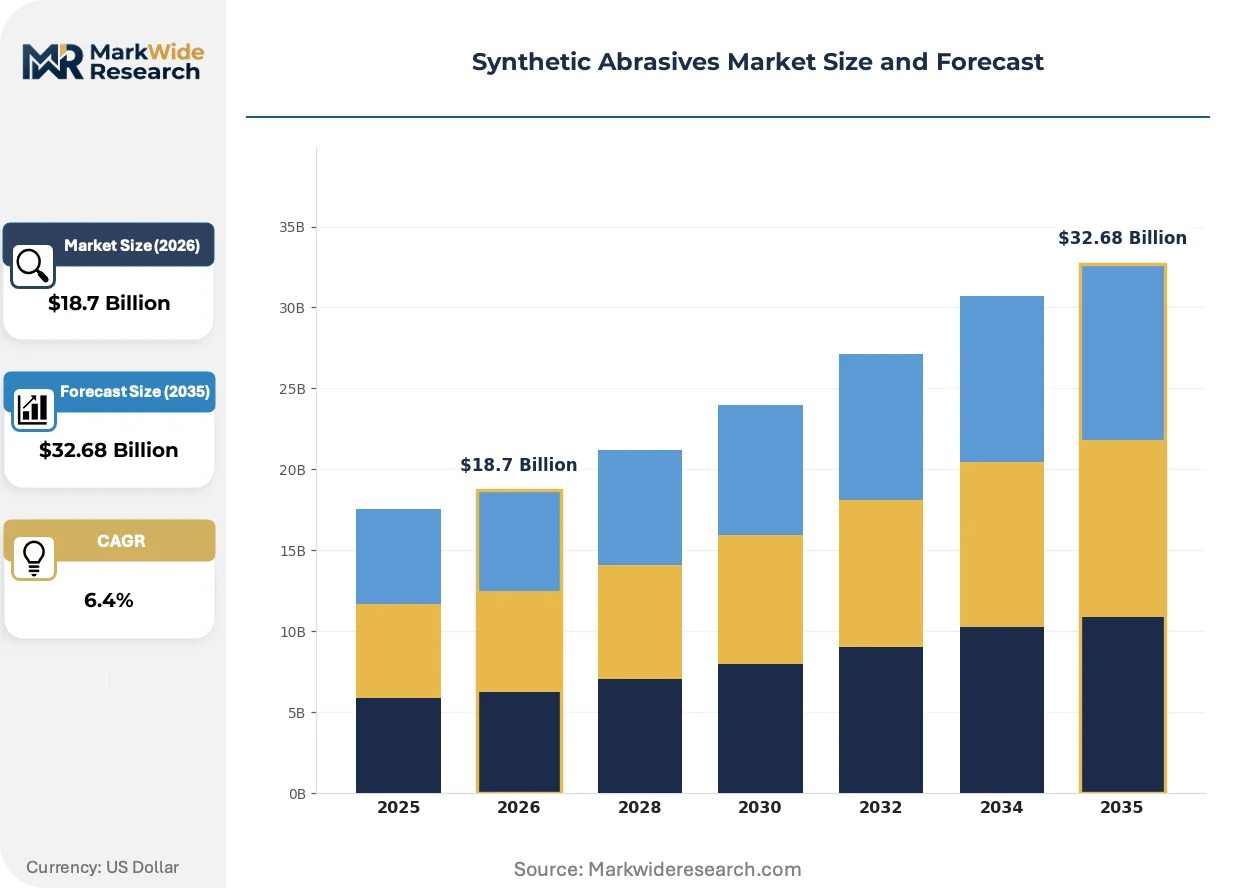
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Silicon Carbide, Cubic Boron Nitride, Diamond End Use Industry: Aerospace, Automotive, Construction, Electronics Form: Coated, Bonded, Non-Woven, Loose Abrasives Application: Grinding, Cutting, Polishing, Sanding |
| Companies Covered | 3M Company, Saint-Gobain Abrasives, Tyrolit Group, Fujimi Incorporated, Mirka Ltd., Klingspor AG, Abrasive Technology, Inc., Robert Bosch GmbH, Asahi Diamond Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Abrasives Market Evolving Landscape
Precision grading technology and regulatory toxicity thresholds are fragmenting the abrasive value chain into premium precision tiers and commodity volume pools.
Sol-gel engineered ceramic grains are bifurcating the market between high-performance precision applications and conventional fused mineral grinding. Automotive powertrain manufacturers in Germany and Japan specify these grains for camshaft and crankshaft finishing where dimensional tolerance demands sub-micron consistency. The technology is bifurcating supplier tiers, separating captives with in-house sol-gel capacity from merchant fused mineral blenders locked in price competition.
REACH Annex XVII restrictions on respirable crystalline silica are tightening permissible exposure limits across European abrasive manufacturing and workplace deployment. Formulators must substitute engineered ceramic grains for conventional silica-containing minerals in bonded wheels and coated papers. Coated abrasive producers in Italy and Spain face reformulation costs and supply chain requalification cycles.
Direct specification relationships between automotive OEMs and abrasive formulators are displacing traditional distributor channels for precision finishing applications. BMW, Volkswagen, and Toyota now mandate approved abrasive lists for tier-one machining contractors. This concentration is most visible in Germany's Mittelstand machine tool sector, where single-source abrasive agreements lock out secondary suppliers.
Synthetic Abrasives Market Segmentation
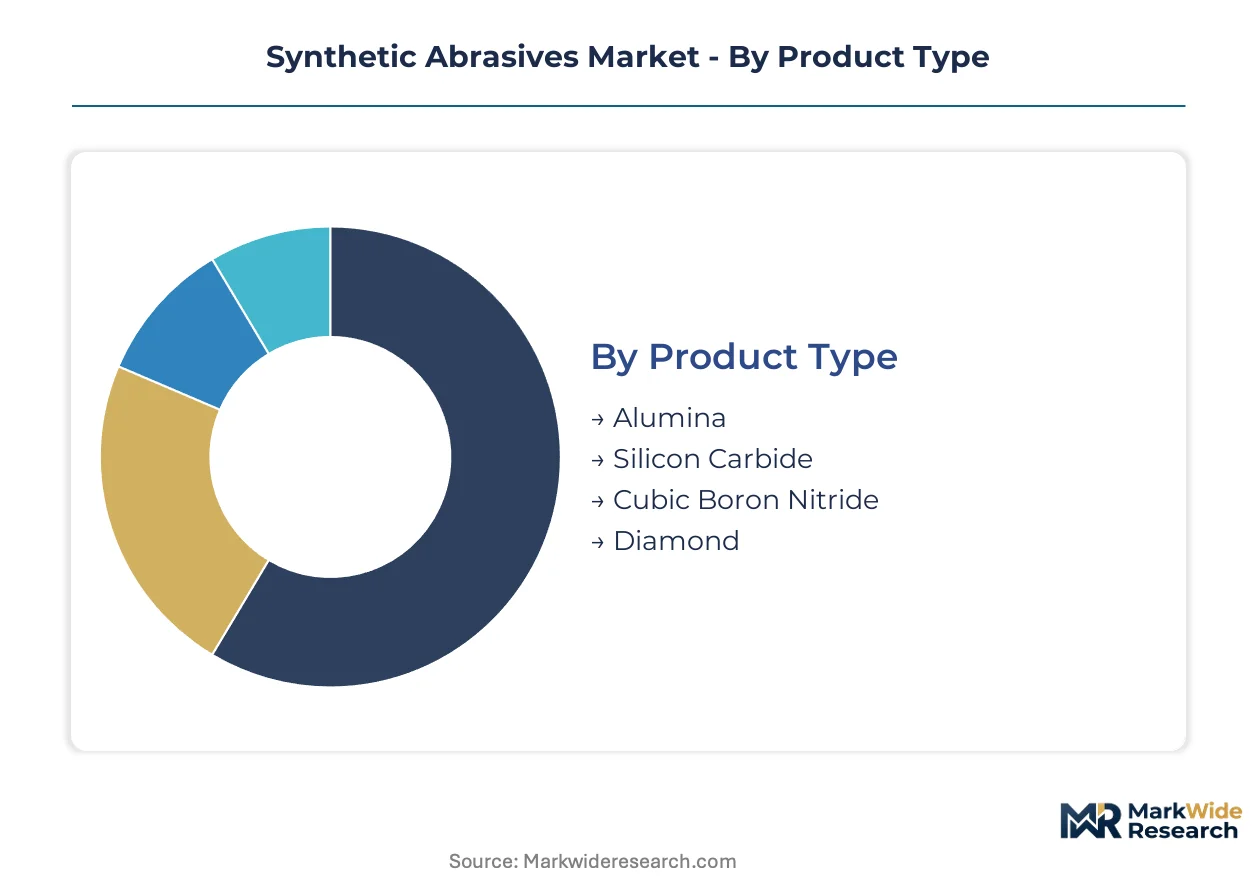
Synthetic abrasives fragment into distinct performance tiers based on crystalline hardness, thermal stability, and precision grading requirements. Each segmentation axis reveals divergent margin structures and competitive dynamics that reshape supplier positioning across industrial end uses.
Product Type:
Margin pools concentrate in superhard precision materials where synthesis complexity creates supply scarcity and pricing power.
- Alumina:Fused aluminum oxide dominates volume through electric arc furnace production of brown and white variants. General grinding applications in Germany's automotive belt absorb the largest share, though energy cost volatility at European kiln networks compresses producer margins.
- Silicon Carbide:Produced through Acheson furnace reduction of silica sand and petroleum coke, this material commands premium positioning in semiconductor wafer slicing and photovoltaic ingot cutting. Taiwan's foundry cluster drives specification-grade demand for green silicon carbide with controlled purity profiles.
- Cubic Boron Nitride:Second-hardest known material after diamond, synthesized under high-pressure high-temperature conditions for precision machining of hardened steels.
- Diamond:Synthetic monocrystalline and polycrystalline forms produced via HPHT and chemical vapor deposition for ultra-precision grinding and polishing.
The dominant share belongs to alumina formulations, while cubic boron nitride is closing the gap fastest through automotive powertrain specification.
End Use Industry:
Application intensity varies sharply by sector, with precision tolerances and surface finish requirements dictating abrasive grade selection.
- Aerospace:Superalloy turbine blade finishing and composite material trimming demand engineered ceramic grains with controlled fracture properties. Rolls-Royce and GE Aviation specifications in the UK and US mandate qualified abrasive lists for tier-one suppliers.
- Automotive:EV powertrain components—motor laminations, battery housings, and inverter substrates—require sub-micron precision abrasives. OEMs in Germany and Japan now bypass distributors to specify approved formulations directly.
- Construction:Concrete surface preparation and masonry cutting absorb commodity-grade fused minerals with lower margin profiles.
- Electronics:Semiconductor wafer polishing and display glass edge grinding consume sub-micron graded alumina and ceria formulations.
Automotive applications command the highest value per ton, while electronics is expanding most quickly through foundry capacity additions.
Form:
Product configuration determines replacement frequency and channel economics across industrial workflows.
- Coated:Paper and cloth backing with resin-bonded abrasive grains serve automated sanding lines in automotive finishing and electronics fabrication. Consumable replacement cycles generate recurring revenue streams that attract distributor investment.
- Bonded:Vitrified or resinoid wheels for precision grinding and cutting operations in toolmaking and metalworking clusters. China's Yangtze River Delta manufacturing corridor anchors bonded wheel consumption for CNC machining centers.
- Non-Woven:Nylon fiber matrices impregnated with abrasive grains for surface conditioning and deburring without substrate damage.
- Loose Abrasives:Free-flowing grains for blasting, mass finishing, and lapping applications with minimal value-added processing.
Coated formats sustain the steepest expansion trajectory through automation adoption, while bonded wheels retain the largest installed base.
Application:
Process type dictates grain morphology, bond chemistry, and operational parameters that segment supplier capabilities.
- Grinding:Precision dimensioning of hardened components requires friable ceramic grains that fracture to expose fresh cutting edges. Germany's Mittelstand machine tool sector specifies sol-gel engineered grains for camshaft and crankshaft finishing.
- Cutting:Thin bonded wheels and coated belts for severing operations prioritize grain retention and thermal dissipation. Construction and metal fabrication absorb volume here with lower specification barriers.
- Polishing:Sub-micron particle size distributions for surface finish improvement in semiconductor and optical applications.
- Sanding:Coated abrasive belts and discs for material removal and surface preparation across woodworking and automotive refinishing.
Grinding captures the dominant value share, while polishing is gaining share fastest through semiconductor wafer output expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in synthetic abrasives tilt toward net-exporting kiln networks in China and integrated European refractory producers, while precision-grading demand concentrates in import-dependent semiconductor fabrication clusters across East Asia and Western Europe.
China
Guizhou and Shanxi provinces supply high-grade calcined bauxite for white fused alumina, anchoring the Yangtze River Delta manufacturing corridor where Shanghai, Suzhou, and Ningbo toolmaking clusters expand bonded abrasive consumption. MEE air quality enforcement tightens particulate emissions standards, advantaging first-movers with wet classification and baghouse filtration systems.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify precision abrasives directly for EV powertrain finishing, bypassing traditional distributor channels. REACH Annex XVII restrictions on respirable crystalline silica force reformulation toward engineered ceramic grains. The Mittelstand machine tool sector around Stuttgart and Munich anchors sol-gel ceramic grain specification for camshaft and crankshaft workflows.
United States
EPA particulate matter standards and OSHA permissible exposure limits for respirable crystalline silica constrain conventional abrasive formulation and workplace deployment. Aerospace superalloy finishing in the Pacific Northwest and Southeast automotive supplier parks drive specification-grade demand. Electric arc furnace energy costs for brown fused alumina production face pricing volatility threats.
Japan
Semiconductor wafer polishing requirements in the Kyushu and Kansai regions consume sub-micron graded alumina and ceria formulations. METI industrial standards guide precision grading metrology investment. Japanese machine tool builders pilot closed-loop abrasive recovery systems for regenerable sol-gel ceramic grains in the Chubu and Kanto manufacturing belts.
India
PLI-linked manufacturing schemes for electronics and automotive components expand precision machining capacity in Tamil Nadu and Karnataka. CDSCO and BIS regulatory alignment accelerates supplier qualification timelines. Abrasive suppliers anchor local grading and coating operations to serve Bengaluru's electronics fabrication and Chennai's automotive component clusters.
Synthetic Abrasives Market Competitive Landscape
Concentration sits with integrated refractory producers and specialized precision finishers, creating a tiered structure where captive fused mineral capacity competes against merchant grading technology. The market fragments across three strategic archetypes: European kiln-network operators with backward bauxite integration, Japanese precision-grading specialists serving semiconductor workflows, and German channel-integrated tool system suppliers. Dominant competitive moves include geographic expansion into India's PLI-linked manufacturing zones and technology licensing for sol-gel ceramic grain synthesis.
Within the integrated refractory tier, Saint-Gobain Abrasives and Robert Bosch GmbH exemplify divergent positioning—one anchored to captive fused alumina capacity across European and North American kiln networks, the other competing via direct channel control into professional power tool ecosystems. Fujimi Incorporated occupies a precision-grading specialist position, representing the semiconductor-facing archetype where sub-micron particle size distribution capabilities create supplier scarcity.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain Abrasives |
| Tyrolit Group |
| Fujimi Incorporated |
| Mirka Ltd. |
| Klingspor AG |
| Abrasive Technology, Inc. |
| Robert Bosch GmbH |
| Asahi Diamond Industrial Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for sub-micron precision-graded abrasives concentrate pricing power with Japanese and German specialists, while commodity fused alumina cycles through spot-indexed volatility tied to Chinese kiln capacity and bauxite export licensing.
Pricing Analysis
Configured-to-order pricing for semiconductor-grade ceria formulations commands 40-60% premiums over standard fused alumina mesh products. Three-tier pricing structure across premium, standard, and economy levels separates sol-gel engineered ceramic grains from brown fused alumina and construction-grade silicon carbide. Cost compression in commodity tiers is intensifying because European electric arc furnace energy costs feed directly into brown fused alumina production economics. Tier-one automotive OEMs exhibit lowest price sensitivity due to qualified-supplier lock-in, while construction distributors face acute margin pressure from interchangeable mineral sourcing.
Supply Chain Analysis
Inventory positions for high-grade calcined bauxite rarely exceed 45 days at European refractory producers, exposing formulations to Guizhou and Shanxi supply disruptions. Raw material flows draw from Chinese bauxite calcination, Australian alumina refining, and petroleum coke streams from US Gulf Coast refineries. Single-source vulnerability concentrates in Chinese cubic press manufacturing for HPHT synthetic diamond synthesis. Distribution runs through direct OEM specification channels for precision grades and distributor networks for commodity construction abrasives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from regenerable sol-gel ceramic grains that threaten recurring revenue models in bonded and coated abrasive segments.
For Market Incumbents: Compound defensive positioning by anchoring captive sol-gel synthesis capacity and locking direct specification relationships with automotive OEMs in Germany and Japan. Backward integration into Guizhou bauxite offtake agreements secures feedstock against export licensing shifts. Certification investment in IATF 16949 and ISO 9001 parallel tracks accelerates tier-one supplier qualification timelines.
For New Entrants and Emerging Players: Lead with precision grading capability in India's PLI-linked electronics and automotive corridors, where Tamil Nadu and Karnataka machining clusters lack local sub-micron abrasive supply. Target semiconductor wafer polishing formulations for Bengaluru's foundry ecosystem. Anchor go-to-market strategy through technical service partnerships with Japanese machine tool builders piloting closed-loop abrasive recovery.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because precision grading talent scarcity and 18-24 month automotive certification cycles create durable moats for specialized finishers. Acquisition targets center on Japanese or German sub-micron metrology specialists with existing OEM approval lists. Monitor MEE air quality enforcement intensity in China as inflection signal for first-mover filtration technology adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Supply | Secures Guizhou and Shanxi calcined bauxite offtake against export licensing volatility. |
| Sol-Gel Ceramic Grain Capacity Expansion | Captures automotive powertrain specification shifts away from conventional fused minerals. |
| Precision Grading Operations in India | Positions to serve PLI-linked electronics and automotive machining clusters in Tamil Nadu. |
| Closed-Loop Abrasive Recovery Systems | Aligns with Japanese machine tool builder pilots for regenerable ceramic grain reuse. |
| Direct OEM Specification Channel Development | Bypasses distributor networks where BMW and Volkswagen now mandate approved abrasive lists. |
Research Methodology
Desk research of trade flow databases, ECHA REACH registration filings, and SEC 10-K disclosures from integrated refractory producers preceded structured interviews with procurement leads at German automotive OEMs, technical directors at Japanese semiconductor equipment makers, and plant managers at Chinese fused alumina kiln networks. Primary fieldwork combined with secondary validation from customs export records and MEE air quality enforcement bulletins. Bottom-up abrasive consumption modeling triangulated against top-down manufacturing value-add estimates.
Variance decomposition across product type, end-use industry, and regional production hub dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro manufacturing indicators. Forecast inputs incorporated electric arc furnace energy cost indices for European brown fused alumina and HPHT press capacity utilization rates for synthetic diamond synthesis.
Underlying assumptions cover sustained REACH silica restriction enforcement and MEE particulate emissions compliance, with deviation risk concentrated in bauxite export licensing shifts and automotive OEM qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Tools Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Sandblaster Market
Abrasives
North America Abrasives Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Abrasive Tools Market
Abrasives
Fine Sandpaper Market
Abrasives
Grinding Wheels Market
Abrasives
Europe Abrasives Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Carborundum Market
Abrasives
Boron Carbide Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Coated Abrasives Market
Abrasives
Carbide Grinding Wheel Market