
 Tungsten Carbide Balls Market | 2026-2036
Tungsten Carbide Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Carbide Balls Market Insights
Ceramic matrix composites in high-temperature valve seats is consolidating share from traditional tungsten carbide in select energy applications. Sandvik AB leverages captive powder metallurgy capabilities to control raw material cost volatility across its precision ball portfolio. Kennametal Inc. anchors North American supply through integrated carbide recycling and repressing operations in Pennsylvania and Illinois. CERATIZIT S.A. competes on European aerospace certification density, holding multiple NADCAP-adjacent process approvals for critical flight hardware.
Tungsten carbide balls are sintered cemented carbide spheres typically comprising 85-95% tungsten carbide with a cobalt or nickel binder matrix, finished to sphericity tolerances below 0.25 micrometers for precision bearing and flow-control service. Their primary industrial purpose centers on extreme-wear environments where hardness above 90 HRA couples with corrosion resistance in drilling, grinding, and valve-actuation systems. Precision balls dominate margin pools due to superfinishing labor intensity and aerospace qualification barriers, while custom shapes capture growth from additive-manufacturing tooling and medical instrument pivots. Spherical balls sustain volume leadership across oil and gas and mining applications where standardized seat geometries prevail.
REACH substance restrictions in Europe and EPA hazardous waste rules in the United States govern cobalt binder content and spent-ball disposal pathways, directly influencing reformulation R&D toward nickel and iron binder alternatives. China's GB standards and Japan's JIS specifications create divergent dimensional tolerance regimes that fragment cross-border procurement for multinational equipment builders. Stakeholders must monitor binder-metal substitution timelines and regional certification reciprocity to avoid stranded inventory in aerospace and medical device supply chains.
Market Dynamics
Cobalt binder substitution timelines and REACH substance restrictions are fragmenting formulation strategies across precision-grade supply chains, forcing parallel qualification tracks for nickel and iron-matrix alternatives.
Growth Catalysts
- Downhole drilling precision demands:North American exploration companies specify sphericity tolerances below 0.25 micrometers for valve-actuation systems in extreme-pressure environments.
- REACH compliance deadlines:ECHA substance restrictions on cobalt content are accelerating R&D into alternative binder matrices across European aerospace certification pipelines.
- Additive manufacturing tooling expansion:Custom spherical geometries for medical instrument pivots and grinding media are opening volume channels outside traditional bearing applications.
Market Restraints
- Tungsten powder cost volatility:Concentrated upstream mining in China creates input price instability that compresses margin pools for superfinishing-intensive precision grades.
- Cobalt supply concentration:DRC-dominant raw material sourcing exposes cemented carbide producers to geopolitical disruption and ethical sourcing audit requirements.
- Ceramic matrix composite substitution:Silicon carbide and alumina-zirconia hybrids are capturing share in high-temperature valve seats above 400°C operating thresholds.
Strategic Opportunities
- India precision manufacturing expansion:BIS certification alignment with ISO 3290 standards is enabling domestic aerospace bearing supply for multinational equipment builders.
- EPA hazardous waste rule reformulation:Spent-ball disposal pathway restrictions are creating first-mover advantage for nickel-binder products in US medical device supply chains.
- Digital metrology integration:Laser interferometry and automated sphericity measurement are compressing aerospace qualification timelines from 18 to 8 months.
Industry Challenges
- Superfinishing labor scarcity:Master lapping technicians with sub-micron tolerance expertise are retiring faster than apprenticeship pipelines replenish.
- NADCAP process approval timelines:Aerospace certification density requirements demand 24-36 month validation cycles that strand working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Carbide Balls Market |
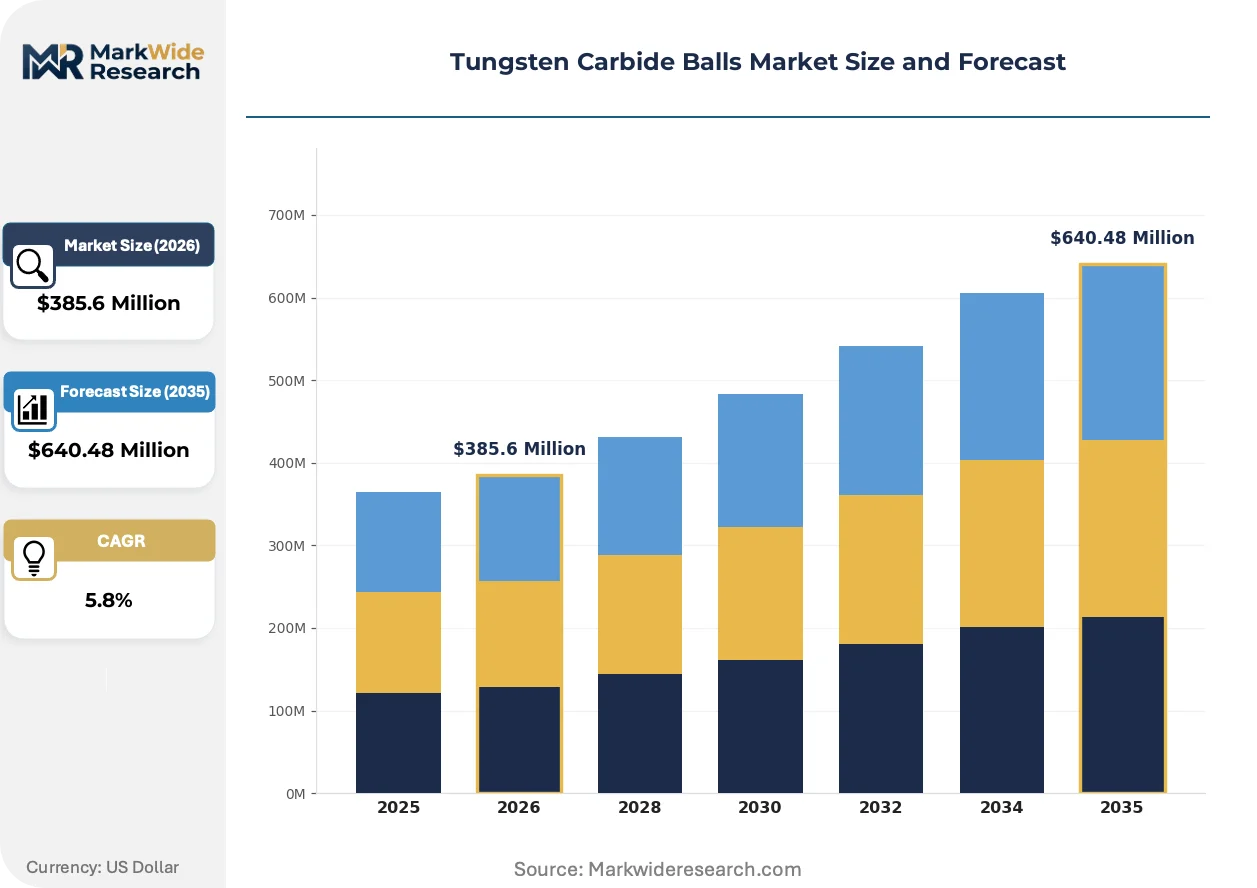
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical Balls, Cylindrical Balls, Custom Shapes, Precision Balls Size: Micro, Small, Medium, Large Application: Oil & Gas, Aerospace, Mining, Manufacturing End User: Automotive Manufacturers, Defense Contractors, Industrial Equipment, Medical Device Firms |
| Companies Covered | Sandvik AB, Kennametal Inc., SKF, CCR Products, Abbott Ball Company, Hartford Technologies, GTEK Tungsten Carbide, CERATIZIT S.A., Zhuzhou Max Precision Carbide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Carbide Balls Market Trends and Innovations
Precision finishing automation and binder-matrix diversification are compressing traditional competitive moats while expanding addressable applications beyond legacy bearing markets.
Laser-assisted lapping systems are overtaking conventional mechanical superfinishing for precision-grade spherical balls. Japanese aerospace bearing manufacturers adopted this technology at commercial scale during 2022-2024 qualification cycles. The shift is overtaking labor-intensive master technician dependencies while tightening sphericity repeatability to 0.1 micrometer bands.
REACH Annex XVII cobalt restrictions are forcing dual-track formulation development across European supply chains. ECHA sunset dates for unrestricted cobalt use in consumer-contact applications are accelerating nickel-binder validation for medical instrument pivots. German and French aerospace subcontractors are maintaining parallel inventories until NADCAP-adjacent process approvals stabilize.
Specification-driven procurement is consolidating buyer power among multinational oilfield service companies. Integrated drilling contractors now mandate material traceability from powder lot to finished ball, displacing spot-market purchasing for downhole valve components. This concentration is most visible in US Permian Basin operations where exploration companies specify single-source qualification for 10,000-unit annual contracts.
Tungsten Carbide Balls Market Segmentation
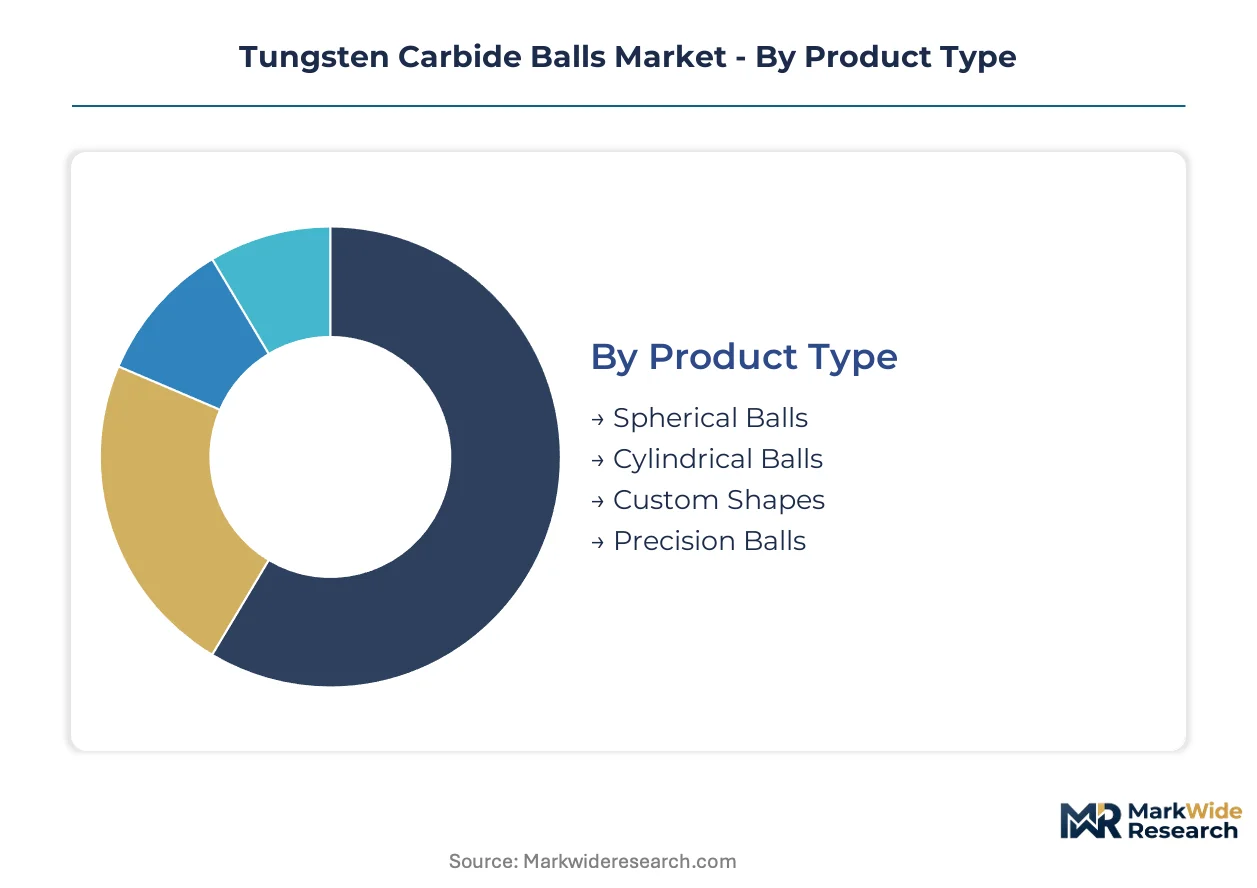
Segmentation in tungsten carbide balls reveals how formulation chemistry and finishing intensity map to divergent margin structures. Buyers sort across precision grades based on sphericity tolerance requirements and binder-metal compliance rather than commodity pricing alone.
Product Type:
Supply concentration in superfinishing capability creates tiered access to precision-grade output, with captive powder metallurgy operations controlling cost positions across spherical and custom geometries.
- Precision Balls:Finished to sub-0.25 micrometer sphericity tolerances with cobalt or nickel binder matrices. Demand concentrates in German and Japanese aerospace bearing supply chains where NADCAP-adjacent process approvals govern procurement. REACH cobalt restrictions are accelerating parallel nickel-binder qualification tracks that fragment inventory strategies.
- Spherical Balls:Standardized cemented carbide spheres comprising 85-95% tungsten carbide for extreme-wear valve-actuation systems. North American oilfield service companies in the Permian Basin specify material traceability from powder lot to finished ball for downhole drilling contracts.
- Custom Shapes:Additive-manufacturing tooling and medical instrument pivot geometries outside legacy bearing markets.
- Cylindrical Balls:Grinding media and flow-control applications with lower sphericity requirements.
Today's leader: Precision Balls. Tomorrow's challenger: Custom Shapes.
Size:
Cost tier separation follows labor intensity in superfinishing, with micro-scale production requiring master technician expertise that outpaces apprenticeship pipeline replenishment.
- Micro:Sub-millimeter diameters for medical instrument pivots and miniature bearing assemblies. Japanese manufacturers adopted laser-assisted lapping systems during 2022-2024 qualification cycles to compress sphericity repeatability into 0.1 micrometer bands.
- Large:Heavy-section spheres for mining grinding media and oilfield valve seats where standardized geometries prevail. Chinese tungsten powder cost volatility compresses margin pools most severely at this scale where material intensity peaks.
- Small:Precision bearing components for aerospace and industrial equipment.
- Medium:General industrial flow-control and actuation systems.
Volume concentrates in Large. Value concentrates in Micro.
Application:
Application-driven procurement consolidates buyer power among integrated drilling contractors and multinational equipment builders with divergent certification requirements.
- Aerospace:Flight-critical bearing applications demanding 90+ HRA hardness with corrosion resistance. German and French subcontractors maintain parallel cobalt and nickel-binder inventories until ECHA sunset dates stabilize qualification pathways.
- Oil & Gas:Downhole valve-actuation systems in extreme-pressure environments. Exploration companies specify single-source qualification for 10,000-unit annual contracts with full material traceability mandates.
- Mining:Grinding media and wear-resistant flow-control components.
- Manufacturing:General industrial tooling and additive-manufacturing support equipment.
Certification barriers protect Aerospace margins. Procurement consolidation squeezes Oil & Gas pricing.
End User:
Customer type determines compliance burden intensity, with medical device and defense procurement subject to spent-ball disposal pathway restrictions that favor nickel-binder reformulation.
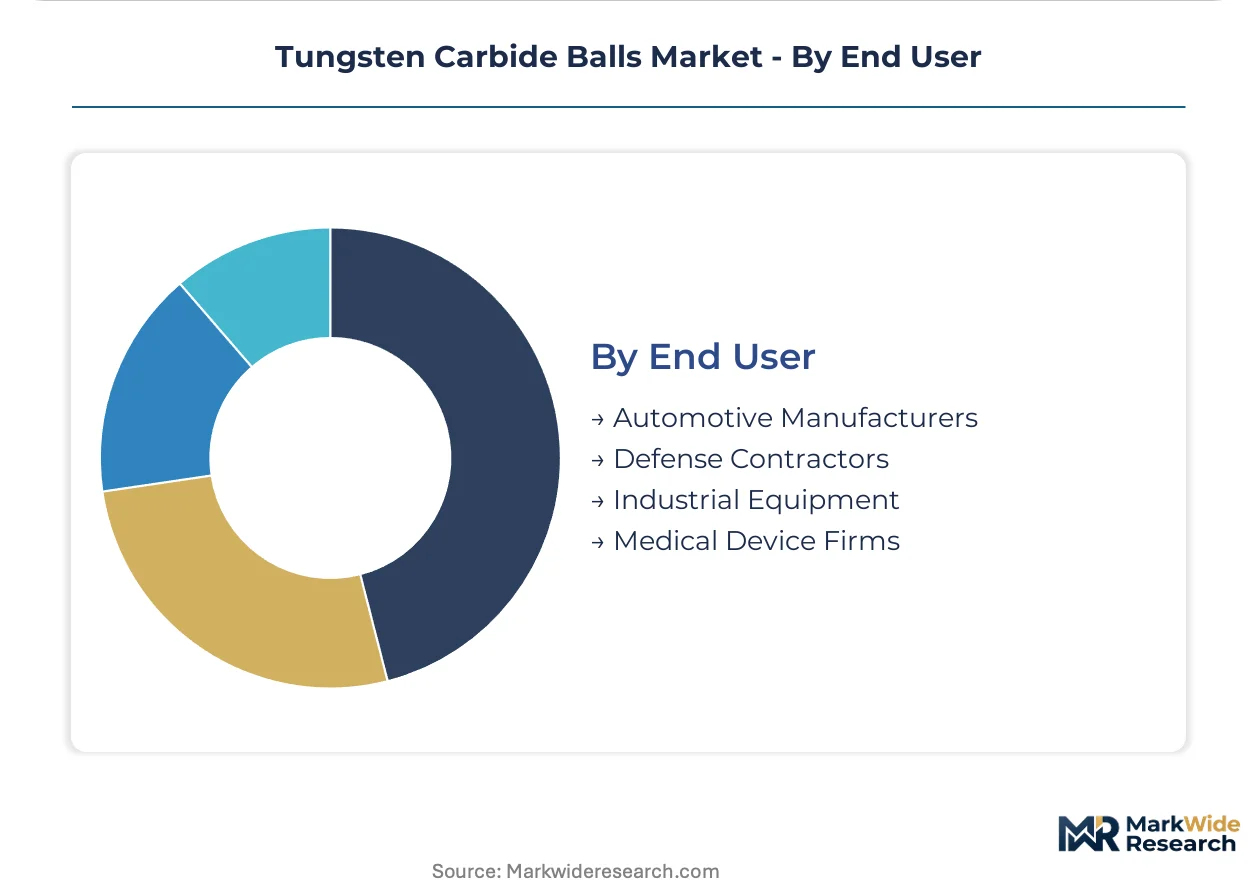
- Medical Device Firms:Surgical instrument pivots and implantable component bearings. EPA hazardous waste rule reformulation creates first-mover advantage for nickel-binder products in US supply chains.
- Defense Contractors:Critical flight hardware and precision weapon systems. NADCAP process approval timelines demand 24-36 month validation cycles that strand working capital and favor incumbent suppliers.
- Automotive Manufacturers:Precision transmission and engine component bearings.
- Industrial Equipment:General machinery and flow-control system builders.
Compliance intensity peaks with Medical Device Firms. Volume scale peaks with Industrial Equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin drilling corridor anchors North American precision-grade demand, with integrated contractors mandating material traceability from powder lot to finished ball for 10,000-unit annual valve-actuation contracts.
United States
Exploration companies in Texas and New Mexico specify sphericity tolerances below 0.25 micrometers for extreme-pressure downhole systems. EPA hazardous waste rules govern spent-ball disposal pathways and favor nickel-binder reformulation in medical device supply chains. Pennsylvania and Illinois host integrated carbide recycling and repressing operations serving domestic aerospace qualification pipelines.
Germany
Aerospace bearing demand concentrates among Baden-Württemberg and Bavaria subcontractors serving Airbus and MTU Aero Engines supply chains. ECHA REACH Annex XVII cobalt restrictions accelerate parallel nickel-binder validation tracks that fragment inventory strategies. Stuttgart and Munich industrial clusters maintain dual certification pipelines until NADCAP-adjacent process approvals stabilize.
Japan
Precision manufacturers in the Chubu region around Nagoya adopted laser-assisted lapping systems during 2022-2024 qualification cycles. METI industrial standards and JIS specifications create divergent dimensional tolerance regimes for cross-border procurement. Kansai-based aerospace bearing producers compress sphericity repeatability to 0.1 micrometer bands through automated superfinishing.
China
Zhuzhou and Zhengzhou cemented carbide clusters face tungsten powder cost volatility from concentrated domestic mining. GB standards for dimensional tolerance diverge from ISO 3290 specifications, complicating export qualification for multinational equipment builders. MIIT industrial policy supports captive powder metallurgy capabilities to control input price instability.
India
BIS certification alignment with ISO 3290 standards enables domestic aerospace bearing supply for multinational equipment builders. Karnataka and Tamil Nadu precision manufacturing expansion targets medical instrument pivot applications. CDSCO medical device regulations and DGFT export promotion schemes accelerate nickel-binder product qualification timelines.
Tungsten Carbide Balls Market Competitive Landscape
Global majors compete with regional champions across certification density and captive powder metallurgy capabilities. Market structure tiers between integrated cemented carbide producers with in-house recycling operations and specialized precision finishing houses. Three archetypes dominate: European aerospace-certified specialists, North American oilfield-anchored integrators, and Chinese scale-driven powder metallurgy players. Competitive moves center on backward integration into tungsten powder supply and digital metrology adoption to compress qualification timelines.
Among European aerospace-certified specialists, CERATIZIT S.A. exemplifies the NADCAP-adjacent process approval archetype, while Sandvik AB represents captive powder metallurgy control. Kennametal Inc. anchors the North American integrated recycling model. These three occupy positions across the tiered competitive map without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Sandvik AB |
| Kennametal Inc. |
| SKF |
| CCR Products |
| Abbott Ball Company |
| Hartford Technologies |
| GTEK Tungsten Carbide |
| CERATIZIT S.A. |
| Zhuzhou Max Precision Carbide |
| Others |
Pricing and Supply Chain Analysis
Tungsten powder cost volatility from concentrated Chinese mining feeds through three distinct pricing tiers downstream, with superfinishing labor intensity separating precision-grade aerospace bearings from standardized oilfield valve components. Buyers in the Permian Basin negotiate single-source contracts with full material traceability mandates, while European aerospace subcontractors absorb dual-inventory carrying costs during parallel cobalt and nickel-binder qualification tracks.
Pricing Analysis
Input-cost pass-through from tungsten powder and cobalt binder metals dominates pricing formation across all grades. Three-tier pricing structure across precision, standard, and industrial levels separates NADCAP-certified aerospace bearings from general oilfield valve balls, with certification density and superfinishing labor as primary differentiation drivers. Pricing pressure stems from Chinese tungsten concentrate export volatility and DRC cobalt supply disruptions, compressing margins most severely at the large-diameter grinding media tier. Oilfield service companies exhibit highest price sensitivity due to procurement consolidation, while medical device firms accept premium positioning for EPA-compliant nickel-binder alternatives.
Supply Chain Analysis
Reverse-logistics flows for spent carbide balls anchor closed-loop supply economics, with Kennametal's Pennsylvania and Illinois repressing operations and Sandvik's captive powder metallurgy networks capturing value from end-of-life material recovery. Upstream concentration centers on China for tungsten mining, the Democratic Republic of Congo for cobalt, and Germany for precision finishing equipment. Raw material dependencies span tungsten ore concentrates, cobalt metal cathodes, and nickel powder for binder-matrix alternatives. Single-source vulnerability in DRC cobalt exposes formulation strategies to ethical sourcing audit disruptions and geopolitical interruption. Distribution runs through integrated cemented carbide producers with in-house recycling capabilities rather than spot-market merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tungsten Carbide Balls Market functions as a stable compounder anchored by irreplaceable wear-resistance performance in extreme-pressure drilling and flight-critical bearing applications where material substitution remains technically constrained.
For Market Incumbents: Lock in aerospace certification density through accelerated NADCAP-adjacent process approvals before ECHA REACH sunset dates stabilize nickel-binder qualification pathways. Defend against ceramic matrix composite substitution in high-temperature valve seats by deepening captive tungsten powder supply relationships in Zhuzhou and Zhengzhou clusters. Prioritize laser-assisted lapping automation to offset master technician retirement waves.
For New Entrants and Emerging Players: EPA hazardous waste rule reformulation in the United States opens a window for nickel-binder product positioning in medical device supply chains underserved by incumbent cobalt-dominant portfolios. Target micro-scale precision manufacturing for surgical instrument pivots in Karnataka and Tamil Nadu where BIS certification alignment with ISO 3290 standards lowers aerospace entry barriers. Pursue digital metrology integration partnerships with Japanese Chubu-region equipment suppliers to compress qualification timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where superfinishing labor scarcity and 24-36 month NADCAP validation cycles strand working capital at sub-scale precision finishing houses. Long-term viability favors integrated cemented carbide producers with captive powder metallurgy and established aerospace customer relationships. Monitor ECHA cobalt restriction enforcement timelines and EPA medical device disposal rule implementation as inflection indicators for binder-matrix substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Powder Supply | Captive mining and powder metallurgy operations in Zhuzhou insulate margin pools from Chinese export volatility. |
| Laser-Assisted Lapping System Deployment | Japanese aerospace bearing manufacturers compress sphericity repeatability to 0.1 micrometer bands through automation. |
| Dual-Track Binder Qualification | Parallel cobalt and nickel-matrix validation protects European aerospace supply chains against REACH Annex XVII disruption. |
| Closed-Loop Carbide Recycling Expansion | Integrated repressing operations in Pennsylvania recover value from spent balls while meeting EPA hazardous waste mandates. |
| Digital Metrology Integration Partnership | Laser interferometry adoption compresses aerospace qualification timelines from 18 to 8 months for new entrants. |
Research Methodology
Multiple input streams — executive interviews with cemented carbide plant managers and aerospace bearing procurement leads, technical discussions with superfinishing equipment specialists, and validation with oilfield service contract managers — were reconciled against secondary sources including SEC 10-K filings from integrated producers, ECHA REACH substance restriction documentation, EPA hazardous waste rule dockets, and Japanese METI industrial standards publications. Bottom-up volume modeling across precision, spherical, and custom shape categories was cross-checked against top-down tungsten carbide consumption estimates from powder metallurgy trade data.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product grade tier, sphericity tolerance band, binder-metal composition, end-use application intensity, and regional certification cluster. CAGRs were derived from trend extrapolation of aerospace bearing demand, oilfield drilling activity indices, and medical device pivot adoption curves, calibrated against historical tungsten powder price elasticity and superfinishing labor cost trajectories.
Revisions become necessary when ECHA accelerates cobalt restriction timelines, EPA expands medical device disposal pathway restrictions, or ceramic matrix composite performance thresholds advance below 400°C operating limits. Practitioners should monitor DRC cobalt supply disruption indicators, Japanese laser-lapping equipment adoption rates, and Indian BIS certification reciprocity developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
North America Abrasives Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Grinding Wheels Market
Abrasives
Super Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Carbide Tools Market
Abrasives
Boron Carbide Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
RDP Powder Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Abrasive Cloth Market
Abrasives
New Zealand Abrasives Market
Abrasives
Chemical Deflasher Market
Abrasives
Lapping and Polishing Films Market