
 Super Abrasives Market | 2026-2036
Super Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Super Abrasives Market Analysis
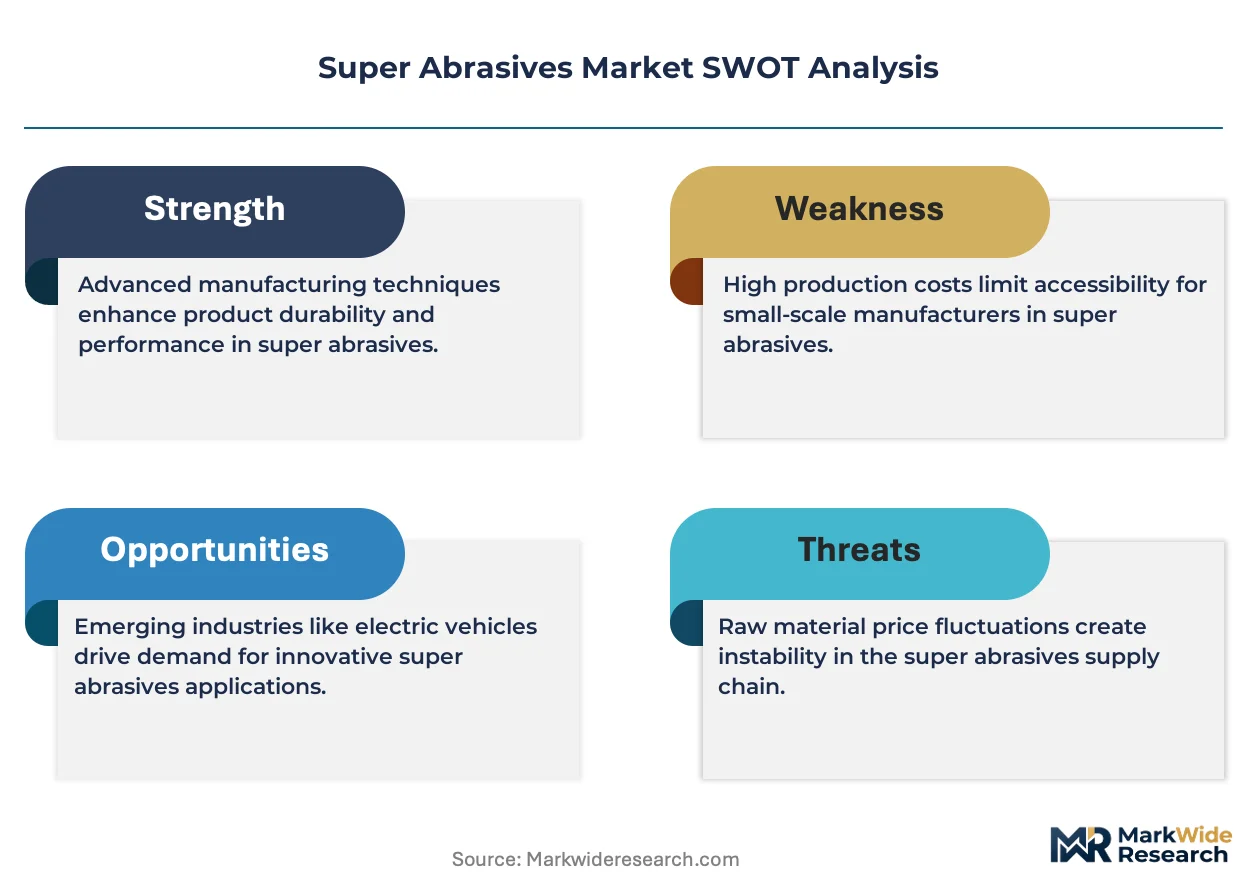
Asset-light leasing models for precision grinding equipment is tilting competitive dynamics toward firms with service networks rather than pure manufacturing scale. Saint-Gobain leverages its vitrified bond technology leadership to anchor premium positioning in aerospace contracts. Tyrolit Group sustains geographic dominance through localized production hubs that reduce logistics exposure for European automotive tier suppliers. Carborundum Universal Limited differentiates via backward integration into synthetic diamond feedstock, securing margin control across volatile raw material cycles.
Super abrasives comprise synthetic diamond and cubic boron nitride (CBN) particles bonded to grinding wheels, cutting tools, and polishing media through vitrified, resin, or metal matrices, with particle sizes typically ranging from 0.5 to 500 microns depending on finish requirements. These materials remove hardened steels, ceramics, and superalloys that conventional aluminum oxide or silicon carbide abrasives cannot process efficiently. Diamond product type segments occupy the largest value share due to unmatched hardness in non-ferrous applications, though CBN segments are displacing conventional options in ferrous precision grinding as tool life expectations rise. Electroplated technology leads in high-stock-removal cutting operations, while vitrified bond systems capture margin pools in superfinishing applications where surface roughness below Ra 0.1 micrometers defines contract awards.
EPA air quality standards and OSHA permissible exposure limits for respirable crystalline silica compel U.S. manufacturers to invest in enclosed grinding systems and engineered bond chemistries that suppress dust generation. REACH registration requirements in Europe restrict certain resin precursors, redirecting R&D toward water-based and bio-derived bond formulations. Stakeholders must monitor how dual carbon goals in China reshape synthetic diamond production energy sourcing and whether MEE enforcement accelerates consolidation among smaller electroplated tool shops.
Market Dynamics
Tightening tolerances in aerospace turbine blade finishing are compressing grinding wheel replacement cycles and elevating specification requirements across the supply base. Asset-light leasing models for precision grinding equipment are tilting competitive dynamics toward firms with service networks rather than pure manufacturing scale.
Growth Catalysts
- Aerospace tolerance compression:Engine OEMs now demand surface roughness below Ra 0.1 micrometers for hot-section components, mandating vitrified bond super abrasives in blade finishing operations.
- EU F-Gas Regulation:Manufacturers are redirecting R&D toward bonded abrasives with lower greenhouse gas footprints as the regulation phases down hydrofluorocarbon use in industrial processes.
- CBN displacement of conventional abrasives:Cubic boron nitride segments are capturing ferrous precision grinding applications as tool life expectations rise in automotive powertrain machining.
Market Restraints
- Synthetic diamond feedstock volatility:Energy-intensive high-pressure high-temperature synthesis exposes producers to electricity price swings, compressing margins during raw material cycles.
- REACH registration friction:ECHA restrictions on certain resin precursors are forcing reformulation timelines that delay product launches in European markets.
- Silicon carbide substitution in non-critical applications:Conventional abrasives retain cost advantage in rough grinding where surface finish specifications remain permissive.
Strategic Opportunities
- Water-based bond chemistry:Bio-derived formulations bypass REACH-registered precursors while opening positioning in sustainability-driven buyer segments.
- India precision machining expansion:Stuttgart and Aachen cluster expertise is transplanting to Pune and Chennai as automotive OEMs localize supply chains.
- Electroplated tool leasing:Service-based revenue models capture lifetime value from high-stock-removal cutting operations in job shop environments.
Industry Challenges
- Bond chemistry R&D talent scarcity:Vitrified and resin matrix formulation expertise concentrates among aging specialists in Germany and Japan, constraining new product development velocity.
- Enclosed grinding system capex:EPA air quality standards and OSHA permissible exposure limits for respirable crystalline silica compel capital investment in dust-suppression infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Abrasives Market |
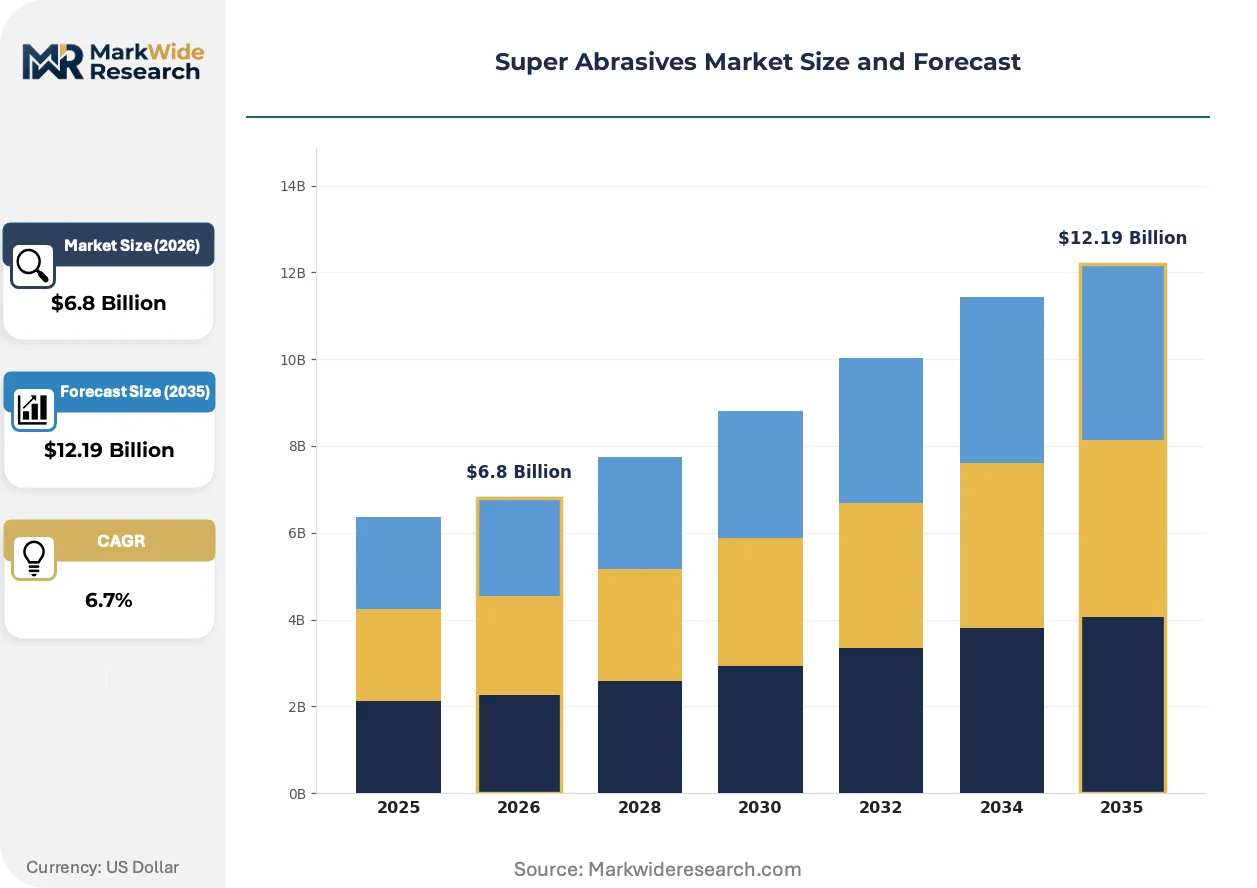
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond, CBN, Resin Bond, Metal Bond Application: Grinding, Cutting, Polishing, Drilling End User: Aerospace, Automotive Parts, Electronics, Tool Manufacturing Technology: Electroplated, Vitrified, Hybrid, Superfinishing |
| Companies Covered | Asahi Diamond Industrial Co., Ltd., Carborundum Universal Limited, 3M, Fujimi Incorporated, Hyperion Materials & Technologies, Saint-Gobain, Noritake Co., Limited, Zhengzhou Hongtuo Super Abrasive Products Co., Ltd, Tyrolit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Abrasives Market Emerging Trajectories
Process integration and environmental compliance are compressing traditional technology lifecycles while opening new specification tiers. Three developments are restructuring how value flows through the super abrasives value chain.
Hybrid vitrified-metal bond systems are collapsing the historical separation between rough grinding and superfinishing operations. Aerospace tier suppliers in Germany are adopting single-setup workflows that eliminate wheel changeover downtime. This convergence is collapsing the addressable market for standalone resin bond products in intermediate finishing stages.
REACH registration requirements are redirecting R&D investment toward water-based and bio-derived bond formulations. ECHA restrictions on specific resin precursors are accelerating reformulation timelines for European market access. Vitrified bond manufacturers with in-house ceramic chemistry capabilities are capturing specification authority as resin-dependent competitors face compliance delays.
Precision grinding equipment leasing is displacing capital purchase in European automotive supply chains. Tier suppliers around Stuttgart are unbundling after-sales service from equipment ownership, transferring utilization risk to abrasives providers. This model concentrates in Germany's precision machining cluster where asset-light strategies align with OEM just-in-sequence requirements.
Super Abrasives Market Segmentation
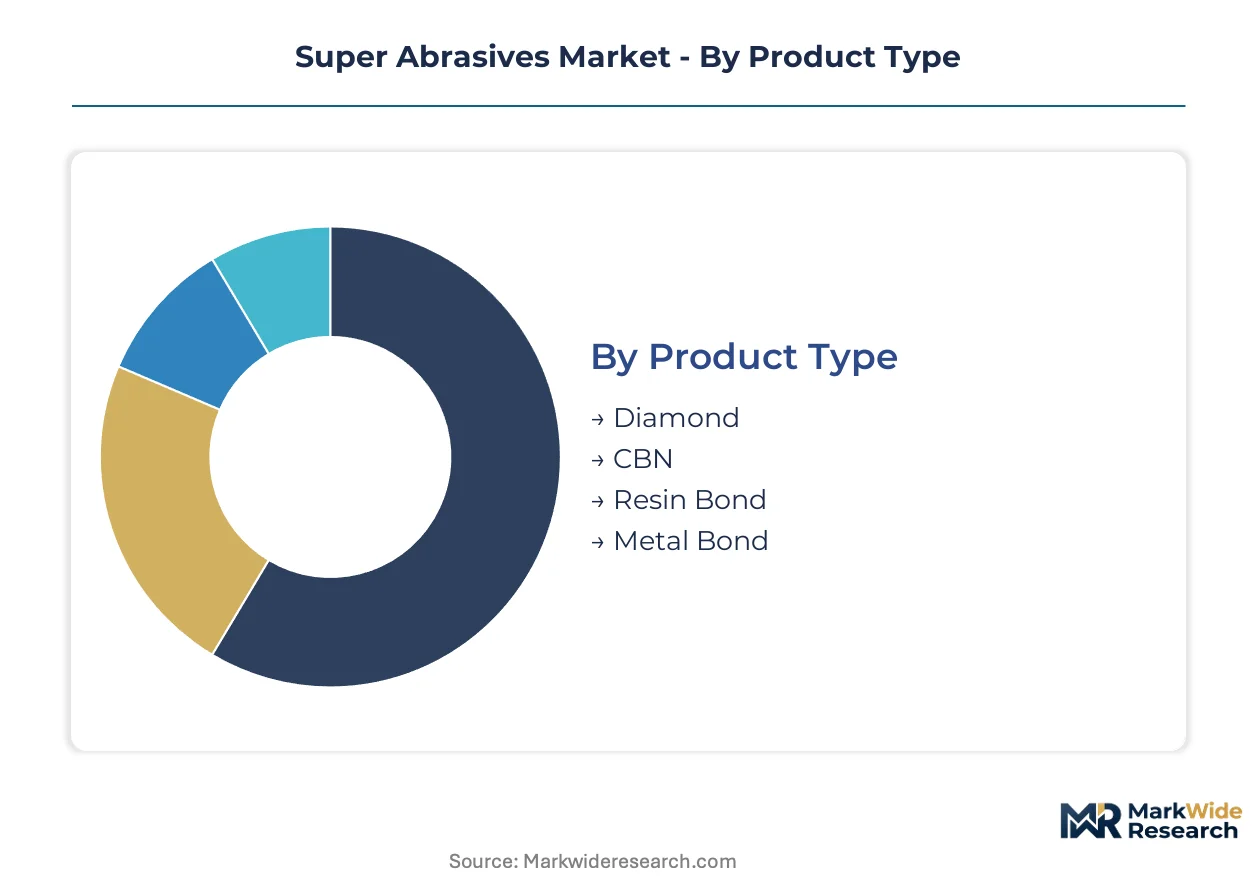
Super abrasives segmentation reveals how material properties, bonding chemistry, and finishing specifications map to distinct value pools across precision manufacturing. Product type and technology dimensions dominate margin capture, while application and end-use alignment determines contract tenure and specification authority.
Product Type:
Mature synthetic diamond formulations anchor high-volume production, while emerging bond innovations reshape competitive positioning in regulated markets.
- Diamond:Synthetic diamond particles, synthesized through high-pressure high-temperature or chemical vapor deposition methods, deliver unmatched hardness for non-ferrous grinding applications. Demand concentrates in Germany's precision machining cluster around Stuttgart, where aerospace turbine blade finishing mandates surface roughness below Ra 0.1 micrometers. EPA air quality standards and OSHA permissible exposure limits for respirable crystalline silica compel enclosed grinding system investments that favor premium diamond specifications.
- CBN:Cubic boron nitride crystals, second only to diamond in hardness, exhibit superior thermal stability in ferrous material processing. Automotive powertrain machining in Stuttgart and Aachen drives adoption as tool life expectations compress replacement cycles. EU F-Gas Regulation phases down hydrofluorocarbon use, redirecting R&D toward CBN bonded abrasives with lower greenhouse gas footprints.
- Resin Bond:Phenolic and polyimide resin matrices offer elasticity for fine finishing operations in electronics and tool manufacturing segments.
- Metal Bond:Bronze and nickel-based matrices provide durability in high-stock-removal cutting applications where wheel wear resistance defines economics.
Diamond retains volume leadership; CBN holds the steepest expansion curve as ferrous precision grinding displaces conventional abrasives.
Application:
Application segmentation tracks how stock removal rate and surface finish requirements stratify across manufacturing process stages.
- Grinding:Precision material removal operations using bonded super abrasive wheels to achieve dimensional tolerances in hardened steels, ceramics, and superalloys. Aerospace hot-section component manufacturing in Germany demands vitrified bond systems that maintain profile accuracy through extended cutting cycles. REACH registration requirements restrict certain resin precursors, accelerating reformulation toward water-based bond chemistries in European markets.
- Cutting:High-speed separation processes employing electroplated diamond and CBN tools for slotting, grooving, and cutoff operations. Job shop environments around Stuttgart adopt electroplated tool leasing models that transfer utilization risk to abrasives providers. Asset-light strategies align with automotive OEM just-in-sequence requirements.
- Polishing:Final surface refinement using fine-grain super abrasives to achieve optical-grade finishes in electronics and aerospace components.
- Drilling:Precision hole generation in advanced ceramics and composite materials using diamond-impregnated drill bits.
Grinding commands the largest addressable value pool; cutting applications are gaining share fastest through service-based revenue models.
End User:
End user segmentation reflects how specification authority and contract tenure vary across durability-critical manufacturing sectors.
- Aerospace:Engine OEMs and tier suppliers mandate super abrasives for turbine blade finishing, compressor airfoil profiling, and hot-section component manufacturing. Tightening tolerances in blade finishing compress grinding wheel replacement cycles and elevate specification requirements. Vitrified bond super abrasives dominate where surface roughness below Ra 0.1 micrometers defines contract awards.
- Automotive Parts:Powertrain machining, transmission component finishing, and bearing manufacturing drive CBN adoption for ferrous material processing. Stuttgart's precision machining cluster localizes supply chains for European automotive tier suppliers. Precision grinding equipment leasing displaces capital purchase as tier suppliers unbundle after-sales service from equipment ownership.
- Electronics:Semiconductor wafer dicing, substrate polishing, and ceramic package manufacturing employ fine-grain diamond abrasives.
- Tool Manufacturing:Cutting tool regrinding and precision die finishing operations utilize both diamond and CBN specifications.
Aerospace commands premium pricing authority; automotive parts segments are expanding most quickly through localized production hub strategies.
Technology:
Technology segmentation distinguishes between stock removal efficiency and surface finish precision in bonding system design.
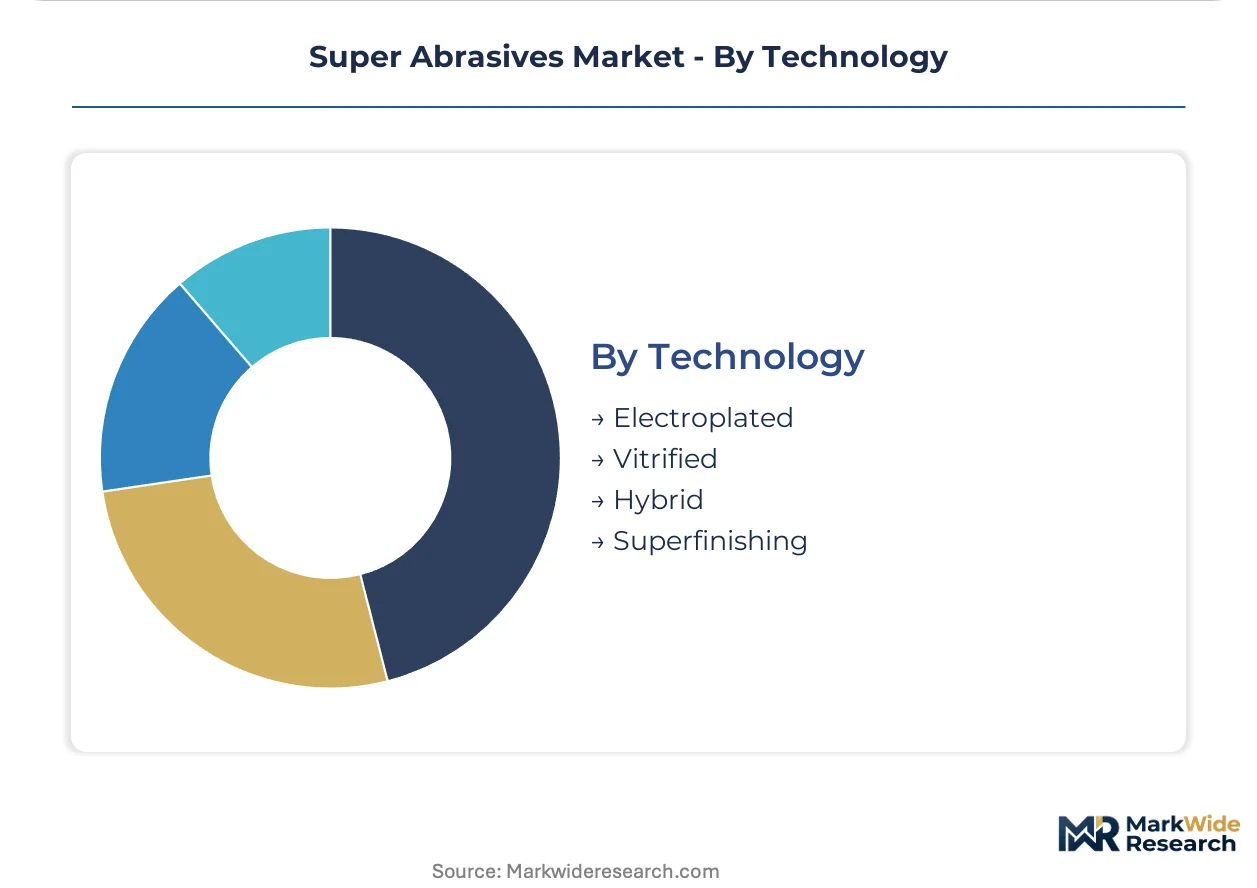
- Electroplated:Single-layer diamond or CBN crystals nickel-bonded to steel cores deliver aggressive cutting action for high-stock-removal operations. Job shop environments favor electroplated tools for cutting applications where wheel changeover downtime exceeds productivity thresholds. Leasing models capture lifetime value from high-utilization cutting operations.
- Vitrified:Glass-ceramic bond matrices provide controlled porosity and chemical stability for superfinishing applications. Aerospace blade finishing in Germany and Japan concentrates expertise among aging specialists, constraining new product development velocity. In-house ceramic chemistry capabilities capture specification authority as resin-dependent competitors face REACH compliance delays.
- Hybrid:Combined vitrified-metal bond systems collapse historical separation between rough grinding and superfinishing operations. Single-setup workflows eliminate wheel changeover downtime for aerospace tier suppliers.
- Superfinishing:Ultra-precision processes achieving surface roughness below Ra 0.05 micrometers for optical and semiconductor applications.
Vitrified systems retain margin leadership in specification-driven contracts; hybrid technologies are climbing the fastest as process integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing authority through Stuttgart's precision machining cluster, while Chinese producers compete on scale despite energy cost pressures from dual carbon enforcement. This asymmetry shapes investment flows across manufacturing geographies.
Germany
Aerospace turbine blade finishing and automotive powertrain machining drive specification-grade demand. The EU F-Gas Regulation phases down hydrofluorocarbon use, redirecting R&D toward bonded abrasives with lower greenhouse gas footprints. Stuttgart and Aachen host concentrated precision machining clusters where vitrified bond expertise anchors contract awards.
United States
EPA air quality standards and OSHA permissible exposure limits for respirable crystalline silica compel enclosed grinding system investments. Aerospace engine OEMs in the Southeast and Midwest mandate surface roughness below Ra 0.1 micrometers for hot-section components. Precision grinding equipment leasing models gain traction among automotive tier suppliers seeking asset-light strategies.
China
Dual carbon goals reshape synthetic diamond production energy sourcing as MEE enforcement accelerates consolidation among electroplated tool shops. High-pressure high-temperature synthesis faces electricity price volatility, compressing margins during raw material cycles. Zhengzhou anchors domestic production capacity for both diamond feedstock and finished abrasive products.
Japan
Automotive and electronics manufacturing sustain demand for superfinishing applications where surface roughness specifications define supplier selection. METI industrial standards guide bond chemistry development for precision grinding operations. Nagoya and Osaka metropolitan areas concentrate vitrified bond formulation expertise among specialized manufacturers.
India
Automotive OEM supply chain localization transplants Stuttgart and Aachen cluster expertise to Pune and Chennai manufacturing corridors. BIS standards alignment supports export competitiveness in precision grinding applications. Domestic synthetic diamond feedstock production expands as producers seek margin control across volatile raw material cycles.
Super Abrasives Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and bond chemistry. The market exhibits tiered consolidation with premium specification authority concentrating among European and Japanese specialists, while scale-driven competition characterizes commodity-grade segments. Three archetypes dominate: vitrified bond technology leaders, synthetic diamond feedstock integrators, and precision grinding service networks. Competitive moves center on geographic hub localization and water-based bond chemistry R&D to bypass REACH-registered precursors.
Among diversified materials conglomerates, Saint-Gobain and 3M occupy positions spanning multiple bonding technologies and end-use segments. Japanese specialists Asahi Diamond Industrial Co., Ltd. and Noritake Co., Limited exemplify concentrated expertise in vitrified and resin bond systems for aerospace and electronics applications. These named entities represent archetype anchors rather than exhaustive market coverage, with competitive dynamics further shaped by regional specialists in synthetic diamond synthesis and electroplated tool fabrication.
| Leading Market Players |
|---|
| Asahi Diamond Industrial Co., Ltd. |
| Carborundum Universal Limited |
| 3M |
| Fujimi Incorporated |
| Hyperion Materials & Technologies |
| Saint-Gobain |
| Noritake Co., Limited |
| Zhengzhou Hongtuo Super Abrasive Products Co., Ltd |
| Tyrolit Group |
| Others |
Supply Flow & Price Mechanics
Rhine-Alpine corridor freight dynamics amplify cost differentials between Stuttgart's precision machining cluster and Asian manufacturing hubs, concentrating premium pricing power among vitrified bond specialists while compressing margins on commodity-grade electroplated tools shipped through Rotterdam-Antwerp gateways.
Pricing Analysis
Configured-to-order pricing for aerospace blade finishing specifications commands spreads exceeding standard catalog pricing by multiples, driven by surface roughness below Ra 0.1 micrometers certification tiers and dedicated application engineering support. Three-tier pricing structure across premium, standard, and economy levels stratifies by bond chemistry complexity and after-sales service bundling. Cost compression in economy-grade resin bond segments is intensifying because silicon carbide substitution erodes volume leverage. Automotive tier suppliers exhibit highest price sensitivity due to just-in-sequence procurement mandates, while aerospace engine OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control regimes limiting synthetic diamond synthesis technology transfers constrain capacity expansion outside established manufacturing corridors in Germany, Japan, and China. High-pressure high-temperature synthesis equipment draws from specialized press manufacturers in Japan and the United States, while CBN feedstock sources from European and Asian chemical processors. Single-source vulnerability concentrates in vitrified bond ceramic chemistry expertise aging among German and Japanese specialists. Distribution runs through authorized distributor networks serving precision machining clusters, with direct OEM relationships capturing specification authority in aerospace contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The super abrasives market is undergoing high-growth disruption as EU F-Gas Regulation phases down hydrofluorocarbon use, forcing bond chemistry reformulation and collapsing product lifecycles for resin-dependent competitors.
For Market Incumbents: Harden specification authority by embedding vitrified bond R&D teams within Stuttgart aerospace tier supplier facilities, co-developing next-generation superfinishing formulations. Deepen backward integration into synthetic diamond feedstock through captive high-pressure high-temperature synthesis capacity in Germany or India, insulating margin structures from electricity price volatility. Prioritize water-based bond chemistry patent filings to preempt REACH-registered precursor restrictions.
For New Entrants and Emerging Players: Pursue electroplated tool leasing models in Indian automotive corridors around Pune and Chennai, transplanting German precision machining service expertise through technical partnerships. Target water-based bond formulation white space in European markets where ECHA restrictions delay incumbent product launches. Anchor go-to-market strategy through precision grinding equipment OEM channel partnerships rather than direct abrasive sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned super abrasives divisions lacking dedicated R&D investment. Long-term viability hinges on bond chemistry talent retention and geographic proximity to aerospace certification centers. Watch for MEE enforcement intensity in China as consolidation signal among electroplated tool shops.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Feedstock | Captures margin control across volatile electricity pricing cycles in HPHT synthesis operations. |
| Water-Based Bond Chemistry R&D Program | Bypasses REACH-registered resin precursors while opening sustainability-driven buyer segments in Europe. |
| Precision Grinding Equipment Leasing Model | Transfers utilization risk to abrasives providers and captures lifetime value from high-stock-removal cutting. |
| Localized Production Hub in India | Aligns with automotive OEM supply chain localization from Stuttgart-Aachen expertise transplant. |
| Hybrid Vitrified-Metal Bond System Launch | Collapses rough grinding and superfinishing operations into single-setup workflows for aerospace tiers. |
Methodological Framework
A spread of perspectives from grinding operations managers at aerospace tier suppliers, vitrified bond R&D directors, synthetic diamond procurement leads, and precision grinding equipment OEM sales executives converged on the working assumptions. Primary fieldwork combined with secondary validation against SEC filings from diversified materials conglomerates, ECHA REACH registration databases, EU F-Gas Regulation implementation reports, and German mechanical engineering association production statistics. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation dimensions spanning product type, bond technology, application stage, and end-use industry vertical across the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates, calibrated against synthetic diamond feedstock production capacity expansion timelines and aerospace engine OEM delivery schedules.
Sensitivities concentrate around REACH precursor restriction scope expansion, MEE enforcement intensity reshaping Chinese synthetic diamond production economics, and aerospace blade finishing tolerance compression rates. Forecasts reflect documented assumptions on bond chemistry innovation timelines and regional production hub localization patterns. Material shifts in EU F-Gas Regulation phase-down schedules or dual carbon goal implementation in China would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Bonded Abrasive Market
Abrasives
Synthetic Abrasives Market
Abrasives
Europe Abrasives Market
Abrasives
Tungsten Carbide Market
Abrasives
Glass Abrasives Market
Abrasives
Metal Abrasives Market
Abrasives
Carbide Tools Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
RDP Powder Market
Abrasives
Carborundum Market
Abrasives
Liquid Sandpaper Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Tile Abrasion Testing Market