
 Europe Abrasives Market | 2026-2036
Europe Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Abrasives Market Foresight
The EU Green Deal is decoupling abrasives demand from conventional manufacturing footprints by mandating lower-carbon production methods and circular material flows. Saint-Gobain leverages its vertically integrated fused mineral operations to control raw material quality across European plants. Robert Bosch GmbH anchors its abrasives portfolio through dense distribution networks serving automotive repair chains. Tyrolit Schleifmittelwerke Swarovski specializes in precision super abrasive tools for turbine blade machining, a niche where technical specifications command premium positioning.
Abrasives are hard materials—typically aluminum oxide, silicon carbide, diamond, or ceramic grains bonded to paper, cloth, resin, or metal substrates—engineered to remove surface material through grinding, cutting, polishing, or finishing operations with defined grit sizes and hardness ratings. Bonded abrasives dominate volume across European metal fabrication shops where grinding wheels face steady replacement cycles, while super abrasives capture disproportionate margin pools in aerospace turbine grinding where diamond and cubic boron nitride tolerances reach sub-micron precision. Coated abrasives sustain broad demand in automotive surface preparation, though price competition from Asian imports compresses returns in standardized paper and cloth belts.
REACH enforcement through ECHA restricts crystalline silica and heavy metal binders in bonded abrasive formulations, forcing reformulation investments that favor larger manufacturers with in-house chemistry labs. The EU F-Gas Regulation indirectly shapes demand by accelerating electric motor and heat pump production, both of which require precision abrasive finishing on copper windings and compressor housings. Stakeholders must monitor how the EU AI Act's manufacturing quality requirements could automate abrasive process control, altering buyer specifications for sensor-compatible finishing systems.
Market Dynamics
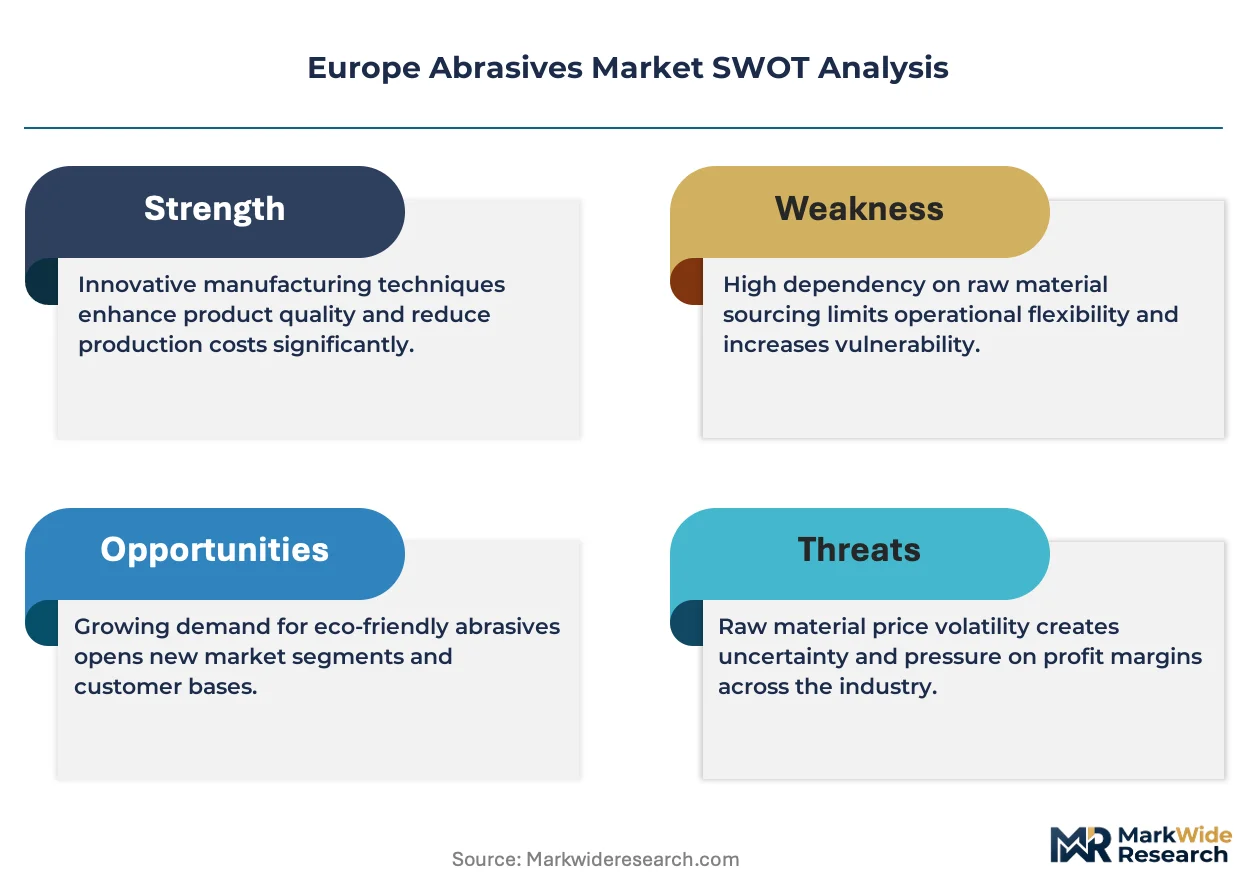
REACH enforcement through ECHA is forcing bonded abrasive manufacturers to eliminate crystalline silica and heavy metal binders, creating a structural divide between reformulation-capable integrated producers and dependent compounders facing compliance failure.
Growth Catalysts
- EU F-Gas Regulation:Accelerated heat pump and electric motor manufacturing across Germany and France is expanding precision abrasive demand for copper winding finishing and compressor housing machining.
- EV powertrain grinding:German automotive OEMs are scaling precision grinding operations for electric motor shafts and battery housing components, displacing conventional engine block abrasive cycles.
- Ceramic grain technology:Sol-gel ceramic abrasives are penetrating aerospace turbine blade machining in Italy and France where sub-micron tolerances command technical specification premiums.
Market Restraints
- Fused alumina supply concentration:European fused mineral production concentrates in Germany and Austria, exposing grinding wheel manufacturers to energy cost volatility and single-source dependency risks.
- REACH reformulation costs:ECHA chemical content restrictions are forcing SME abrasive compounders to outsource binder chemistry, eroding margin control and technical differentiation.
- Asian coated abrasive imports:Standardized paper and cloth belt imports from China and India are compressing returns in automotive surface preparation segments where specification commoditization prevails.
Strategic Opportunities
- Polish metal fabrication expansion:Underdeveloped precision grinding infrastructure in Polish aerospace supply chains offers first-mover positioning for super abrasive tool vendors.
- EU AI Act manufacturing compliance:Automated abrasive process control requirements are creating specification demand for sensor-compatible finishing systems in German automotive plants.
- Circular material flows:EU Green Deal waste reduction mandates are opening service-contract models for abrasive recycling and reconditioning in French and Italian metalworking clusters.
Industry Challenges
- Tribology and materials science expertise:Grinding process optimization for ceramic and CBN applications requires specialized knowledge scarce outside German and Austrian technical universities.
- Multi-certification burden:Aerospace suppliers must simultaneously maintain AS9100, Nadcap, and customer-specific process approvals, extending qualification timelines for new abrasive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Abrasives Market |
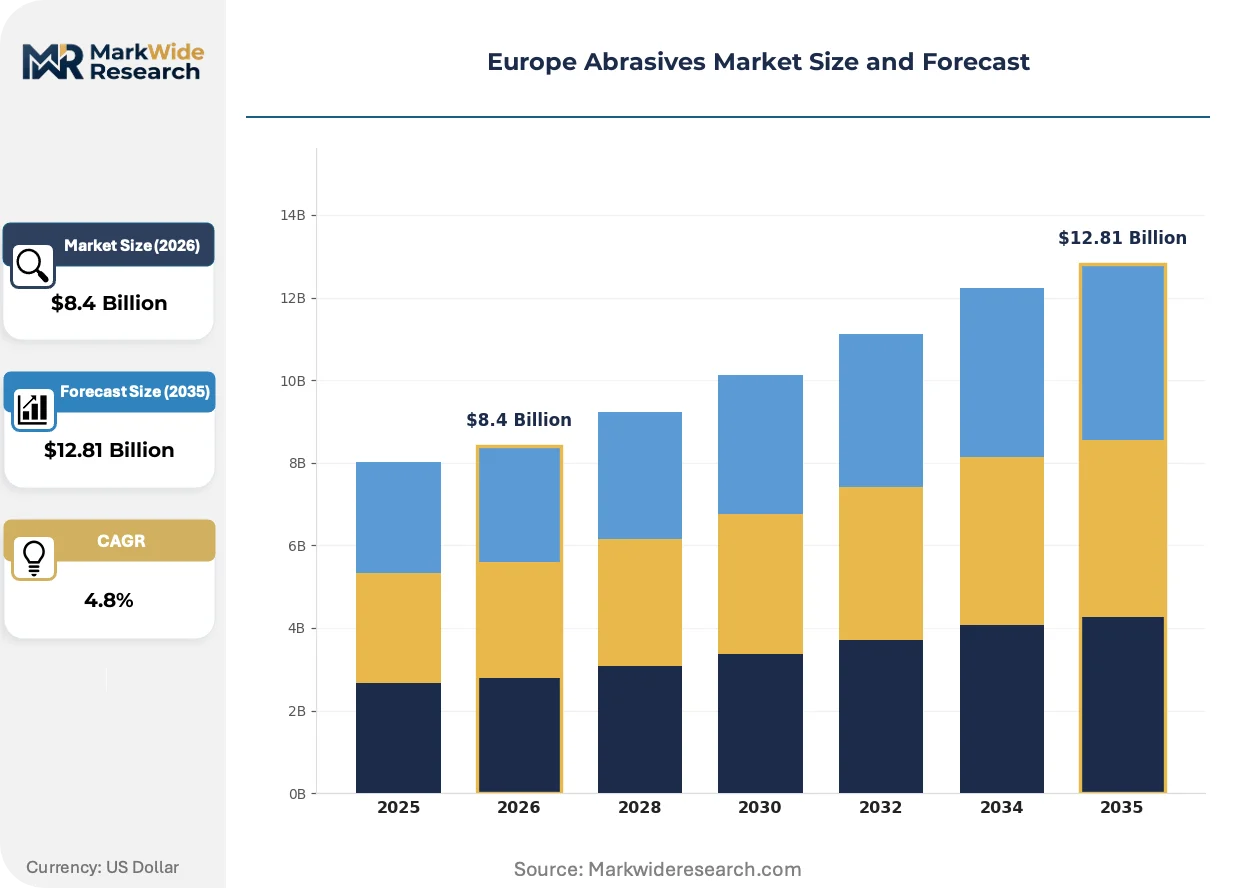
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Super Abrasives, Specialty Abrasives End User: Automotive, Aerospace, Metal Fabrication, Construction Application: Grinding, Cutting, Polishing, Surface Preparation Material: Silicon Carbide, Aluminum Oxide, Diamond, Ceramic |
| Companies Covered | Tyrolit Schleifmittelwerke Swarovski AG & Co KG, Henkel AG & Co KGaA, Compagnie de Saint-Gobain S.A., CUMI AWUKO Abrasives GmbH, Deerfos Co., Ltd, Robert Bosch GmbH, sia Abrasives Industries AG, Asahi Diamond Industrial Europe, 3M Co, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Abrasives Market Shifts & Advancements
Electrification of transport and industrial equipment is redefining abrasive performance specifications, while regulatory chemistry constraints and digital manufacturing integration are simultaneously reshaping product architecture and vendor selection criteria.
Sol-gel engineered ceramic grains with self-sharpening microstructure are consolidating market share in high-performance precision grinding applications. German aerospace turbine manufacturers are adopting these materials for nickel alloy blade machining where conventional fused alumina suffers glazing and thermal damage. The technology is consolidating technical differentiation around vendors with captive ceramic synthesis capabilities, compressing position for pure abrasive fabricators.
REACH authorization requirements through ECHA are systematically eliminating crystalline silica and cobalt-based binders from bonded abrasive formulations. Manufacturers with in-house chemistry laboratories are accelerating reformulation timelines while smaller compounders face extended external testing dependencies. German and Italian grinding wheel producers are most affected, with compliance investments diverting R&D resources from performance innovation.
Automotive OEMs are unbundling abrasive supply from machine tool procurement, establishing direct specification control over grinding consumables. Tier-one suppliers in France and Germany are losing captive abrasive margins as vehicle manufacturers centralize process parameter standardization. This concentration is most visible in EV battery tray machining where Tesla, BMW, and Volkswagen have each issued proprietary abrasive specification catalogs to their stamping and welding partners.
Europe Abrasives Market Segmentation
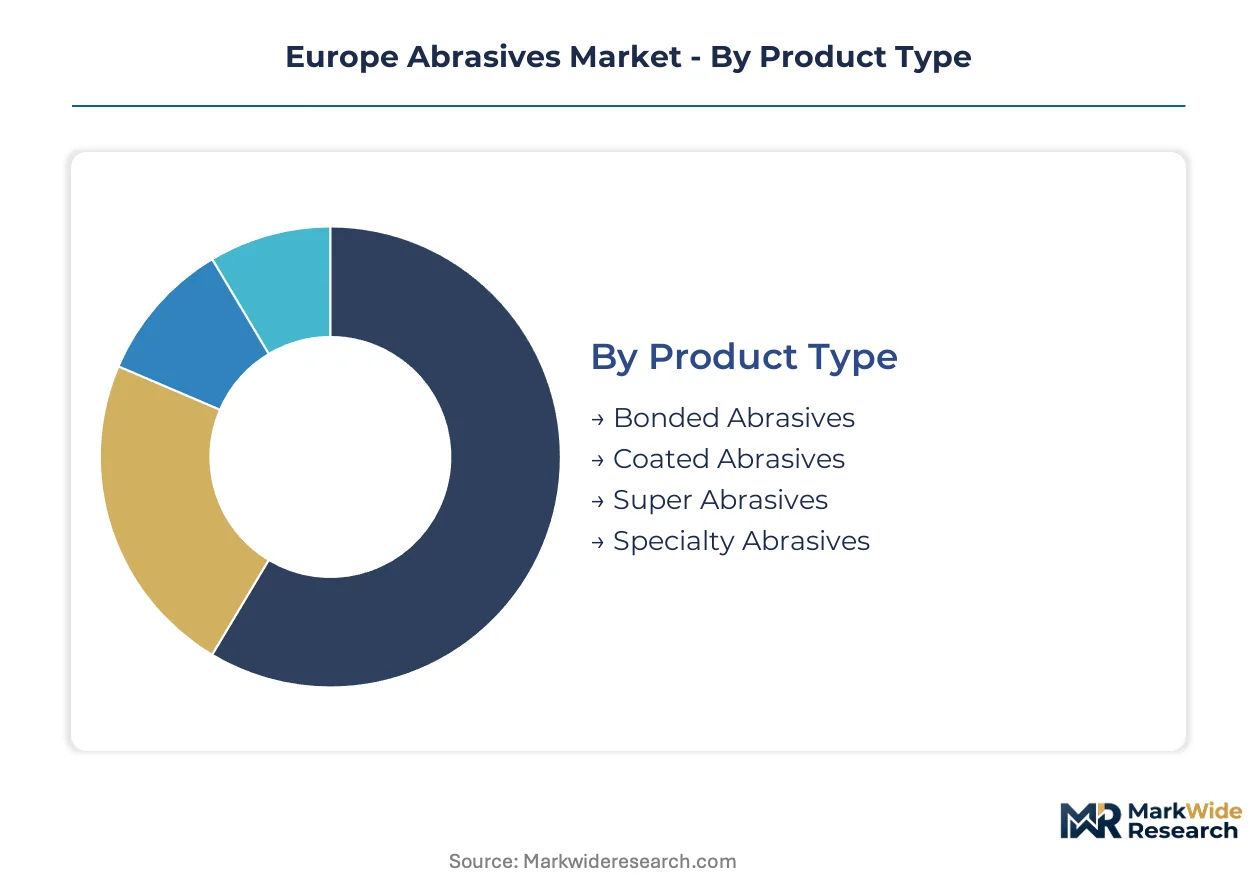
Segmentation reveals how abrasive specifications diverge across European manufacturing verticals. Product architecture, end-use precision requirements, and material chemistry each create distinct competitive arenas with different margin structures and regulatory exposures.
Product Type:
Buyers in this category separate by process intensity and tool replacement frequency rather than absolute purchase volume.
- Bonded Abrasives:Grinding wheels and discs fuse abrasive grains with vitrified or resin bonds for heavy stock removal. German and Italian metal fabrication shops drive replacement demand as REACH reformulation raises per-unit costs for standardized wheels.
- Super Abrasives:Diamond and cubic boron nitride tools achieve sub-micron tolerances in single-point dressing and creep-feed grinding. French and Italian aerospace turbine manufacturers specify these for nickel alloy blade machining where thermal damage tolerance is minimal.
- Coated Abrasives:Paper and cloth belts with resin-bonded grains serve automotive surface preparation. Asian import competition compresses margins in standardized grades.
- Specialty Abrasives:Engineered shapes for gear honing and medical device finishing command specification premiums in Swiss and German precision manufacturing clusters.
Bonded abrasives lead volumes today; super abrasives is gaining share fastest.
End User:
Customer procurement sophistication varies sharply, with some verticals centralizing abrasive specification control while others delegate to machine tool vendors.
- Automotive:German OEMs are unbundling abrasive supply from machine tool procurement, issuing proprietary specification catalogs for EV battery tray machining and electric motor shaft finishing.
- Metal Fabrication:Small and mid-sized job shops across Poland and the Czech Republic drive volume demand for bonded wheels in structural steel processing. REACH compliance costs are pushing these buyers toward larger suppliers with in-house chemistry capabilities.
- Aerospace:Tier-one suppliers in France and Italy maintain AS9100 and Nadcap certifications that lock in super abrasive vendors for turbine blade grinding cycles.
- Construction:Infrastructure and residential building activity in Spain and Eastern Europe sustains demand for portable grinding and cutting discs with lower specification intensity.
Metal fabrication dominates volume today; automotive is climbing the fastest as powertrain electrification redefines finishing requirements.
Application:
Process physics and surface finish specifications determine abrasive selection more than workpiece material alone.
- Grinding:Precision material removal with defined grit geometry. German EV powertrain manufacturers are scaling cylindrical grinding for motor shafts, displacing conventional engine block abrasive cycles.
- Surface Preparation:Cleaning and profiling prior to coating or bonding. Automotive repair chains in France specify coated abrasives for collision repair, though price pressure from Asian imports limits margin expansion.
- Cutting:Severing operations with reinforced wheels. Construction activity in Poland and Romania drives demand for portable cut-off wheels in structural steel.
- Polishing:Final finish operations requiring controlled surface roughness. Italian luxury automotive trim suppliers and German medical device manufacturers specify fine-grain products for aesthetic and functional surfaces.
Grinding leads volumes today; surface preparation is expanding most quickly as automated finishing systems penetrate automotive plants.
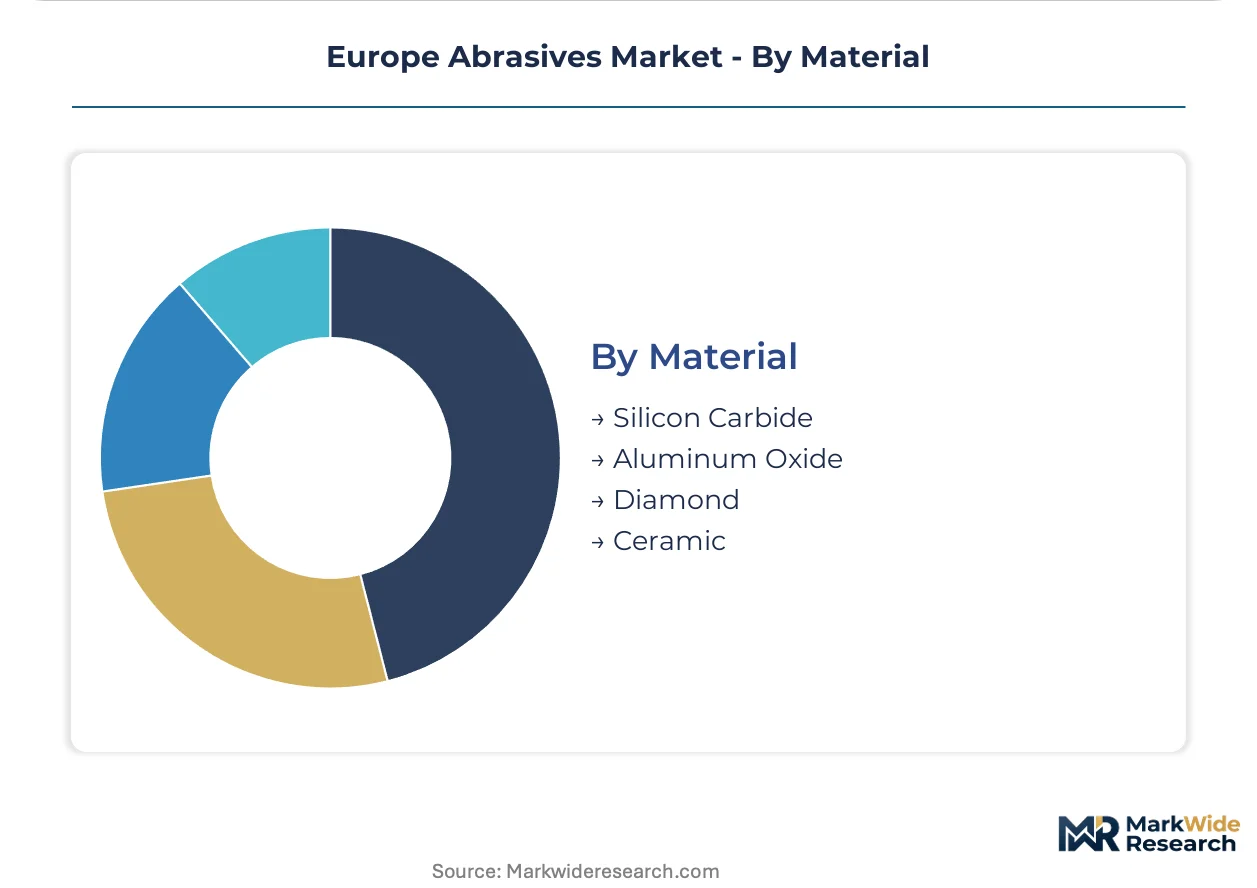
Material:
Raw material chemistry and synthesis capability create tiered supply security among abrasive grain producers.
- Aluminum Oxide:Fused and sintered variants dominate general-purpose grinding. European production concentrates in Germany and Austria, exposing buyers to energy cost volatility.
- Ceramic:Sol-gel engineered grains with self-sharpening microstructure penetrate high-performance precision applications. Vendors with captive ceramic synthesis capabilities are consolidating technical differentiation.
- Silicon Carbide:Harder and more brittle than aluminum oxide, preferred for non-ferrous metals and stone. Demand concentrates in Italian stone processing and German glass manufacturing.
- Diamond:Natural and synthetic monocrystalline and polycrystalline forms for super abrasive tools. Sub-micron tolerances in aerospace turbine grinding command premium positioning.
Aluminum oxide leads volumes today; ceramic is gaining share fastest as sol-gel technology displaces conventional fused grains in precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision grinding technology first achieved industrial scale in Germany during the early twentieth century, establishing Central Europe as the foundational geography for bonded abrasive manufacturing and super abrasive tool development.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are scaling cylindrical grinding operations for electric motor shafts and battery housing components. ECHA REACH enforcement is eliminating crystalline silica from bonded wheel formulations produced in the Solingen grinding tool cluster. Stuttgart's precision engineering corridor maintains dense concentrations of super abrasive applications for aerospace turbine blade machining.
Italy
Aerospace tier-one suppliers in Lombardy and Piedmont drive demand for diamond and CBN tools in nickel alloy component finishing. The EU Green Deal's waste reduction mandates are opening service-contract models for abrasive reconditioning in Brescia's metalworking district. Turin-based automotive suppliers are adopting proprietary abrasive specifications for EV powertrain components as OEMs centralize procurement control.
France
Heat pump manufacturing expansion around Lyon and Grenoble is expanding precision abrasive demand for copper winding finishing and compressor housing machining under the EU F-Gas Regulation. Île-de-France aerospace suppliers maintain AS9100 and Nadcap certifications that lock in super abrasive vendors for turbine blade grinding cycles. Saint-Gobain's vertically integrated fused mineral operations anchor raw material supply security across domestic plants.
Austria
Swarovski Group's super abrasive operations in Tyrol specialize in precision tools for turbine blade machining where sub-micron tolerances command premium positioning. The country's fused alumina production concentrates in Vorarlberg, exposing grinding wheel manufacturers to energy cost volatility from hydroelectric dependency. REACH reformulation investments are diverting R&D resources from performance innovation at domestic compounders.
Poland
Underdeveloped precision grinding infrastructure in Lower Silesia's aerospace supply chains offers first-mover positioning for super abrasive tool vendors. Metal fabrication job shops in Katowice drive volume demand for bonded wheels in structural steel processing. Construction activity in Warsaw and Kraków sustains demand for portable grinding and cutting discs with lower specification intensity.
Europe Abrasives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical specification tiers, with super abrasive specialists capturing disproportionate returns while standardized coated abrasive fabricators face Asian import compression. The vendor base clusters around three strategic archetypes: vertically integrated fused mineral producers controlling raw material quality, precision super abrasive specialists serving aerospace certification requirements, and distributed fabricators competing on logistics reach for automotive repair chains. Dominant competitive moves include captive ceramic synthesis investments and direct OEM specification partnerships that bypass traditional machine tool vendor channels.
Among European-based integrated producers, Compagnie de Saint-Gobain S.A. and Tyrolit Schleifmittelwerke Swarovski AG & Co KG occupy positions that exemplify the premium-tier archetype through upstream mineral control and precision tool specialization respectively. Robert Bosch GmbH anchors the distribution-intensive segment through dense networks serving automotive repair chains. These three represent distinct competitive vectors: mineral integration, technical specification leadership, and channel scale.
| Leading Market Players |
|---|
| Tyrolit Schleifmittelwerke Swarovski AG & Co KG |
| Henkel AG & Co KGaA |
| Compagnie de Saint-Gobain S.A. |
| CUMI AWUKO Abrasives GmbH |
| Deerfos Co., Ltd |
| Robert Bosch GmbH |
| sia Abrasives Industries AG |
| Asahi Diamond Industrial Europe |
| 3M Co |
| Others |
Supply & Pricing Matrix
Fused alumina price indices in Germany and Austria cascade through European abrasive supply chains into three distinct pricing tiers. REACH reformulation costs concentrate in premium bonded wheel segments while Asian import competition compresses economy-tier coated abrasive returns. Buyers in automotive OEM direct-specification programs absorb technical premiums that job shops in Polish metal fabrication cannot pass downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European abrasive procurement. Price differentiation rests on REACH certification grade and captive ceramic synthesis capability rather than commodity grain sourcing alone. Cost compression in standardized coated abrasives is intensifying because Chinese and Indian belt imports displace domestic fabricators in automotive surface preparation. Metal fabrication job shops exhibit highest price sensitivity due to thin margin structures, while aerospace turbine manufacturers accept technical specification premiums for sub-micron tolerance tools.
Supply Chain Analysis
Freight cost volatility from energy price swings in Central Europe amplifies geographic supply concentration risks. Raw material production clusters in Germany, Austria, and France control fused mineral and super abrasive feedstock availability. European grinding wheel manufacturing draws from bauxite refining, petroleum coke processing, and synthetic diamond synthesis operations concentrated along the Rhine corridor. Single-source vulnerability in Vorarlberg hydroelectric-dependent fused alumina smelting threatens supply security during peak demand periods. Distribution runs through Saint-Gobain's vertically integrated mineral operations, Tyrolit's precision tool specialists, and Bosch's automotive repair channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Abrasives Market offers margin expansion through sol-gel ceramic grain substitution and service-contract reconditioning models under EU Green Deal waste mandates. Premium-tier displacement of conventional fused alumina in precision grinding applications supports pricing power for vendors with captive synthesis capabilities.
For Market Incumbents: Extend technical specification control through direct OEM partnerships that bypass traditional machine tool vendor channels. Defend against Asian import compression in coated abrasives by embedding sensor-compatible finishing systems into automated automotive plant contracts. Prioritize REACH reformulation R&D investments that smaller compounders cannot replicate, consolidating market share in bonded wheel segments where regulatory compliance now gates market access. For New Entrants and Emerging Players: The premium-to-economy price gap in Polish aerospace supply chains offers entry positioning for super abrasive tool vendors with Nadcap certification capabilities. Target underdeveloped precision grinding infrastructure in Lower Silesia where tier-one suppliers lack established vendor relationships. Pursue service-contract models for abrasive recycling and reconditioning in French and Italian metalworking clusters where EU Green Deal mandates create recurring revenue structures. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive ceramic synthesis and established aerospace certification pathways. Long-term viability favors vendors integrating upstream mineral control with downstream OEM specification partnerships rather than pure distribution plays. Watch for inflection signals in German automotive OEM unbundling trends as direct abrasive procurement centralization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Synthesis Capacity Expansion | Sol-gel grain investments in Germany and Austria lock in technical differentiation against fused alumina commoditization. |
| REACH Compliance Certification | ECHA authorization pathways for silica-free bonded formulations exclude smaller compounders from premium segments. |
| OEM Direct Specification Partnership | Bavarian and Baden-Württemberg automotive manufacturers are consolidating abrasive procurement control outside machine tool channels. |
| Service-Contract Reconditioning Models | EU Green Deal waste reduction mandates in Brescia and Lyon metalworking districts enable recurring revenue streams. |
| Polish Aerospace Supply Chain Entry | Lower Silesia's underdeveloped precision grinding infrastructure offers first-mover positioning for Nadcap-certified vendors. |
Research Methodology
Coverage spans Germany, Italy, France, Austria, and Poland, with primary inputs from each national metal fabrication and aerospace cluster. The research combines structured interviews with plant managers at grinding wheel manufacturers, procurement leads at German automotive OEMs, technical R&D directors at fused mineral producers, and aftermarket service heads at distribution networks. Secondary validation draws from ECHA REACH authorization databases, EU customs trade statistics, SEC filings of listed abrasive producers, and national industrial production indices. Bottom-up segment sizing triangulates against top-down macroeconomic manufacturing indicators.
Granularity extends to product type, end user vertical, application process, and raw material chemistry dimensions across the modeling period. The analytical framework models bonded abrasive replacement cycles, super abrasive tool penetration in aerospace, and coated abrasive import displacement separately. CAGRs derive from regression analysis of historical manufacturing output correlations and forward projection of regulatory-driven specification shifts. Key inputs include EV powertrain production forecasts for German OEMs and heat pump manufacturing expansion under the EU F-Gas Regulation.
The model assumes a particular technology adoption path; alternative pathways for sol-gel ceramic grain displacement of conventional fused alumina would alter the outlook for premium-tier vendor positioning. Forecasts reflect assumptions about REACH enforcement timelines and automotive OEM procurement centralization trends that regulatory or competitive dynamics could accelerate or delay. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Bonded Abrasive Market
Abrasives
Grinding Wheels Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Liquid Sandpaper Market
Abrasives
North America Abrasives Market
Abrasives
Calcined Shale Market
Abrasives
Anthracite Fines Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Abrasive Grains Market
Abrasives
Abrasive Rolls Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Synthetic Abrasives Market
Abrasives
Carborundum Market
Abrasives
Carbide Tools Market
Abrasives
Global Rubber Bonded Abrasive Market