
 Global Rubber Bonded Abrasive Market | 2026-2036
Global Rubber Bonded Abrasive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Bonded Abrasive Market Foresight
The EU Green Deal is shifting procurement criteria across European metal fabrication, compelling abrasive suppliers to reformulate bonding systems. Saint-Gobain Abrasives leverages its vertically integrated raw material network to control synthetic rubber feedstock costs. PFERD anchors its competitive position through specialized grinding wheel portfolios for precision engineering. Tyrolit Group dominates Central European distribution channels for automotive finishing applications.
Rubber bonded abrasives are composite tools manufactured by embedding abrasive grains—typically aluminum oxide, silicon carbide, or zirconia—within an elastic rubber matrix, with bond hardness graded on the A-to-Z durometer scale to control cutting aggressiveness. These tools absorb vibration and minimize workpiece damage during precision finishing operations. Grinding wheels command the largest product category share, sustained by continuous demand from metal surface finishing lines. Polishing pads represent the fastest-expanding segment, propelled by glasscraft specialists and optical component manufacturers requiring sub-micron surface quality. Synthetic rubber bonding materials capture growing preference over natural rubber due to tighter lot-to-lot consistency and superior thermal stability during high-speed operation.
FDA oversight of food-contact polishing equipment and EPA emissions standards for rubber curing operations shape formulation and facility investment decisions in the United States. ECHA REACH restrictions on polycyclic aromatic hydrocarbons in rubber compounding directly limit bonding material options for European suppliers. ISO 9001 and ISO 14001 certifications function as baseline market access requirements for Tier-1 automotive contracts. Stakeholders must monitor evolving chemical substance restrictions and validate alternative bonding chemistries before regulatory deadlines eliminate incumbent formulations.
Market Dynamics
REACH restrictions on polycyclic aromatic hydrocarbons are forcing European suppliers to abandon incumbent rubber bonding chemistries and validate alternative formulations ahead of regulatory deadlines. Automotive finishing lines in Germany's industrial corridor are accelerating consumption of precision grinding wheels as EV component tolerances tighten.
Growth Catalysts
- EV powertrain manufacturing:Precision grinding requirements for electric motor shafts and battery housing finishes are expanding wheel consumption in automotive supplier parks.
- ECHA REACH compliance deadlines:Reformulation mandates are creating first-mover advantages for suppliers with validated low-VOC bonding systems already in production.
- Synthetic rubber consistency:Lot-to-lot uniformity in nitrile and SBR bonding matrices is enabling tighter process control for optical component polishers.
Market Restraints
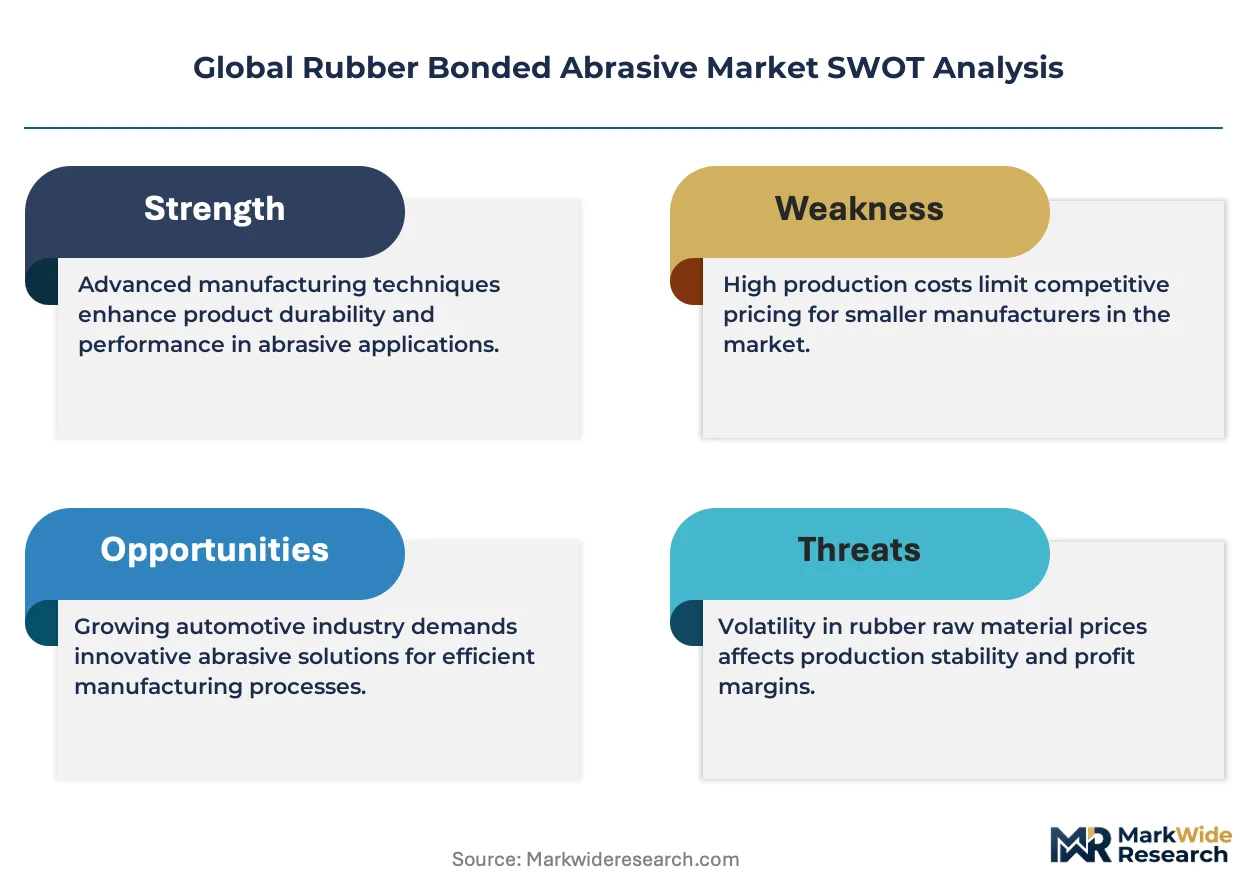
- Petrochemical feedstock volatility:Synthetic rubber prices track naphtha and butadiene futures, compressing margin predictability for bonding material producers.
- German supply concentration:Central European abrasive manufacturing clusters create geographic risk exposure to single-region energy cost shocks.
- Superabrasive substitution:Diamond and CBN bonded wheels are displacing conventional aluminum oxide in high-value precision applications.
Strategic Opportunities
- India automotive supplier base:PLI scheme incentives for component manufacturing are creating greenfield demand for finishing abrasives in Pune and Chennai corridors.
- Optical glass polishing pads:Sub-micron surface quality requirements for smartphone camera lenses and AR waveguides are opening specialty product lines.
- EU Green Deal procurement criteria:Public tender preferences for low-carbon manufacturing inputs are rewarding suppliers with ISO 14001-validated bonding processes.
Industry Challenges
- Formulation chemist scarcity:Expertise in rubber-to-abrasive grain adhesion chemistry is retiring faster than training programs replace it.
- Dual certification timelines:ISO 9001 and IATF 16949 audits for Tier-1 automotive contracts require 12-18 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Bonded Abrasive Market |
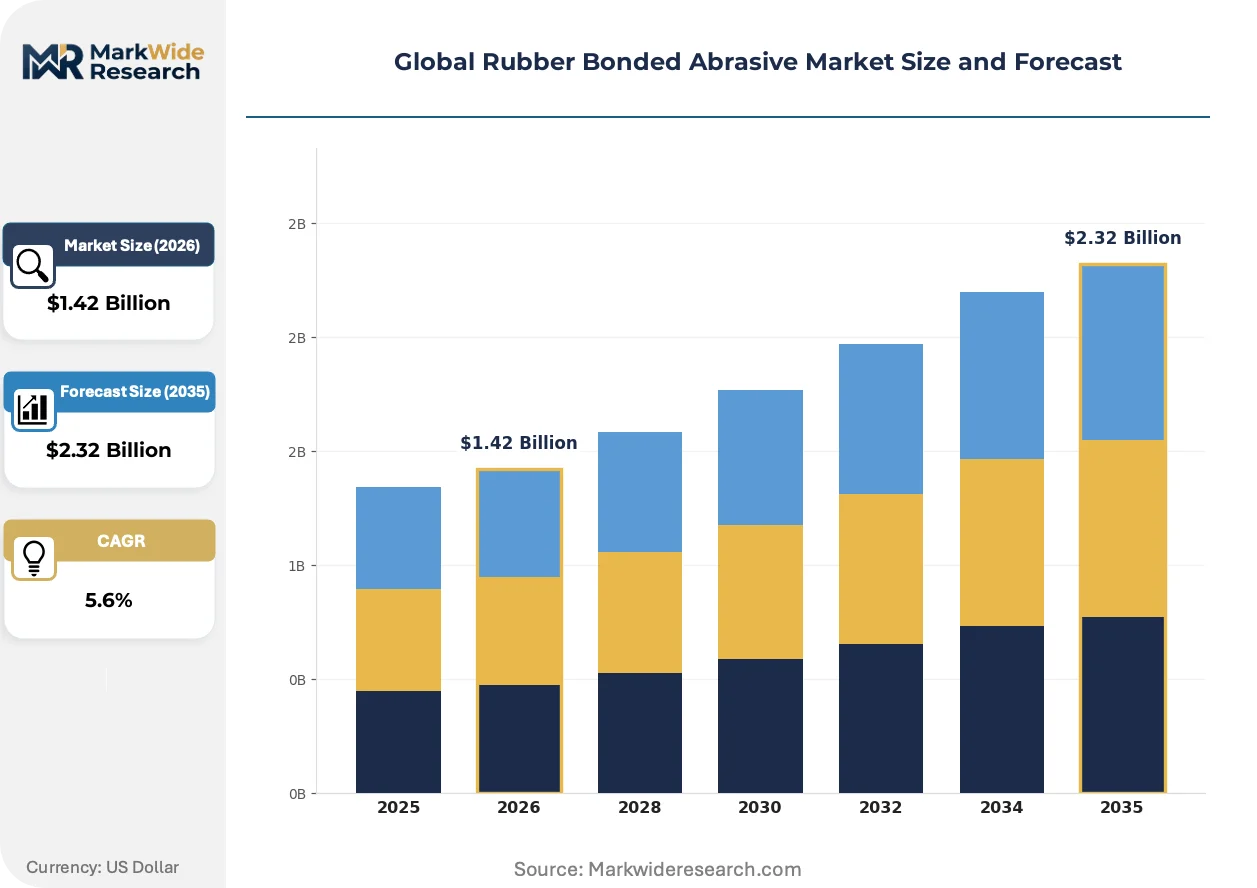
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grinding Wheels, Polishing Pads, Buffing Wheels, Sharpening Stones, Cutting Discs Bonding Material: Natural Rubber, Synthetic Rubber, Latex, Neoprene, Butadiene Rubber Application: Metal Surface Finishing, Woodworking, Automotive Component Production, Glass Polishing, Stone Carving End User: Metal Fabricators, Woodwork Shops, Vehicle Manufactures, Glasscraft Specialists, Sculpture Studios |
| Companies Covered | PFERD, Carborundum Universal, 3M, KURE Grinding Wheel, Noritake, Saint-Gobain Abrasives, Abrasivos Manhattan, Schwarzhaupt GmbH & Co. KG, Tyrolit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Bonded Abrasive Market Shifts & Advancements
Digital process monitoring and closed-loop grinding systems are compressing the feedback cycle between wheel wear and process adjustment. Suppliers are embedding sensors directly into bonded abrasive structures.
Ceramic grain technology is electrifying cutting performance in high-speed precision applications. Aerospace turbine blade manufacturers are adopting seeded-gel aluminum oxide wheels for nickel alloy finishing. This grain architecture is compressing cycle times by enabling aggressive stock removal without thermal damage to thin-walled components.
EPA emissions standards for rubber curing operations are constraining facility expansion in the United States. Curing oven VOC capture requirements are adding capital intensity to greenfield investments. California-based suppliers are relocating curing operations to states with less stringent air quality management districts.
Consolidated procurement through integrated tool management systems is displacing spot purchasing in metal fabrication. Large contract manufacturers are mandating vendor-managed inventory programs with direct line-feed arrangements. This shift is most visible in German automotive supplier networks where OEMs dictate approved abrasive supplier lists.
Global Rubber Bonded Abrasive Market Segmentation
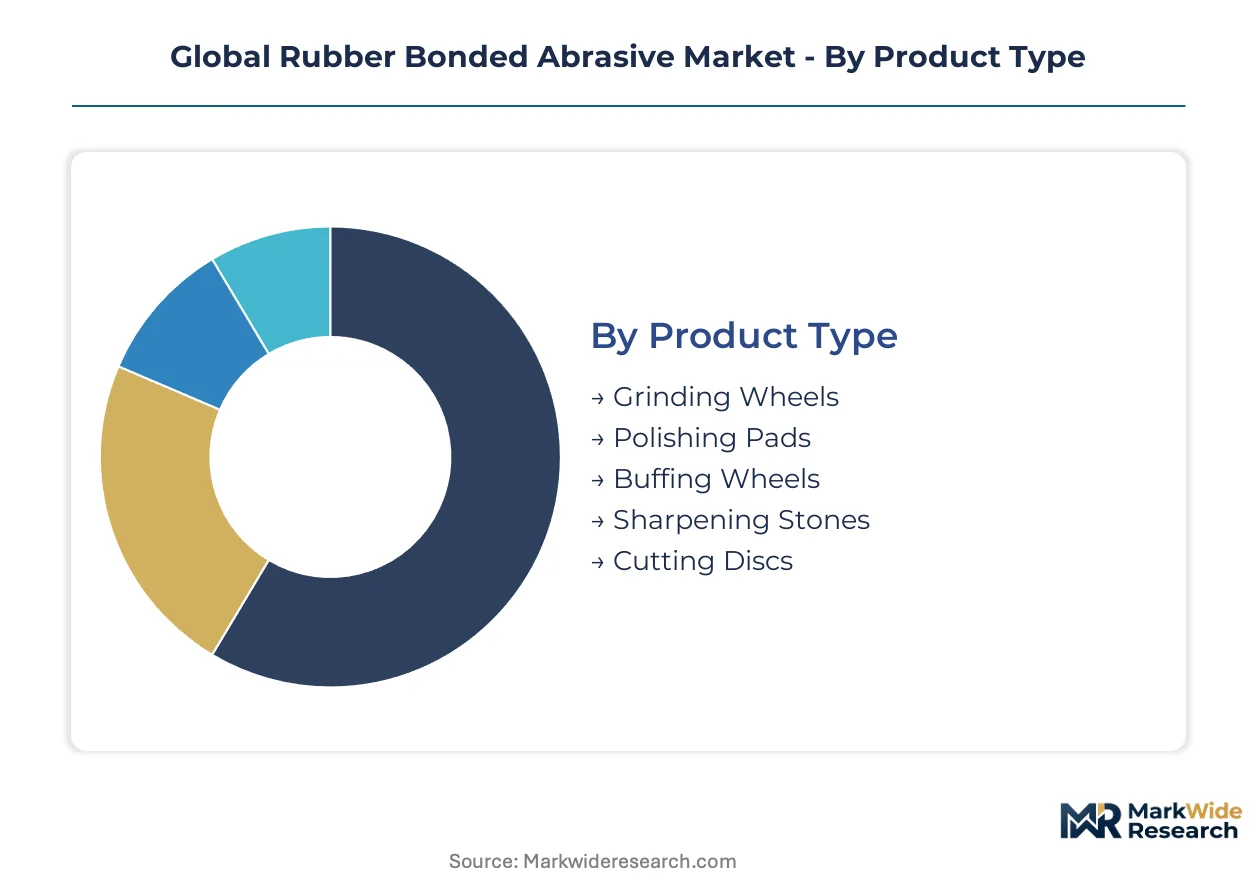
Rubber bonded abrasive manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles and certification requirements that shape supplier positioning strategies.
Product Type:
Customization intensity spans from commodity cutting discs to application-engineered polishing pads requiring sub-micron surface specifications.
- Grinding Wheels:Composite structures embedding aluminum oxide or silicon carbide grains within graded rubber matrices, with durometer hardness calibrated to workpiece material. Demand concentrates in Germany's automotive supplier corridor where EV powertrain tolerances are tightening surface finish specifications.
- Polishing Pads:Elastic bonded tools engineered for sub-micron surface quality on optical glass and precision metal components. Glasscraft specialists in Japan and smartphone lens manufacturers in South Korea are driving specification escalation toward nanometer-scale surface roughness control.
- Buffing Wheels:Open-cell rubber structures for final-stage aesthetic finishing on decorative metalwork and automotive trim.
- Sharpening Stones:Dense rubber-bonded abrasives for edge maintenance in industrial cutting tool operations.
- Cutting Discs:Thin-section reinforced wheels for portable cutoff applications in metal fabrication job shops.
Most installed capacity flows through grinding wheels. Expansion is steepest in polishing pads.
Bonding Material:
Cost tiers separate commodity natural rubber formulations from performance-graded synthetic matrices commanding specification premiums.
- Synthetic Rubber:Nitrile and SBR matrices delivering lot-to-lot consistency for optical component polishers requiring thermal stability during high-speed operation. REACH compliance deadlines are accelerating substitution away from aromatic-rich formulations.
- Natural Rubber:Hevea-based bonding systems with inherent elasticity for vibration-dampening grinding applications. Malaysian and Indonesian feedstock supply volatility is compressing margin predictability for commodity-grade wheel producers.
- Latex:Aqueous dispersion systems for low-temperature curing in temperature-sensitive abrasive grain applications.
- Neoprene:Chloroprene matrices resisting degradation from cutting fluids in wet grinding environments.
- Butadiene Rubber:High-resilience bonding for aggressive stock removal wheels in foundry and forging operations.
Volume leadership sits with synthetic rubber. Neoprene is climbing fastest on chemical resistance requirements.
Application:
Customer maturity separates specification-driven precision finishing from price-sensitive rough grinding operations.
- Metal Surface Finishing:Precision grinding and polishing of steel, aluminum, and nickel alloys across aerospace turbine blade and automotive powertrain component production. ISO 9001 certification is mandatory for Tier-1 supplier qualification.
- Automotive Component Production:EV motor shaft finishing and battery housing surface preparation in Germany, China, and India supplier parks. Tightening geometric tolerances are elevating wheel specification requirements beyond conventional aluminum oxide performance limits.
- Woodworking:Elastic bonded abrasives for furniture and millwork surface preparation.
- Glass Polishing:Sub-micron finishing for architectural, automotive, and optical glass applications.
- Stone Carving:Aggressive cutting and shaping wheels for dimensional stone and monument fabrication.
Metal surface finishing commands the largest installed base. Automotive component production is expanding most quickly on EV manufacturing ramp.
End User:
Procurement sophistication ranges from integrated tool management systems at vehicle manufacturers to spot purchasing at sculpture studios.
- Metal Fabricators:Job shops and contract manufacturers consuming grinding wheels and cutting discs across diversified industrial customer bases. Vendor-managed inventory programs are displacing spot purchasing among large contract manufacturers in German automotive supplier networks.
- Vehicle Manufacturers:OEM and Tier-1 operations with approved supplier lists dictating abrasive procurement specifications. IATF 16949 certification requirements impose 12-18 month validation cycles that delay new supplier entry.
- Woodwork Shops:Small and mid-sized operations purchasing through distributor channels.
- Glasscraft Specialists:Precision optical component manufacturers with sub-micron surface quality requirements.
- Sculpture Studios:Artisan and monument fabrication operations with low-volume, high-variety consumption patterns.
Vehicle manufacturers concentrate procurement volume. Glasscraft specialists are gaining share fastest on optical component demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubber bonded abrasive manufacturing originated in Germany's industrial heartland during the early twentieth century, with precision grinding technology spreading through Central European metalworking clusters before establishing production bases across automotive manufacturing corridors worldwide.
Germany
Automotive powertrain finishing and EV battery housing surface preparation dominate demand in Stuttgart and Munich supplier parks. ECHA REACH restrictions on polycyclic aromatic hydrocarbons are compelling reformulation of rubber bonding chemistries ahead of compliance deadlines. Baden-Württemberg's precision engineering corridor concentrates the highest density of grinding wheel consumption for aerospace turbine blade manufacturers.
United States
EPA emissions standards for rubber curing operations are constraining facility expansion in California while driving relocation to states with less stringent air quality districts. FDA oversight of food-contact polishing equipment shapes formulation decisions for dairy and pharmaceutical processing applications. Michigan's automotive supplier networks maintain approved abrasive supplier lists dictating procurement specifications for Tier-1 contracts.
China
MIIT industrial upgrading initiatives are accelerating substitution of conventional aluminum oxide with ceramic grain architectures in high-speed precision applications. Dual carbon goals are pressuring bonding material suppliers to reduce curing oven energy intensity. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate optical component polishing demand for smartphone camera lens production.
India
PLI scheme incentives for automotive component manufacturing are generating greenfield demand for finishing abrasives in Pune and Chennai corridors. BIS certification requirements for industrial abrasives are tightening market access for imported bonding systems. Tamil Nadu's supplier parks are expanding precision grinding capacity to serve export-oriented EV motor shaft finishing contracts.
Japan
METI technology roadmaps for advanced manufacturing are driving specification escalation toward nanometer-scale surface roughness control in optical glass polishing. JIS standards for bonded abrasives function as baseline procurement criteria for domestic precision engineering customers. Osaka-Kobe industrial zone maintains concentrated demand for sub-micron polishing pads serving smartphone lens and AR waveguide manufacturers.
Global Rubber Bonded Abrasive Market Competitive Landscape
Capital-heavy producers with captive rubber compounding and curing infrastructure compete with asset-light designers outsourcing bonding matrix formulation to specialized chemical suppliers. The market structures around three tiers: integrated multinationals controlling synthetic rubber feedstock costs, mid-scale specialists anchoring regional distribution networks, and commodity assemblers serving price-sensitive job shops. Strategic moves concentrate on backward integration into raw material supply and geographic expansion through distributor acquisition rather than greenfield manufacturing.
Within the integrated multinational tier, Saint-Gobain Abrasives and 3M exemplify players leveraging vertically controlled raw material networks to manage synthetic rubber cost volatility. Tyrolit Group anchors Central European distribution channels through specialized automotive finishing portfolios. Among precision-focused specialists, PFERD occupies a position exemplifying application-engineered grinding wheel development for metal fabrication markets.
| Leading Market Players |
|---|
| PFERD |
| Carborundum Universal |
| 3M |
| KURE Grinding Wheel |
| Noritake |
| Saint-Gobain Abrasives |
| Abrasivos Manhattan |
| Schwarzhaupt GmbH & Co. KG |
| Tyrolit Group |
| Others |
Supply & Pricing Matrix
Tier-1 automotive supplier concentration in Germany's industrial corridor anchors contract-based long-term offtake agreements that lock in volume commitments and insulate premium-grade wheel producers from spot price volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-validated low-VOC formulations from conventional REACH-compliant grades and commodity natural-rubber wheels. Price differentiation hinges on certification tier and lot-to-lot synthetic rubber consistency. Cost compression in economy-grade natural rubber wheels is intensifying because Malaysian feedstock supply volatility feeds through to compounders. Job shop metal fabricators exhibit highest price sensitivity, while optical component polishers accept specification premiums for sub-micron surface control.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich automotive supplier parks, while specialized distributors serve precision engineering clusters. Manufacturing gravity centers on Germany, China, and India, with synthetic rubber feedstock drawing from petrochemical complexes in South Korea and Japan. Supply chain risk concentrates in single-source vulnerability for ceramic grain architectures from limited qualified producers. Distribution runs through vendor-managed inventory programs mandated by German automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EV powertrain tolerance tightening toward sub-micron specifications is elevating demand for premium-grade synthetic rubber bonded wheels with validated thermal stability.
For Market Incumbents: Extend backward integration into captive synthetic rubber compounding to buffer naphtha and butadiene feedstock volatility. Lock in IATF 16949 certification renewals ahead of Tier-1 supplier list consolidation. Diamond and CBN superabrasive substitution in high-value precision applications threatens conventional aluminum oxide wheel margins, demanding ceramic grain R&D investment to defend specification relevance. For New Entrants and Emerging Players: The mid-tier price gap between Saint-Gobain's premium synthetic rubber wheels and commodity natural rubber assemblers opens white-space for SBR-nitrile hybrid formulations with REACH-validated chemistry. Target India's Pune and Chennai automotive supplier corridors where PLI scheme incentives are greenfielding finishing capacity without entrenched supplier relationships. Lead with optical glass polishing pad specialization to bypass automotive certification barriers. For Investors and Strategic Acquirers: Specialty chemical conglomerates with rubber compounding expertise are the most active acquirer in this space, seeking abrasive application outlets for captive polymer capacity. Five-to-ten year viability rests on formulation chemistry IP and regional distribution density rather than manufacturing scale. Watch for ECHA REACH enforcement actions on polycyclic aromatic hydrocarbon violations as signal for incumbent formulation obsolescence and replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Compounding | Captive nitrile and SBR supply secures margin control against petrochemical volatility. |
| REACH-Compliant Formulation Validation | ECHA deadlines are eliminating incumbent aromatic-rich bonding chemistries from European supply. |
| Ceramic Grain Architecture Adoption | Seeded-gel aluminum oxide compresses cycle times for aerospace turbine blade finishers. |
| Vendor-Managed Inventory Programs | German automotive OEM mandates are displacing spot purchasing through direct line-feed arrangements. |
| Optical Polishing Pad Specialization | Sub-micron surface specifications for AR waveguides and smartphone lenses command specification premiums. |
Research Methodology
Multiple input streams — procurement director interviews at Tier-1 automotive suppliers, technical consultations with rubber compounding chemists, and trade data reconciliation — were synthesized with secondary validation from ECHA regulatory filings, MIIT industrial upgrading directives, and customs records. Primary fieldwork captured plant manager perspectives at grinding wheel manufacturing facilities and distribution channel partners serving metal fabrication job shops. Bottom-up unit economics and top-down sectoral demand models were cross-referenced for convergence.
Historical consumption patterns were benchmarked against panel input from precision engineering procurement leads to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type, bonding material chemistry, application severity, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted demand curves incorporating EV manufacturing ramp rates and optical component polishing intensity. Industry-specific forecast inputs captured REACH compliance deadline impacts and ceramic grain substitution velocity.
Caveats apply where ECHA enforcement stringency, synthetic rubber feedstock price spikes, or superabrasive cost reductions could materially shift the outlook. Forecasts embed assumptions regarding regulatory timeline adherence and technology adoption curves. Periodic stress-testing of base assumptions against automotive production data and chemical regulatory announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Tools Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Super Abrasives Market
Abrasives
Abrasive Rolls Market
Abrasives
Global Abrasives Market
Abrasives
RDP Powder Market
Abrasives
Australia Abrasives Market
Abrasives
Synthetic Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Abrasive Tools Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Abrasive Grains Market
Abrasives
Europe Abrasives Market
Abrasives
Global Ceramic Flap Disc Market