
 Coated Abrasives Market | 2026-2036
Coated Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Abrasives Market Analysis
The gap between premium ceramic-grain products and commodity aluminum oxide lines is consolidating as tier-one manufacturers internalize binder chemistry and grain sourcing while smaller producers retreat to private-label distribution. Saint-Gobain leverages fused mineral research across its European production network to sustain pricing power in aerospace finishing. Klingspor anchors its position through deep inventory programs at German distributor partners. Bosch competes by integrating abrasive output into its power tool ecosystem, locking aftermarket demand.
Coated abrasives consist of a backing material—paper, cloth, or polyester—bonded with a layer of abrasive grains via resin or glue adhesives, with open-coat or closed-coat configurations determining cut rate and finish quality; the primary purpose is controlled material removal across metal, wood, and composite surfaces. Flap discs now lead growth in metalworking fabrication shops where operators prioritize single-step grinding-to-finishing workflows. Silicon carbide occupies the premium tier in glass and stone polishing applications where hardness dictates performance. Woodworking demand for aluminum oxide sheets remains mature, with margin pools shifting toward custom-width rolls for automated sanding lines.
FDA oversight of food-contact surfaces and OSHA permissible exposure limits for respirable crystalline silica directly shape product design and workplace deployment protocols in US manufacturing plants. REACH registration requirements in Europe restrict certain phenolic resin precursors, pushing suppliers toward water-based binder alternatives. EPA air quality standards for volatile organic compounds from coating operations add compliance costs that favor scaled producers with captive environmental controls. Stakeholders must monitor how evolving silica exposure thresholds and binder chemistry restrictions reshape the cost structure of commodity versus specialized product lines.
Market Dynamics
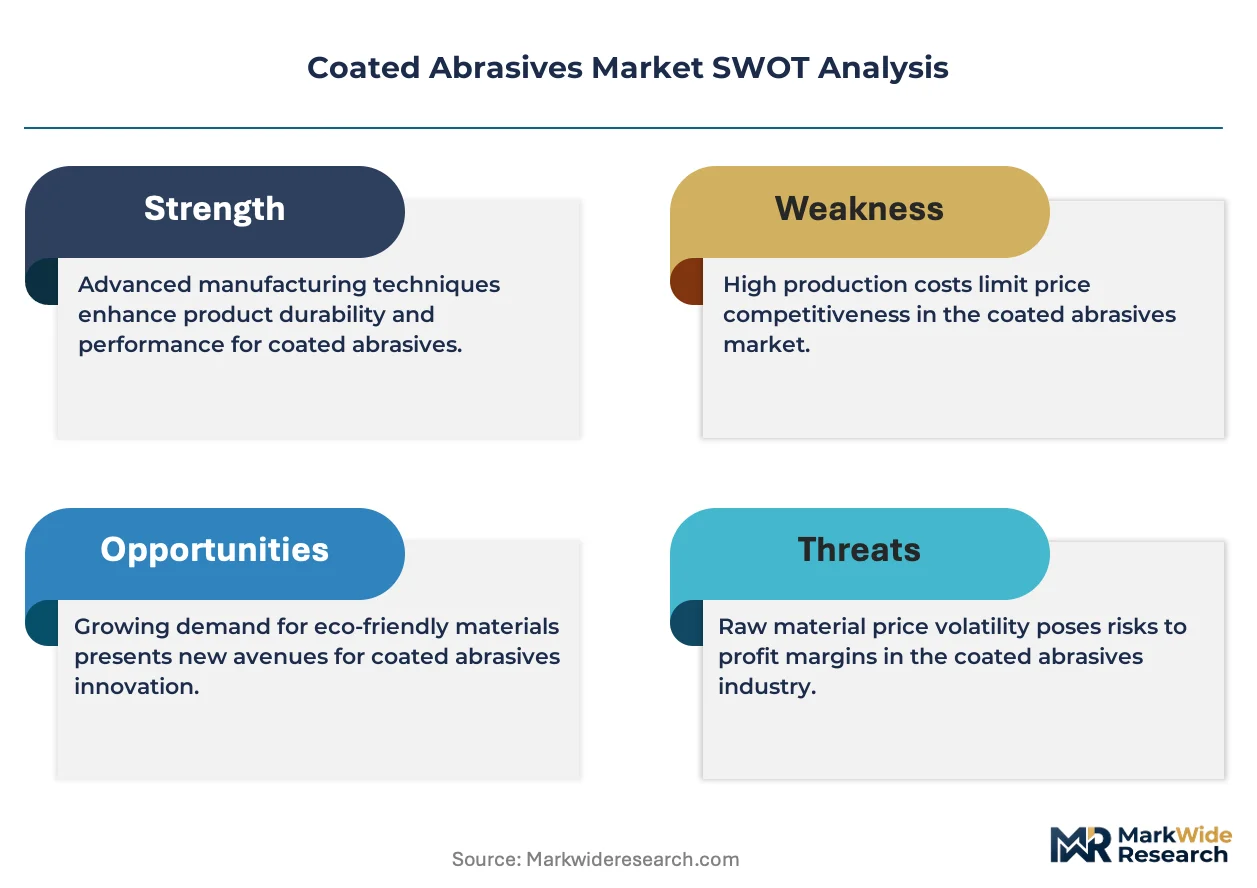
REACH compliance in Europe is forcing phenolic resin reformulation across the supply base, compressing margins for commodity producers while rewarding integrated manufacturers with captive binder chemistry capabilities.
Growth Catalysts
- Ceramic Grain Technology:Automotive refinishing shops now specify ceramic abrasives for collision repair, displacing aluminum oxide in high-precision metal removal applications.
- REACH Registration Requirements:ECHA mandates on phenolic resin precursors accelerate water-based binder adoption, creating first-mover advantages for compliant suppliers.
- Stuttgart Supply Corridor:Germany's automotive manufacturing belt concentrates demand for precision-coated abrasives in automated finishing systems.
Market Restraints
- Fused Mineral Cost Volatility:Energy-intensive production of aluminum oxide and silicon carbide exposes margins to electricity price swings in European smelting regions.
- Supply Concentration Risk:Three producers control the majority of high-purity ceramic grain output, creating bottleneck vulnerability for premium abrasive lines.
- Technical Limitation:Water-based binders underperform phenolic resins in high-heat grinding applications, restricting adoption in heavy metal fabrication.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for capital goods production attract abrasive suppliers to serve domestic automotive and metalworking growth.
- Composite Material Finishing:Wind turbine blade manufacturing creates demand for specialized abrasive configurations handling carbon fiber and epoxy resin.
- Digital Inventory Integration:German distributors deploy vendor-managed stock systems, locking in volume commitments through real-time consumption tracking.
Industry Challenges
- Binder Chemistry Expertise Gap:Formulation chemists with REACH-compliant phenolic resin experience command premium compensation, constraining mid-tier producer hiring.
- Environmental Control Capex:EPA volatile organic compound standards require scrubber and thermal oxidizer investments that favor scaled coating operations over smaller competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Abrasives Market |
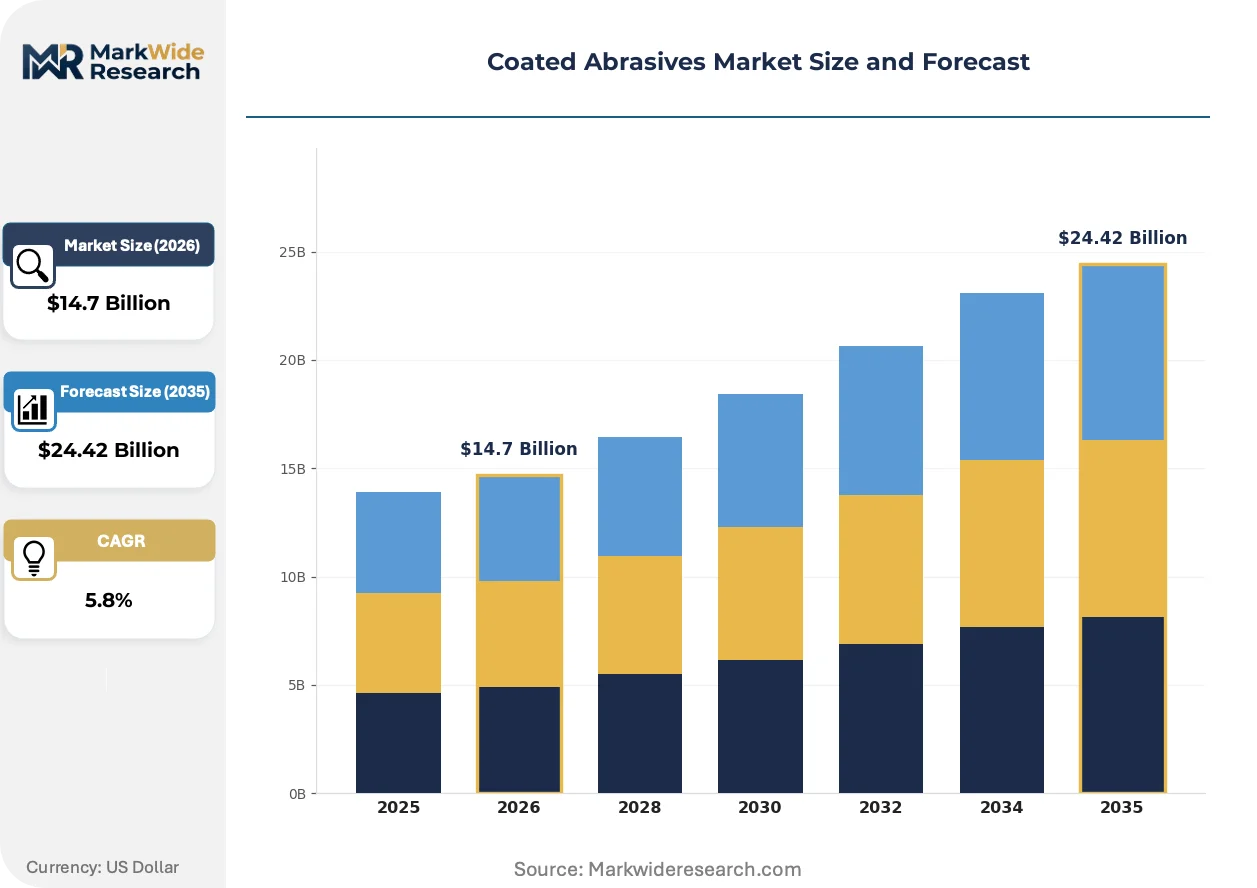
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandpaper, Abrasive Discs, Abrasive Sheets, Flap Discs Material: Aluminum Oxide, Silicon Carbide, Diamond, Zirconia End User: Automotive, Metalworking, Construction, Woodworking Application: Surface Finishing, Grinding, Polishing, Deburring |
| Companies Covered | 3M, Saint-Gobain, Robert Bosch GmbH, Norton Abrasives, Klingspor, Mirka, Carborundum Universal, Hermes Schleifmittel, Fujimi Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Abrasives Market Emerging Trajectories
Coated abrasives are undergoing material science transformation as ceramic grain technology matures and regulatory pressure on traditional binders intensifies, reshaping competitive advantage toward integrated supply chains.
Ceramic abrasive grains engineered with micro-fracturing properties deliver consistent cut rates across extended use cycles. Aerospace finishing operations and automotive collision repair facilities adopt these materials for single-step material removal workflows. Saint-Gobain's fused mineral research network is integrating proprietary grain geometries across its European production footprint, compressing the performance gap between premium and standard product tiers.
REACH restrictions on phenolic resin precursors force systematic binder reformulation throughout the European supply base. ECHA registration requirements eliminate certain formaldehyde-based crosslinkers from coating formulations. Suppliers with captive water-based adhesive development capabilities capture volume from import-dependent competitors facing compliance delays.
Flap disc configurations now dominate metalworking fabrication as operators prioritize grinding-to-finishing workflows that reduce tool change frequency. Independent job shops and contract manufacturers consolidate abrasive purchases through integrated distributor programs. German automotive supply chain participants demonstrate the strongest adoption velocity, driven by just-in-time production requirements and specification standardization across tiered supplier networks.
Coated Abrasives Market Segmentation
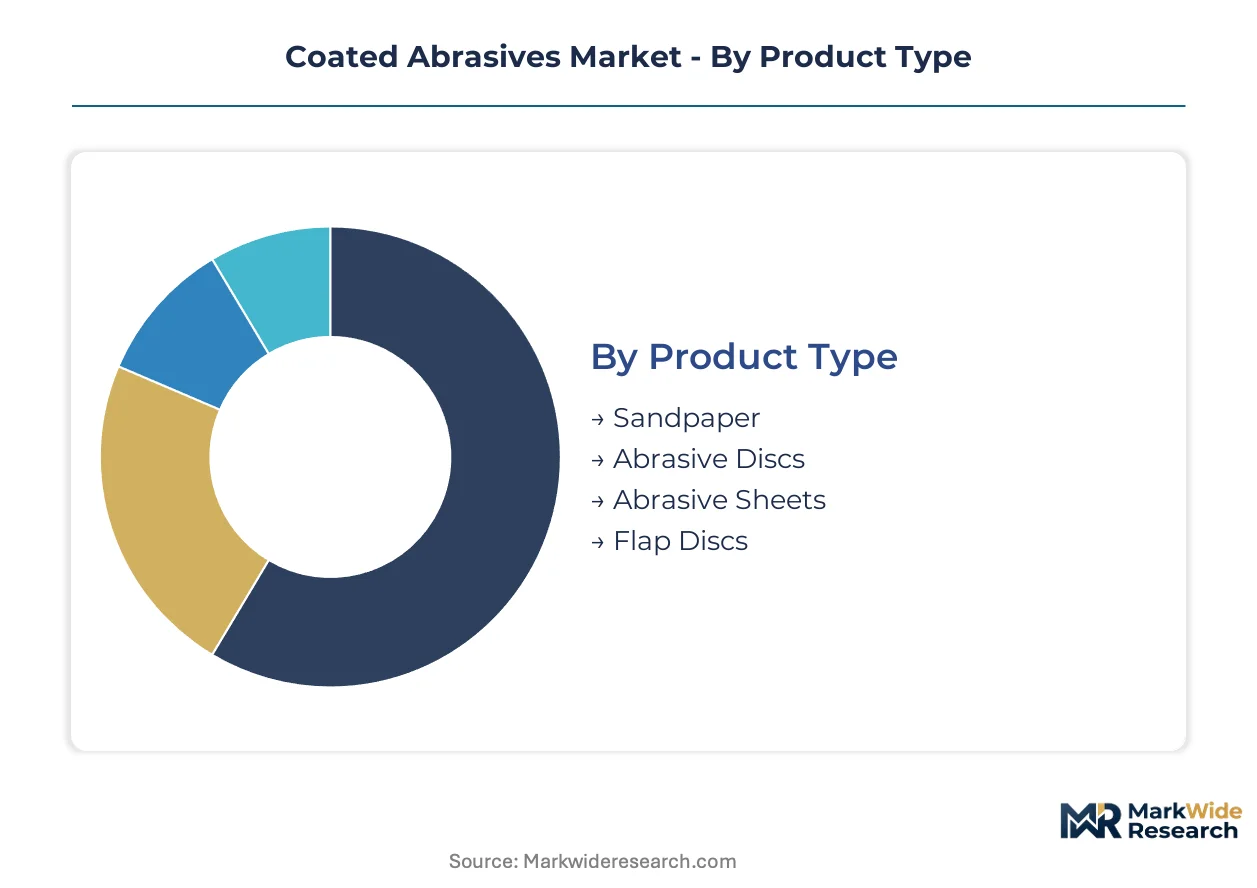
Coated abrasives serve heterogeneous workflows across metal removal, surface preparation, and precision finishing. Segment boundaries reflect divergent technical requirements, regulatory exposure, and procurement economics that reshape supplier positioning.
Product Type:
Grain geometry and backing flexibility define performance ceilings across handheld, automated, and robotic deployment modes.
- Flap Discs:Layered abrasive flaps mounted on fiberglass or plastic backplates enable single-step grinding-to-finishing transitions. Metalworking fabrication shops in Germany's Stuttgart corridor specify these configurations to minimize tool change downtime in high-mix production.
- Abrasive Discs:PSA-backed or hook-and-loop fastening systems mount on random orbital and angle grinders for controlled material removal. Automotive collision repair facilities specify ceramic-grain variants for aluminum panel preparation where heat generation must stay below substrate distortion thresholds.
- Sandpaper:Paper or cloth backing with resin-bonded grains serves woodworking and general-purpose metal sanding applications. OSHA respirable crystalline silica rules shape workplace deployment protocols in US manufacturing plants.
- Abrasive Sheets:Large-format rolls and cut-to-size sheets feed automated sanding lines in furniture and flooring manufacturing. Custom-width configurations command margin premiums over standard dimensions.
Flap discs lead on scale; abrasive discs lead on momentum.
Material:
Hardness, fracture behavior, and thermal stability determine application-matching economics across substrate types.
- Aluminum Oxide:Fused mineral production yields durable grains for ferrous metal and wood sanding at moderate cost. Energy-intensive smelting in European regions exposes pricing to electricity volatility.
- Silicon Carbide:Harder-than-alumina crystalline structure enables glass, stone, and non-ferrous metal polishing where scratch resistance dictates specification. REACH-compliant phenolic resin binders face reformulation pressure for these high-precision applications.
- Zirconia:Self-sharpening grain structure maintains cut rates through extended use cycles in heavy stock removal. Foundry and weld grinding operations specify zirconia for reduced abrasive consumption per unit of material removed.
- Diamond:Superabrasive grains bonded to rigid backplates handle carbide, ceramic, and hardened steel where conventional minerals glaze or fracture. Concentrated supply among three producers creates bottleneck vulnerability for premium product lines.
Aluminum oxide dominates volume; ceramic-engineered variants gain share fastest.
End User:
Procurement sophistication and specification authority vary sharply across OEM-integrated versus independent operator channels.
- Automotive:Tier-one suppliers and collision repair networks drive ceramic abrasive adoption through standardized process specifications. ECHA registration requirements accelerate water-based binder qualification for European assembly plants.
- Metalworking:Job shops and contract manufacturers consolidate purchases through distributor-managed inventory programs. Flap disc configurations displace separate grinding and finishing operations to reduce cycle times.
- Construction:On-site grinding and surface preparation demand portable, dust-controlled abrasive systems. EPA air quality standards for volatile organic compounds from coating operations favor scaled suppliers with captive environmental controls.
- Woodworking:Automated sanding lines in furniture and flooring manufacturing specify custom-width abrasive rolls. Aluminum oxide sheets remain mature with margin pools shifting toward engineered grain geometries for premium finishing.
Automotive commands specification authority; metalworking delivers volume scale.
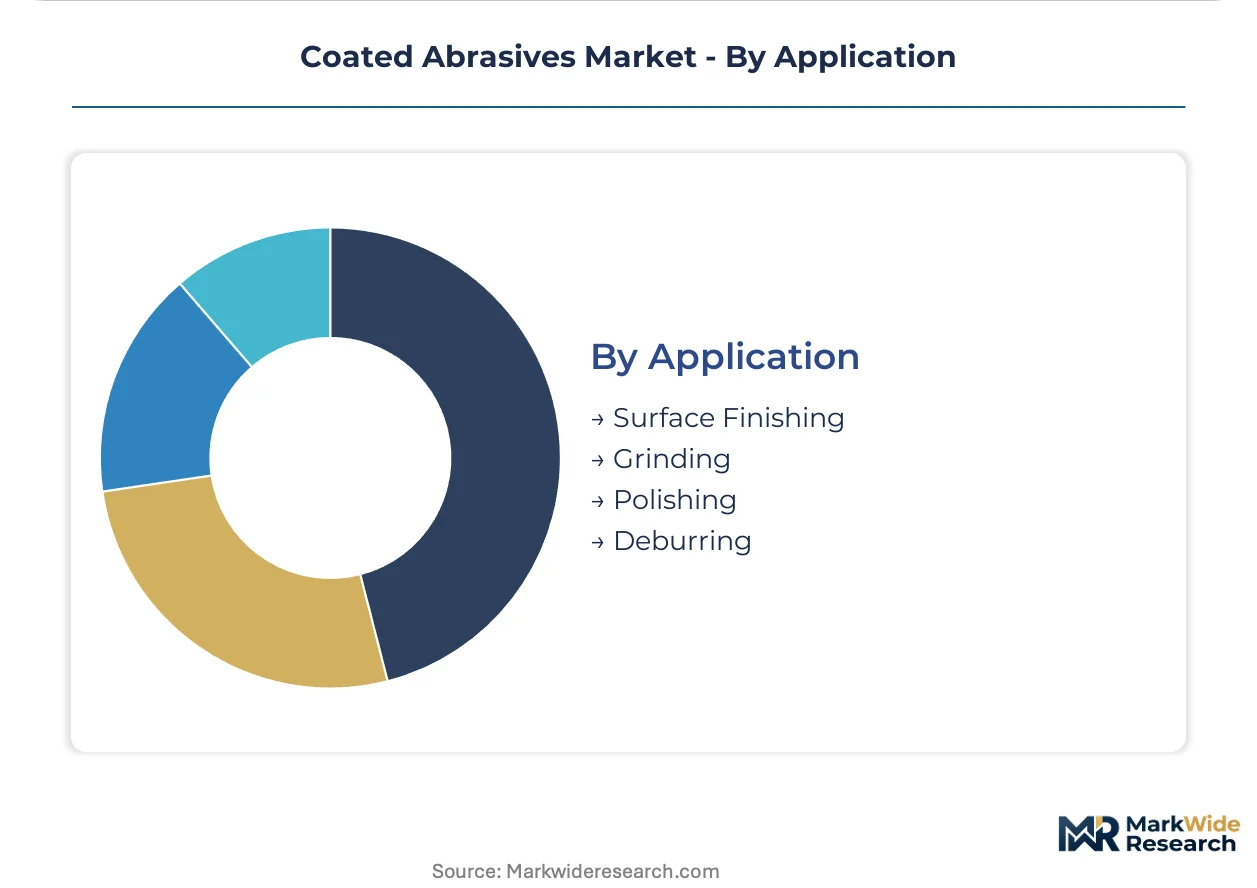
Application:
Material removal rate and surface integrity requirements dictate grain selection, binder chemistry, and backing construction.
- Surface Finishing:Controlled scratch pattern generation for paint adhesion and aesthetic quality. Aerospace finishing operations specify ceramic grains for titanium and composite substrate preparation.
- Grinding:Aggressive stock removal with heat management for metallurgical integrity. Water-based binder underperformance in high-heat applications restricts adoption in heavy fabrication.
- Polishing:Final-stage surface refinement to specified roughness averages. Silicon carbide dominates glass and stone applications where hardness differential drives performance.
- Deburring:Edge break and burr removal from machined, cast, or welded components. Automated robotic cells in automotive powertrain manufacturing specify engineered grain configurations for process consistency.
Grinding anchors volume demand; surface finishing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists with REACH-compliant phenolic resin expertise cluster in Germany's industrial belt, anchoring European supply capabilities while Asian manufacturing centers scale ceramic grain production capacity.
Germany
Automotive collision repair networks and aerospace finishing operations drive ceramic abrasive consumption. ECHA registration requirements on formaldehyde-based crosslinkers accelerate water-based binder qualification timelines. Stuttgart's automotive supply corridor concentrates demand for precision-coated abrasives in automated finishing systems serving Mercedes-Benz and Porsche assembly plants.
United States
Metalworking fabrication shops and construction surface preparation crews sustain volume demand for flap disc configurations. OSHA permissible exposure limits for respirable crystalline silica reshape workplace deployment protocols in manufacturing plants. EPA volatile organic compound standards favor scaled coating operations with captive environmental controls in Ohio and Pennsylvania industrial zones.
China
Wind turbine blade manufacturing and domestic automotive production expand addressable market for specialized abrasive configurations. MIIT industrial upgrading policies incentivize advanced materials manufacturing capabilities. Yangtze River Delta industrial clusters concentrate aluminum oxide smelting capacity exposed to electricity price volatility.
India
Domestic automotive assembly and capital goods production attract abrasive supplier manufacturing investments. PLI scheme incentives for automotive component manufacturing strengthen downstream demand visibility. Maharashtra and Gujarat industrial corridors host expanding metalworking fabrication capacity requiring abrasive consumables.
Japan
Precision electronics finishing and automotive supplier networks sustain demand for engineered grain geometries. METI carbon neutrality roadmaps pressure energy-intensive fused mineral production operations. Kansai region abrasive manufacturers face input cost pressure from electricity market liberalization.
Coated Abrasives Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across tiered market positions. Integrated manufacturers with captive binder chemistry capabilities capture margin from commodity import-dependent competitors facing REACH compliance delays. Three strategic archetypes dominate: European heritage specialists with deep distributor relationships, Asian scale producers leveraging integrated mineral supply, and diversified industrial conglomerates bundling abrasives into tool ecosystems. Capacity expansion and portfolio diversification toward ceramic-engineered products represent the dominant competitive vectors reshaping supply-side positioning.
Among heritage European specialists, Saint-Gobain and Klingspor occupy positions defined by fused mineral research networks and distributor inventory programs respectively. Robert Bosch GmbH exemplifies the conglomerate archetype, integrating abrasive output into power tool ecosystems to lock aftermarket demand. These three anchors illustrate how competitive advantage concentrates in formulation chemistry expertise, supply chain integration depth, and end-use ecosystem control rather than manufacturing scale alone.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Robert Bosch GmbH |
| Norton Abrasives |
| Klingspor |
| Mirka |
| Carborundum Universal |
| Hermes Schleifmittel |
| Fujimi Incorporated |
| Others |
Supply Flow & Price Mechanics
Phenolic resin precursor costs transmit directly from European chemical suppliers through three pricing tiers—premium ceramic-grain formulations, standard aluminum oxide lines, and economy-grade private-label products—compressing margins at each downstream step as REACH compliance expenses accumulate.
Pricing Analysis
Bundled distributor-managed inventory programs command premium positioning against unbundled spot purchases in German automotive corridors. Three-tier pricing structure across premium, standard, and economy levels reflects grain geometry sophistication and binder chemistry certification. Cost compression in commodity aluminum oxide lines is intensifying because energy-intensive fused mineral production exposes European smelters to electricity volatility. Independent metalworking job shops exhibit highest price sensitivity; aerospace finishing operations demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with high-purity ceramic grain output concentrated among three producers. Manufacturing gravity centers on Germany, China, and the United States for coating operations and fused mineral production. The supply chain draws from bauxite/alumina feedstocks, phenolic resin precursors, and specialized backing substrates. Tariff exposure on Chinese aluminum oxide imports creates structural risk for North American coating operations. Distribution runs through German distributor partnerships with vendor-managed inventory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between European REACH compliance costs and Asian manufacturing scale, with phenolic resin reformulation expenses in Germany running substantially above water-based binder qualification timelines in Indian PLI-subsidized corridors.
For Market Incumbents: Lock in ceramic grain supply agreements before three-producer concentration tightens further. Secure captive binder chemistry capabilities to defend against water-based formulation specialists capturing European volume. Add coating capacity in Maharashtra or Gujarat to arbitrage labor and environmental compliance costs against Stuttgart corridor operations.
For New Entrants and Emerging Players: Ceramic-engineered flap disc configurations for wind turbine blade finishing offer the most penetrable white-space target, with composite material abrasive demand outpacing established supplier qualification cycles. Enter through Indian automotive component manufacturing clusters where PLI scheme visibility reduces customer acquisition friction. Lead with water-based binder expertise to capture European import-dependent competitors facing REACH delays.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier producers lack captive phenolic resin reformulation capabilities and distributor inventory program scale. Five-to-ten year viability favors integrated manufacturers with backward control over grain sourcing and binder chemistry. Target acquisition archetype: European heritage specialists with stranded mineral processing assets and established automotive distributor relationships. Watch ceramic grain supply agreement renewal rates as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Mineral Production | Captive aluminum oxide smelting insulates Saint-Gobain from European electricity volatility. |
| Water-Based Binder Qualification Program | ECHA-compliant adhesive development unlocks volume from REACH-delayed import competitors. |
| Vendor-Managed Inventory Partnership | Klingspor's German distributor programs convert specification authority into locked recurring revenue. |
| Ceramic Grain Capacity Expansion | Three-producer concentration creates bottleneck vulnerability for premium abrasive lines serving aerospace. |
| Power Tool Ecosystem Integration | Bosch bundles abrasive output with cordless grinder platforms to capture aftermarket replacement demand. |
Methodological Framework
Direct dialogue with coating plant managers, automotive procurement leads at Tier 1 suppliers, German distributor inventory specialists, and REACH compliance officers anchored qualitative foundations. Secondary validation drew from ECHA registration databases, SEC 10-K filings of listed abrasive manufacturers, German automotive production statistics, and customs trade data on aluminum oxide imports. Bottom-up volume modeling triangulated against top-down market sizing across grain type, backing material, and end-use industry segments.
Bottom-up shipment analysis by product configuration and grain chemistry combined with top-down macroeconomic elasticity modeling across the projection horizon. Segmentation dimensions included abrasive type, material hardness tier, end-use industry procurement sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit trends. Forecast inputs incorporated REACH compliance cost pass-through rates and ceramic grain adoption curves in automotive collision repair.
The model holds under stable regulatory enforcement timelines and continued automotive production clustering in Germany; deviation in ECHA registration deadline extensions or Chinese electricity market reforms would shift volume and value trajectories. Forecasts reflect documented assumptions on binder chemistry substitution rates and distributor program penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Tungsten Carbide Balls Market
Abrasives
Australia Abrasives Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Liquid Sandpaper Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Polishing Chemicals Market
Abrasives
New Zealand Abrasives Market
Abrasives
Artificial Abrasives Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Bonded Abrasive Market
Abrasives
Metal Abrasives Market
Abrasives
RDP Powder Market
Abrasives
Calcined Shale Market
Abrasives
Fine Sandpaper Market
Abrasives
Chemical Deflasher Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market