
 White Mineral Oil Market | 2026-2036
White Mineral Oil Market Size, Share, and Industry Trends Forecast 2026-2036
White Mineral Oil Market Intelligence
Market Context
China is fragmenting white mineral oil supply as new refining complexes in Shandong and Guangdong add technical-grade capacity alongside established pharmaceutical-grade producers. ExxonMobil leverages integrated base oil infrastructure across the US Gulf Coast to sustain high-purity output for regulated applications. Sonneborn specializes in hydrogenated white oils for cosmetics and food-contact segments, competing on certification breadth rather than volume scale. Sasol anchors African supply through its Fischer-Tropsch-derived wax and oil complex in Secunda, exporting to European personal care formulators.
Technical Profile and Segment Structure
White mineral oil comprises saturated aliphatic and naphthenic hydrocarbons refined from petroleum distillates through severe hydrotreating or acid treatment, yielding colorless, odorless liquids with viscosity ranges from 7 to 30 cSt at 40°C and UV absorbance limits defined by USP and FDA 21 CFR 172.878. These properties make it indispensable as a lubricant, laxative base, moisture barrier, and process aid across pharmaceutical tablet coating, cosmetic emulsions, and food machinery protection. Light mineral oil leads pharmaceutical and cosmetic applications where low viscosity and high purity command premium positioning, while heavy mineral oil occupies industrial lubricant segments where cost efficiency outweighs certification intensity. Food-grade white oils represent the fastest-growing application tier as global food safety regulators tighten machinery lubricant incidental contact standards.
Regulatory Environment and Outlook
FDA 21 CFR 172.878 and 178.3620(a) govern US food-contact and direct-additive use, while REACH and EU Regulation 231/2012 set purity thresholds for European pharmaceutical and cosmetic incorporation. BIS IS 335 standards and CDSCO excipient guidelines shape Indian market access, with recent amendments aligning more closely with USP-NF monographs. The US EPA and state-level air quality boards are scrutinizing refining emissions from hydrotreater operations, adding compliance cost layers for capacity expansion. Stakeholders must monitor divergence between FDA and EMA purity testing protocols, as misalignment creates dual-certification burdens that favor suppliers with existing multi-regional laboratory infrastructure.
Market Dynamics
Pharmaceutical-grade white mineral oil supply is tightening as hydrotreater capacity expansion lags behind formulation demand from topical drug manufacturers seeking USP-certified excipients.
Growth Catalysts
- FDA 21 CFR 178.3620(a) incidental contact standards:Food machinery lubricant specifications are tightening across US processing facilities, forcing upgrades to technical-grade white oils.
- India's CDSCO excipient alignment:Domestic pharmaceutical production is scaling capacity rapidly as BIS IS 335 amendments converge with USP-NF monographs, opening export pathways.
- Cosmetic emulsion formulation:Hydrogenated white oils are displacing petroleum-based alternatives in premium skincare as EU Regulation 231/2012 purity thresholds elevate certification requirements.
Market Restraints
- Crude oil feedstock volatility:Saturated aliphatic and naphthenic hydrocarbon costs fluctuate with refining margins, compressing margin stability for hydrotreated output.
- Shandong-Guangdong supply fragmentation:Technical-grade capacity additions in China's coastal refining complexes are flooding mid-tier segments without matching pharmaceutical-grade purity infrastructure.
- Plant-based lipid substitution:Cosmetic formulators are piloting squalane and jojoba oil alternatives in moisture-barrier applications where odorless properties are less critical.
Strategic Opportunities
- Brazil ANVISA pharmaceutical excipient registration:Latin American topical drug manufacturing remains underpenetrated by USP-grade suppliers despite expanding generic production.
- Dual-certification laboratory infrastructure:Multi-regional testing capabilities that bridge FDA and EMA protocol divergence command premium positioning as purity standard misalignment widens.
- Food-grade machinery lubricant channel consolidation:Direct technical service relationships with protein processing and bakery equipment OEMs are displacing commodity distributor networks.
Industry Challenges
- Hydrotreater emissions compliance:US EPA and state air quality board scrutiny is extending permitting timelines for capacity expansion projects by 18-24 months.
- UV absorbance testing standardization:Divergent FDA and EMA analytical protocols force duplicate certification runs, straining laboratory throughput and validation documentation.
- Legacy tablet coating equipment compatibility:Pharmaceutical manufacturers face reformulation costs when migrating from established mineral oil grades to higher-purity alternatives with altered viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Mineral Oil Market |
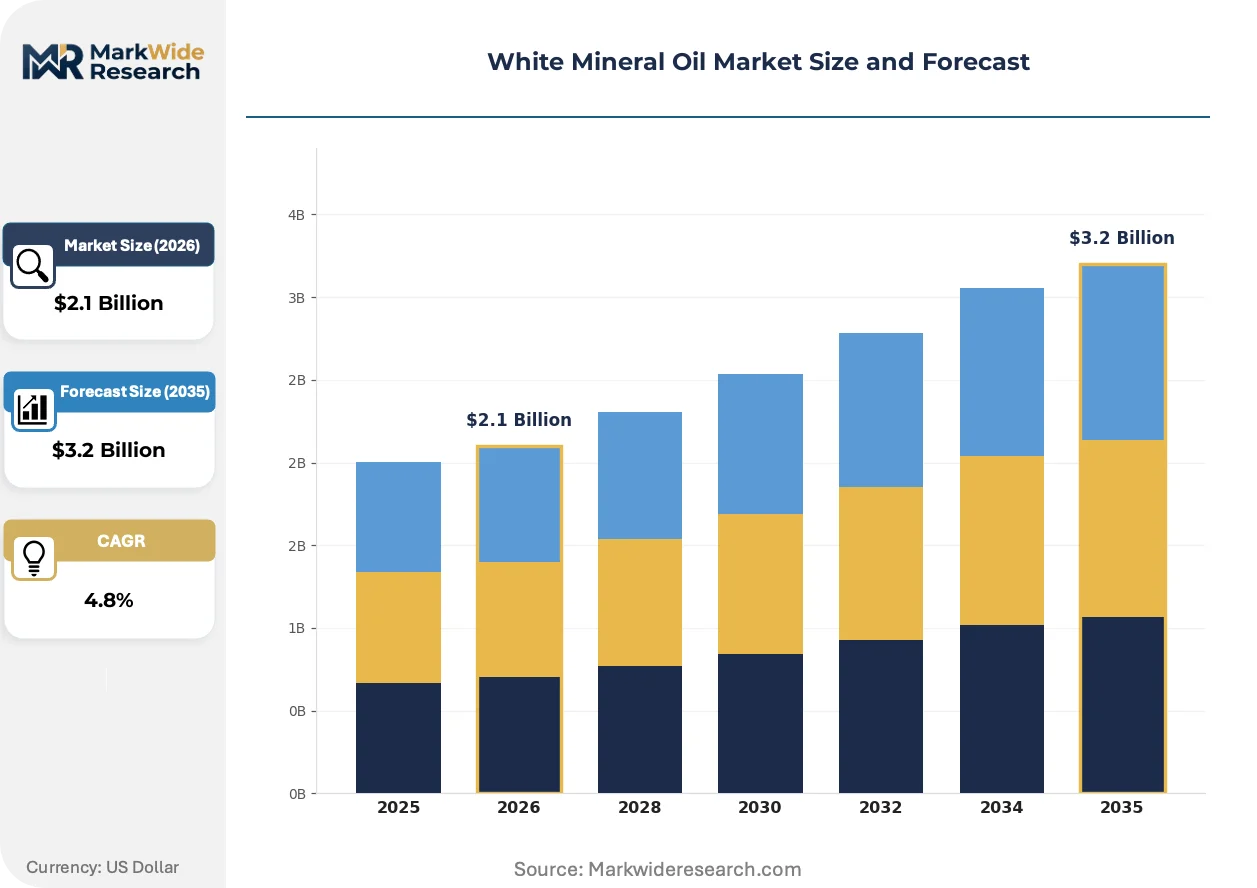
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
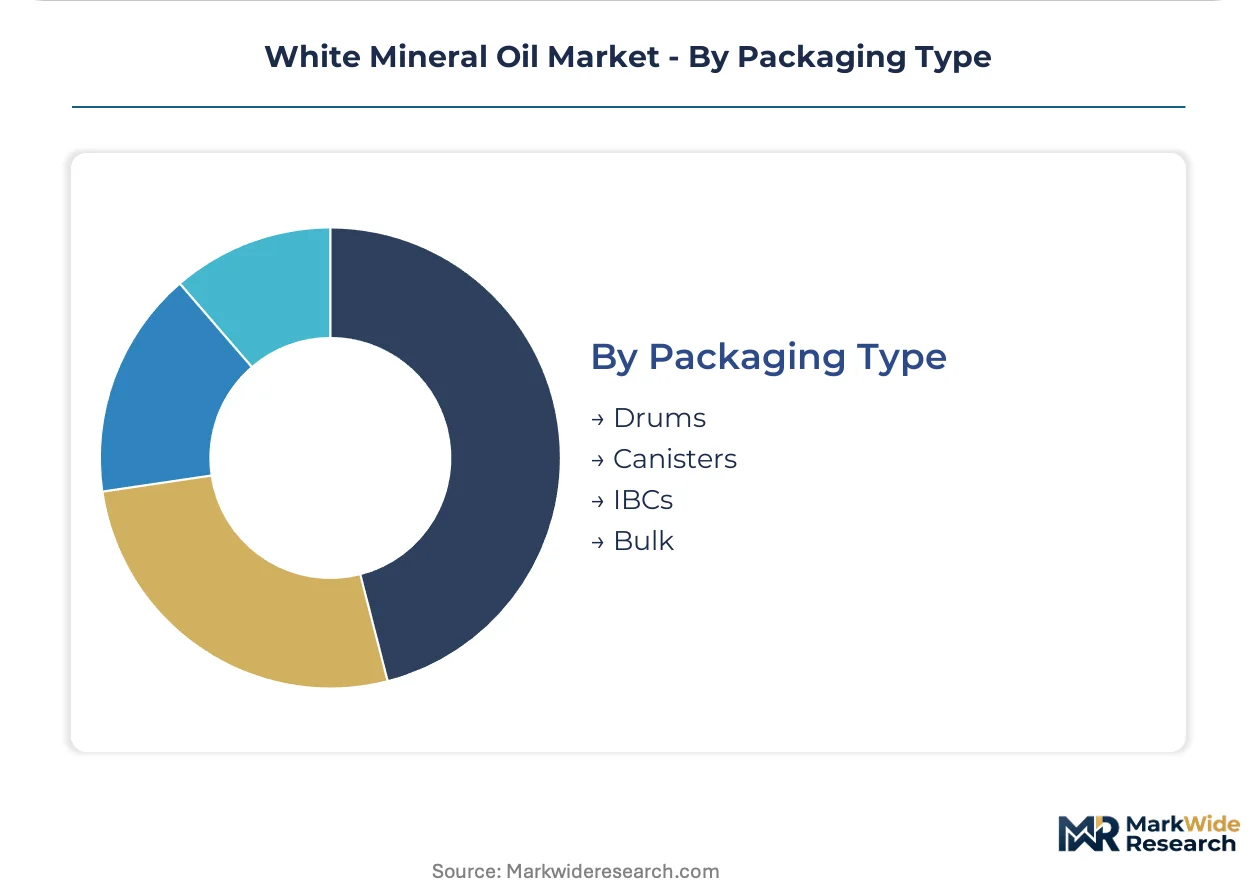
| Segmentation | Product Type: Light Mineral Oil, Heavy Mineral Oil, White Oils, Liquid Paraffin Application: Cosmetics, Pharmaceuticals, Food Industry, Industrial Lubricants End User: Personal Care, Healthcare, Food Manufacturing, Chemical Processing Packaging Type: Drums, Canisters, IBCs, Bulk |
| Companies Covered | ExxonMobil Corporation, Sonneborn LLC, Calumet, Inc., China Petroleum & Chemical Corporation (Sinopec), Chevron Corporation, Phillips 66 Company, Sasol Limited, Renkert Oil, Nynas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Mineral Oil Market Strategic Shifts & Innovations
Refining technology and regulatory protocol evolution are compressing the viable supply base for high-purity white mineral oils while opening differentiated positioning for certification-capable producers.
Membrane filtration-assisted hydrotreating is collapsing the capital threshold for achieving USP-grade UV absorbance specifications. Mid-scale refiners in India and Southeast Asia are adopting hybrid purification trains that bypass conventional severe hydrotreater investments. This technology compression is fragmenting pharmaceutical-grade supply away from integrated majors toward specialized regional processors.
REACH substance evaluation under ECHA's 2023-2025 work program is tightening polycyclic aromatic hydrocarbon limits for cosmetic-grade white oils. European personal care formulators are demanding enhanced certificates of analysis documenting sub-ppm PAH content. The regulatory pressure is accelerating laboratory outsourcing to third-party testing houses with GC-MS capabilities in Germany and Switzerland.
Direct procurement relationships between pharmaceutical excipient buyers and refinery technical teams are displacing traditional chemical distributor intermediaries. Large generic drug manufacturers in India are establishing technical service agreements specifying batch-to-batch viscosity consistency and accelerated stability testing. This channel compression is most visible in Hyderabad and Ahmedabad, where domestic formulation scale has reached vertical integration thresholds.
White Mineral Oil Market Segmentation
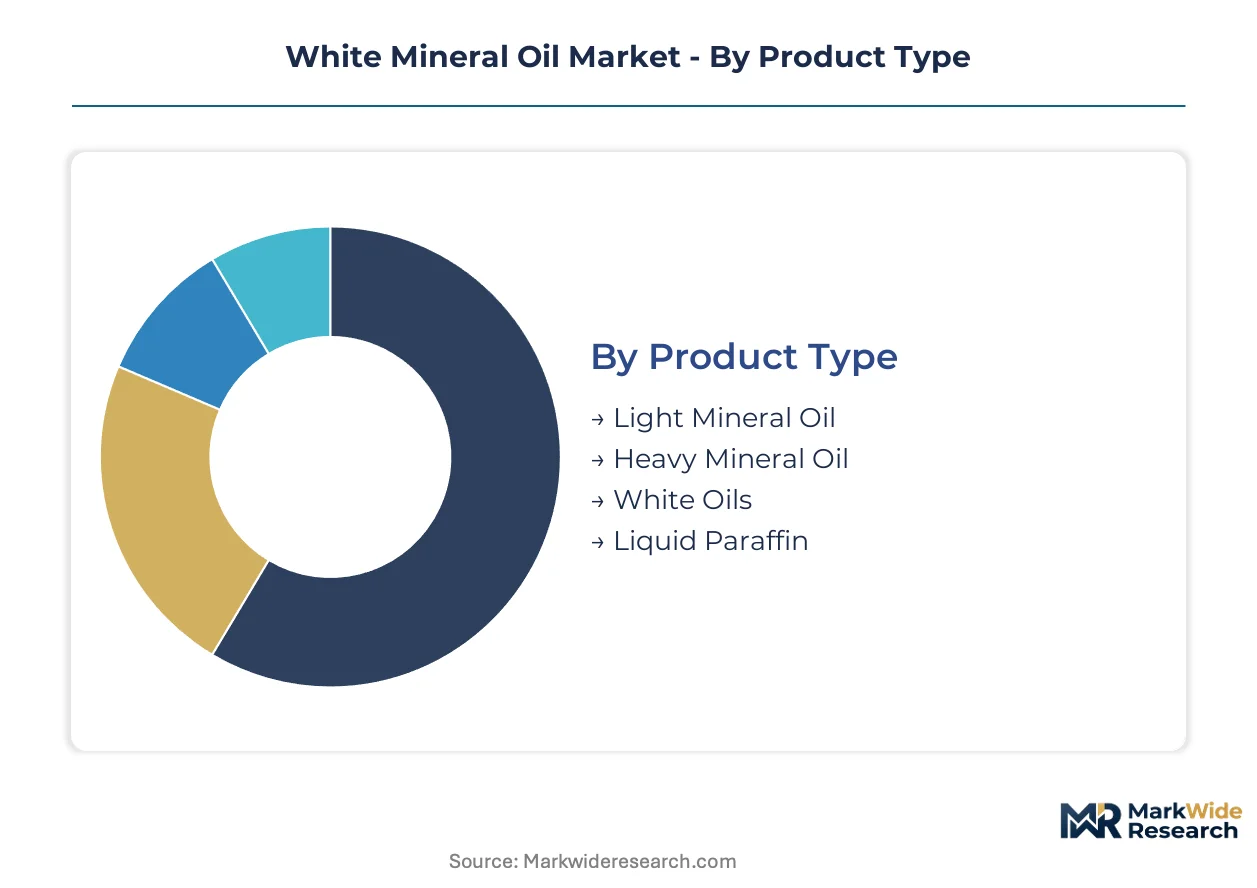
White mineral oil segmentation reflects divergent purity requirements across regulated industries. Certification thresholds and viscosity specifications create non-substitutable demand pockets that resist commoditization.
Product Type:
Mature refining technologies anchor established segments while emerging hydrotreatment advances reshape competitive access to pharmaceutical-grade specifications.
- Light Mineral Oil:Low-viscosity saturated aliphatic hydrocarbons refined through severe hydrotreating achieve USP-grade UV absorbance limits. Hyderabad pharmaceutical formulators specify light mineral oil for topical drug delivery systems as CDSCO excipient guidelines converge with USP-NF monographs.
- Heavy Mineral Oil:Higher viscosity naphthenic base stocks serve industrial lubricant segments where FDA 21 CFR 178.3620(a) compliance is unnecessary. Shandong refining complexes are flooding technical-grade heavy oil supply as new capacity lacks pharmaceutical-grade hydrotreater infrastructure.
- White Oils:Hydrogenated specialty grades command premium positioning in EU cosmetic applications under REACH PAH limits.
- Liquid Paraffin:British Pharmacopoeia-monographed variants dominate UK and Commonwealth laxative and emollient formulations.
Light mineral oil handles the majority of throughput; heavy mineral oil is the fastest mover on share as technical-grade capacity expands.
Application:
Cost tier stratification separates certification-intensive uses from volume-driven industrial segments.
- Pharmaceuticals:USP-grade excipients for tablet coating and oral drug delivery demand batch-to-batch viscosity consistency. Indian generic manufacturers in Ahmedabad are establishing direct technical service agreements with refiners to bypass distributor intermediaries.
- Cosmetics:Hydrogenated white oils displace petroleum alternatives in premium skincare as EU Regulation 231/2012 elevates purity documentation requirements. German and Swiss third-party laboratories with GC-MS capabilities are capturing outsourced PAH testing demand.
- Food Industry:FDA 21 CFR 172.878 direct-additive and 178.3620(a) incidental-contact grades face tightening machinery lubricant specifications across US protein processing facilities.
- Industrial Lubricants:Technical-grade white oils serve food machinery protection where cost efficiency outweighs certification intensity.
Pharmaceutical applications concentrate the highest value throughput; food-grade machinery lubricant demand is expanding most quickly as safety standards tighten.
End User:
Customer type determines procurement channel structure and technical service intensity.
- Healthcare:Hospital and clinical procurement of laxative bases and topical emollients requires USP documentation. CDSCO-aligned Indian manufacturers are scaling capacity for export to Latin American markets where ANVISA registration remains underpenetrated.
- Personal Care:Cosmetic formulators in European personal care clusters demand enhanced certificates of analysis with sub-ppm PAH documentation under ECHA substance evaluation timelines.
- Food Manufacturing:Protein processors and bakery equipment operators face forced upgrades to technical-grade white oils as FDA incidental contact standards tighten.
- Chemical Processing:Polymer and textile auxiliary applications utilize technical grades with lower certification burdens.
Healthcare commands the deepest technical service relationships; food manufacturing is gaining share fastest on regulatory-driven replacement cycles.
Packaging Type:
Volume scale and contamination risk shape packaging selection across the supply chain.
- Bulk:Tanker and railcar delivery serves high-volume pharmaceutical and food-grade users with dedicated storage infrastructure. Integrated US Gulf Coast refiners leverage pipeline networks to sustain bulk pharmaceutical-grade output.
- IBCs:Intermediate bulk containers balance volume efficiency with contamination control for mid-scale cosmetic formulators.
- Drums:Standard 55-gallon steel drums dominate chemical processing and smaller pharmaceutical compounders.
- Canisters:Small-format packaging serves retail pharmaceutical and personal care distribution with tamper-evident requirements.
Bulk packaging handles the majority of tonnage; IBC formats are climbing the fastest as mid-scale formulators seek contamination control without dedicated tankage investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US buyers prioritize FDA-certified pharmaceutical and food-contact grades. European demand centers on REACH-compliant cosmetic applications. Indian pharmaceutical formulators drive volume expansion as export capacity scales.
United States
Pharmaceutical tablet coating and food machinery lubricant applications dominate US consumption. FDA 21 CFR 172.878 and 178.3620(a) standards enforce strict UV absorbance and purity documentation. Gulf Coast refining clusters in Texas and Louisiana sustain integrated base oil infrastructure for high-purity output.
Germany
Cosmetic-grade white oils command premium positioning in personal care formulation. ECHA REACH substance evaluation and EU Regulation 231/2012 tighten polycyclic aromatic hydrocarbon limits. Cologne-Düsseldorf chemical clusters drive demand for enhanced certificates of analysis with sub-ppm PAH documentation.
India
Generic pharmaceutical manufacturing and domestic personal care production scale capacity rapidly. CDSCO excipient guidelines and BIS IS 335 amendments converge with USP-NF monographs. Hyderabad and Ahmedabad pharmaceutical hubs establish direct technical service agreements with refiners, bypassing distributor intermediaries.
China
Technical-grade capacity expansion outpaces pharmaceutical-grade infrastructure development. GB standards and SAMR food-contact regulations shape domestic market access. Shandong and Guangdong coastal refining complexes flood mid-tier segments without matching USP-grade hydrotreater investments.
Brazil
Latin American topical drug manufacturing remains underpenetrated by USP-grade suppliers despite expanding generic production. ANVISA pharmaceutical excipient registration requirements create compliance barriers. São Paulo pharmaceutical clusters seek import partnerships as domestic refining lacks certification infrastructure.
White Mineral Oil Market Key Industry Players
Capability concentration sits with integrated petrochemical majors; scale advantage sits with specialized regional processors. The market structures around three tiers: Gulf Coast-integrated refiners with base oil infrastructure, European hydrogenation specialists with cosmetic certification breadth, and emerging Asian processors adopting membrane filtration-assisted hydrotreating. Strategic moves center on dual-certification laboratory infrastructure investment and direct technical service relationships with pharmaceutical formulators.
Among integrated majors, ExxonMobil Corporation anchors the Gulf Coast tier with base oil infrastructure spanning Texas and Louisiana refining complexes. Sonneborn LLC occupies the hydrogenation specialist position, competing on certification breadth for cosmetics and food-contact segments. Sasol Limited represents the Fischer-Tropsch-derived supply archetype, anchoring African output for European personal care formulators. These three exemplify how geographic integration and certification capability determine competitive positioning.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Sonneborn LLC |
| Calumet, Inc. |
| China Petroleum & Chemical Corporation (Sinopec) |
| Chevron Corporation |
| Phillips 66 Company |
| Sasol Limited |
| Renkert Oil |
| Nynas AB |
| Others |
Cost & Logistics Intelligence
US Gulf Coast refining clusters anchor pharmaceutical-grade white mineral oil supply, concentrating margin capture with integrated majors while regional processors in India and Southeast Asia compete on membrane filtration-assisted hydrotreating economics. This upstream concentration shapes downstream pricing power across certification tiers.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade procurement as generic drug manufacturers in Hyderabad and Ahmedabad seek batch-to-batch viscosity consistency. Three-tier pricing structure across USP-certified, technical-grade, and industrial-grade levels reflects certification intensity and hydrotreater investment recovery timelines. Cost compression in technical-grade segments intensifies because Shandong and Guangdong capacity additions flood mid-tier supply without matching purity infrastructure. Food-grade machinery lubricant buyers exhibit highest price sensitivity as FDA 21 CFR 178.3620(a) compliance upgrades force budget-constrained facility conversions.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as Indian pharmaceutical formulators scale procurement volumes and negotiate supply-chain finance facilities. Production draws from the United States, China, and India as primary supply nodes, with feedstock anchored in saturated aliphatic and naphthenic hydrocarbon streams from petroleum distillates and Fischer-Tropsch synthesis. Single-source vulnerability concentrates around hydrotreater capacity expansion delays as US EPA emissions scrutiny extends permitting timelines. Distribution runs through direct technical service relationships with pharmaceutical formulators, displacing traditional chemical distributor intermediaries in high-value segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White mineral oil incumbents face substitution pressure from plant-based lipids in cosmetic moisture-barrier applications where odorless properties are less critical. Defending market position requires strategic moves across certification, capacity, and channel control.
For Market Incumbents: Entrench pharmaceutical-grade positioning through dual-certification laboratory infrastructure bridging FDA and EMA protocol divergence. Expand hydrotreater capacity at existing US Gulf Coast sites before emissions permitting timelines extend further. Plant-based lipid substitution in premium skincare represents the immediate threat; backward integration into base oil feedstock secures margin control against crude volatility. For New Entrants and Emerging Players: Build out membrane filtration-assisted hydrotreating capacity in India to serve CDSCO-aligned domestic pharmaceutical production scaling for export. Brazil ANVISA pharmaceutical excipient registration remains the most penetrable geography as Latin American topical drug manufacturing expands without local certification infrastructure. Target direct technical service agreements with mid-scale generic manufacturers seeking to bypass distributor intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward regional processors with existing multi-regional laboratory infrastructure and established relationships with pharmaceutical formulators. Long-term viability hinges on certification capability moats widening as purity standard divergence between FDA and EMA intensifies. Watch for ECHA REACH substance evaluation outcomes tightening polycyclic aromatic hydrocarbon limits as the signal indicating accelerated laboratory outsourcing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Investment | Bridges FDA and EMA protocol divergence for pharmaceutical-grade suppliers. |
| Membrane Filtration-Assisted Hydrotreating Adoption | Enables mid-scale Indian and Southeast Asian refiners to achieve USP-grade specifications. |
| Direct Technical Service Agreements | Displaces distributor intermediaries as Hyderabad and Ahmedabad formulators scale procurement. |
| Backward Integration into Base Oil Feedstock | Secures margin control against crude volatility for integrated Gulf Coast refiners. |
| ANVISA Pharmaceutical Excipient Registration | Opens Latin American topical drug manufacturing to USP-grade suppliers. |
Research Approach
A spread of perspectives from refinery technical directors, pharmaceutical procurement managers, cosmetic formulators, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with downstream stakeholders and upstream suppliers, validated against secondary sources including FDA 21 CFR filings, ECHA REACH substance evaluation documentation, CDSCO excipient guidelines, and BIS IS 335 amendments. Bottom-up volume estimates from end-use application segments triangulated with top-down capacity assessments across US Gulf Coast, European, and Asian refining clusters.
Demand-supply-balance modeling across the projection horizon incorporated grade tier segmentation by certification intensity, end-use industry stratification across pharmaceutical, cosmetic, food, and industrial applications, and regional production hub analysis. CAGRs derived from weighted average growth contributions across modeled segments, with specific inputs including hydrotreater capacity expansion timelines, REACH PAH limit evolution, and CDSCO guideline convergence trajectories with USP-NF monographs.
Practitioners should monitor hydrotreater emissions permitting outcomes, ECHA substance evaluation results, and plant-based lipid substitution rates in cosmetic formulations for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
US Esters Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Paraffin Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
1-Decene Market
Oleochemicals
Ethylhexyl Cocoate Market