
 Vitrified Bonded Grinding Wheels Market | 2026-2036
Vitrified Bonded Grinding Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Vitrified Bonded Grinding Wheels Market Insights
Aerospace Manufacturers is pivoting toward tighter-tolerance finishing requirements, pulling demand for high-performance vitrified wheels in turbine blade and landing gear applications. Saint-Gobain leverages its European ceramic expertise to anchor supply relationships with tier-one aerostructures suppliers. Tyrolit sustains R&D intensity in engineered grain technologies for heat-resistant superalloys. CUMI dominates South Asian distribution through backward integration into fused alumina production.
Vitrified bonded grinding wheels are abrasive tools manufactured by firing a mixture of abrasive grains, ceramic bond materials, and temporary binders at temperatures exceeding 1,200°C, producing a porous, rigid structure that permits coolant flow and resists thermal deformation during high-speed grinding. Their primary industrial purpose is precision material removal in hardened steel, ceramic, and superalloy workpieces where dimensional accuracy and surface integrity are critical. Straight wheels and cup wheels together occupy the majority of product type volume, with cup wheels capturing disproportionate margin pools in toolroom and cutter grinding applications where profile retention justifies premium pricing. Cubic boron nitride and diamond abrasive materials represent the fastest-expanding material category, displacing conventional aluminum oxide in automotive powertrain and aerospace superalloy finishing where wheel life and cutting efficiency determine total process economics.
FDA oversight of medical device manufacturing surfaces shapes demand for certified vitrified wheels in orthopedic implant grinding, while EPA emissions standards constrain bond formulation chemistry and kiln firing protocols in U.S. production facilities. REACH registration requirements in Europe restrict certain bond system additives, compelling reformulation investments that favor suppliers with in-house ceramic chemistry capabilities. OSHA silica exposure limits in metalworking facilities are pushing end users toward engineered abrasives with lower respirable particle generation. Stakeholders must monitor evolving MEE enforcement in China around ceramic industry emissions, as tightening environmental compliance there could redirect export supply toward domestic consumption or trigger capacity relocation to Southeast Asian manufacturing zones.
Market Dynamics
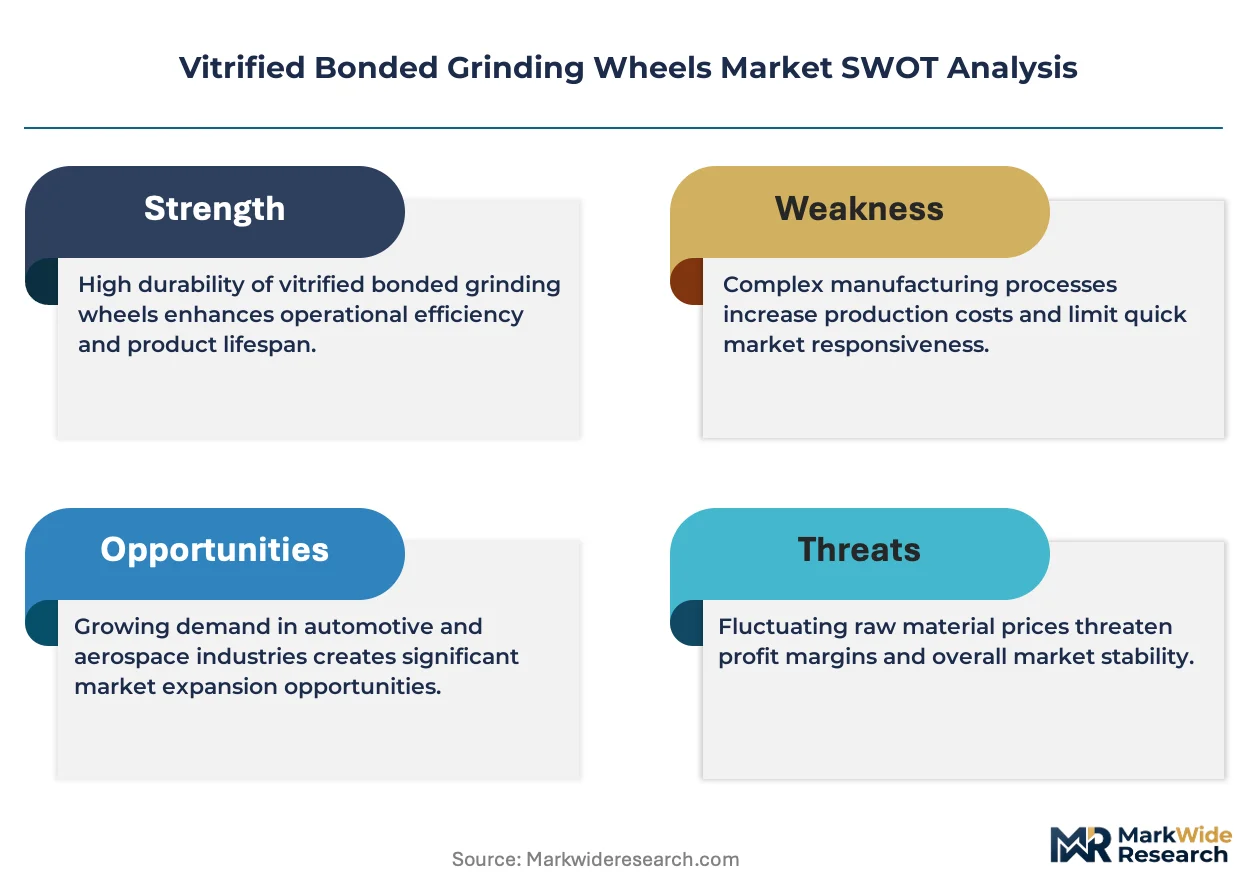
Aerospace turbine blade finishing tolerances now demand sub-micron surface integrity, pulling specification authority toward end-users with captive metrology capabilities and compressing margin for commodity wheel suppliers.
Growth Catalysts
- EU F-Gas Regulation:Bond reformulation mandates for reduced fluorinated gas emissions in kiln firing are accelerating demand for compliant vitrified systems in German and French aerospace clusters.
- Superalloy machining intensity:Heat-resistant nickel alloys in next-generation jet engines require engineered ceramic abrasives that withstand thermal loading without wheel degradation.
- Stuttgart-Solingen corridor:Precision tool manufacturing concentration in southwestern Germany generates sustained pull for high-retention cup wheels in cutter grinding applications.
Market Restraints
- Fused alumina price volatility:Energy-intensive fusion processes expose raw material costs to natural gas and electricity tariff swings, compressing formulation margins.
- Supply concentration in East Asian fused grain:Dependence on limited geographic sources for premium white and pink alumina creates vulnerability to export quota disruptions.
- REACH registration barriers:ECHA compliance costs for novel bond system additives favor incumbents with established chemical dossiers, raising entry thresholds for new formulations.
Strategic Opportunities
- Indian orthopedic implant grinding:CDSCO-regulated medical device manufacturing expansion creates certified wheel demand in Chennai and Ahmedabad machining clusters.
- CBN-diamond hybrid convergence:Multi-layer superabrasive architectures combining cubic boron nitride with diamond segments enable single-setup finishing of hardened steel-ceramic composites.
- Digital abrasive selection platforms:AI-driven wheel specification tools are compressing distributor technical sales cycles and shifting specification authority to procurement functions.
Industry Challenges
- Ceramic bond chemistry expertise scarcity:Retiring kiln engineers and formulation chemists in European manufacturing bases constrain R&D velocity for next-generation porous structures.
- ISO 9001:2015 plus MDR dual certification timelines:Medical device wheel qualification protocols extend commercialization cycles by 18-24 months for new product introductions.
- Legacy ERP integration with IoT-enabled grinding monitoring:Real-time wheel wear sensing systems require middleware development that strains mid-tier supplier IT capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitrified Bonded Grinding Wheels Market |
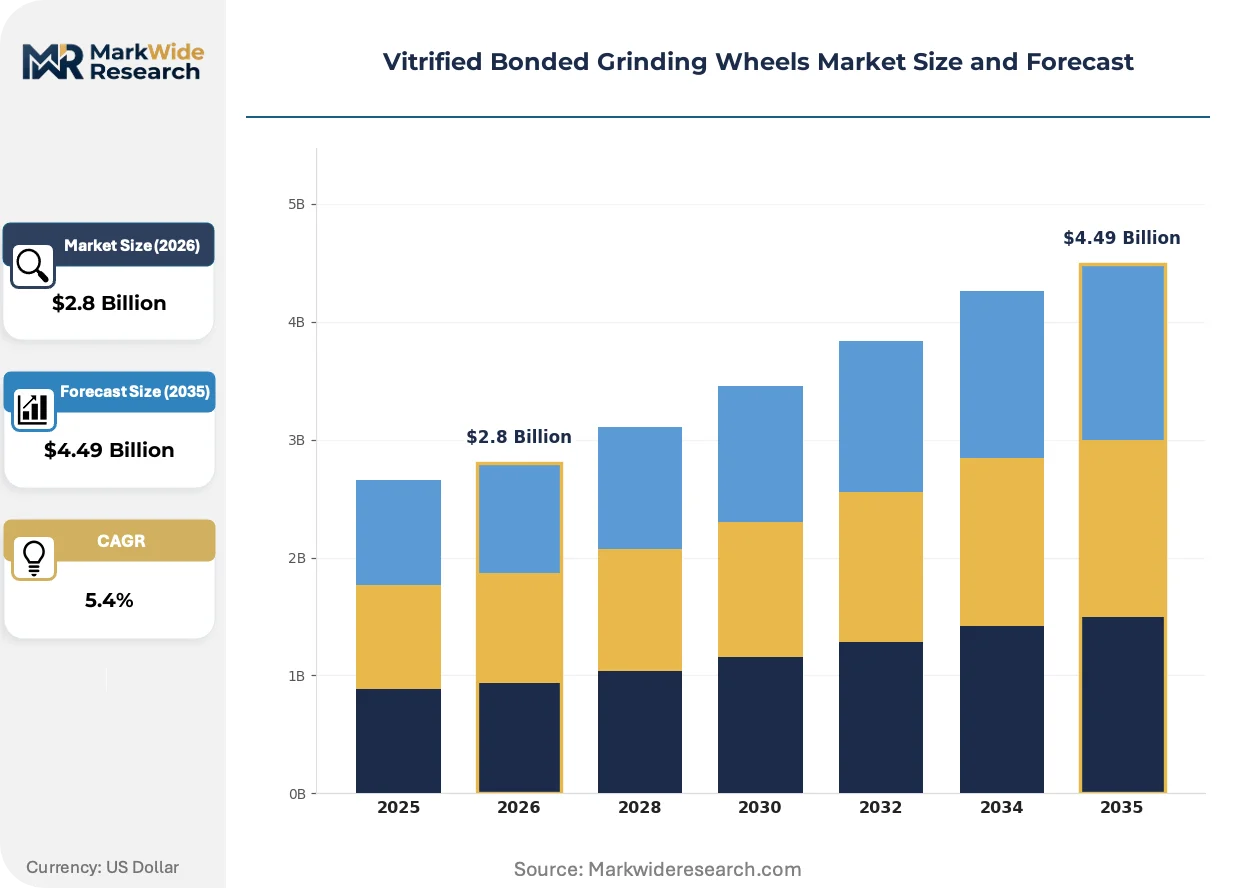
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Wheels, Cylinder Wheels, Tapered Wheels, Cup Wheels, Segmental Wheels Abrasive Material: Aluminum Oxide, Silicon Carbide, Cubic Boron Nitride, Diamond, Ceramic, Zirconia Alumina Application: Metalworking, Stone Cutting, Precision Grinding, Tool Sharpening, Surface Finishing, Die Grinding End User Industry: Machine Shops, Aerospace Manufacturers, Foundry Facilities, Toolmakers, Electronics Fabricators |
| Companies Covered | 3M, Saint-Gobain, Tyrolit, Noritake, Norton, CUMI, Robert Bosch, Buffalo Abrasives, Carborundum Universal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitrified Bonded Grinding Wheels Market Trends and Innovations
Additive manufacturing of metal components is reshaping grinding wheel specification requirements as near-net-shape parts reduce stock removal volumes while demanding tighter final tolerances.
Engineered grain structures with controlled micro-fracture properties are decentralizing the traditional tradeoff between wheel life and cutting aggressiveness. Aerospace powertrain machine shops in Germany and Japan are specifying these ceramics for Inconel turbine disk finishing. The technology is decentralizing procurement decisions from centralized abrasive commodity buyers toward plant-level process engineers with direct P&L accountability for machining cell throughput.
REACH authorization requirements for boron compounds in bond systems are forcing reformulation investments across European production facilities. Manufacturers are substituting alternative glass-ceramic matrices that maintain porosity without restricted additives. Medical device grinding applications face the steepest compliance cost escalation, with some suppliers exiting orthopedic implant wheel categories rather than absorbing ECHA registration burdens.
Specification authority migration from distributor technical sales to end-user manufacturing engineering teams is compressing traditional channel relationships. Tier-one automotive powertrain producers in Stuttgart and Detroit now issue direct wheel performance specifications to manufacturers, bypassing regional abrasive distributors. This pattern is most pronounced in high-volume camshaft and crankshaft grinding operations where process consistency penalties exceed any distributor service value.
Vitrified Bonded Grinding Wheels Market Segmentation
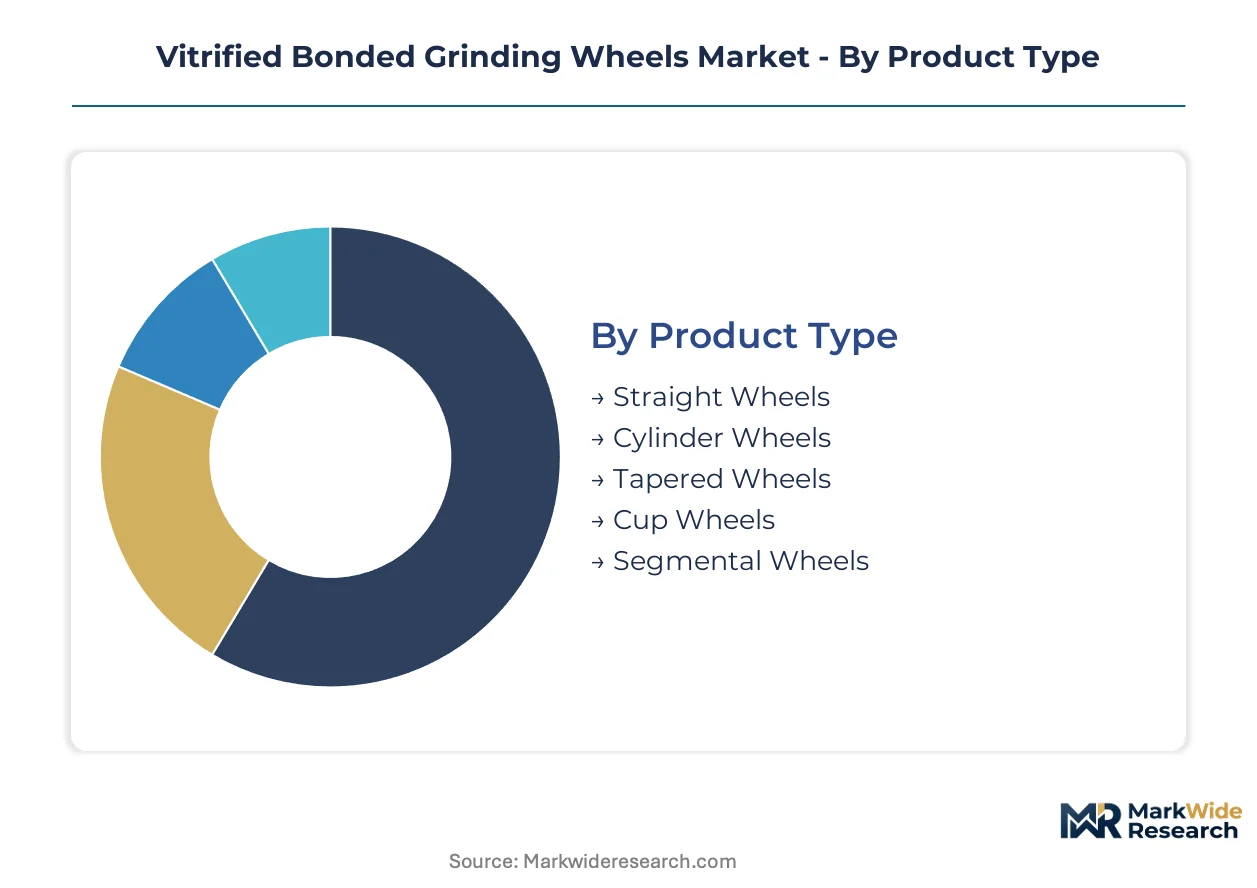
Segmentation in vitrified bonded grinding wheels reflects divergent capital requirements across product architectures and abrasive technologies. Specification authority migrates toward end-users with captive metrology capabilities, fragmenting procurement patterns by performance tier rather than volume scale.
Product Type:
Straight wheels and cup wheels demand the heaviest kiln infrastructure investment, with firing cycles exceeding 1,200°C requiring specialized refractory handling systems.
- Straight Wheels:These flat-profile wheels dominate cylindrical grinding operations for hardened steel shafts and bearing races. Aerospace manufacturers in Germany specify these for turbine disk finishing where dimensional repeatability across batch runs determines supplier qualification. REACH-compliant bond formulations are compressing margin pools for commodity-grade straight wheel producers without in-house ceramic chemistry capabilities.
- Cup Wheels:Flanged designs with recessed profiles enable face-grinding of cutting tools and cutter bodies. The Stuttgart-Solingen corridor generates concentrated demand for high-retention cup wheels in precision toolroom applications where profile integrity justifies 40-60% price premiums over standard configurations.
- Cylinder Wheels:Peripheral grinding of crankshafts and camshafts in automotive powertrain operations.
- Tapered Wheels:Tool sharpening applications requiring angular approach geometry for cutter clearance angles.
- Segmental Wheels:Large-diameter surface grinding with replaceable abrasive segments for cost efficiency in heavy stock removal.
Straight wheels absorb the bulk of installed capacity; cup wheels are expanding most quickly.
Abrasive Material:
Raw material cost tiers separate commodity aluminum oxide from engineered superabrasives, with cubic boron nitride and diamond commanding 8-15x formulation premiums.
- Aluminum Oxide:Fused brown and white alumina variants remain the volume foundation for general-purpose metalworking. Foundry facilities in India rely on domestic fused alumina supply chains for cost-competitive rough grinding of cast iron components. Energy-intensive fusion processes expose producers to natural gas tariff volatility.
- Cubic Boron Nitride:Synthetic superabrasive crystals engineered for hardened ferrous alloy grinding at elevated temperatures. Japanese automotive powertrain producers specify CBN wheels for camshaft finishing where wheel life economics outweigh 12-18x initial cost premiums over conventional abrasives.
- Silicon Carbide:Harder but more brittle than aluminum oxide, preferred for non-ferrous metals and stone cutting.
- Diamond:Superabrasive for tungsten carbide, ceramics, and composite materials in electronics fabrication.
- Ceramic:Engineered grain structures with controlled micro-fracture properties for aggressive cutting action.
- Zirconia Alumina:Tougher grain structure for heavy-duty grinding of stainless steels and high-alloy materials.
Aluminum oxide retains the largest installed base; cubic boron nitride is climbing the fastest.
Application:
Process economics vary sharply by stock removal volume versus final tolerance requirements, with precision grinding commanding disproportionate margin capture.
- Precision Grinding:Sub-micron tolerance finishing of hardened steel and ceramic workpieces. Aerospace turbine blade manufacturers in France and Germany specify vitrified wheels with engineered porosity for coolant delivery without wheel loading. FDA-regulated orthopedic implant grinding imposes dual ISO 9001:2015 and MDR certification burdens extending commercialization timelines.
- Metalworking:General-purpose stock removal across machine shop environments. OSHA silica exposure limits are pushing U.S. facilities toward engineered abrasives with lower respirable particle generation.
- Stone Cutting:Granite and marble processing with silicon carbide formulations.
- Tool Sharpening:Cutter reconditioning in maintenance departments and small toolrooms.
- Surface Finishing:Final dimensional correction and surface integrity improvement.
- Die Grinding:Portable applications with mounted vitrified points and plugs.
Metalworking represents the largest volume category; precision grinding is gaining share fastest.
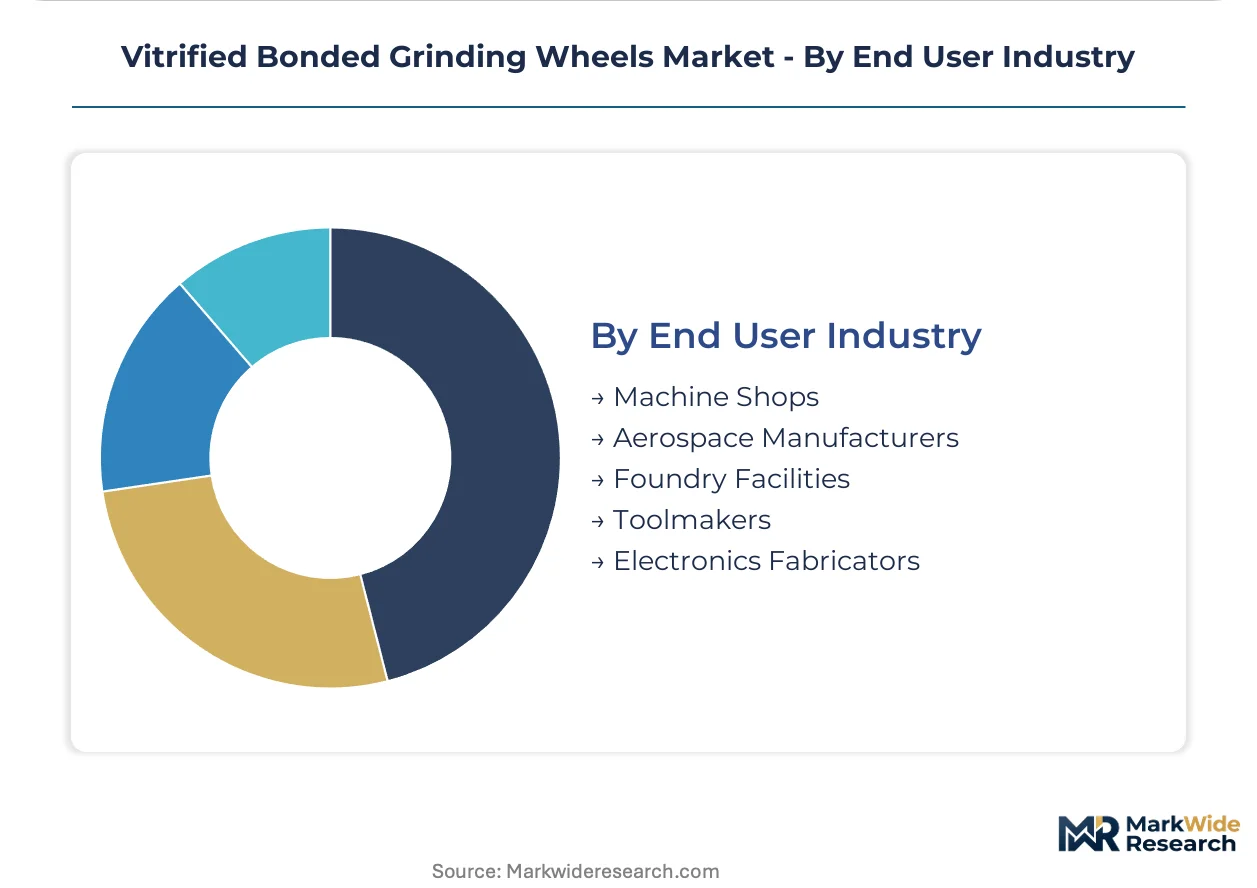
End User Industry:
Customer sophistication tiers separate specification-driven aerospace producers from price-sensitive foundry operations.
- Aerospace Manufacturers:Tier-one aerostructures suppliers with captive grinding process engineering teams. Inconel and titanium alloy machining requirements in turbine blade finishing pull demand for heat-resistant bond systems. EU F-Gas Regulation compliance is accelerating qualification of reformulated low-emission vitrified wheels in French and German aerospace clusters.
- Machine Shops:Diverse job shop environment with fragmented procurement authority and distributor-dependent technical selection.
- Foundry Facilities:High-volume rough grinding of cast components with emphasis on wheel cost per cubic centimeter removed.
- Toolmakers:Precision cutter grinding with cup wheel and straight wheel specifications for profile retention.
- Electronics Fabricators:Ceramic substrate and semiconductor material processing with diamond superabrasive requirements.
Machine shops represent the broadest customer base; aerospace manufacturers are expanding specification authority most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asian fused alumina zones while consumption concentrates in precision manufacturing corridors across Germany, the United States, and Japan. This geographic split shapes trade flows and regulatory compliance costs. Environmental enforcement in ceramic firing operations is tightening fastest in Europe and China.
Germany
Aerospace turbine blade finishing and precision tool grinding pull demand for high-retention cup wheels. The EU F-Gas Regulation mandates reformulated bond systems with reduced fluorinated gas emissions in kiln firing. Stuttgart and Solingen anchor the densest concentration of cutter grinding operations in southwestern Germany.
United States
Automotive powertrain producers and medical device manufacturers specify vitrified wheels for camshaft and orthopedic implant grinding. EPA emissions standards constrain bond formulation chemistry and kiln firing protocols in domestic production facilities. The Midwest manufacturing belt around Detroit and Cleveland generates concentrated demand for cylindrical grinding applications.
China
Domestic fused alumina supply chains feed cost-competitive rough grinding operations for foundry and metalworking sectors. MEE enforcement around ceramic industry emissions is tightening, potentially redirecting export supply toward domestic consumption. Yangtze River Delta industrial zones concentrate precision grinding demand for electronics fabrication.
Japan
Automotive and aerospace superalloy machining drives specification of CBN wheels for hardened ferrous alloy grinding. METI industrial standards shape quality certification requirements for export-oriented manufacturers. Nagoya and Osaka industrial corridors concentrate captive grinding process engineering capabilities.
India
Domestic fused alumina production supports backward-integrated wheel manufacturing for South Asian distribution. CDSCO-regulated medical device manufacturing expansion creates certified wheel demand in Chennai and Ahmedabad machining clusters. Foundry operations in Gujarat and Maharashtra rely on cost-competitive aluminum oxide formulations for cast iron rough grinding.
Vitrified Bonded Grinding Wheels Market Competitive Landscape
Top-tier vendors anchor premium specification authority with aerospace and medical device producers, while mid-tier fabricators compete on price-sensitive metalworking and foundry applications. The vendor base stratifies across three tiers: integrated superabrasive specialists, regional fused alumina wheel producers, and distributor-branded commodity suppliers. Strategic moves concentrate on ceramic bond chemistry R&D investments and backward integration into abrasive grain production.
Within the integrated superabrasive tier, Saint-Gobain and Tyrolit exemplify European ceramic expertise anchoring supply relationships with tier-one aerostructures suppliers. CUMI occupies a position among South Asian fabricators leveraging captive fused alumina production for regional distribution control. These three represent distinct archetypes: Saint-Gobain and Tyrolit sit within premium specification-driven positioning, while CUMI exemplifies cost-integrated regional scale.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Tyrolit |
| Noritake |
| Norton |
| CUMI |
| Robert Bosch |
| Buffalo Abrasives |
| Carborundum Universal |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in southwestern Germany anchor premium pricing discipline through generational ceramic chemistry expertise that resists commoditization pressure. Their captive control over bond formulation intellectual property enables selective participation in aerospace qualification programs while forcing price-responsive competitors toward undifferentiated metalworking volumes.
Pricing Analysis
Margin tightening in commodity aluminum oxide wheels reflects fused alumina energy cost pass-through and Indian import competition. Three-tier pricing structure across aerospace-certified, industrial-standard, and economy foundry grades separates specification-driven buyers from price-sensitive rough grinding operations. Cost compression accelerates in standard-tier cylindrical wheels as Chinese producers expand European distribution. Aerospace turbine blade grinding specifications show lowest price elasticity, while Indian foundry procurement teams drive aggressive cost-per-wheel negotiations.
Supply Chain Analysis
Dual-sourcing mandates from tier-one aerostructures suppliers in Germany and France force qualified producers to maintain redundant kiln capacity across multiple facilities. Fused alumina supply concentrates in China, India, and Germany, with premium white alumina production anchored in Chinese Henan province and Indian Odisha. Bond system additives draw from specialty chemical producers in Belgium and Japan. Single-source vulnerability in engineered ceramic grain technology creates qualification bottlenecks for next-generation superabrasive wheels. Distribution runs through regional abrasive distributors with technical sales capabilities, though direct manufacturer relationships are expanding in high-volume automotive powertrain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization requirements for boron compounds create insurmountable registration barriers for new entrants lacking established ECHA dossiers.
For Market Incumbents: Hedge ceramic bond chemistry expertise scarcity by capturing retiring European kiln engineers through targeted technical recruitment in Stuttgart and Solingen. Deepen captive fused alumina supply through selective Indian mining asset partnerships before Chinese MEE enforcement redirects export supply toward domestic consumption. Defend aerospace specification authority against emerging diamond-CBN hybrid wheel specialists by accelerating ISO 9001:2015 plus MDR dual certification timelines for orthopedic implant grinding categories. For New Entrants and Emerging Players: Begin with CDSCO-regulated medical device manufacturing expansion in Chennai and Ahmedabad, where certified wheel demand outpaces qualified domestic supply. Target foundry rough grinding segments in Gujarat and Maharashtra with cost-competitive brown alumina formulations that bypass premium bond chemistry requirements. Pursue digital abrasive selection platform partnerships to compress technical sales cycles and shift specification authority toward procurement functions receptive to transparent pricing. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European wheel producers with established aerospace qualification records but strained working capital from REACH reformulation investments. Long-term viability hinges on ceramic bond chemistry capabilities that cannot be replicated through capital expenditure alone. Watch MEE enforcement intensity in Chinese ceramic firing operations as the inflection signal determining whether export supply redirects toward domestic consumption or triggers Southeast Asian capacity relocation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Bond Reformulation | ECHA registration investments protect aerospace supply relationships in German and French clusters. |
| Backward Integration into Fused Alumina | Captive Indian and Chinese raw material supply secures cost position against energy tariff volatility. |
| CBN-Diamond Hybrid Architecture Development | Multi-layer superabrasive designs enable single-setup finishing of hardened steel-ceramic composites for aerospace. |
| Digital Wheel Specification Platform Launch | AI-driven selection tools compress distributor technical sales cycles in fragmented machine shop segments. |
| Medical Device Dual Certification Acceleration | ISO 9001:2015 plus MDR qualification opens orthopedic implant grinding in regulated Chennai and Ahmedabad clusters. |
Research Methodology
Trade association filings, customs export records, and ECHA registration databases formed the secondary backbone for supply-side capacity assessment. Primary interviews with grinding process engineers at tier-one aerostructures suppliers, procurement leads at German automotive powertrain producers, technical directors at ceramic bond chemistry specialists, and distribution channel managers in South Asia validated demand segmentation assumptions. Bottom-up and top-down triangulation reconciled facility-level production estimates with end-use consumption patterns across aerospace, automotive, and medical device manufacturing.
Bottom-up modeling aggregated individual facility capacities and utilization rates across Chinese, Indian, and European production zones, while top-down analysis cross-checked against end-use industry grinding intensity metrics. Segmentation dimensions included product architecture, abrasive material tier, application precision requirements, and end-user industry sophistication. CAGRs derived from regression analysis against industrial production indices and aerospace order backlogs. Forecast inputs incorporated REACH compliance cost trajectories and MEE enforcement probability scenarios for Chinese ceramic firing operations.
Fused alumina price volatility, REACH authorization timeline delays, and aerospace production cycle downturns are the dominant revision risks. Deviation in Chinese environmental enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Coated Abrasives Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Europe Abrasives Market
Abrasives
New Zealand Abrasives Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Abrasive Tools Market
Abrasives
Abrasive Base Paper Market
Abrasives
Carborundum Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Grinding Wheels Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Fine Sandpaper Market
Abrasives
Tungsten Carbide Market
Abrasives
Australia Abrasives Market