
 Grinding Wheels Market | 2026-2036
Grinding Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Grinding Wheels Market Foresight
Modular wheel-and-arbor bundling is shifting buyer choice away from standalone commodity purchases toward pre-balanced, application-specific kits. Tyrolit Group leverages its Austrian engineering base to dominate high-precision superabrasive systems for aerospace turbine grinding. Klingspor AG anchors its position through backward integration into coated abrasive substrates, giving it captive supply of critical bonding materials. Robert Bosch GmbH competes by extending its power-tool ecosystem into consumables, locking workshop customers into compatible wheel formats.
A grinding wheel is a bonded abrasive tool, typically comprising alumina, silicon carbide, diamond, or cubic boron nitride grains held in vitrified, resin, or metal matrices, designed to remove material through controlled friction at surface speeds often exceeding 35 meters per second. Its primary industrial purpose is dimensional finishing, surface preparation, and precision shaping of hardened metals, ceramics, and composites across manufacturing operations. Diamond wheels command the highest margin pools in the product type dimension, serving carbide tool grinding and semiconductor wafer processing where tolerance requirements exclude conventional alternatives. CBN wheels represent the fastest-growing material segment for automotive crankshaft and camshaft applications, displacing alumina in high-volume production lines.
REACH in Europe restricts phenolic resin formulations and mandates disclosure of crystalline silica content, compelling reformulation of conventional bonding systems. OSHA's respirable crystalline silica standard in the United States drives fabricators toward engineered wheels with lower dust generation profiles, directly shaping procurement criteria. ISO 9001 and ISO 14001 certifications function as baseline market-access filters for suppliers serving tier-one automotive and aerospace OEMs. Stakeholders must monitor how tightening particulate exposure limits across multiple jurisdictions reshape the cost structure of conventional versus superabrasive wheel portfolios.
Market Dynamics
Precision grinding operations for electric drivetrain components in Germany, Japan, and the United States are restructuring demand toward engineered superabrasive wheels that reduce airborne particulate generation under tightening exposure limits.
Growth Catalysts
- REACH compliance in Europe:Phenolic resin restrictions and crystalline silica disclosure mandates are compelling manufacturers to reformulate bonding systems toward lower-emission alternatives.
- Automotive crankshaft grinding:CBN wheels are displacing alumina in high-volume production lines as tolerance requirements tighten for electric vehicle powertrain components.
- China's eastern manufacturing corridor:Machine tool density in this cluster supports bulk consumption of both conventional alumina and diamond wheels for precision finishing operations.
Market Restraints
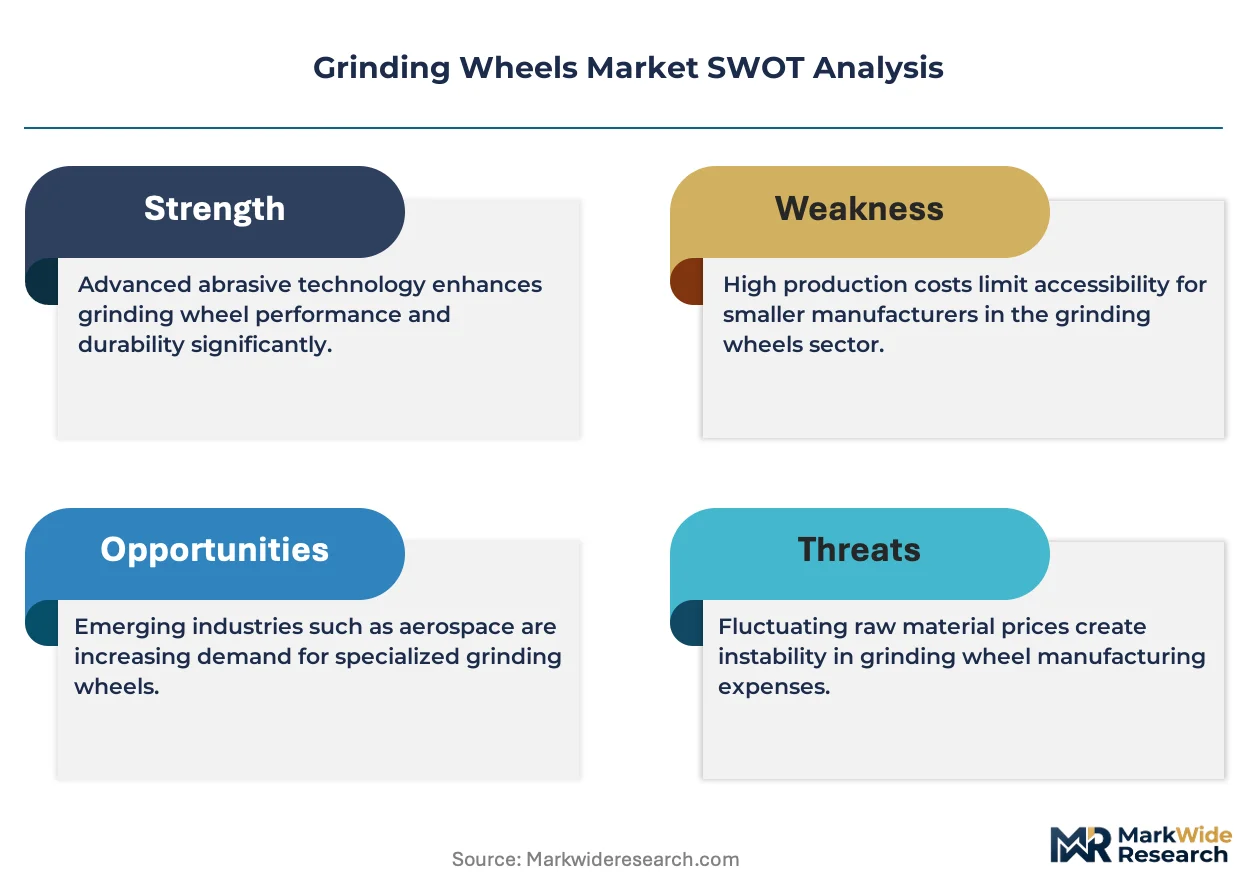
- Synthetic diamond supply concentration:Critical superabrasive feedstock production clusters in limited geographic zones create vulnerability for wheel manufacturers dependent on consistent grit quality.
- OSHA silica exposure enforcement:Fabricators face elevated compliance costs and operational disruption as respirable crystalline silica standards tighten inspection protocols.
- Resin bond thermal limitations:Phenolic and polyimide matrices degrade at temperatures above 250°C, constrinding high-speed grinding applications where vitrified bonds remain uncompetitive.
Strategic Opportunities
- Semiconductor wafer processing:Diamond wheels for silicon carbide substrate preparation represent an emerging high-margin application as power electronics demand accelerates.
- Modular wheel-and-arbor bundling:Pre-balanced, application-specific kits are capturing procurement preference over standalone commodity purchases in aerospace and medical device sectors.
- EU Green Deal industrial decarbonization incentives:Funding streams for energy-efficient manufacturing equipment are steering capital toward superabrasive systems with lower friction energy requirements.
Industry Challenges
- ISO 9001 and ISO 14001 certification timelines:Tier-one automotive and aerospace OEMs require these as baseline market-access filters, extending supplier qualification cycles to 18-24 months.
- Bonding chemistry R&D specialization:The shift from conventional alumina to engineered superabrasive formulations demands materials science expertise that remains scarce in traditional grinding wheel engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grinding Wheels Market |
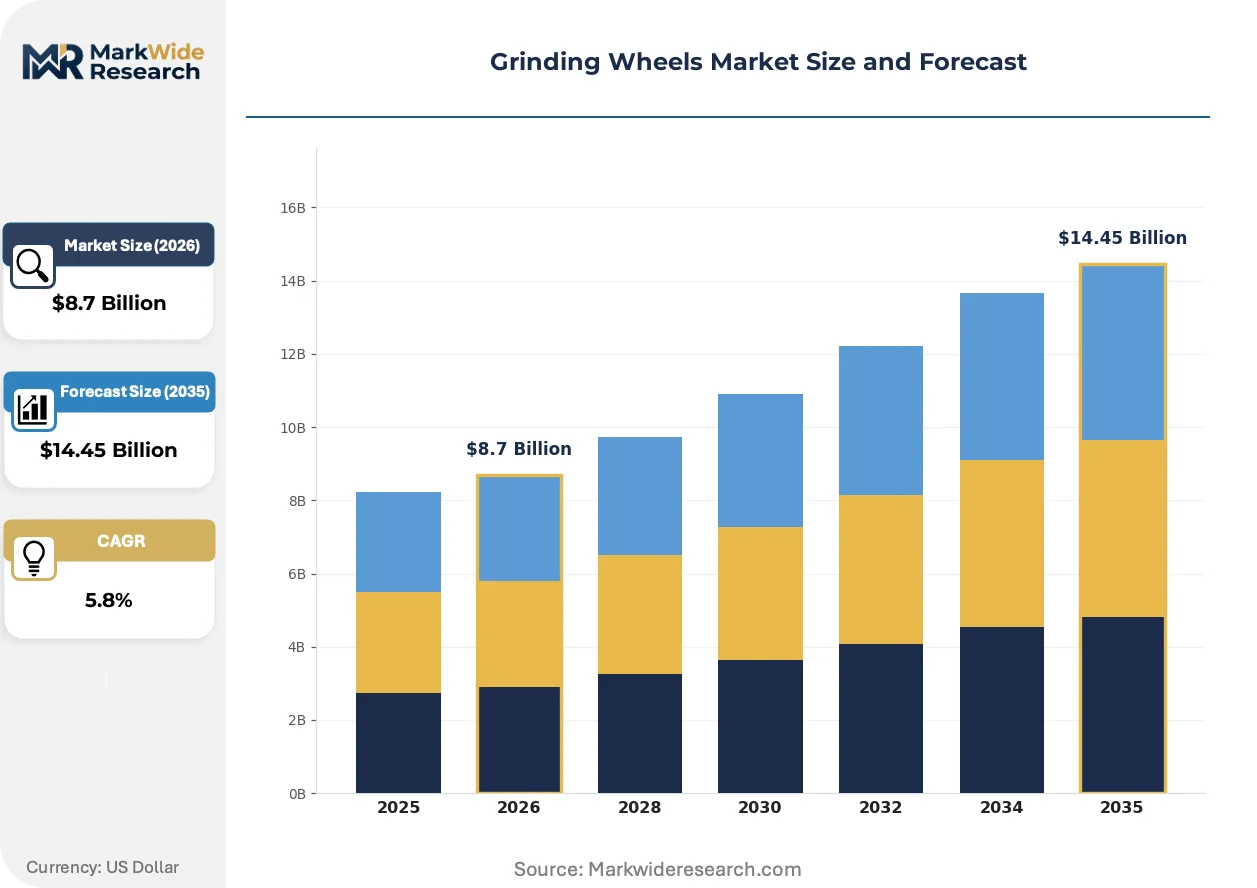
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Wheels, Diamond Wheels, CBN Wheels, Cut-off Wheels Material: Alumina, Silicon Carbide, Diamond, Cubic Boron Nitride Application: Metalworking, Woodworking, Construction, Automotive End User: Manufacturers, Fabricators, Workshops, Artisans |
| Companies Covered | Tyrolit Group, Camel Grinding Wheels, 3M Company, Klingspor AG, ATLANTIC GmbH, Compagnie de Saint-Gobain S.A., Robert Bosch GmbH, Pferd Inc., Noritake Co., Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grinding Wheels Market Shifts & Advancements
Digital process monitoring and predictive wheel wear analytics are compressing maintenance cycles and reshaping how manufacturers specify consumable life metrics in long-term supply agreements.
Metal-bonded diamond wheels with in-situ dressing capability are decentralizing precision grinding from centralized job shops toward distributed production cells. Automotive suppliers in Stuttgart and Detroit are deploying these systems at satellite facilities to reduce work-in-process logistics. This architecture is decentralizing quality control authority from master plants to regional tier-two operations.
REACH restrictions on phenolic resin formulations are forcing disclosure of crystalline silica content across European supply chains. Wheel manufacturers must reformulate conventional bonding systems or face market exclusion. Vitrified bond alternatives are gaining share in Germany and France as fabricators pre-empt compliance costs.
Buyer concentration among automotive OEMs is compressing switching cycles and demanding volume-commitment contracts with penalty clauses. Tier-one suppliers in Japan and the United States are consolidating vendor lists to three approved wheel sources per application. This consolidation is most visible in powertrain component grinding where single-source risk mitigation has become a procurement priority.
Grinding Wheels Market Segmentation
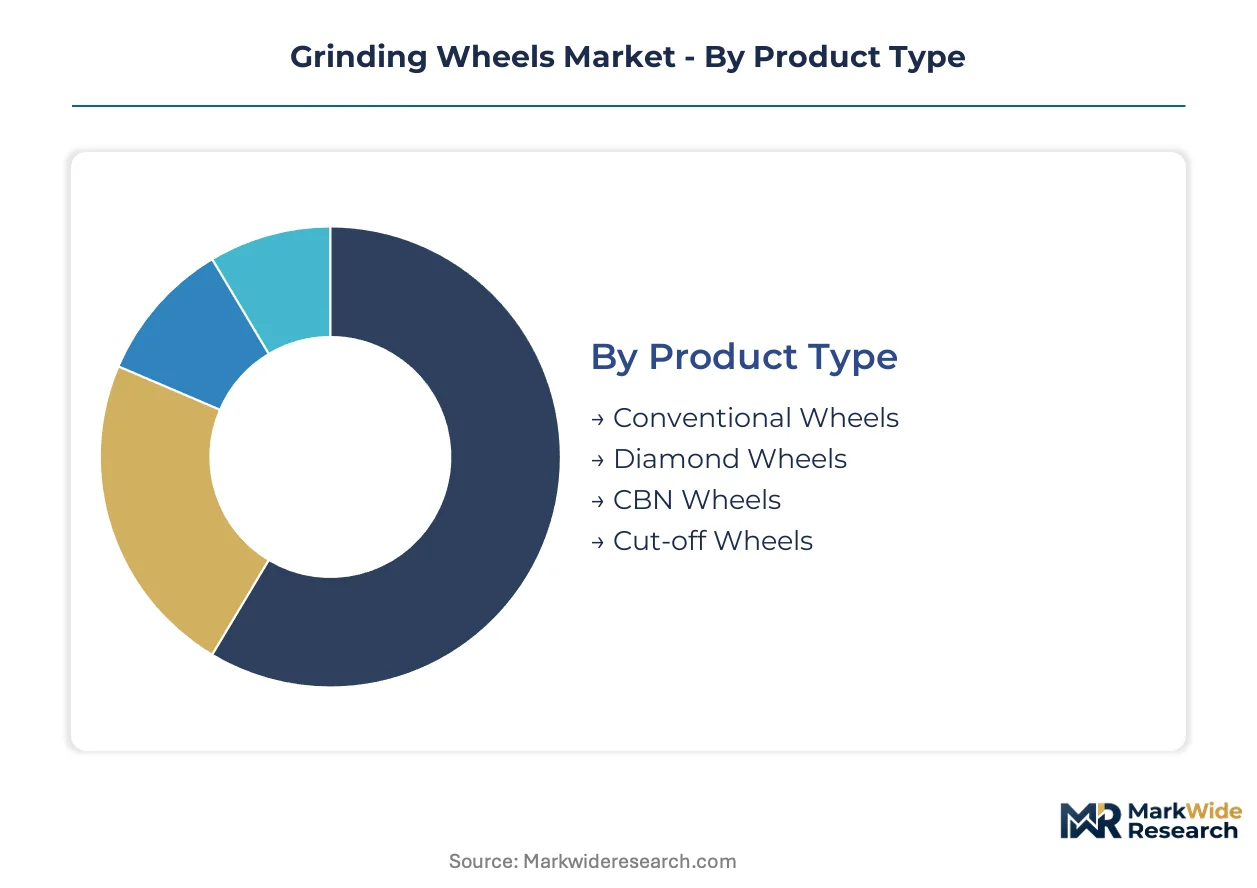
Grinding wheel procurement diverges sharply between high-volume commodity consumption and precision-engineered superabrasive systems. Understanding where volume concentrates versus where margins pool determines supplier resource allocation and R&D prioritization across bonding chemistry and abrasive grain portfolios.
Product Type:
Volume sits with conventional alumina systems, while premium capture concentrates in superabrasive formulations for tight-tolerance applications.
- Conventional Wheels:Alumina and silicon carbide grains in vitrified or resin bonds dominate mass-market metal removal. Demand concentrates in China's eastern manufacturing corridor where machine tool density supports bulk consumption for general-purpose finishing.
- Diamond Wheels:Synthetic or natural diamond grit in metal, resin, or vitrified matrices command the highest margin pools. Carbide tool grinding and semiconductor wafer processing in Germany, Japan, and the United States drive specification where tolerance requirements exclude conventional alternatives.
- CBN Wheels:Cubic boron nitride superabrasives serve hardened ferrous metals. Automotive crankshaft and camshaft grinding lines are climbing the fastest as electric drivetrain tolerance requirements displace alumina in high-volume production.
- Cut-off Wheels:Thin resin-bonded discs for severing operations. Construction and metal fabrication workshops in the United States generate consistent demand under OSHA silica exposure compliance pressures.
Mature deployment sits with Conventional Wheels. Newer deployment is concentrated in CBN Wheels.
Material:
Cost structure and thermal performance separate commodity abrasives from engineered superabrasive feedstocks.
- Alumina:Fused aluminum oxide in brown, white, and pink variants remains the workhorse for general grinding. REACH phenolic resin restrictions in Europe are compelling reformulation of alumina wheel bonding systems toward lower-emission alternatives.
- Silicon Carbide:Harder and more brittle than alumina, optimal for non-ferrous metals and ceramics. Woodworking and construction applications in the United States favor this material for stone and concrete surface preparation.
- Diamond:Highest hardness and thermal conductivity. Synthetic diamond supply concentration in limited geographic zones creates vulnerability for wheel manufacturers dependent on consistent grit quality for semiconductor substrate processing.
- Cubic Boron Nitride:Second-hardest material, chemically inert to ferrous metals at high temperatures. Expanding most quickly in automotive powertrain grinding where CBN displaces alumina for precision crankshaft finishing.
Procurement scale favors Alumina. Specification intensity is climbing fastest in Diamond.
Application:
End-use requirements dictate bond selection, grain specification, and wheel geometry with minimal cross-application compatibility.
- Metalworking:Precision grinding of hardened steels, tool steels, and superalloys. Germany's automotive suppliers and Japan's machine tool builders specify vitrified CBN wheels for dimensional finishing operations.
- Woodworking:Stock removal and surface preparation on hardwoods and engineered panels. Silicon carbide wheels dominate this segment with lower precision requirements than metal applications.
- Construction:Portable grinding and cutting of masonry, concrete, and structural steel. OSHA respirable crystalline silica enforcement in the United States is steering fabricators toward engineered wheels with lower dust generation profiles.
- Automotive:Powertrain component grinding, brake rotor finishing, and body panel preparation. Electric drivetrain manufacturing in Stuttgart, Detroit, and Toyota City is restructuring demand toward superabrasive systems with tighter tolerance capability.
Standardized consumption patterns characterize Woodworking. Custom specification intensity defines Automotive.
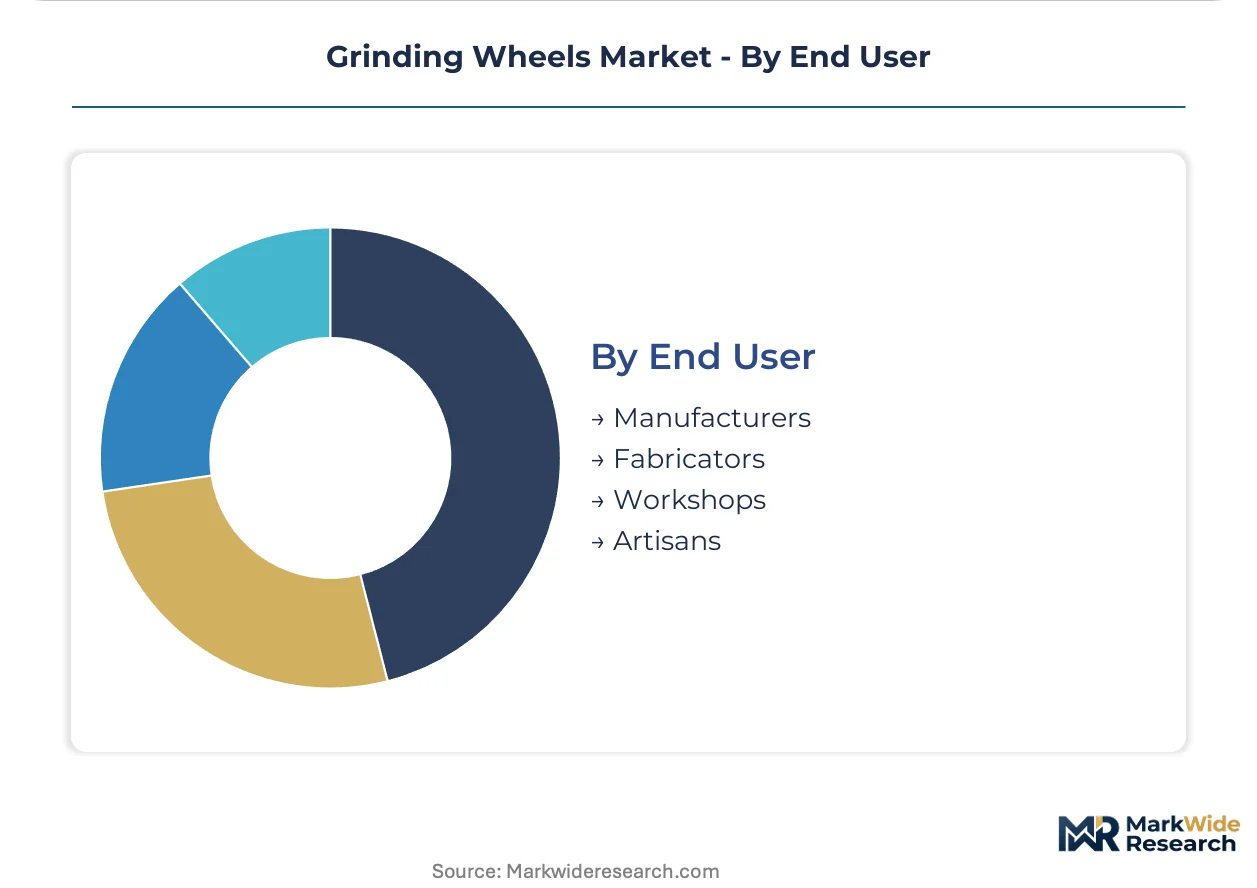
End User:
Technical sophistication and procurement authority vary dramatically across the user base, shaping packaging, distribution, and support requirements.
- Manufacturers:Tier-one automotive and aerospace OEMs with centralized procurement. ISO 9001 and ISO 14001 certifications function as baseline market-access filters, extending supplier qualification cycles to 18-24 months.
- Fabricators:Mid-scale metal service centers and job shops. Modular wheel-and-arbor bundling is capturing procurement preference over standalone commodity purchases in this segment.
- Workshops:Independent repair and maintenance operations. Robert Bosch GmbH competes by extending its power-tool ecosystem into consumables, locking workshop customers into compatible wheel formats.
- Artisans:Small-scale craft and restoration specialists. Lowest volume per account but highest price sensitivity and brand loyalty to established abrasive suppliers.
Consolidated vendor management sits with Manufacturers. Fragmented purchasing patterns persist among Artisans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor functions as the dominant tax-incentive zone for grinding wheel consumption, with machine tool density in Jiangsu and Zhejiang provinces supporting bulk procurement of both conventional alumina and diamond wheels for precision finishing operations.
United States
OSHA's respirable crystalline silica standard is restructuring procurement criteria toward engineered wheels with lower dust generation profiles. The EPA coordinates with state regulators to enforce workplace exposure limits that elevate compliance costs for fabricators. Detroit's automotive supplier cluster is deploying CBN wheel systems for electric drivetrain component grinding.
Germany
REACH compliance mandates phenolic resin reformulation and crystalline silica disclosure across European supply chains. The KBA enforces automotive quality standards that filter wheel suppliers through ISO 9001 and ISO 14001 certification requirements. Stuttgart's precision engineering corridor is consolidating vendor lists to three approved wheel sources per powertrain application.
Japan
METI's industrial decarbonization incentives are steering capital toward superabrasive systems with lower friction energy requirements. JIS standards function as baseline technical filters for wheel specifications in automotive and machine tool sectors. Toyota City's electric vehicle manufacturing cluster is restructuring demand toward engineered superabrasive wheels with tighter tolerance capability.
China
MIIT's dual carbon goals are accelerating factory upgrades toward energy-efficient grinding equipment. GB standards govern abrasive product safety and performance disclosures for domestic and export markets. The Yangtze River Delta machine tool concentration supports bulk consumption of conventional alumina wheels for general-purpose metal finishing.
India
PLI scheme incentives for automotive and electronics manufacturing are expanding precision grinding operations for domestic and export component supply. BIS certification requirements filter imported and locally manufactured wheel products. Tamil Nadu's automotive component cluster is scaling CBN wheel procurement for crankshaft and camshaft finishing lines.
Grinding Wheels Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: Austrian and German engineering-led superabrasive system providers, Japanese precision abrasive manufacturers with integrated materials science capabilities, and diversified industrial conglomerates extending power-tool ecosystems into consumables. Consolidation pressures are intensifying as tier-one automotive OEMs compress vendor lists and demand volume-commitment contracts with penalty clauses. Backward integration into coated abrasive substrates and captive supply of critical bonding materials represent dominant competitive moves.
Among European engineering-led specialists, Tyrolit Group and Klingspor AG exemplify the premium superabrasive tier. Tyrolit Group occupies a position anchored in Austrian precision manufacturing heritage for aerospace turbine grinding applications. Klingspor AG represents backward integration strategy through in-house production of coated abrasive substrates. Robert Bosch GmbH sits within the diversified conglomerate archetype, extending its power-tool ecosystem into consumables to lock workshop customers into compatible wheel formats.
| Leading Market Players |
|---|
| Tyrolit Group |
| Camel Grinding Wheels |
| 3M Company |
| Klingspor AG |
| ATLANTIC GmbH |
| Compagnie de Saint-Gobain S.A. |
| Robert Bosch GmbH |
| Pferd Inc. |
| Noritake Co., Limited |
| Others |
Supply & Pricing Matrix
Synthetic diamond grit costs cascade through superabrasive wheel pricing tiers, with feedstock concentration in limited geographic zones amplifying margin pressure on manufacturers serving semiconductor wafer processing and carbide tool grinding applications.
Pricing Analysis
Cost-down pressure on conventional alumina wheels accelerates as China's eastern manufacturing corridor saturates with machine tool density and bulk procurement power. Three-tier pricing structure across premium superabrasive, standard engineered, and economy commodity levels separates diamond and CBN formulations from vitrified alumina systems. Price differentiation hinges on ISO 9001 certification grade and volume-scale commitment terms. Tier-one automotive OEMs exhibit lowest price sensitivity due to tolerance-driven specification lock-in, while independent workshops demonstrate highest elasticity, gravitating toward Bosch-compatible bundled formats.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's MIIT dual carbon goals are reshaping sourcing patterns for abrasive grain and bonding resin inputs. Synthetic diamond production concentrates in China, Russia, and South Africa, while phenolic resin formulations draw from German and Belgian chemical suppliers. Single-source vulnerability in superabrasive feedstock creates exposure for wheel manufacturers dependent on consistent grit quality. Distribution runs through authorized industrial distributors serving tier-one OEMs, with direct-to-fabricator channels capturing mid-scale metal service center demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grinding wheel competition has become a vertical-integration race, with captive supply of critical bonding materials and backward integration into coated abrasive substrates determining margin defense against REACH-driven reformulation costs.
For Market Incumbents: Extend superabrasive system portfolios into modular wheel-and-arbor bundling to lock aerospace and medical device procurement preference. Deepen upstream control over synthetic diamond grit supply through long-term offtake agreements with producers in Russia and South Africa, insulating against feedstock concentration risk that threatens consistent quality for semiconductor wafer processing applications. For New Entrants and Emerging Players: The price-point gap between premium Tyrolit-engineered superabrasives and unbranded Chinese commodity wheels creates entry space for mid-tier positioned players. Target India's Tamil Nadu automotive component cluster with CBN wheel formulations for crankshaft finishing lines, leveraging PLI scheme incentives to offset 18-24 month OEM qualification cycles. Lead with technical service bundling rather than price-alone positioning. For Investors and Strategic Acquirers: Tier-one automotive OEM consolidation to three approved wheel sources per application is the leading indicator that vendor list compression will accelerate M&A activity among mid-cap specialists. Five-to-ten year viability favors targets with captive resin bonding chemistry R&D and ISO 14001 certification already in place. Watch for MIIT factory upgrade subsidy disbursement rates as the signal for Chinese domestic demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bonding Materials | Klingspor's captive resin substrate production secures supply continuity under REACH phenolic restrictions. |
| Modular Wheel-and-Arbor Kit Development | Pre-balanced aerospace bundles capture procurement preference away from standalone commodity purchases. |
| Superabrasive Formulation R&D Expansion | CBN wheel development for electric drivetrain grinding displaces alumina in Stuttgart and Detroit lines. |
| Long-term Supply Agreement Structuring | Volume-commitment contracts with penalty clauses align with tier-one OEM vendor consolidation mandates. |
| Regional Manufacturing Footprint Expansion | Tamil Nadu and Yangtze River Delta proximity reduces logistics exposure to India's BIS certification timelines. |
Research Methodology
Document review covered customs trade databases, SEC filings from diversified industrial conglomerates, and ISO certification registries, complemented by interviews with plant engineers at tier-one automotive suppliers, procurement leads at aerospace OEMs, technical R&D directors at abrasive manufacturers, and aftermarket service heads at industrial distributors. Secondary validation drew from MIIT factory upgrade disclosures, REACH compliance filings, and OSHA enforcement action records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical consumption patterns with expert panel input on electric drivetrain tolerance evolution shaped the projection framework. Segmentation dimensions modeled include product type, abrasive material, end-use application, and regional machine tool density cluster. CAGRs derived from curve-fitting against documented capacity expansion announcements and OEM vendor list consolidation trends. Forecast inputs incorporated METI decarbonization incentive disbursement rates and EPA-OSHA coordinated silica enforcement intensity.
Inputs from primary field interviews and regulatory filing databases were available through the study window; gaps in real-time synthetic diamond spot pricing and confidential OEM volume-commitment terms introduce uncertainty bands around superabrasive segment projections. Forecasts reflect documented assumptions on REACH phenolic resin phase-out timelines and MIIT dual carbon goal implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Anthracite Fines Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Polishing Chemicals Market
Abrasives
Bonded Abrasive Market
Abrasives
Synthetic Abrasives Market
Abrasives
Carbide Tools Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Abrasive Base Paper Market
Abrasives
Chemical Deflasher Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Abrasive Rolls Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Artificial Abrasives Market
Abrasives
Tungsten Carbide Market