
 Chemical Deflasher Market | 2026-2036
Chemical Deflasher Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Deflasher Market Analysis
German specialty chemical producers is recalibrating capacity allocation toward low-VOC deflashing formulations as OEMs tighten procurement standards. BASF SE leverages its integrated material science platform to supply both base polymers and finishing chemistries. Evonik Industries AG anchors its position through high-purity solvent systems engineered for medical-grade elastomer finishing. Dow Chemical Company differentiates via water-based deflasher portfolios aligned with automotive sustainability scorecards.
Chemical deflasher denotes a formulated cleaning agent—typically comprising organic solvents, surfactant blends, or supercritical CO₂ carriers—engineered to remove flash, burrs, and mold residue from injection-molded rubber and thermoplastic components without substrate damage. The product type dimension shows solvent-based formulations still dominating volume in heavy-flash rubber applications, while eco-friendly variants capture the fastest expansion as REACH and state-level air-quality rules tighten discharge limits. Within end users, automotive purchasing specifications now mandate deflashing process documentation, creating margin pools for suppliers with certified quality systems.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are forcing reformulation investments across European supply chains. In the United States, EPA NESHAP standards for hazardous air pollutants govern solvent-based deflasher emissions at rubber processing facilities. OSHA permissible exposure limits further constrain on-site solvent handling protocols. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven supply disruptions.
Market Dynamics
REACH registration requirements and EPA NESHAP standards are forcing simultaneous reformulation investments across European and North American supply chains, compressing margins for solvent-dependent producers while rewarding early movers into water-based chemistries.
Growth Catalysts
- Automotive surface-finish mandates:Tier-one suppliers in Germany now require documented deflashing process certification, creating captive demand for qualified chemical vendors.
- Cryogenic service expansion:Cryogenic deflashing using liquid nitrogen carriers is displacing mechanical trimming in medical-grade silicone production.
- ECHA authorization timelines:Accelerated sunset dates for chlorinated solvents under REACH are redirecting procurement toward surfactant-based alternatives.
Market Restraints
- Feedstock volatility:Petrochemical-derived solvents face input cost swings tied to naphtha cracking margins.
- Concentrated supply risk:Specialty surfactant production concentrates among German and Dutch chemical clusters.
- Performance ceiling:Water-based formulations still struggle with heavy-flash nitrile rubber applications where solvent penetration depth matters.
Strategic Opportunities
- Medical elastomer finishing:ISO 13485-certified deflashing services for implantable device manufacturers command premium positioning.
- US state-level air quality rules:California CARB standards are creating regional demand pockets for low-VOC formulations ahead of federal mandates.
- Supercritical CO₂ convergence:Integration of supercritical fluid extraction with precision cleaning is opening closed-loop process architectures.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-polymer compatibility for multi-substrate finishing remains concentrated among retiring specialists.
- Dual certification burden:Suppliers must maintain both ISO 9001 quality systems and REACH-compliant safety data documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Deflasher Market |
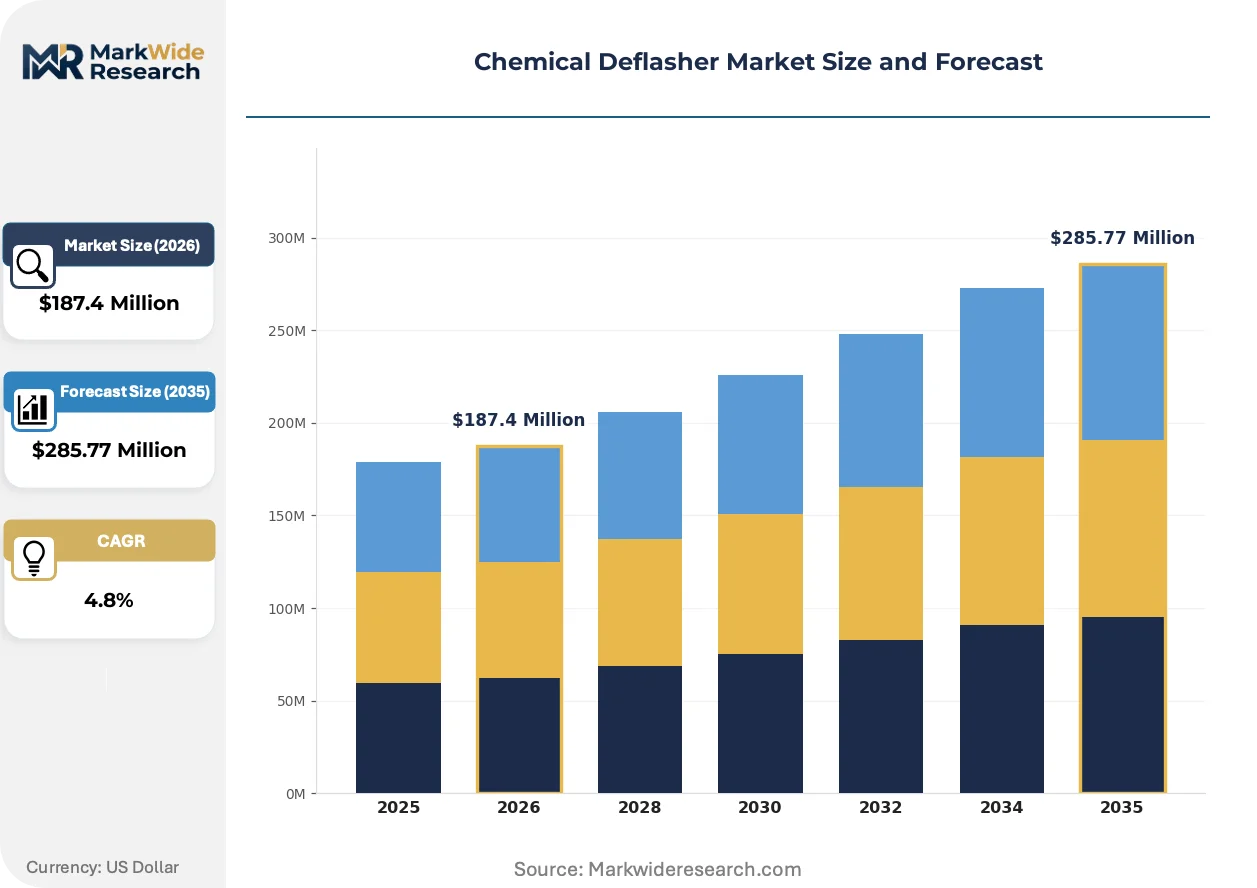
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Eco-Friendly, Aerosol Application: Rubber Manufacturing, Plastics Processing, Textile Treatment, Coating End User: Automotive, Aerospace, Construction, Consumer Goods Packaging Type: Drums, Pails, Bulk Containers, Sachets |
| Companies Covered | 3M Company, BASF SE, Evonik Industries AG, Huntsman Corporation, Dow Chemical Company, Solvay SA, Clariant AG, Mitsubishi Chemical Group, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Deflasher Market Emerging Trajectories
Process intensification and regulatory chemistry are converging to redefine competitive advantage in component finishing, with technology adoption curves now tracking compliance deadlines rather than pure performance metrics.
Supercritical CO₂ deflashing systems are electrifying process economics for high-volume precision molding operations. Automotive seal manufacturers in Stuttgart and Wolfsburg are retrofitting existing trim cells with closed-loop CO₂ recirculation modules. The technology is electrifying capital allocation toward equipment-as-a-service models that transfer chemical risk to vendors.
REACH authorization restrictions on dichloromethane and N-methyl-2-pyrrolidone are compressing the solvent formulation window. ECHA's 2025 sunset review timeline is forcing European compounders to validate water-based alternatives under accelerated testing protocols. Medical device molders in Ireland and the Netherlands are most exposed, with several facilities already switching to enzymatic flash removal for silicone components.
Consolidated procurement through automotive sustainability scorecards is reshaping vendor selection criteria. Buyers now bundle deflashing chemistry purchases with base polymer contracts, squeezing standalone chemical suppliers. German OEM purchasing consortiums are most advanced in this practice, with tier-one suppliers extending compliance requirements to second-tier molders across Eastern Europe.
Chemical Deflasher Market Segmentation
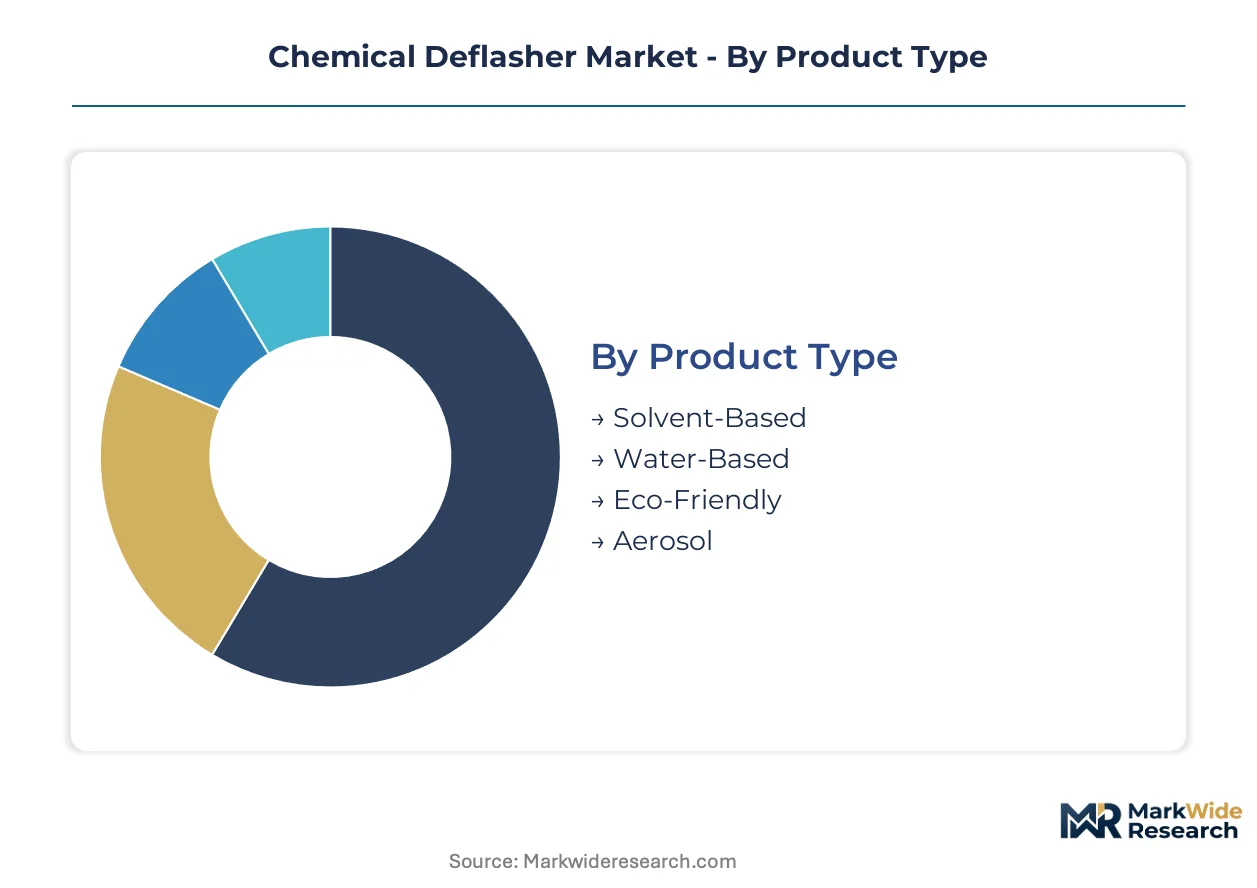
Chemical deflasher procurement decisions pivot on substrate compatibility, regulatory exposure, and process integration requirements. Formulation chemistry determines flash removal efficacy across rubber durometers and thermoplastic crystallinities, while packaging configurations align with compounder batch sizes and automotive tier-one supply chain protocols.
Product Type:
Procurement teams weight total cost of ownership against REACH authorization risk and OSHA exposure thresholds when selecting formulation chemistry.
- Solvent-Based:Chlorinated and hydrocarbon solvent blends deliver deep penetration into heavy-flash nitrile rubber and fluoroelastomer matrices. Demand concentrates at German automotive seal manufacturers serving powertrain applications where mechanical deflashing risks dimensional tolerance drift.
- Water-Based:Surfactant-polymer emulsions eliminate VOC emissions and reduce hazardous waste disposal burdens. Tier-one suppliers in Stuttgart and Wolfsburg now mandate water-based documentation for interior trim components under sustainability scorecard requirements.
- Eco-Friendly:Bio-derived ester formulations and enzymatic cleaners target medical-grade silicone finishing with ISO 13485 process validation.
- Aerosol:Pressurized solvent delivery systems serve prototyping labs and low-volume molders requiring targeted spot deflashing without batch tank infrastructure.
Volume sits with Solvent-Based formulations; growth tilts toward Water-Based alternatives as ECHA sunset dates accelerate.
Application:
Substrate morphology dictates deflasher selection—amorphous rubbers demand different penetration kinetics than semi-crystalline thermoplastics.
- Rubber Manufacturing:Injection-molded EPDM and HNBR seals for automotive cooling systems require flash removal without surface oxidation. Cryogenic deflashing services using liquid nitrogen carriers are displacing mechanical trimming at Irish medical silicone facilities.
- Plastics Processing:PEEK and PPS precision components for aerospace connectors demand non-residue finishing chemistries. Dutch compounders serving AS9100-certified electronics housings specify surfactant-based cleaners compatible with subsequent plasma treatment.
- Textile Treatment:Mold release agent removal from coated fabric substrates uses low-foaming surfactant blends in continuous dip processes.
- Coating:Overspray and edge-bead removal from painted automotive fascias requires solvent systems that attack flash without degrading basecoat adhesion.
Rubber Manufacturing commands the largest formulation volumes; Plastics Processing climbs fastest on aerospace qualification timelines.
End User:
Industry-specific quality system requirements create distinct procurement specifications and certification burdens.
- Automotive:IATF 16949 mandates drive documented deflashing process control with SPC data retention. German OEM purchasing consortiums bundle chemistry contracts with base polymer supply agreements, compressing standalone vendor margins.
- Aerospace:Nadcap accreditation for chemical processing restricts qualified supplier pools. French and Italian tier-two molders serving landing gear component manufacturers face extended validation cycles for new deflasher introductions.
- Construction:EPDM gasket and membrane producers prioritize bulk drum economics over formulation sophistication.
- Consumer Goods:Appliance seal and toy manufacturers balance cost minimization against CPSIA and EU Toy Safety Directive migration limits.
Automotive absorbs the highest premium-grade volumes; Aerospace offers the steepest expansion trajectory on qualification backlogs.
Packaging Type:
Logistics economics and batch size optimization determine container selection across compounder scale tiers.
- Drums:Standard 200-liter steel drums dominate mid-volume rubber processing facilities with weekly formulation turnover cycles.
- Pails:20-25 liter polyethylene containers serve prototyping centers and specialty elastomer compounders requiring frequent product changeovers.
- Bulk Containers:Intermediate bulk containers and tanker deliveries minimize unit costs at high-throughput automotive seal plants in Lower Saxony.
- Sachets:Pre-measured single-use packets support field service operations and export markets with constrained chemical handling infrastructure.
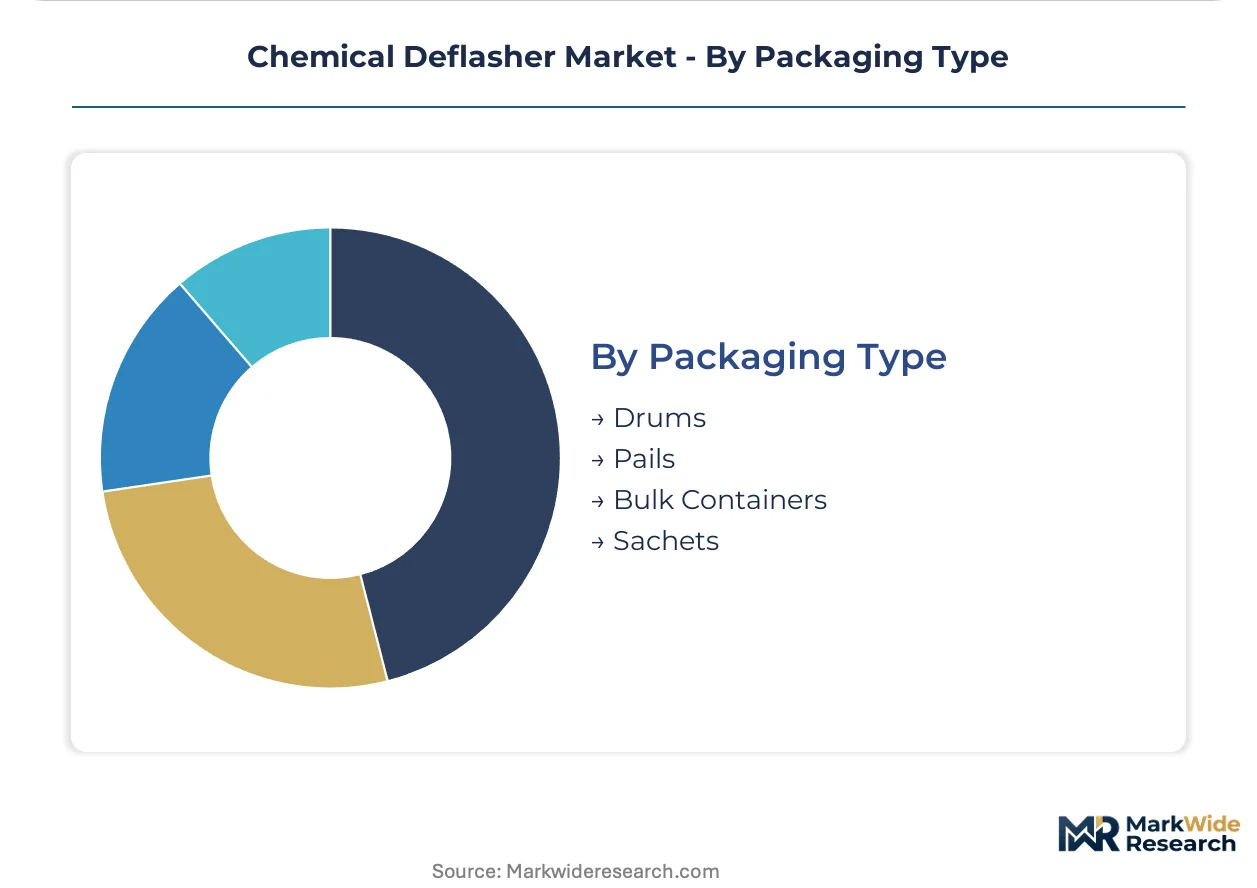
Drums anchor current shipment volumes; Bulk Containers gain share fastest as automotive suppliers consolidate procurement through regional distribution hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and specialty chemical clusters along Germany's Rhine corridor anchor regional production economics for formulated deflashing agents.
United States
Automotive seal manufacturers in Michigan and Ohio drive solvent-based formulation demand for heavy-flash nitrile applications. EPA NESHAP standards for hazardous air pollutants constrain emissions at rubber processing facilities in the Midwest. Houston-area chemical distributors maintain bulk tank infrastructure serving Gulf Coast compounders.
Germany
Precision rubber clusters in Stuttgart and Wolfsburg generate concentrated demand for REACH-compliant water-based alternatives. ECHA authorization timelines for chlorinated solvents accelerate reformulation investments among specialty chemical producers. BASF SE leverages integrated material science platforms from Ludwigshafen to supply both base polymers and finishing chemistries.
China
Automotive component manufacturing expansion in Shanghai and Guangdong provinces creates volume demand for cost-optimized deflashing formulations. MIIT industrial standards for volatile organic compound emissions tighten discharge limits at rubber processing facilities. Yangtze River Delta chemical parks attract surfactant blending capacity for water-based alternatives.
Japan
Medical-grade silicone molders in Osaka and Nagoya prefectures prioritize high-purity solvent systems for implantable device finishing. METI chemical management policies emphasize low-emission process technologies. Kanto region automotive suppliers integrate deflashing documentation into IATF 16949 quality systems.
India
EPDM gasket producers in Maharashtra and Gujarat states balance bulk drum economics against emerging environmental compliance requirements. BIS standards for chemical handling in rubber processing facilities remain under development. Tamil Nadu automotive component clusters adopt cryogenic deflashing services for export-bound precision seals.
Chemical Deflasher Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated petrochemical conglomerates with captive surfactant production, specialty chemical houses focused on application-specific blends, and regional distributors with localized blending operations. Dominant competitive moves include backward integration into surfactant manufacturing and geographic expansion through distribution partnerships in high-growth automotive corridors.
Within the integrated chemical conglomerate tier, BASF SE and Dow Chemical Company exemplify archetypes combining base polymer supply with finishing chemistry portfolios. Evonik Industries AG occupies a position among specialty chemical houses emphasizing high-purity solvent systems. These three entities represent distinct strategic postures: integrated material platforms, water-based sustainability alignment, and medical-grade purity specialization respectively.
| Leading Market Players |
|---|
| 3M Company |
| BASF SE |
| Evonik Industries AG |
| Huntsman Corporation |
| Dow Chemical Company |
| Solvay SA |
| Clariant AG |
| Mitsubishi Chemical Group |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Cryogenic deflashing adoption across German automotive seal plants is compressing unit economics for solvent-based formulations while concentrating procurement leverage among tier-one buyers. REACH-driven reformulation timelines are forcing simultaneous cost structure resets across European supply chains.
Pricing Analysis
Service-bundling models separate process certification documentation from base chemical supply, with IATF 16949-compliant validation packages commanding substantial premiums over unbundled commodity formulations. Three-tier pricing structure separates REACH-authorized solvent systems from water-based alternatives and economy-grade surfactant blends. Cost compression in mid-tier water-based portfolios is intensifying because surfactant feedstock volatility feeds through formulation costs. Automotive tier-one suppliers exhibit lowest price sensitivity due to sustainability scorecard mandates, while construction-sector EPDM compounders prioritize bulk drum economics over performance premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through integrated polymer-chemistry contracts, while specialty distributors serve mid-volume compounders with blended formulations. Production concentrates in Germany, the United States, and China, with Rhine corridor specialty chemical clusters anchoring European supply. Key inputs draw from petrochemical naphtha derivatives, bio-based ester feedstocks, and high-purity surfactant intermediates. Single-source vulnerability concentrates in German-Dutch surfactant manufacturing clusters. Distribution runs through regional chemical distributors with localized blending capabilities serving automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
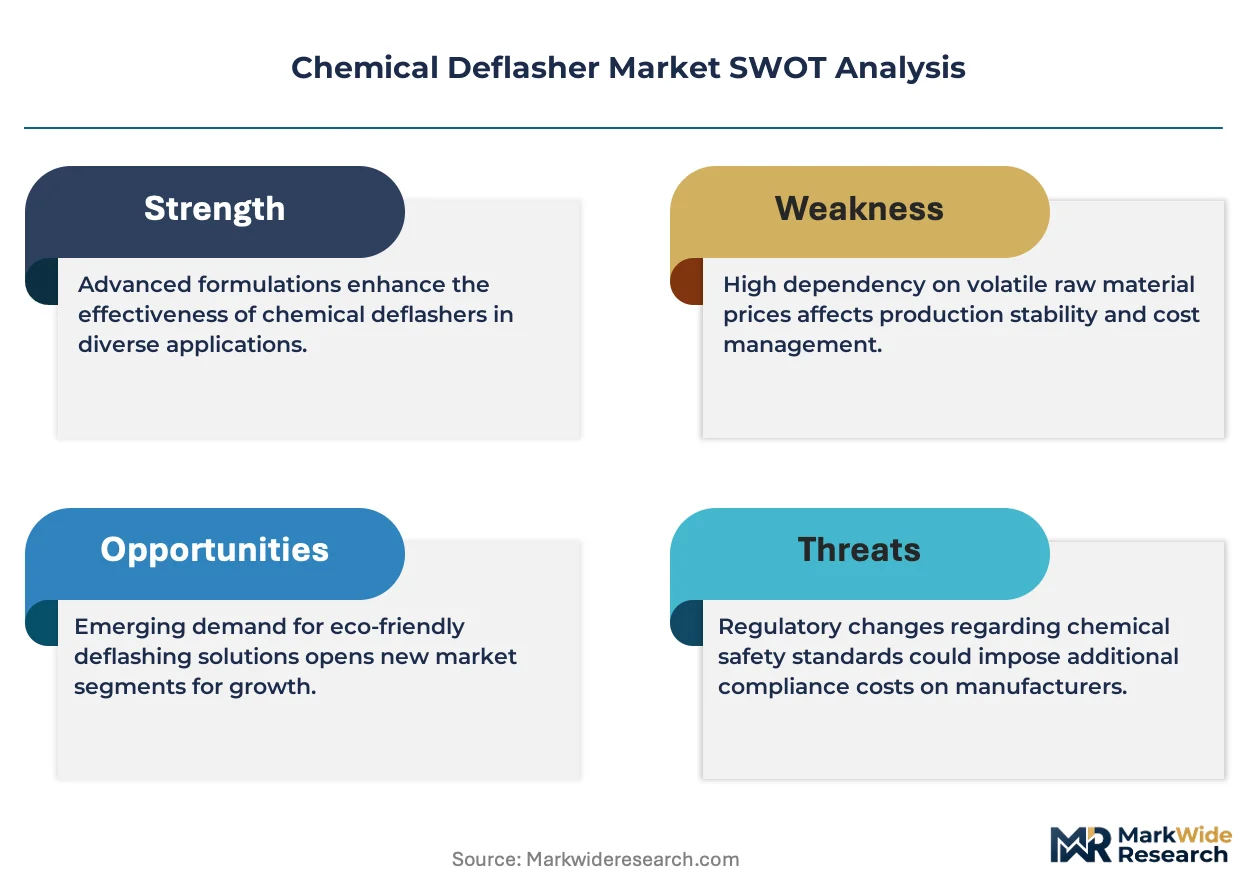
Specialty surfactant production capacity constraints in German and Dutch chemical clusters are propping pricing power for qualified deflasher suppliers. Formulation chemist scarcity limits rapid capacity expansion.
For Market Incumbents: Lock in backward integration into surfactant manufacturing to secure input supply against feedstock volatility and specialized chemist retirement waves. Extend certification investments into ISO 13485 medical-grade validation to capture premium positioning as enzymatic alternatives displace solvent systems in implantable device finishing. For New Entrants and Emerging Players: Enter via cryogenic deflashing service provision rather than commodity chemical supply, targeting Indian and Chinese automotive export clusters where process documentation requirements are tightening fastest. Bundle equipment-as-a-service models with closed-loop CO₂ recirculation to transfer chemical risk and accelerate adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical conglomerates seeking finishing chemistry portfolios. Five-to-ten year viability hinges on successful water-based formulation validation before ECHA sunset dates. Monitor ECHA authorization timeline acceleration as the critical inflection signal for solvent-dependent asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Captive supply of high-purity intermediates insulates margin structures from Rhine corridor concentration risk. |
| Green Manufacturing Transition | Water-based and bio-derived formulations align with EU Green Deal chemical sustainability procurement mandates. |
| Long-term Supply Agreement | Automotive tier-one bundling contracts lock in volume commitments through integrated base polymer supply. |
| Capacity Expansion | Regional blending facilities in Yangtze River Delta chemical parks capture Chinese automotive component demand. |
| Joint Venture | Equipment-as-a-service partnerships with cryogenic system manufacturers transfer chemical risk and accelerate adoption. |
Methodological Framework
Multi-period observation of ECHA authorization timelines, EPA NESHAP enforcement patterns, and automotive OEM sustainability scorecard evolution anchored the trend analysis, supplemented by interviews with formulation chemists, procurement leads at tier-one automotive suppliers, plant managers at rubber processing facilities, and distribution channel partners. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up segmentation modeling and top-down macroeconomic triangulation cross-checked volume and value estimates.
Input-output matrices mapped formulation chemistry costs through packaging configurations to end-user price points across the projection horizon. Segmentation dimensions modeled include product type chemistry, substrate application, end-user industry quality systems, and regional regulatory clusters. CAGRs were derived from slope analysis of period-to-period growth trajectories. Industry-specific forecast inputs incorporated surfactant-polymer compatibility testing protocols and cryogenic equipment penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA sunset schedules or feedstock supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Tools Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Anthracite Fines Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Carborundum Market
Abrasives
New Zealand Abrasives Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Synthetic Abrasives Market
Abrasives
Liquid Sandpaper Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Australia Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Abrasive Cloth Market