
 Ginger Ale Market | 2026-2036
Ginger Ale Market Size, Share, and Industry Trends Forecast 2026-2036
Ginger Ale Market Analysis
The ginger ale category is pivoting sharply between premium artisanal formulations and mass-market commodity production. Fevertree Drinks Plc leverages its botanical heritage and mixer positioning to command premium shelf space in European and North American bars. PepsiCo Inc. anchors the mainstream segment through Canada Dry's decades-old distribution network in convenience and grocery channels. Boylan Bottling Co. differentiates through cane-sweetened, glass-bottled heritage recipes that occupy specialty retail and independent restaurant accounts.
Ginger ale is a carbonated soft drink flavored with ginger root extract or artificial ginger flavoring, typically containing carbonated water, sweeteners, acidulants, and preservatives, with alcohol content below 0.5% by volume; it functions primarily as a standalone refreshment beverage and as a cocktail mixer in bars and restaurants. The organic product type segment leads margin capture as consumers pay premiums for certified non-GMO ginger sourcing and natural sweeteners. Cans dominate packaging volume due to portability and recycling economics, though glass bottles sustain higher per-unit profitability in on-premise hospitality settings where visual presentation influences purchase decisions.
The FDA governs ingredient labeling and GRAS status for ginger extracts and flavor additives in the United States, while the EU's F-Gas Regulation and broader Green Deal frameworks pressure manufacturers to decarbonize production and shift toward recyclable packaging formats. State-level sugar taxes in California and New York are forcing reformulation toward diet and zero-sugar variants. Stakeholders must monitor evolving sweetener regulations and packaging mandates to anticipate which product architectures will retain channel access across diverging regulatory environments.
Market Dynamics
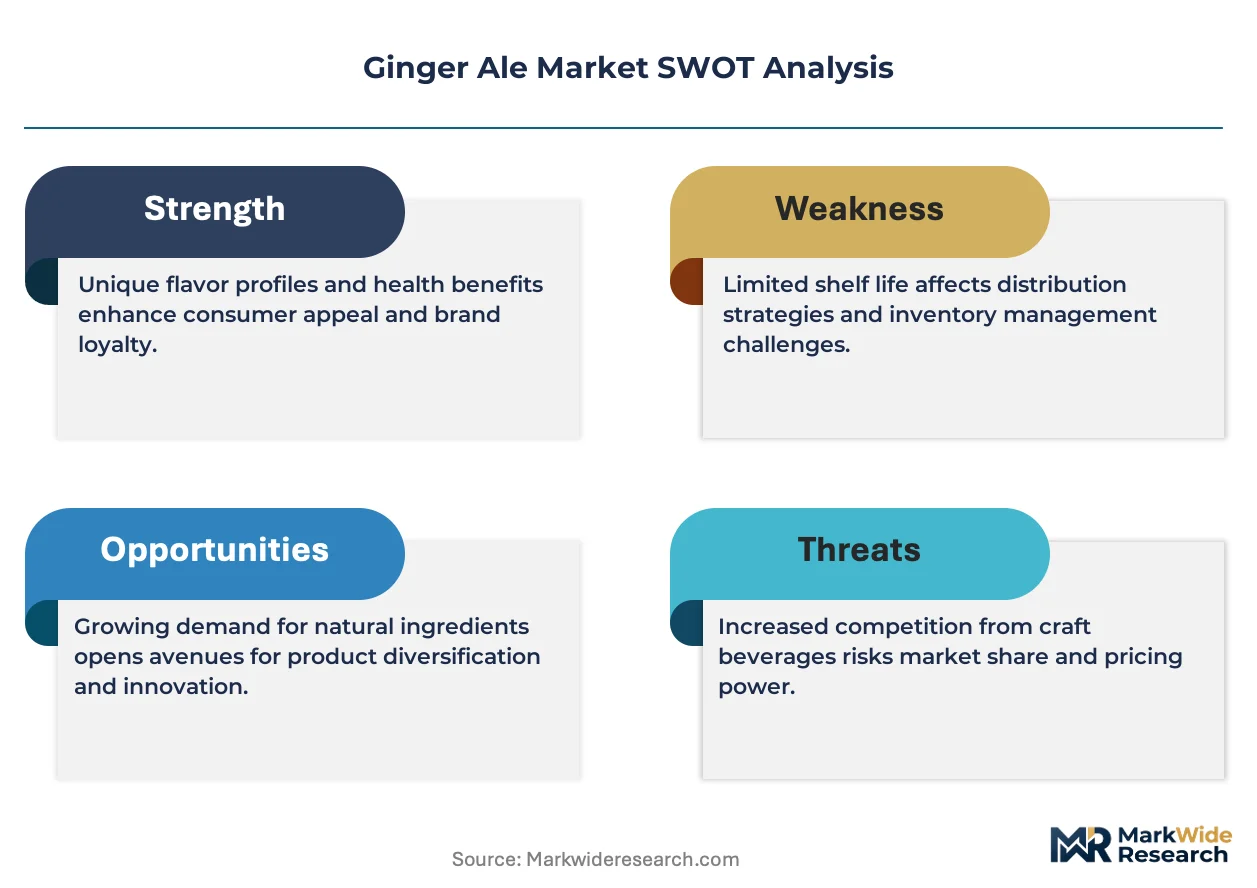
The ginger ale category faces a structural pivot between mass-market commodity production and premium craft positioning, driven by clean-label mandates and sugar reduction policies that are forcing simultaneous reformulation across multiple price tiers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating investment in energy-efficient carbonation systems, reducing production emissions for manufacturers operating across Germany, France, and Italy.
- Cocktail culture expansion:High-end mixology programs in metropolitan hospitality clusters are elevating ginger ale from commodity mixer to curated ingredient, opening shelf space for botanical-forward formulations.
- Glass bottling revival:Independent restaurants and specialty retailers are prioritizing visual presentation and perceived authenticity, creating pull-through for heritage packaging formats that command price premiums.
Market Restraints
- Input cost volatility:Certified organic ginger root from India and Nigeria faces harvest variability and currency fluctuation, compressing margins for clean-label product lines.
- Supply concentration risk:Carbon dioxide sourcing for carbonation concentrates among industrial gas suppliers in the US Gulf Coast, exposing producers to regional production disruptions.
- Technical limitation:Natural ginger extract stability remains inferior to artificial flavoring, shortening shelf life and constraining distribution radius for premium formulations.
Strategic Opportunities
- Underpenetrated India:Rising disposable income and expanding modern trade retail in Mumbai, Delhi, and Bangalore create whitespace for both premium imports and localized production.
- Regulatory tailwind:California's sugar-sweetened beverage tax and New York's proposed equivalent are accelerating consumer trial of zero-sugar variants that retain full-margin pricing.
- Direct-to-hotel distribution:Bypassing traditional beverage distributors to supply cocktail bars and boutique hotels directly captures margin and builds brand equity in influential on-premise accounts.
Industry Challenges
- Reformulation complexity:Replacing high-fructose corn syrup with natural alternatives like monk fruit or stevia requires extensive sensory testing and supply chain requalification, extending new product timelines.
- Certification backlog:USDA Organic and Non-GMO Project verification queues are stretching to 14-18 months, delaying market entry for new clean-label entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ginger Ale Market |
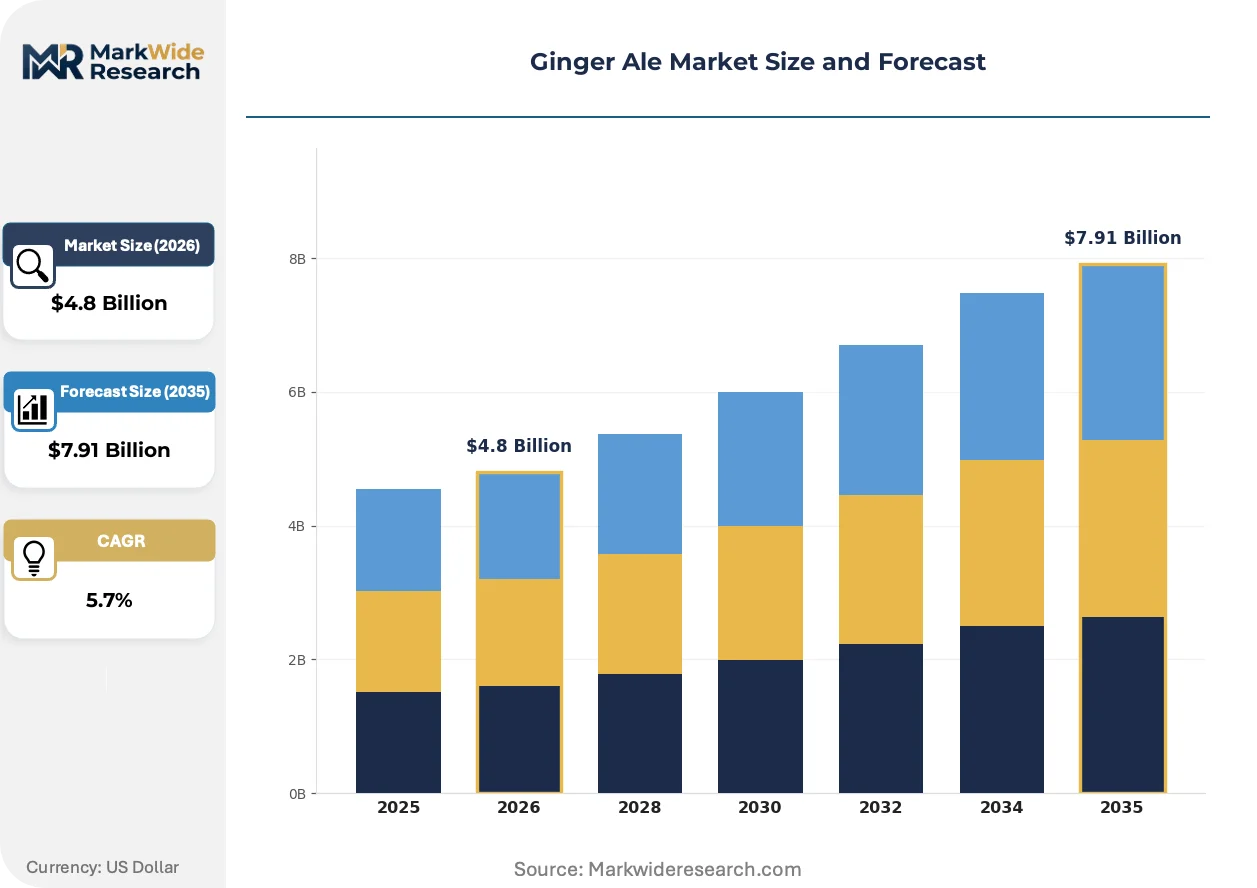
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Diet, Spicy, Organic Packaging Type: Cans, Glass Bottles, Plastic Bottles, Kegs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Restaurants End User: Households, Food Service, Events, Hospitality |
| Companies Covered | Fevertree Drinks Plc, Buffalo Rock Company, The Coca Cola Co., Boylan Bottling Co., Blenheim Ginger Ale, PepsiCo Inc., Canada Dry, Reeds, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ginger Ale Market Emerging Trajectories
Carbonation technology, regulatory chemistry standards, and procurement behavior are converging to reshape how ginger ale is formulated, packaged, and sold across hospitality and retail channels.
Precision fermentation for natural ginger flavor compounds is rewriting the economics of premium formulation. Biotech suppliers in California and the Netherlands are scaling microbial-derived extracts that match artificial intensity with clean-label compliance. Major beverage manufacturers are piloting these inputs to bridge the stability gap that has constrained all-natural product lines.
REACH authorization requirements for food contact materials are tightening migration limits for can linings and bottle coatings across EU member states. Manufacturers serving Germany and France are accelerating transitions to epoxy-phenolic alternatives or glass-heavy portfolios. The compliance burden falls hardest on mid-tier producers lacking dedicated regulatory affairs capacity.
Bar and restaurant buyers are consolidating supplier relationships around single-source beverage programs that bundle mixers, sodas, and non-alcoholic options. Distributors in Texas and Florida are responding with curated portfolios that replace fragmented purchasing across multiple vendors. This consolidation favors suppliers with breadth across tonic, ginger beer, and ginger ale rather than mono-product specialists.
Ginger Ale Market Segmentation
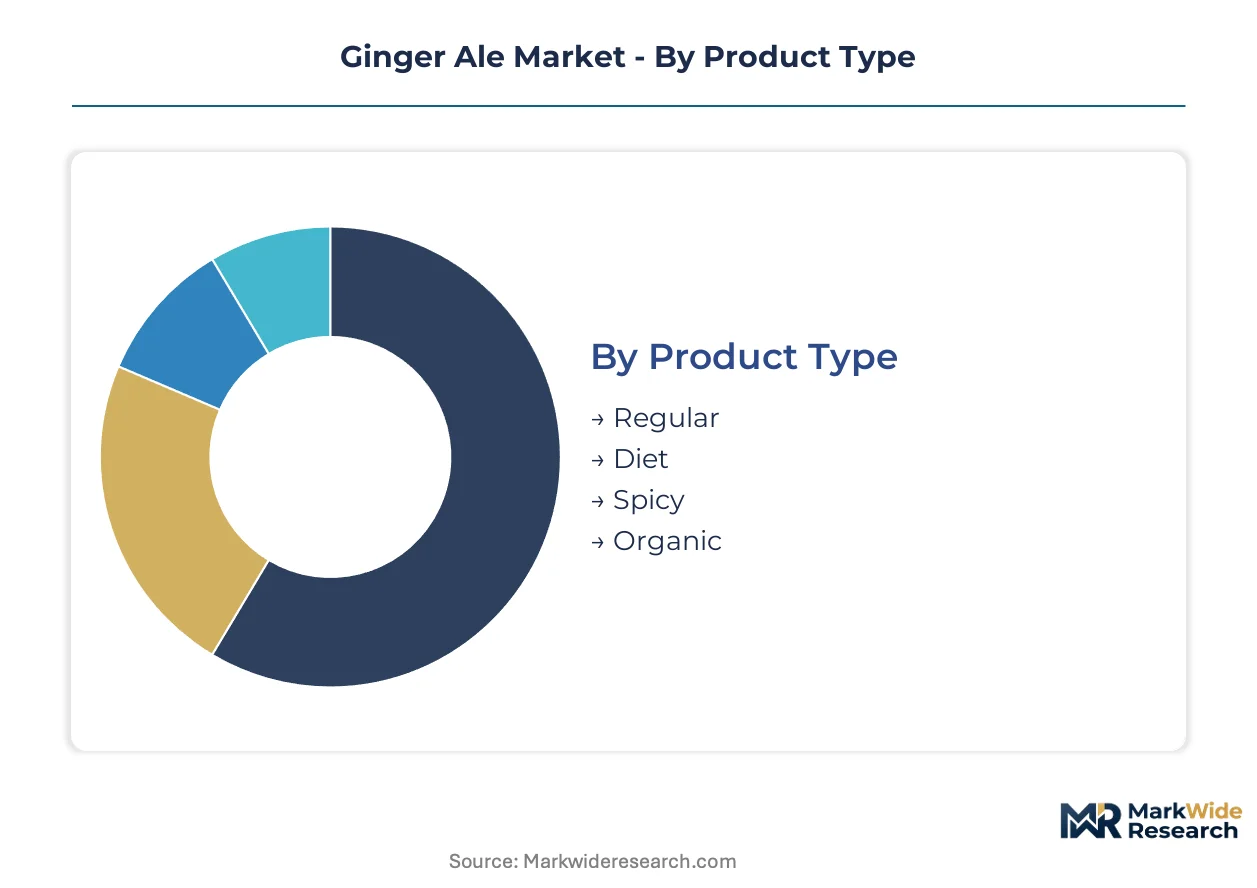
Ginger ale segmentation reveals divergent margin architectures across formulation intensity and channel access. Premium organic variants command shelf-space premiums in specialty retail while commodity regular formulations anchor volume through mass grocery distribution.
Product Type:
Standardization dominates at the base of this spectrum while certified organic and heat-calibrated spicy variants occupy customization extremes with supply chain complexity premiums.
- Regular:High-fructose corn syrup or cane sugar formulations with conventional ginger extract. Volume concentrates in US metropolitan grocery chains where Canada Dry and Schweppes maintain decades-old cooler placement contracts with retailers.
- Organic:Certified non-GMO ginger root from India or Nigeria combined with natural sweeteners like agave or coconut sugar. Demand clusters in Whole Foods Market and independent natural grocers across California and New York where clean-label mandates drive reformulation.
- Diet:Aspartame, sucralose, or stevia-sweetened variants targeting sugar-reduction compliance. State-level sugar taxes in California and New York accelerate placement in convenience store cold vaults.
- Spicy:Elevated gingerol content through fresh root processing or added capsicum heat. Cocktail bars in Austin, Nashville, and Brooklyn adopt these for signature Moscow Mule and Whiskey Ginger builds.
Leading the category by volume: Regular. Expanding most quickly: Organic.
Packaging Type:
Cost tier separation runs from single-serve aluminum cans at economy scale to refillable keg systems for hospitality volume contracts.
- Cans:Aluminum 12-ounce and 16-ounce formats dominate recycling economics and portability. PepsiCo and Keurig Dr Pepper deploy can-heavy portfolios through Walmart and Target distribution centers in Texas and Florida.
- Glass Bottles:Heritage 12-ounce and 750-ml formats with crown or swing-top closures. Independent restaurants in Chicago and San Francisco prioritize visual presentation and perceived authenticity, accepting 40-60% per-unit premiums over cans.
- Plastic Bottles:PET 2-liter and 20-ounce formats for family-size pantry stocking. Dollar General and Aldi channels in the US Southeast move volume through price-focused multi-packs.
- Kegs:Stainless steel 5-gallon and 15.5-gallon systems for on-premise dispensing. Boutique hotels in Miami and Charleston deploy kegged ginger ale for high-velocity bar programs with reduced packaging waste.
Highest velocity: Cans. Steepest expansion trajectory: Glass bottles.
Distribution Channel:
Customer type stratification separates planned pantry loading from immediate consumption and curated hospitality procurement.
- Supermarkets:Full-category shelving with planogram placement fees driving visibility. Kroger and Albertsons in California negotiate slotting allowances that favor multi-brand suppliers with tonic and ginger beer breadth.
- Convenience Stores:Cold vault single-serve placement for impulse purchase. 7-Eleven and Circle K in Texas prioritize 20-ounce plastic bottles and 12-ounce cans with rapid inventory turns.
- Online Retail:Direct-to-consumer and marketplace fulfillment with subscription bundling. Amazon and Thrive Market move premium glass-bottled and organic variants through pantry-box programs with reduced last-mile costs.
- Restaurants:On-premise fountain, bottle, and keg supply with menu integration. Full-service chains in New York and Los Angeles specify ginger ale for cocktail builds and non-alcoholic beverage programs.
Dominant by volume: Supermarkets. Gaining share fastest: Online retail.
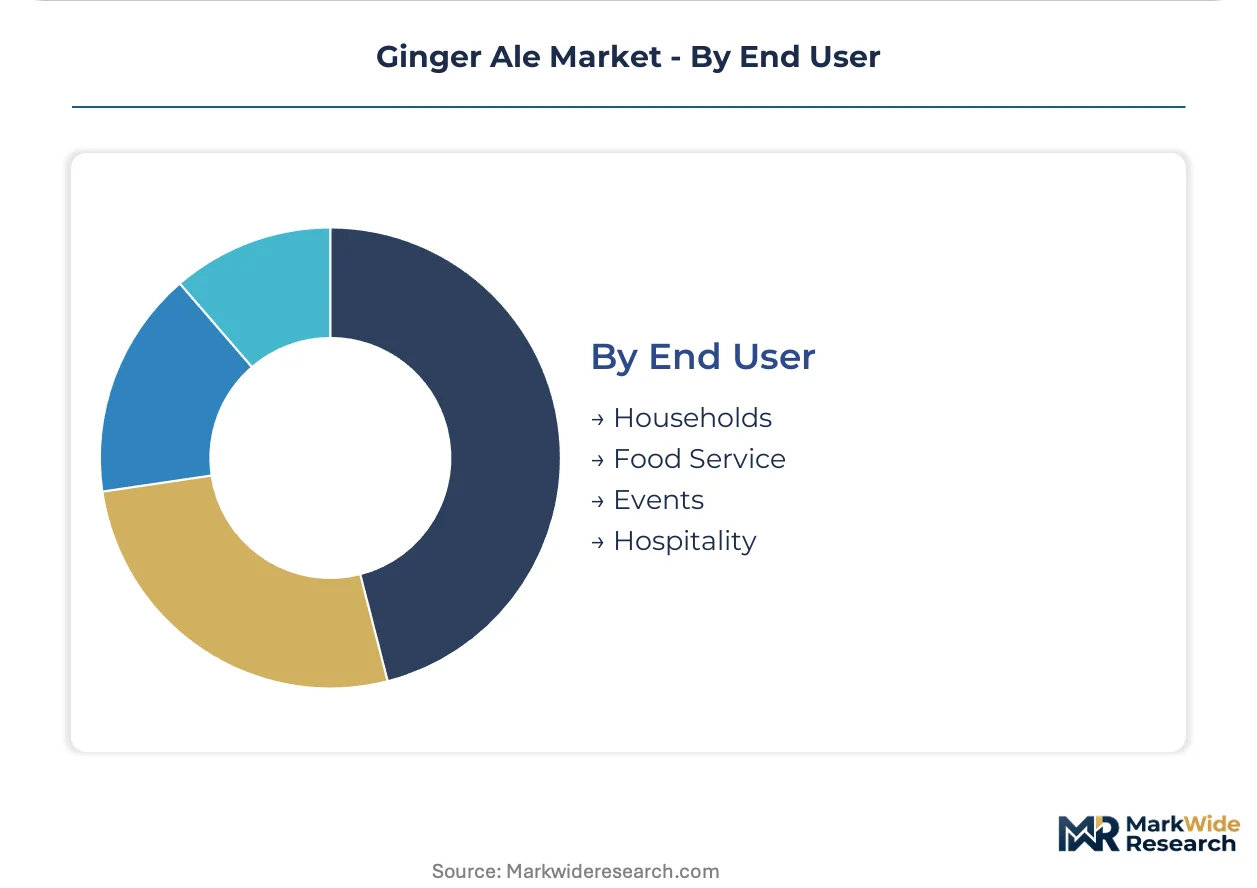
End User:
Application maturity spans from established household pantry stocking to emerging event-based consumption with specialized logistics requirements.
- Households:At-home consumption for standalone refreshment and home bartending. Suburban markets in the US Northeast stock regular and diet variants for family consumption and occasional mixing.
- Food Service:Quick-service and fast-casual fountain and bottle service. Panera Bread and similar chains specify ginger ale in automated fountain systems with calibrated syrup-to-water ratios.
- Events:Temporary permits and mobile bar service for weddings and corporate functions. Rental distributors in Atlanta and Phoenix supply kegged and canned formats with ice and equipment packages.
- Hospitality:Boutique hotels and cocktail bars with curated beverage programs. Independent properties in New Orleans and Portland source heritage glass-bottled variants for minibar and lobby bar differentiation.
Core volume driver: Households. Climbing the fastest: Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan hospitality clusters in New York, Los Angeles, and Chicago anchor North American ginger ale consumption through cocktail bar procurement and premium retail placement. Distribution networks radiate from these nodes into suburban grocery and convenience channels. Regulatory pressure on sugar content and packaging waste is reshaping formulation and sourcing decisions across key markets.
United States
State-level sugar taxes in California and New York accelerate zero-sugar variant development while FDA labeling requirements govern ginger extract GRAS status. The FDA enforces ingredient disclosure standards for natural and artificial flavorings. Cocktail bars in Brooklyn and Austin drive demand for spicy, botanical-forward formulations that command per-unit premiums over mass-market alternatives.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing carbonation equipment upgrades in Bavarian and North Rhine-Westphalian production facilities. REACH authorization tightens migration limits for can linings and bottle coatings. Berlin's independent restaurant scene prioritizes glass-bottled heritage formats that signal authenticity to discerning consumers.
United Kingdom
London's mixology culture elevates ginger ale from commodity mixer to curated cocktail ingredient, opening shelf space for premium botanical formulations. The UK Environment Agency enforces packaging waste regulations that accelerate aluminum recycling economics. Fevertree Drinks Plc leverages its botanical heritage to capture premium positioning in Manchester and Edinburgh hospitality clusters.
India
Rising disposable income in Mumbai, Delhi, and Bangalore creates whitespace for both premium imports and localized production targeting modern trade retail. FSSAI standards govern food additive safety and labeling requirements for carbonated beverages. Domestic ginger cultivation in Kerala and Karnataka offers supply chain advantages for natural extract sourcing.
Japan
Tokyo's high-end izakaya and hotel bar programs import heritage glass-bottled variants for minibar differentiation and craft cocktail builds. METI promotes decarbonization targets that pressure packaging transitions toward recyclable formats. Osaka's beverage distributors consolidate supplier relationships around single-source programs bundling mixers and non-alcoholic options.
Ginger Ale Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation intensity and channel access, with botanical-forward specialists commanding hospitality placement while mass-market brands anchor grocery volume. The vendor base stratifies into three tiers: heritage craft bottlers, multinational beverage conglomerates, and emerging organic specialists. Consolidation pressure favors suppliers with breadth across mixer categories rather than mono-product lines. Dominant competitive moves include direct-to-hotel distribution bypass and portfolio diversification into adjacent carbonated mixers.
Within the heritage craft tier, Boylan Bottling Co. and Blenheim Ginger Ale exemplify cane-sweetened, glass-bottled positioning that captures specialty retail and independent restaurant accounts through perceived authenticity. Fevertree Drinks Plc anchors the premium botanical segment, leveraging mixer-category expertise to command bar placement in European and North American metropolitan clusters. These three represent archetypal strategies: heritage recipe preservation, botanical specialization, and premium channel capture.
| Leading Market Players |
|---|
| Fevertree Drinks Plc |
| Buffalo Rock Company |
| The Coca Cola Co. |
| Boylan Bottling Co. |
| Blenheim Ginger Ale |
| PepsiCo Inc. |
| Canada Dry |
| Reeds |
| Keurig Dr Pepper |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up craft bottlers like Boylan and Blenheim anchor the premium tier through cane-sweetened heritage recipes, while their disciplined inventory management and direct-to-hotel distribution preserve margin architecture against multinational price compression. This ownership pattern concentrates supply negotiation leverage with organic ginger cooperatives in Kerala and Karnataka, insulating premium producers from commodity sweetener volatility that erodes mass-market profitability.
Pricing Analysis
Value-based pricing anchored to cocktail-bar throughput and per-drink yield commands the steepest premiums in Brooklyn, Austin, and Nashville hospitality clusters. Three-tier pricing structure across premium, standard, and economy levels separates certified organic glass-bottled variants from cane-sweetened mainstream cans and high-fructose corn syrup commodity formats. Cost compression in the regular segment is intensifying because state-level sugar taxes in California and New York force reformulation investment. Mass-market grocery buyers exhibit highest price sensitivity, while boutique hotel procurement teams prioritize brand equity and menu differentiation over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and California operate hub-and-spoke patterns radiating from PepsiCo and Keurig Dr Pepper consolidation points. Ginger root sourcing draws from India, Nigeria, and domestic cultivation in Florida and Hawaii, while aluminum can sheet feeds from domestic mills and carbon dioxide concentrates among Gulf Coast industrial gas suppliers. Single-source vulnerability in CO2 procurement exposes producers to regional production disruptions. Distribution runs through beverage distributors in most channels, though direct-to-hotel bypass is gaining traction in metropolitan hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ginger ale category sits in a formulation-transition phase, as precision-fermentation-derived ginger compounds replace legacy artificial flavoring systems and reshape premium product economics.
For Market Incumbents: Extend botanical credibility through precision-fermentation partnerships with California and Netherlands biotech suppliers, closing the stability gap that constrains all-natural distribution radius. Fortify position against craft entrants by locking multi-year cooler placement contracts with Kroger and Albertsons in California, using tonic and ginger beer portfolio breadth to consolidate planogram access. Prioritize zero-sugar variant R&D to capture full-margin pricing under California and New York sugar tax regimes.
For New Entrants and Emerging Players: Begin with underpenetrated modern trade retail in Mumbai, Delhi, and Bangalore, where rising disposable income and FSSAI-compliant domestic production create whitespace for both premium imports and localized organic lines. Target hospitality procurement in Charleston, Portland, and New Orleans boutique hotels, where minibar differentiation demands heritage glass-bottled formats. Pursue direct-to-bar distribution bypassing legacy beverage distributors to capture margin and build brand equity in influential on-premise accounts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor organic-certified mid-caps with India supply chain relationships in Kerala and Karnataka, where climate volatility and certification backlogs compress near-term valuations. Long-term viability hinges on five-to-ten-year positioning for clean-label regulatory convergence across North America and Europe. Watch USDA Organic and Non-GMO Project verification queue lengths as inflection indicator for new entrant supply constraints and incumbent moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial-derived ginger compounds from California biotech firms bridge clean-label compliance with shelf-life stability. |
| Direct-to-Hotel Distribution | Bypassing Texas and Florida beverage distributors captures margin in Miami and Charleston boutique hotel accounts. |
| Zero-Sugar Variant Launch | Stevia and monk fruit reformulation retains full-margin pricing under California and New York sugar tax frameworks. |
| Glass Bottling Capacity Expansion | Swing-top heritage formats command 40-60% premiums in Chicago and San Francisco independent restaurant channels. |
| India Supply Chain Integration | Domestic organic ginger cultivation in Kerala reduces harvest variability exposure and FSSAI compliance friction. |
Methodological Framework
Document review covered FDA GRAS filings for ginger extracts, EU REACH authorization databases for food contact materials, and FSSAI carbonated beverage standards, complemented by interviews with brand managers at heritage craft bottlers, category buyers at Whole Foods Market and Kroger, procurement leads at boutique hotel chains in New Orleans and Portland, and supply planners at aluminum can manufacturers. Secondary validation drew from Nielsen retail audit data, customs import records for organic ginger root, and SEC 10-K beverage segment disclosures. Bottom-up channel volume estimates and top-down category spend analysis were triangulated against production capacity disclosures.
Segment-level projections across product type, packaging format, distribution channel, and end-user application were generated through the analysis window. The modeling framework incorporated formulation cost curves for natural versus artificial ginger inputs, state-level sugar tax implementation timelines, and carbonation equipment upgrade cycles under EU F-Gas Regulation phasedown schedules. CAGRs were derived from regression analysis of historical volume trends against macroeconomic indicators and regulatory event markers.
Underlying measurement precision varies by segment; regular and diet variants with established retail distribution carry tighter precision than emerging spicy and organic lines with fragmented hospitality penetration. Forecasts reflect documented assumptions regarding sugar tax expansion, certification queue durations, and precision-fermentation commercialization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Bottled Water Market
Beverages
Powdered Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Soft Serve Premix Market
Beverages
Sports and Energy Drinks Market
Beverages
Sarsaparilla Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Kombucha Market
Beverages
Oat Based Beverages Market
Beverages
Beverage Premix Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Crystal Boba Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Aloe Vera Drinks Market
Beverages
Asia Pacific Soy Beverages Market