
 Oat Based Beverages Market | 2026-2036
Oat Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Based Beverages Market Intelligence
Formulation development for specialty applications, such as barista-grade milks and infant formulas, is rewriting the competitive positioning for manufacturers. Oatly Group AB leverages its brand strength and early-mover advantage in the cafe channel. In contrast, Danone, through its Alpro brand, competes with a broad portfolio across multiple plant-based categories. Califia Farms differentiates with unique flavor profiles and cold-brew coffee blends.
Oat based beverages are non-dairy liquid products derived from whole or rolled oat groats processed with water and enzymes. The primary purpose is to serve as a milk alternative for direct consumption, in cereals, or as an ingredient in coffee and cooking, catering to dietary preferences and restrictions. Plain oat drink and oat milk variants dominate volume, but flavored oat drink options for health-conscious consumers are expanding rapidly. While supermarkets remain the core distribution channel, sales through online retail and direct-to-consumer models are accelerating.
Labeling standards are governed by agencies like the US FDA and the European Food Safety Authority (EFSA), which dictate the use of terms like 'milk'. Fortification guidelines, such as those from Health Canada, influence the addition of vitamins and minerals, shaping product formulation and health claims. Producers must navigate evolving consumer perceptions of processing techniques and ingredient transparency to maintain brand trust.
Market Dynamics
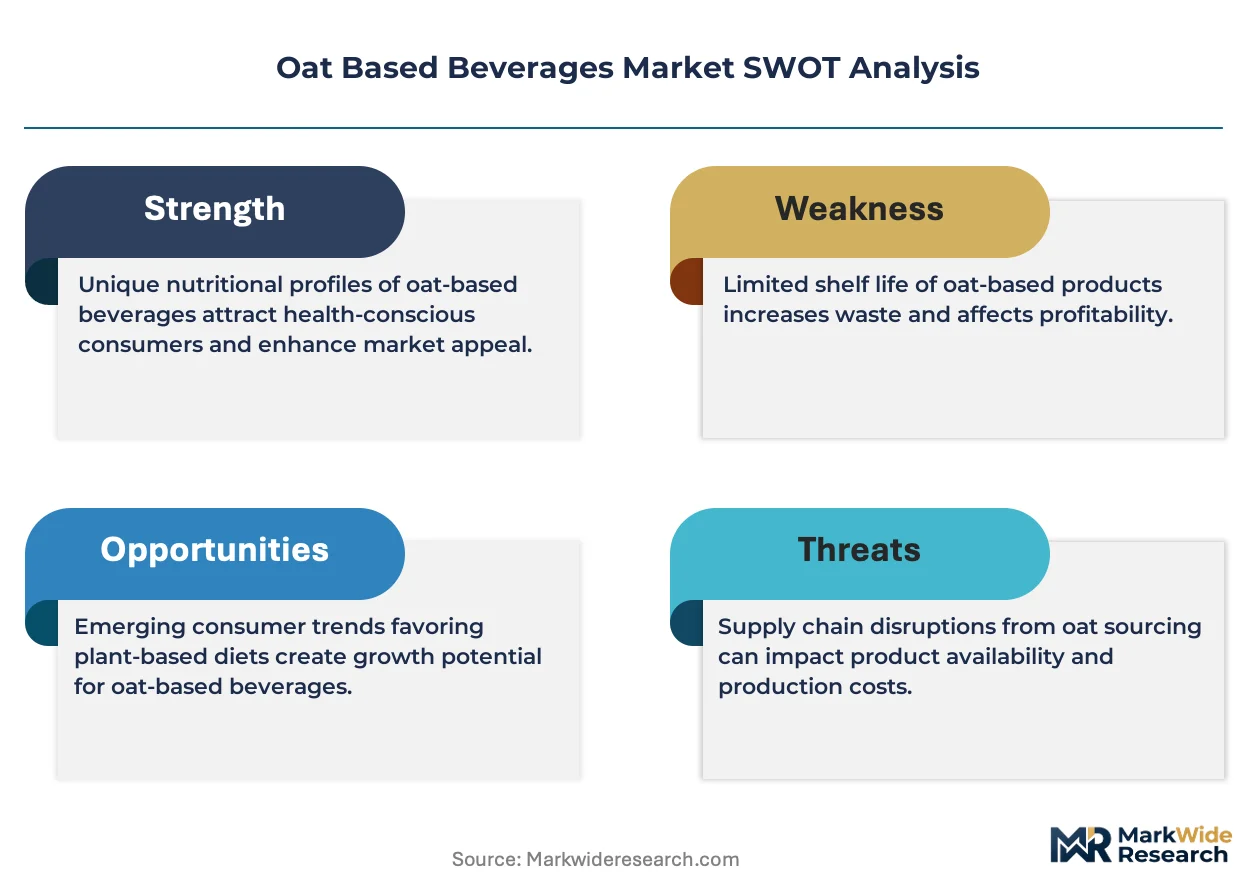
The central tension shaping the oat beverage market is the conflict between achieving industrial scale for mass-market products and the specialized formulation science required for high-margin applications like barista-grade milks and fortified nutritional drinks.
Growth Catalysts
- Enzyme Technology Advancements:Progress in enzymatic hydrolysis allows for improved control over the texture and natural sweetness of oat beverages, reducing the need for added sugars and hydrocolloids, which appeals to health-conscious consumers.
- Food Service Channel Demand:Strong demand from coffee shops in urban centers, particularly in the United Kingdom and Germany, for barista-grade oat milk that delivers consistent foamability and taste profiles is a significant catalyst.
- Fortification Mandates and Guidelines:Regulatory frameworks, such as those from Health Canada, encourage or mandate the fortification of plant-based milk alternatives with vitamins and minerals, enhancing their nutritional profile and consumer appeal.
Market Restraints
- Oat Price Volatility:As an agricultural commodity, the price and quality of oats are subject to fluctuations from weather events and global supply-demand imbalances, creating input cost instability for manufacturers.
- Regulatory Labeling Restrictions:Food safety authorities like the US FDA and the European Food Safety Authority (EFSA) restrict the use of dairy-related terms such as 'milk', creating marketing and consumer education hurdles.
- Intense In-Category Competition:Oat beverages face strong substitution threats from other established plant-based alternatives, including almond, soy, and coconut milk, which compete for the same consumer base and shelf space.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity for market entry and growth in underpenetrated metropolitan areas across Asia-Pacific where dietary habits are shifting and lactose intolerance rates are high.
- Specialized Nutritional Formulations:Development of oat-based products for specific dietary needs, such as infant formulas or clinical nutrition products for the elderly, represents a high-value growth avenue.
- Direct-to-Consumer Channels:Building out online retail and subscription-based direct-to-consumer (DTC) models enables brands to capture higher margins, control the customer experience, and gather valuable consumption data.
Industry Challenges
- Cold Chain Logistics:Expanding distribution for fresh, refrigerated oat beverage lines requires significant capital investment in cold chain infrastructure to ensure product quality and safety, especially in new geographic markets.
- Consumer Perception of Processing:Manufacturers must manage consumer skepticism regarding processing techniques like enzymatic treatments and ultra-high temperature (UHT) pasteurization to maintain ingredient transparency and brand trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Based Beverages Market |
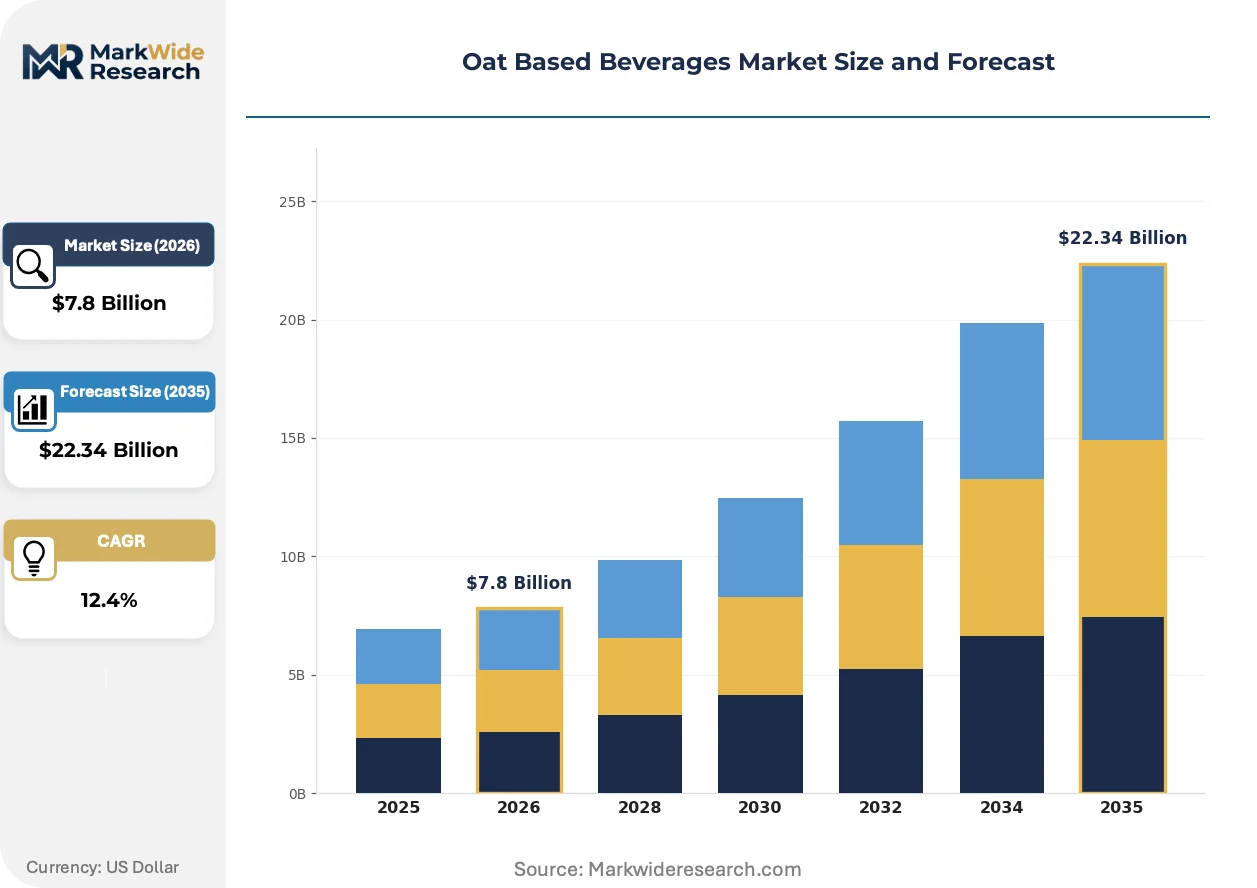
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.34 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Oat Drink, Flavored Oat Drink, Oat Milk, Oat Cream End User: Health-Conscious Consumers, Vegan Customers, Lactose-Intolerant Individuals, Coffee Shops Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafes Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | Quaker Oats Company, Danone, Oatly Group AB, Elmhurst 1925, PepsiCo, Califia Farms, Pacific Foods, Minor Figure, Alpro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Based Beverages Market Strategic Shifts & Innovations
The market's evolution is being defined by a dual focus on both sophisticated food science for functional performance and the parallel consumer demand for clean-label, minimally processed products. This dynamic is reshaping formulation strategies and supply chain priorities.
Enzyme technology, particularly the use of amylase and beta-glucanase, serves to break down oat starches into simpler sugars and modify viscosity. Food service operators and manufacturers of blended coffee drinks are the primary adopters, seeking superior frothing and blending characteristics. The formulation focus is migrating from basic liquefaction to precise enzymatic hydrolysis that engineers sweetness and mouthfeel, reducing reliance on added sugars and stabilizers.
In Europe, regulations enforced by the European Food Safety Authority (EFSA) concerning dairy terminology have a profound impact on market presentation. This policy prohibits the labeling of oat-based products as 'milk', compelling brands to use alternative descriptors like 'drink' or 'beverage'. The segment most affected is consumer marketing, where brands must invest in educating shoppers and crafting packaging that clearly communicates the product's use case without using protected terms.
A significant behavioral change is the consumer pivot toward online subscription and direct-to-consumer (DTC) purchasing. This channel shift often circumvents traditional supermarket retailers, especially for niche or premium-flavored products. This purchasing pattern is particularly visible in developed, digitally-native consumer markets within North America and Western Europe, where logistics networks support efficient home delivery.
Oat Based Beverages Market Segmentation
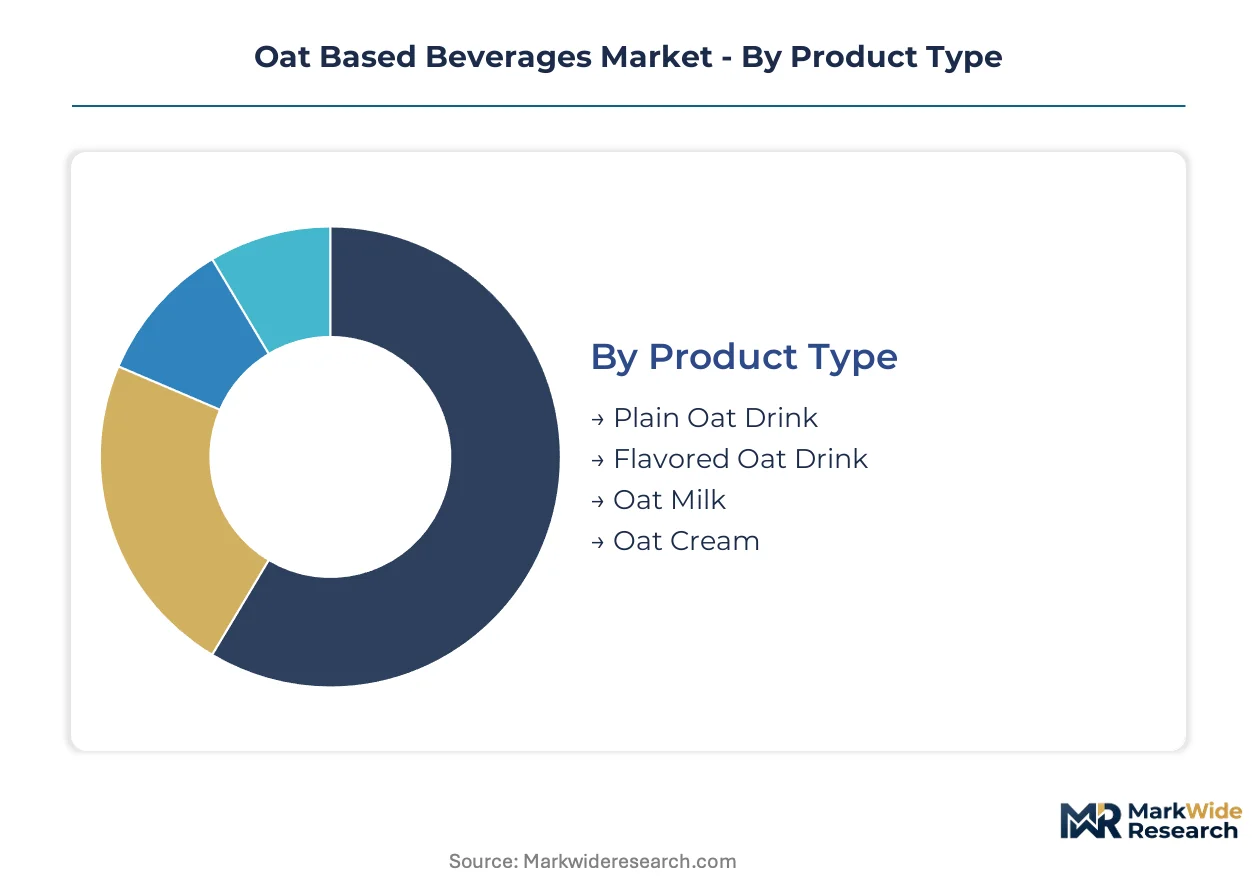
Segmentation analysis provides a granular understanding of the oat based beverages market, dissecting it into distinct categories that reveal varying demand patterns, consumer preferences, and distribution dynamics. This detailed classification helps manufacturers tailor product development and market entry strategies to specific niches. Understanding these segments clarifies the competitive landscape and identifies areas for strategic investment.
Product Type:
The product type segmentation reveals a spectrum of maturity, from established staples to rapidly innovating formulations.
- Plain Oat Drink:This foundational category consists of unflavored oat beverages, often used as a direct milk alternative in cereals, coffee, or for cooking. Demand concentrates in urban centers across the United Kingdom and Germany, driven by general dietary shifts.
- Flavored Oat Drink:These products incorporate natural or artificial flavors like vanilla, chocolate, or fruit, targeting consumers seeking variety and a more palatable taste experience. The expansion of these options appeals to health-conscious consumers seeking alternatives to traditional sugary drinks.
- Oat Milk:This segment encompasses formulations specifically designed to mimic dairy milk in texture and application, often fortified with vitamins and minerals. It serves a broad base of consumers looking for plant-based dairy substitutes.
- Oat Cream:Oat cream products are thicker, higher-fat formulations intended for culinary uses like cooking, baking, or as a coffee creamer. These specialty applications cater to specific foodservice and home cooking needs.
Plain Oat Drink handles the majority of throughput; Flavored Oat Drink is the fastest mover on share.
End User:
End user segmentation highlights the diverse applications driving demand for oat-based beverages across various consumer groups and commercial settings.
- Coffee Shops:This segment represents a significant end-user category, particularly for barista-grade oat milk formulations that offer superior frothing and blending characteristics. Strong demand originates from urban centers in the United Kingdom and Germany.
- Health-Conscious Consumers:Individuals prioritizing nutritional value, clean labels, and reduced sugar content drive demand for oat beverages with specific health claims and fortification. This demographic values the natural sweetness and fiber content of oat products.
- Vegan Customers:This segment exclusively seeks plant-based alternatives to animal products, making oat beverages a staple in their diet for direct consumption and culinary applications. Vegan customers prioritize ethical sourcing and ingredient transparency.
- Lactose-Intolerant Individuals:Consumers unable to digest lactose turn to oat beverages as a dairy-free alternative that provides similar nutritional benefits and versatility. This group values the digestive comfort offered by oat products.
Coffee Shops represent a critical consumption point; Health-Conscious Consumers are expanding most quickly.
Distribution Channel:
Distribution channel analysis reflects varying cost tiers and accessibility points, influencing consumer purchasing behaviors for oat beverages.
- Supermarkets:These large retail outlets remain the core distribution channel for mass-market oat beverage products, offering broad accessibility and competitive pricing. Supermarkets cater to routine grocery shopping needs.
- Online Retail:E-commerce platforms and brand-specific direct-to-consumer models enable convenient purchasing and accelerated sales, especially for niche or premium-flavored products. This channel is gaining traction in digitally-native consumer markets.
- Specialty Stores:Health food stores and organic markets cater to consumers seeking premium, organic, or specific dietary-compliant oat beverages. These stores often offer a curated selection and expert advice.
- Cafes:Coffee shops and other foodservice establishments serve as a key distribution point for ready-to-drink oat beverages and barista-grade formulations. This channel introduces products to consumers in a prepared format.
Supermarkets remain the primary retail channel; Online Retail shows the steepest expansion trajectory.
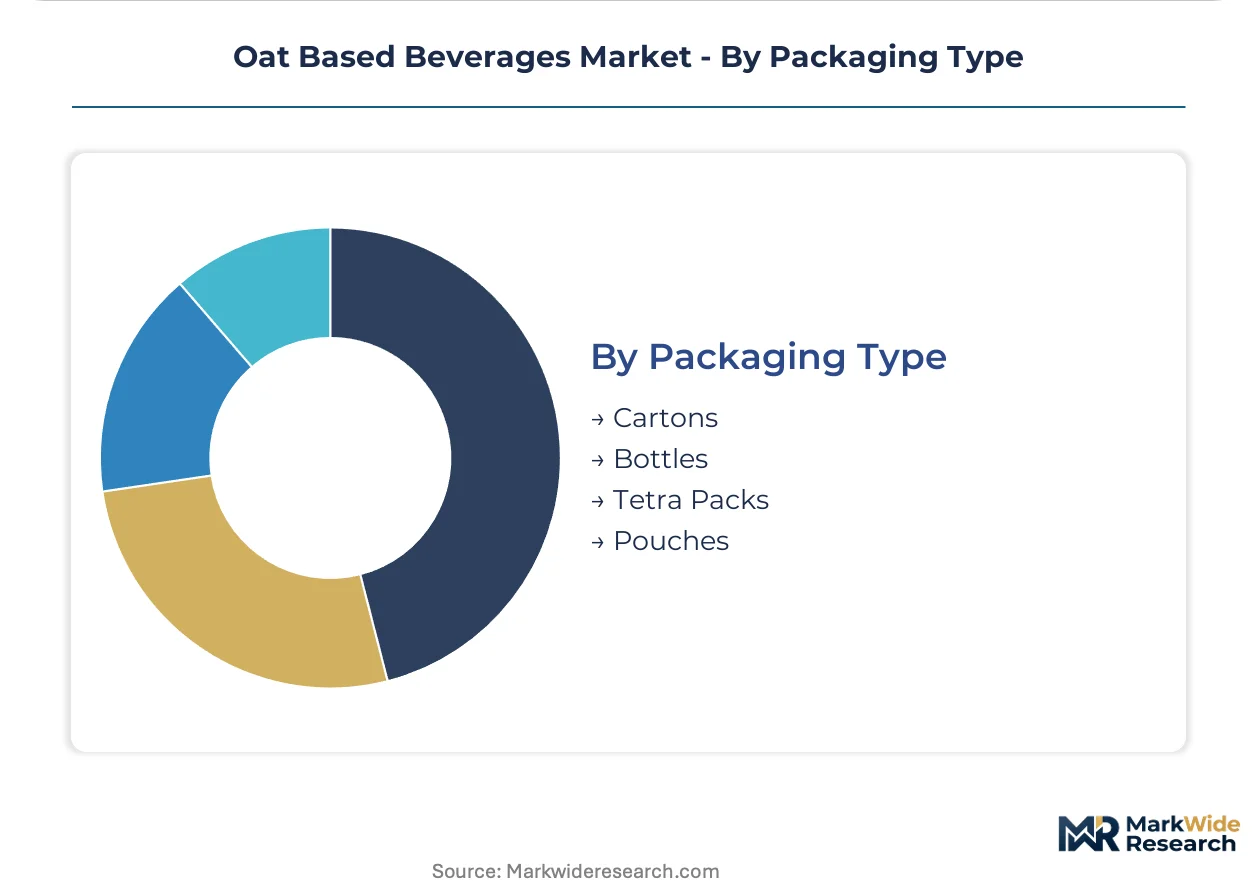
Packaging Type:
Packaging type segmentation delineates the formats optimized for different volume requirements and consumer convenience in the oat beverage market.
- Cartons:Multi-layer cartons are widely used for shelf-stable and refrigerated oat beverages, offering protection from light and oxygen while being cost-effective for large volumes. This format is prevalent in supermarket distribution.
- Tetra Packs:Similar to cartons, Tetra Pak packaging provides extended shelf life for aseptic oat beverages without refrigeration until opened. This packaging is favored for its environmental profile and efficient storage.
- Bottles:Plastic or glass bottles are used for both single-serve and multi-serve oat beverage formats, often for premium or ready-to-drink options. Bottles offer resealability and a clear view of the product.
- Pouches:Flexible pouches are an emerging packaging format, particularly for smaller, on-the-go servings or specialty products. Pouches offer reduced material use and a lighter footprint.
Cartons dominate overall packaging volume; Pouches are gaining share fastest among new formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for oat-based beverages exhibits varying price elasticity across global markets. Consumers in developed Western European and North American urban centers often prioritize premium barista-grade formulations, showing less price sensitivity. Conversely, emerging markets in Asia-Pacific seek more affordable, versatile plant-based alternatives for broader dietary integration.
United Kingdom
Urban consumers in the United Kingdom drive significant demand for barista-grade oat milk and flavored oat drinks. The Food Standards Agency (FSA) provides guidance on food labeling, influencing product claims and consumer trust. London's vibrant coffee culture, for instance, remains a critical hub for innovation and consumption of specialty oat beverages.
Germany
German consumers show strong demand for plain oat drinks as a versatile dairy alternative and for specialty coffee applications. European Food Safety Authority (EFSA) regulations on 'milk' terminology shape marketing strategies and product descriptors across the country. Berlin's metropolitan area demonstrates high per capita consumption, fostering new product introductions and cafe partnerships.
United States
The United States market sees robust demand for fortified oat milk and diverse flavored options, catering to health-conscious consumers. The US Food and Drug Administration (FDA) governs labeling standards for plant-based beverages, impacting nutritional claims and market entry. California's health-focused population and extensive retail networks serve as a key growth engine for innovative oat beverage brands.
Japan
Japanese consumers increasingly adopt oat beverages due to rising health awareness and lactose intolerance rates. Japan's Ministry of Health, Labour and Welfare (MHLW) oversees food safety standards, influencing ingredient approvals and product formulations. Tokyo's urban centers, with their sophisticated food trends, are witnessing a rapid expansion in cafe and retail offerings for oat-based products.
Oat Based Beverages Market Key Industry Players
Established food conglomerates and agile plant-based specialists split the market for oat-based beverages, creating a dynamic competitive environment. The market structure features large-scale, diversified players leveraging extensive distribution networks alongside niche innovators focusing on premiumization and specific functional benefits. Dominant competitive moves include broad portfolio diversification into new plant-based categories and strategic partnerships with coffee shop chains to secure critical channel access. Capacity expansion in processing facilities also remains a key competitive lever for market share gains.
Within the diversified conglomerate archetype, Danone, through its Alpro brand, exemplifies a broad portfolio approach spanning multiple plant-based categories and consumer segments. Oatly Group AB represents an early-mover specialist, leveraging strong brand recognition and deep channel focus within the demanding cafe segment. Califia Farms, a US-based company, anchors the innovation-driven segment, consistently differentiating through unique flavor profiles and strategic cold-brew coffee blends that appeal to a specific consumer base. These players collectively illustrate the varied strategies employed to capture market share in the dynamic oat beverage landscape.
| Leading Market Players |
|---|
| Quaker Oats Company |
| Danone |
| Oatly Group AB |
| Elmhurst 1925 |
| PepsiCo |
| Califia Farms |
| Pacific Foods |
| Minor Figure |
| Alpro |
| Others |
Cost & Logistics Intelligence
The Rotterdam-London freight corridor's cost dynamics influence supply concentration and downstream price differentiation for oat beverages. This corridor's efficiency impacts the affordability of imported raw materials and finished goods, shaping competitive pricing strategies in major European consumption hubs.
Pricing Analysis
Barista-grade formulations, designed for superior frothing and blending, drive lifetime value in the oat beverage market. Value-based pricing differentiates products, with brand premium and specialized application capabilities serving as key factors. Pricing softness affects plain oat drinks in mass-market channels, largely due to intense in-category competition from other plant-based alternatives. Urban coffee shops demonstrate less price sensitivity for high-performance barista-grade milks, while supermarket consumers prioritize affordability for everyday use.
Supply Chain Analysis
Investment in cold chain logistics facilities shapes the oat beverage supply chain, impacting product reach and preservation. Raw oat supply primarily concentrates in agricultural regions like Canada, the United States, and parts of the European Union. Key dependencies include whole oat groats, specialized enzymes, and aseptic packaging materials. Oat price volatility, influenced by weather events and global demand imbalances, represents a significant structural risk. Distribution runs predominantly through supermarket retail networks for mass-market products, complemented by direct-to-consumer models for niche offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oat based beverages market represents an early-cycle expansion story, driven by significant penetration tailwinds from shifting dietary preferences and increased health awareness.
For Market Incumbents: Build brand equity moats by continually innovating in enzyme technology to enhance natural sweetness and texture. Consolidate market share through strategic partnerships with major coffee shop chains, especially in high-growth urban centers like London and Berlin. Diversify product portfolios across specialized nutritional formulations to mitigate intense in-category competition from emerging plant-based alternatives.
For New Entrants and Emerging Players: Underpenetrated metropolitan areas across Asia-Pacific, where lactose intolerance rates are high, represent the most penetrable entry points. Focus on developing specialized nutritional formulations, such as infant formulas or clinical nutrition products, to target high-value niches. Leverage direct-to-consumer models to build brand loyalty and gather consumption data, circumventing established supermarket distribution channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core plant-based assets. Long-term viability hinges on identifying niche innovators with proprietary enzyme technologies or strong brand recognition in specific application segments. A critical signal to watch is the accelerated growth of online retail and subscription-based models, indicating shifts in consumer purchasing behavior.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand enzyme technology R&D | Improves natural sweetness and texture, reducing reliance on added sugars and hydrocolloids. |
| Invest in cold chain infrastructure | Enables wider distribution of fresh, refrigerated oat beverage lines into new geographic markets. |
| Form strategic cafe partnerships | Secures critical channel access and reinforces brand perception in high-visibility urban centers. |
| Develop specialized nutritional products | Unlocks high-value growth avenues in infant formula and clinical nutrition segments. |
| Accelerate direct-to-consumer channel build-out | Captures higher margins and provides valuable consumption data for product development. |
Research Approach
A spread of perspectives from R&D directors, procurement leads at coffee chains, food safety regulators, and marketing executives at oat beverage brands converged on the working assumptions for this analysis. Primary interviews provided qualitative insights, which were then validated against secondary sources including EFSA reports, US FDA guidelines, Health Canada guidelines, and trade association reports. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
The demand-supply-balance framing guided the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end user, distribution channel, packaging type, and regional consumption patterns. Compound annual growth rates were derived from historical data trends and projected market dynamics, with oat commodity prices and enzyme technology adoption rates serving as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income or global agricultural commodity prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and sustained consumer preference for plant-based alternatives. New regulatory restrictions, unforeseen supply chain disruptions, or significant shifts in consumer dietary preferences could revise the forecast.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Saudi Arabia Bottled Water Market
Beverages
Premium Bottled Water Market
Beverages
Caffeine Mint Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Indonesia Bottled Water Market
Beverages
Recovery Drinks Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Beverage Cooler Market
Beverages
Probiotic Beverage Market
Beverages
Blackstrap Molasses Market
Beverages
Kvass Market
Beverages
Superfood Infused Beverages Market
Beverages
Global Soda Maker Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
United Kingdom Energy Drink Market
Beverages
Hydrogen Water Bottle Market