
 Hydrogen Water Dispenser Market | 2026-2036
Hydrogen Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Water Dispenser Market Foresight
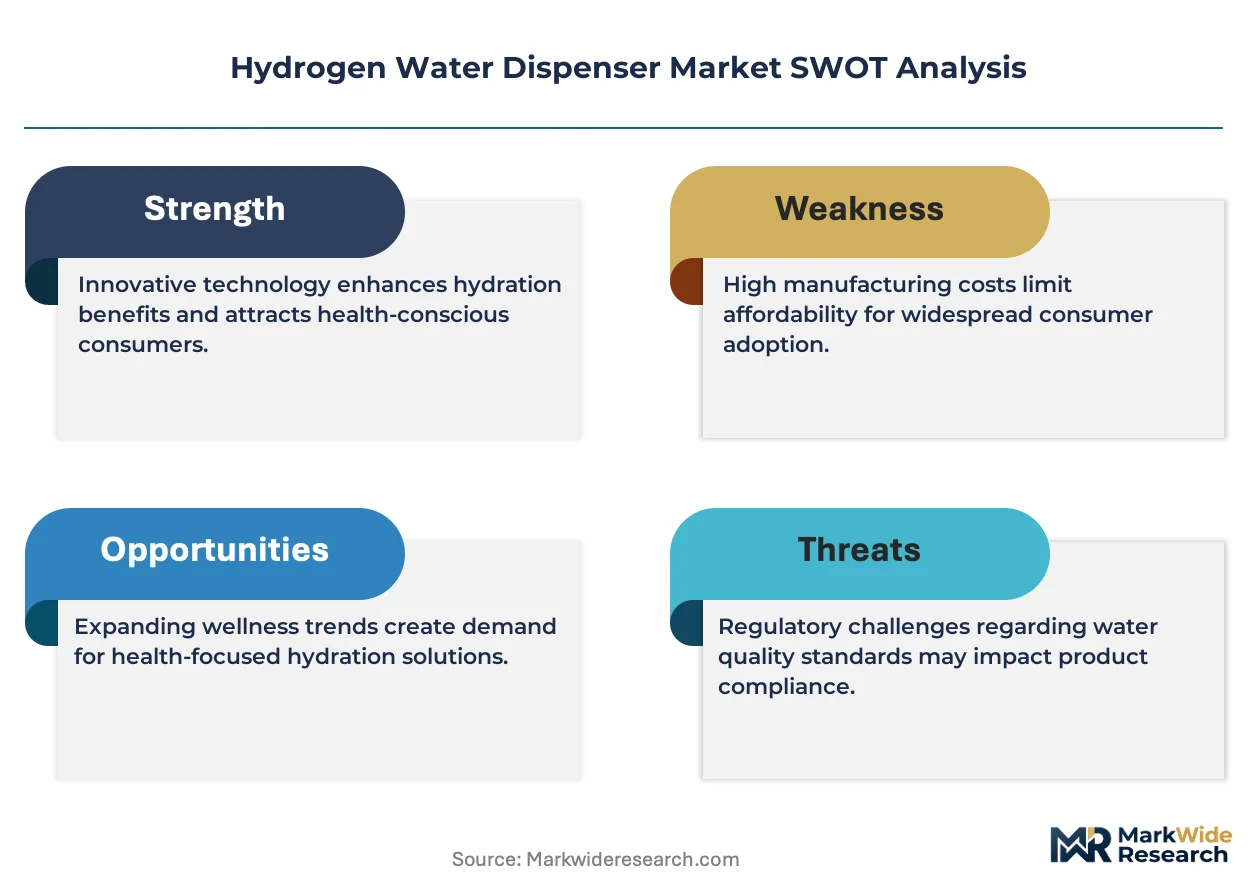
REACH compliance in Europe is restructuring material sourcing requirements for hydrogen water dispenser manufacturers, raising certification costs for new entrants. SOLCO Biomedical leverages its biomedical heritage to anchor premium positioning in clinical-adjacent channels. KENT RO SYSTEMS LTD dominates India's residential water purification infrastructure and extends that channel control into hydrogen-enabled product lines. Guangzhou Olansi Healthcare Co., Ltd specializes in OEM manufacturing scale, competing primarily on cost-adjusted output volumes for export markets.
A hydrogen water dispenser infuses potable water with dissolved molecular hydrogen gas, typically achieving concentrations between 0.5 and 1.6 parts per million through electrolysis or magnesium reaction methods, to deliver antioxidant functionality for consumer hydration applications. Portable dispensers occupy the fastest-growing tier as gym memberships and corporate wellness budgets expand, while countertop models sustain the largest installed base in East Asian households. Electrolysis technology leads on performance metrics but membrane separation methods are gaining share where energy efficiency regulations tighten operational cost structures.
The US FDA classifies hydrogen water devices under food-contact substance guidelines, while China's SAMR enforces GB standard compliance for electrical safety and water quality outputs, and Japan's PMDA maintains pharmaceutical-adjacent oversight for medical-grade claims. These overlapping frameworks fragment certification pathways and extend product development timelines for multi-region suppliers. Stakeholders must monitor evolving hydrogen concentration labeling requirements as consumer protection agencies sharpen enforcement against unsubstantiated health benefit claims.
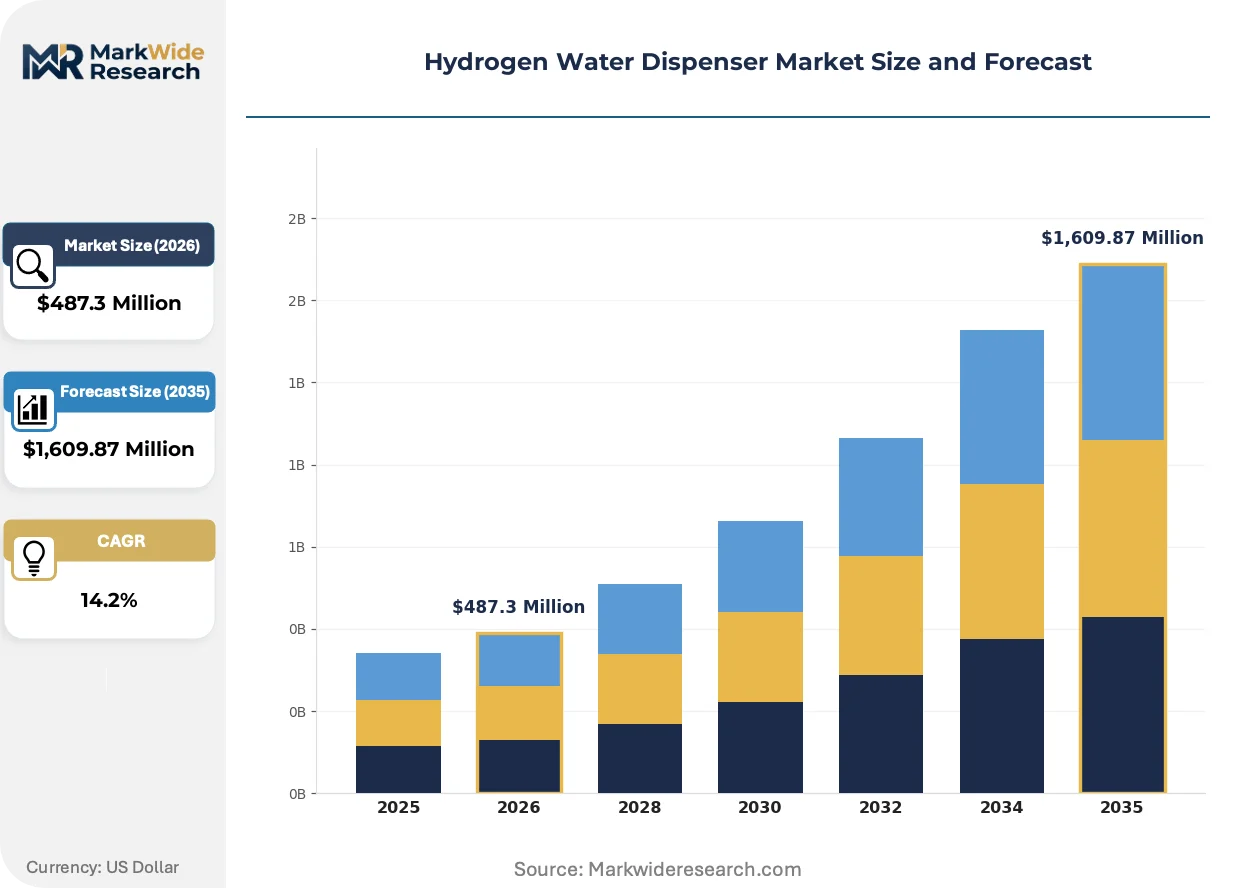
Market Dynamics
Electrolysis membrane miniaturization is compressing unit footprints while maintaining hydrogen saturation rates, forcing incumbent manufacturers to retool assembly lines or surrender countertop share to portable specialists.
Growth Catalysts
- Japan's PMDA pharmaceutical-adjacent framework:Medical-grade hydrogen concentration claims unlock clinical channel access, differentiating premium dispensers from general wellness appliances.
- South Korean wellness hospitality chains:On-property hydrogen water programs create B2B equipment procurement pipelines with recurring filter replacement revenue.
- China's tier-one consumer health expenditure:Beijing, Shanghai, and Shenzhen households outpace national averages for preventive health device adoption, concentrating initial demand.
Market Restraints
- Platinum-coated titanium electrode costs:Electrolysis stack materials face precious metal price volatility, pressuring gross margins on mid-tier units.
- REACH compliance restructuring:ECHA material sourcing mandates raise certification costs for new European entrants, consolidating incumbency advantages.
- Magnesium reaction substitutes:Lower-cost hydrogen generation methods cap pricing power for electrolysis-based systems in price-sensitive segments.
Strategic Opportunities
- India's residential water purification infrastructure:Established RO distribution networks provide channel scaffolding for hydrogen-enabled product line extensions.
- EU Drinking Water Directive purity upgrades:Tightening filtration standards create upgrade cycles for integrated hydrogen-plus-filtration systems.
- Gym membership expansion:Fitness center hydration stations represent underpenetrated B2B deployment for portable dispenser formats.
Industry Challenges
- Multi-region certification timelines:FDA food-contact substance guidelines, SAMR GB standards, and PMDA pharmaceutical oversight fragment approval pathways, extending product development cycles.
- Hydrogen concentration labeling enforcement:Consumer protection agencies sharpen scrutiny against unsubstantiated antioxidant benefit claims, requiring clinical substantiation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Water Dispenser Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dispensers, Countertop Models, Built-in Units, Commercial Systems Technology: Electrolysis, Membrane Separation, Magnesium Method, Chemical Reaction End User: Households, Offices, Restaurants, Gyms Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | SOLCO Biomedical, KENT RO SYSTEMS LTD, SENZA, HOVOGEN, Guangzhou Olansi Healthcare Co., Ltd, NuLife Sciences Inc., Fujiiryoki India, AquaCure, Guangzhou TESRAN Purification Equipment Manufacturing Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Water Dispenser Market Shifts & Advancements
Membrane separation methods are gaining traction where energy efficiency regulations tighten operational cost structures, compressing the historical electrolysis dominance in commercial installations.
Solid polymer electrolyte stacks is overtaking liquid electrolyte designs in portable dispenser manufacturing. Gym operators and corporate wellness coordinators are specifying these units for mobile hydration stations. The technology is overtaking legacy architectures by eliminating reservoir sloshing and enabling IP-rated enclosure designs for outdoor deployment.
REACH substance restriction updates are forcing filtration media reformulation across European supply chains. Activated carbon block suppliers must certify against newly restricted chemical compounds. German and French manufacturers are accelerating in-house membrane casting to bypass third-party certification delays.
Subscription filter replacement programs are displacing transactional aftermarket sales. Direct-to-consumer channels capture recurring revenue through IoT-connected dispensers that auto-trigger consumable shipments. This model concentrates in China's tier-one cities where mobile payment infrastructure supports seamless billing integration.
Hydrogen Water Dispenser Market Segmentation
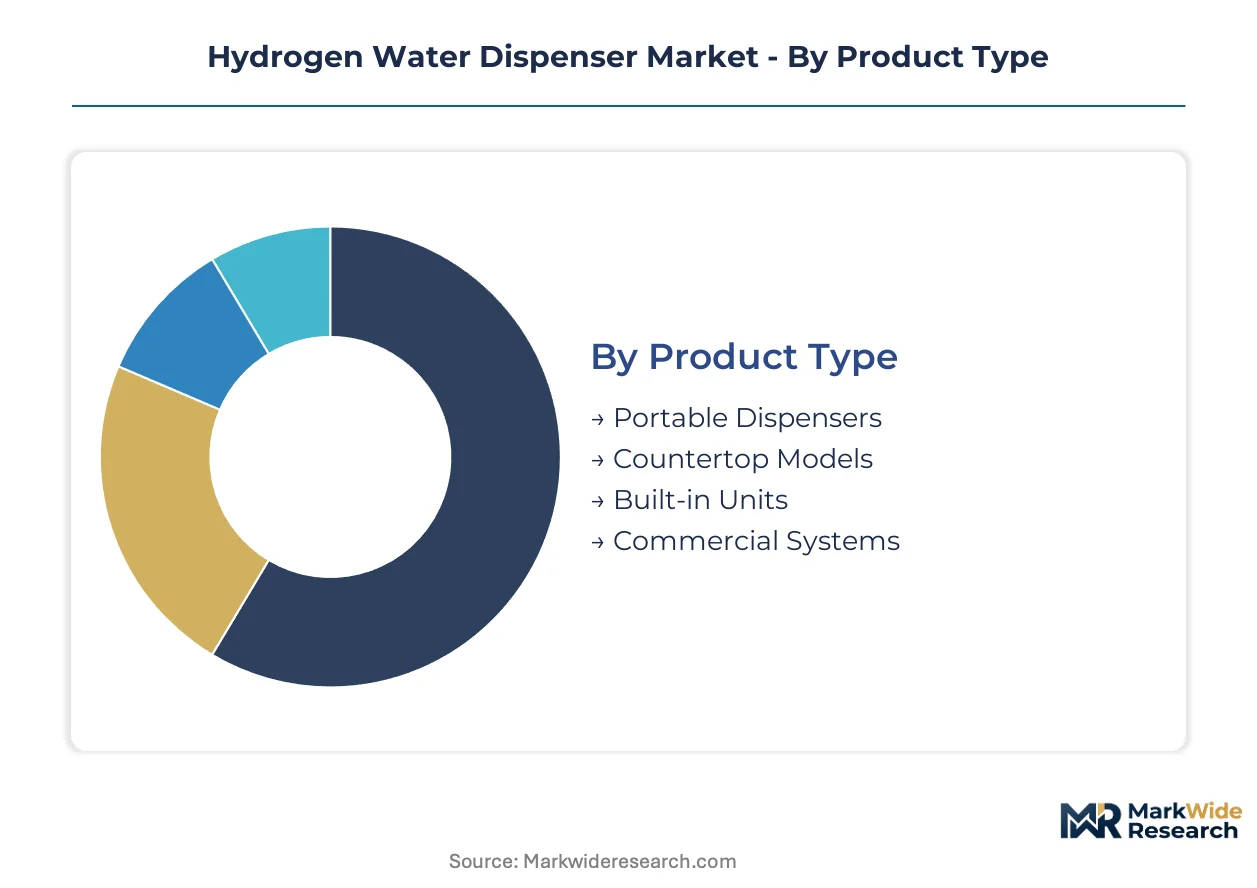
Hydrogen water dispenser segmentation reveals divergent margin profiles across product formats and technology architectures. Channel economics vary sharply between subscription-enabled direct sales and transactional wholesale routes.
Product Type:
Portable dispensers concentrate manufacturing investment as electrolysis membrane miniaturization enables gym and corporate wellness deployments.
- Portable Dispensers:Compact units leverage solid polymer electrolyte stacks to eliminate reservoir sloshing. Demand clusters in South Korean fitness chains and Chinese corporate wellness programs where mobile hydration stations command premium placement fees.
- Countertop Models:Stationary household units maintain the largest installed base across East Asian markets. Beijing, Shanghai, and Shenzhen households drive replacement cycles as hydrogen concentration labeling standards tighten.
- Built-in Units:Integrated kitchen appliances target high-end residential renovations in Japan's urban condominiums.
- Commercial Systems:High-volume installations serve wellness hospitality chains in Seoul and Tokyo with recurring filter service contracts.
Today's leader: Countertop Models. Tomorrow's challenger: Portable Dispensers.
Technology:
Cost tier stratification separates precious metal-dependent electrolysis from commodity-based magnesium alternatives.
- Electrolysis:Platinum-coated titanium electrodes deliver 0.5-1.6 ppm hydrogen saturation with precise concentration control. Performance leadership sustains pricing power in clinical-adjacent channels where Japan's PMDA framework enforces medical-grade claims substantiation.
- Membrane Separation:Energy-efficient gas diffusion methods gain share in EU commercial installations where operational cost structures face tightening efficiency regulations.
- Magnesium Method:Reaction-based generation caps pricing floors for price-sensitive segments through lower material input costs.
- Chemical Reaction:Legacy architectures persist in disposable cartridge formats for travel and emergency use cases.
Electrolysis commands margin premiums. Membrane Separation offers the steepest expansion trajectory where energy costs dominate total cost of ownership.
End User:
Application-specific durability requirements drive enclosure IP ratings and daily cycle specifications.
- Households:Residential adoption concentrates in China's tier-one cities where preventive health device expenditure outpaces national benchmarks.
- Offices:Corporate wellness budgets in South Korea and Japan fund centralized hydration stations with IoT-enabled usage tracking.
- Restaurants:Premium dining concepts in Tokyo and Seoul differentiate through tableside hydrogen water service.
- Gyms:Fitness center procurement specifications emphasize drop resistance and rapid-cycle dispensing for peak-hour throughput.
Households anchor volume. Gyms deliver the fastest volume growth as membership expansion outpaces residential saturation.
Distribution Channel:
Customer type determines payment infrastructure requirements and service integration depth.
- Online Retail:E-commerce platforms in China leverage mobile payment integration for seamless subscription billing. Auto-triggered filter replacement programs concentrate here.
- Specialty Stores:Physical demonstration requirements sustain importance for first-time buyers evaluating hydrogen concentration claims.
- Wholesale Distributors:India's established RO distribution networks provide channel scaffolding for hydrogen-enabled line extensions.
- Direct Sales:Manufacturer-controlled relationships capture recurring service revenue through connected dispenser fleets.
Online Retail scales fastest. Direct Sales extracts highest lifetime value per installed unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's biomedical engineering workforce anchors East Asian innovation in clinical-grade hydrogen generation systems. German precision manufacturing talent supports EU filtration technology upgrades. South Korean wellness hospitality specialists drive B2B equipment procurement pipelines.
Japan
Tokyo's preventive health device clusters concentrate demand for medical-grade hydrogen concentration claims. PMDA pharmaceutical-adjacent oversight unlocks clinical channel access for premium dispensers. Osaka-Kansai manufacturers lead electrolysis membrane miniaturization for countertop units.
South Korea
Seoul's wellness hospitality chains expand on-property hydrogen water programs with recurring filter service contracts. MFDS medical device frameworks enforce concentration labeling standards for consumer protection. Busan-Ulsan industrial zones supply platinum-coated titanium electrode components.
China
Beijing, Shanghai, and Shenzhen households outpace national health expenditure benchmarks for preventive devices. SAMR GB standards regulate electrical safety and water quality outputs for domestic manufacturers. Guangzhou's Pearl River Delta OEM fabricators dominate cost-adjusted export production volumes.
Germany
Bavaria's water technology engineering base supports REACH-compliant filtration media reformulation. ECHA substance restriction updates force activated carbon block certification against restricted compounds. Baden-Württemberg manufacturers accelerate in-house membrane casting to bypass third-party delays.
India
Maharashtra and Gujarat residential markets leverage established RO distribution networks for hydrogen-enabled line extensions. BIS electrical safety standards apply to emerging dispenser categories. Karnataka's Bengaluru tech corridor pilots IoT-connected subscription billing integration.
Hydrogen Water Dispenser Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance segments. The vendor base stratifies between biomedical heritage anchors, residential water purification incumbents, and OEM scale operators. Three archetypes dominate: clinical-channel premium positioned players, mass-market infrastructure extenders, and export-focused volume manufacturers. Competitive moves concentrate on strategic partnerships for multi-region certification and backward integration into membrane electrode assembly.
Within the clinical-adjacent tier, SOLCO Biomedical occupies a position exemplifying premium positioning through biomedical heritage. KENT RO SYSTEMS LTD anchors the residential infrastructure extension archetype, leveraging established channel control. Guangzhou Olansi Healthcare Co., Ltd represents the OEM scale-driven end, competing primarily on cost-adjusted output volumes for export markets.
| Leading Market Players |
|---|
| SOLCO Biomedical |
| KENT RO SYSTEMS LTD |
| SENZA |
| HOVOGEN |
| Guangzhou Olansi Healthcare Co., Ltd |
| NuLife Sciences Inc. |
| Fujiiryoki India |
| AquaCure |
| Guangzhou TESRAN Purification Equipment Manufacturing Co. Ltd. |
| Others |
Supply & Pricing Matrix
Solid polymer electrolyte stack adoption is compressing portable unit manufacturing costs while simultaneously shifting procurement leverage toward membrane electrode assembly specialists in South Korea and Japan. This technology transition rewards manufacturers with captive electrolyzer production capabilities while squeezing margins for assemblers dependent on spot-market component sourcing.
Pricing Analysis
Subscription-enabled filter replacement programs versus transactional hardware sales splits the market into recurring-revenue and one-time-purchase archetypes. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified clinical-grade units from general wellness appliances and magnesium-reaction economy models. Pricing pressure stems from platinum-coated titanium electrode cost volatility pressuring mid-tier electrolysis margins. Corporate wellness procurement teams exhibit lowest price sensitivity due to bundled wellness program budgets, while Indian residential buyers through RO distribution channels remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Busan, Guangzhou, and Osaka anchor hub-and-spoke fulfillment patterns serving East Asian wellness hospitality chains and tier-one Chinese e-commerce platforms. Manufacturing concentrates in China's Pearl River Delta, South Korea's Busan-Ulsan industrial corridor, and Japan's Osaka-Kansai precision engineering clusters. Raw material dependencies center on platinum-group metals for electrodes, proton exchange membranes, and activated carbon filtration media. Single-source vulnerability for platinum-coated titanium components from South Korean suppliers creates concentration risk. Distribution runs through manufacturer-direct channels for subscription-enabled units and wholesale RO distributor networks for Indian residential penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between China's tier-one cities where mobile payment infrastructure enables seamless subscription billing and India's price-sensitive residential markets where established RO distribution networks lower customer acquisition costs.
For Market Incumbents: Anchor clinical-channel positioning through PMDA medical-grade certification investments that magnesium-reaction substitutes cannot replicate. Defend against portable specialists by backward integration into membrane electrode assembly production in Osaka-Kansai manufacturing zones. Consolidate countertop share through IoT-enabled filter replacement programs that lock in recurring revenue. For New Entrants and Emerging Players: Launch via India's established RO distribution networks to bypass direct-to-consumer customer acquisition costs in an underpenetrated hydrogen-enabled product category. Target South Korean gym membership expansion with drop-resistant portable units specifying solid polymer electrolyte architectures. Exploit EU Drinking Water Directive filtration upgrade cycles by positioning integrated hydrogen-plus-filtration systems for Bavarian water technology engineering channels. For Investors and Strategic Acquirers: Valuations sit cheapest among OEM scale operators competing primarily on cost-adjusted export volumes rather than clinical-channel premium positioning. Long-term viability over a multi-year horizon rests on subscription revenue attach rates and regulatory certification moats. Watch for inflection signals in China's SAMR enforcement patterns against unsubstantiated health benefit claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Electrode Assembly | Captive electrolyzer production insulates margins from platinum price volatility and South Korean supply concentration. |
| PMDA Medical-Grade Certification Investment | Pharmaceutical-adjacent oversight unlocks clinical channel access and pricing premiums in Tokyo preventive health clusters. |
| IoT-Enabled Subscription Filter Replacement Launch | Auto-triggered consumable shipments through China's mobile payment infrastructure capture recurring revenue and customer lock-in. |
| RO Distribution Network Partnership in India | Leveraging Maharashtra and Gujarat residential water purification infrastructure lowers customer acquisition costs for hydrogen-enabled line extensions. |
| EU REACH-Compliant Filtration Media Reformulation | ECHA substance restriction compliance enables continued German and French market access while consolidating incumbency advantages. |
Research Methodology
Multiple input streams — executive interviews with electrolyzer manufacturers, procurement discussions with wellness hospitality chains, and regulatory filings with Japan's PMDA and China's SAMR — were reconciled against secondary validation from trade customs data, hospital equipment procurement databases, and fitness center capital expenditure disclosures. Primary engagement covered hydrogen water dispenser product managers, biomedical engineering directors, corporate wellness coordinators, and RO distribution channel partners. Secondary sources included SEC filings of diversified water technology conglomerates, ECHA substance restriction updates, and South Korean MFDS medical device registration records. Bottom-up unit shipment estimates and top-down market sizing were triangulated for convergence.
Data-stream reconciliation across electrolysis and magnesium-reaction technology architectures, portable versus countertop product formats, and household versus commercial end-use segments shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, hydrogen generation technology, end-user application, and distribution channel structure. CAGRs were derived from installed base growth rates, replacement cycle analysis, and penetration assumptions in underdeveloped geographies. Industry-specific forecast inputs incorporated platinum-group metal price trajectory assumptions and PMDA certification timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt platinum price spikes or accelerated SAMR enforcement against unsubstantiated antioxidant claims. Forecasts reflect documented assumptions about electrolysis membrane miniaturization adoption curves and wellness hospitality procurement budget growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Chocolate Malt Drink Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Coconut Water Market
Beverages
Plant Based Protein Beverages Market
Beverages
GCC Bottled Water Market
Beverages
Pineapple Juice Market
Beverages
Breakfast Drink Market
Beverages
United States and Australia Coconut Water Market
Beverages
Ready to Drink Margarita Market
Beverages
Root Beer Market
Beverages
Sarsaparilla Market
Beverages
Global Vinegar Market
Beverages
Carbonated Beverages Market
Beverages
North America Energy Drink Market
Beverages
China Soy Beverages Market
Beverages
Yerba Mate Market