
 All-Natural Flavors System Market | 2026-2036
All-Natural Flavors System Market Size, Share, and Industry Trends Forecast 2026-2036
All-Natural Flavors System Market Outlook
Ingredient sourcing and extraction technology investment is reshaping margin distribution across the All-Natural Flavors System Market. Givaudan leverages captive botanical supply chains in Madagascar and Indonesia to secure vanilla and spice extract volumes. Symrise anchors its position through fermentation-derived natural molecules that reduce agricultural yield dependency. Kerry Group competes via integrated taste and nutrition platforms serving European and North American beverage clients.
An all-natural flavors system comprises concentrated aromatic compounds derived solely from plant, animal, or microbial sources through physical, enzymatic, or microbiological processes, with extraction yields typically ranging from 0.1% to 5% of raw botanical weight depending on solvent type and temperature parameters. These systems replace synthetic flavor chemicals in finished goods where ingredient declarations must list recognizable natural sources. Extracts and oleoresins capture the largest share of value pools due to their concentration efficiency and clean-label compatibility in premium beverage applications. Powdered flavors and spray-dried formulations represent the fastest-expanding segment as dry-mix beverage and bakery manufacturers seek shelf-stable alternatives to liquid carriers.
FDA natural flavoring regulations under CFR 21.101.22, EFSA's Novel Food catalog requirements for botanical extracts, and EU Regulation 1334/2008 on flavorings constrain formulation freedom while creating compliance barriers for non-specialized suppliers. These frameworks elevate documentation costs but also consolidate purchasing toward vendors with established regulatory dossiers. Stakeholders must monitor emerging restrictions on solvent residues and allergen cross-contamination thresholds that will determine qualified supplier lists in the next regulatory cycle.
Market Dynamics
Clean-label procurement mandates from beverage multinationals are compressing supplier qualification timelines and forcing extraction technology upgrades across the all-natural flavors value chain.
Growth Catalysts
- EU Regulation 1334/2008 compliance:Harmonized flavoring standards across member states reduce cross-border formulation barriers for certified suppliers serving pan-European beverage clients.
- Fermentation-derived molecule platforms:Bioprocess engineering advances enable microbial production of vanillin and citrus terpenes independent of agricultural harvest volatility.
- Germany:Premium soft drink manufacturers in this market prioritize certified organic extracts, concentrating procurement volume among qualified botanical suppliers.
Market Restraints
- Vanilla bean supply concentration:Madagascar and Indonesia account for the majority of global vanilla orchid cultivation, exposing processors to climate-induced yield fluctuations.
- EFSA Novel Food catalog requirements:Botanical extracts without established consumption history face protracted safety assessment timelines before market authorization.
- Synthetic flavor substitution threat:Cost-sensitive beverage categories in emerging markets retain reformulation flexibility toward artificial alternatives when natural premiums compress margins.
Strategic Opportunities
- Spray-dried flavor expansion:Dry-mix beverage manufacturers seek shelf-stable alternatives to liquid carriers, opening formulation partnerships beyond traditional liquid extract suppliers.
- India:FSSAI enforcement of stricter additive disclosure rules creates first-mover advantage for natural flavor systems in processed food and beverage segments.
- Biotechnology-conventional extraction convergence:Enzymatic pre-treatment of botanical feedstocks improves yield efficiency for oleoresin producers serving premium applications.
Industry Challenges
- Cross-contamination documentation:Allergen threshold compliance under evolving FDA and EFSA guidance requires capital-intensive facility segregation and batch testing protocols.
- Specialized extraction engineering talent:Supercritical CO2 and molecular distillation expertise remains concentrated among legacy European and North American equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Natural Flavors System Market |
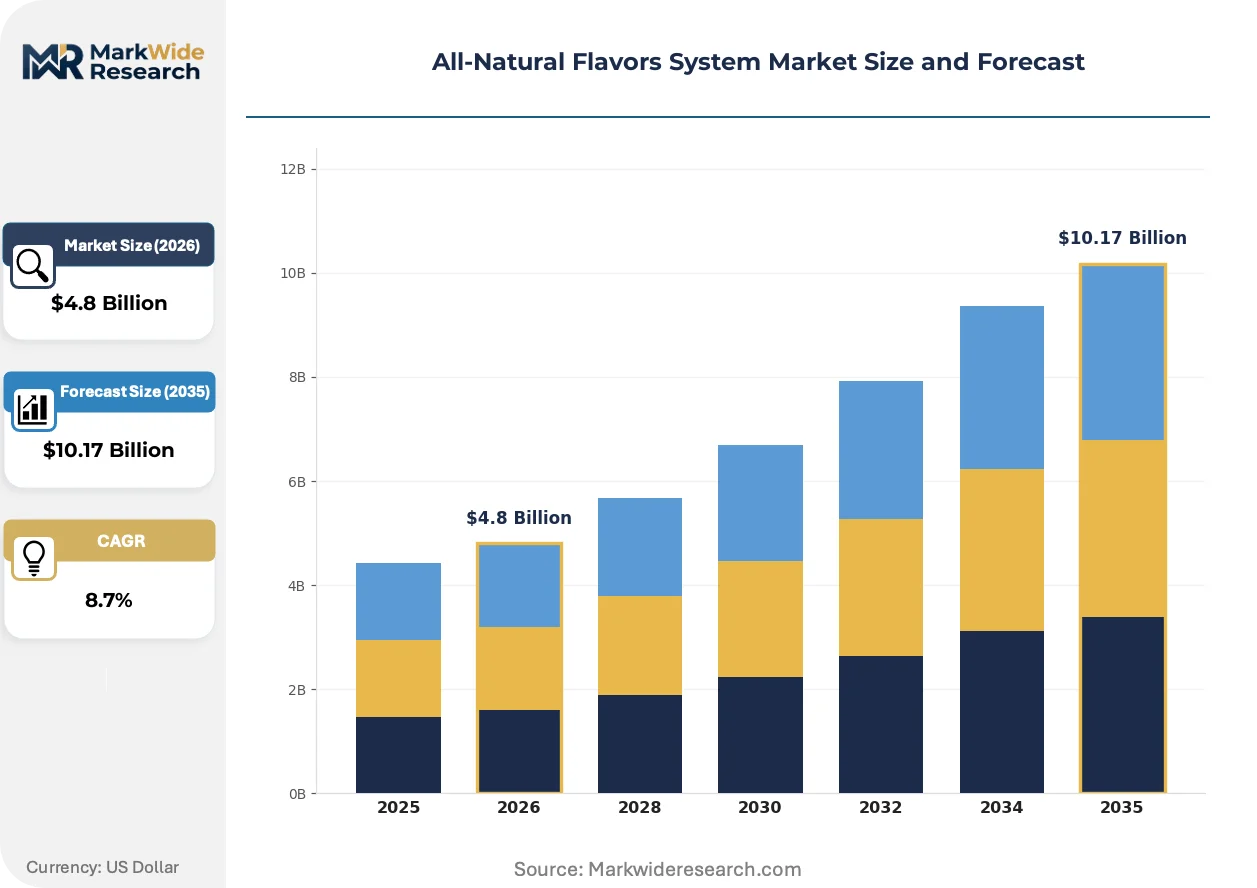
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Essences, Oleoresins, Powdered Flavors Application: Beverages, Bakery, Dairy, Confectionery Formulation Type: Liquid, Dry, Emulsion, Spray-Dried End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Nutraceuticals |
| Companies Covered | Givaudan, Symrise, International Flavors & Fragrances, Firmenich, Sensient Technologies Corporation, Kerry Group, Takasago International Corporation, MANE, Robertet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Natural Flavors System Market Strategic Shifts
Extraction technology advancement and regulatory documentation automation are redefining competitive capability thresholds for natural flavor system suppliers.
Supercritical CO2 extraction is migrating from niche spice oleoresin production toward mainstream citrus and berry flavor recovery. Mid-tier North American beverage ingredient houses adopt this technology to meet clean-label solvent residue specifications. The shift compresses margins for conventional ethanol-extraction operators unable to fund equipment upgrades.
REACH registration requirements for botanical-derived substances are tightening substance characterization obligations for EU-market suppliers. ECHA dossier completeness checks now extend to co-extract composition in complex plant matrices. German and French flavor houses accelerate in-house analytical chemistry investment to maintain qualified supplier status.
Direct-sourcing contracts between beverage manufacturers and botanical originators are displacing traditional multi-tier distributor relationships. Large soft drink and functional beverage producers in the United States and Germany establish captive agronomy programs for vanilla, mint, and citrus raw materials. This channel restructuring concentrates volume among vertically integrated processors while marginalizing independent trading intermediaries.
All-Natural Flavors System Market Segmentation
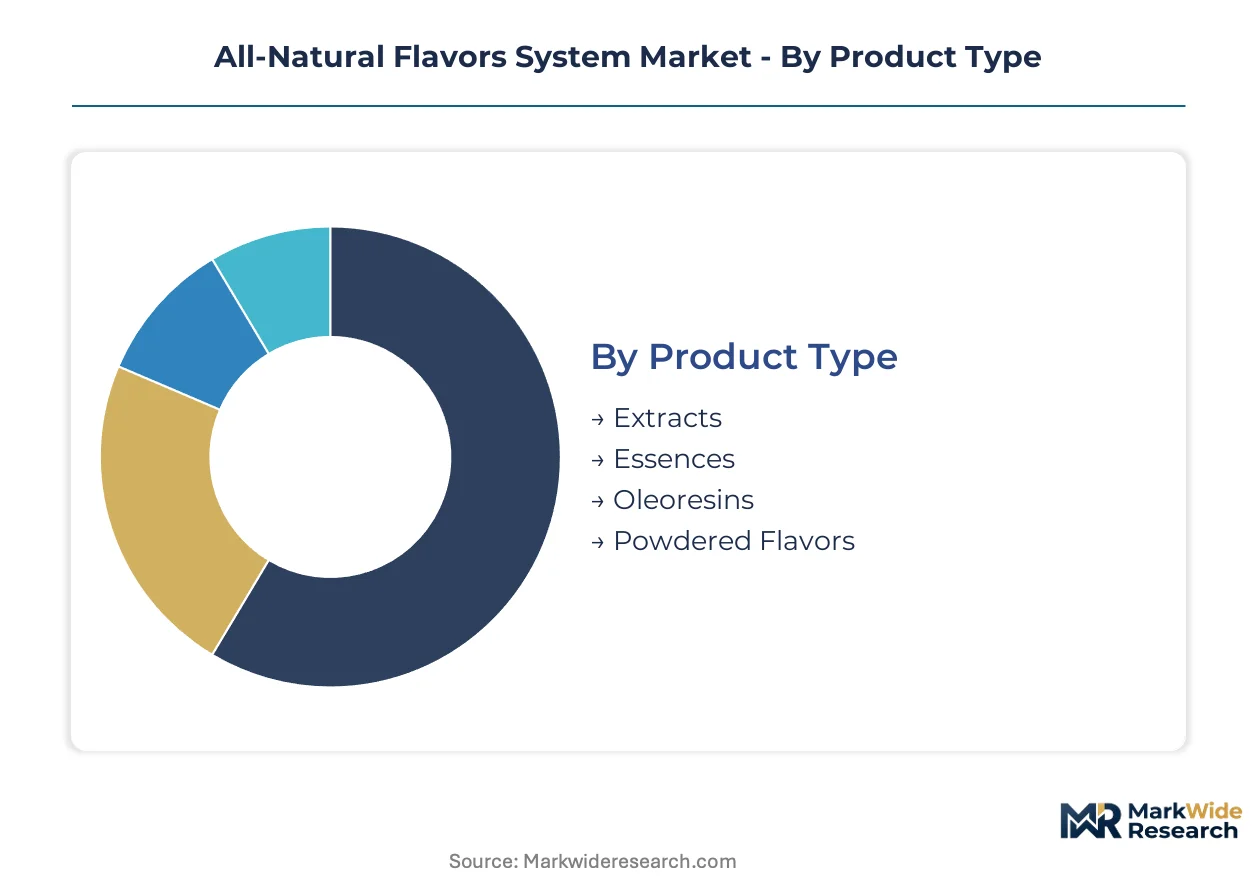
Segmentation in the All-Natural Flavors System Market reveals how extraction technology, formulation physics, and end-use specifications create distinct competitive arenas. Procurement patterns diverge sharply between beverage manufacturers prioritizing liquid clarity and bakery formulators demanding heat-stable dry carriers.
Product Type:
Mature extraction formats dominate revenue pools while emerging concentration technologies reshape margin distribution.
- Extracts:Aqueous or hydroalcoholic solutions containing volatile aromatic compounds recovered through steam distillation or solvent extraction. Beverage manufacturers in Germany specify certified organic extracts for premium soft drinks, with procurement volume concentrating among suppliers with EFSA-compliant botanical dossiers.
- Oleoresins:Viscous concentrates combining essential oils and resinous non-volatiles extracted via supercritical CO2 or hydrocarbon solvents. Spice and citrus oleoresins capture disproportionate value in savory applications where heat stability and standardized potency reduce batch-to-batch variation.
- Essences:Dilute aromatic fractions recovered during fruit juice concentration processes.
- Powdered Flavors:Encapsulated or plated dry formulations enabling shelf-stable distribution to dry-mix manufacturers.
Extracts retain volume leadership; powdered flavors hold the steepest expansion curve.
Application:
Cost tier stratification separates premium positioning from commodity procurement across end-use categories.
- Beverages:Liquid flavor systems integrated into carbonated soft drinks, functional waters, and alcoholic products where solubility and clarity specifications are non-negotiable. Clean-label mandates from multinational beverage producers compress supplier qualification timelines and accelerate extraction technology upgrades.
- Bakery:Heat-stable encapsulated flavors surviving oven temperatures above 180°C without volatile loss. European industrial bakeries specify spray-dried vanilla and fruit systems for consistent aroma release in laminated doughs and fillings.
- Dairy:Fat-compatible flavor emulsions homogenized into yogurt bases and ice cream mixes.
- Confectionery:High-intensity flavor concentrates dosed at low inclusion rates for hard candies and chewing gums.
Beverages command premium pricing tiers; bakery applications are climbing fastest on dry-mix demand.
Formulation Type:
Customer type fragmentation separates multinational beverage houses from regional dry-mix specialists.
- Liquid:Aqueous, alcoholic, or oil-based carrier solutions offering immediate dispersibility in batch processing. Large soft drink manufacturers in the United States specify liquid natural flavors for continuous-flow production lines where metering precision determines cost efficiency.
- Spray-Dried:Atomized emulsions flash-dried onto carbohydrate carriers creating free-flowing powders. Dry-mix beverage and instant coffee manufacturers seek these shelf-stable alternatives to liquid carriers, opening formulation partnerships beyond traditional extract suppliers.
- Dry:Plated or extruded solid flavor preparations for dry blend applications.
- Emulsion:Two-phase systems stabilizing hydrophobic flavor oils in aqueous continuous phases.
Liquid formulations retain installed base dominance; spray-dried systems are gaining share fastest in emerging dry-mix segments.
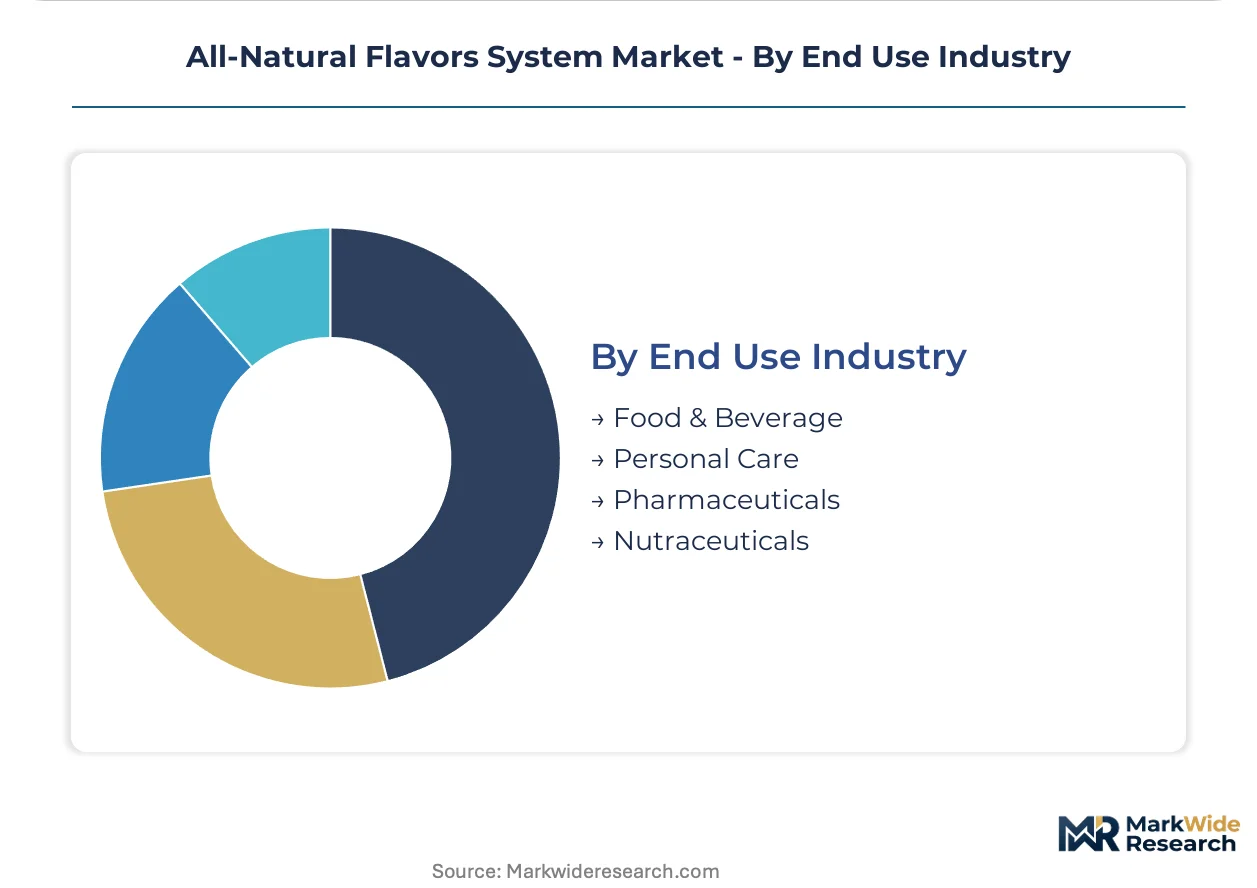
End Use Industry:
Application intensity varies from mass-volume food processing to specification-driven pharmaceutical compliance.
- Food & Beverage:The core demand concentration encompassing all natural flavor procurement for processed foods, beverages, and culinary preparations. FDA natural flavoring regulations under CFR 21.101.22 and EU Regulation 1334/2008 constrain formulation freedom while consolidating purchasing toward vendors with established regulatory dossiers.
- Pharmaceuticals:Flavor masking systems for pediatric and geriatric drug delivery formats. Oral dosage form manufacturers specify natural flavor systems meeting USP-NF monograph requirements for solvent residues and microbial limits.
- Personal Care:Flavor ingredients for lip care and oral hygiene products where incidental ingestion risk triggers food-grade specifications.
- Nutraceuticals:Palatability enhancement for functional ingredients with bitter or astringent off-notes.
Food & Beverage anchors volume concentration; pharmaceuticals follow the steepest compliance-premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys certified organic extracts for premium soft drinks while the United States prioritizes high-volume liquid flavor systems for continuous-flow production. Japan concentrates procurement on fermentation-derived molecules to reduce agricultural dependency. India and Brazil represent emerging procurement frontiers with divergent regulatory maturity.
United States
Large soft drink manufacturers specify liquid natural flavors for continuous-flow production lines where metering precision determines cost efficiency. FDA regulations under CFR 21.101.22 constrain formulation freedom while consolidating purchasing toward vendors with established regulatory dossiers. The Pacific Northwest hosts extraction technology clusters where mid-tier beverage ingredient houses adopt supercritical CO2 systems to meet clean-label solvent residue specifications.
Germany
Premium soft drink manufacturers prioritize certified organic extracts, concentrating procurement volume among qualified botanical suppliers. EU Regulation 1334/2008 harmonizes flavoring standards across member states, reducing cross-border formulation barriers for certified suppliers. The Bavaria region anchors formulation partnerships between industrial bakeries and spray-dried flavor specialists serving laminated dough applications.
Japan
Fermentation-derived molecule platforms enable microbial production of vanillin and citrus terpenes independent of agricultural harvest volatility. METI guidance on bioprocess engineering investment accelerates domestic capacity expansion for natural flavor precursors. The Kansai region clusters enzymatic pre-treatment facilities improving yield efficiency for oleoresin producers.
India
FSSAI enforcement of stricter additive disclosure rules creates first-mover advantage for natural flavor systems in processed food and beverage segments. Domestic beverage manufacturers accelerate procurement of clean-label flavor systems as export compliance requirements tighten. The Maharashtra industrial corridor concentrates dry-mix beverage manufacturing driving demand for shelf-stable powdered flavor alternatives.
Brazil
Cost-sensitive beverage categories retain reformulation flexibility toward artificial alternatives when natural premiums compress margins. ANVISA botanical safety assessment timelines lag European counterparts, delaying market authorization for novel extract suppliers. The São Paulo metropolitan area hosts multinational beverage production facilities where procurement mandates increasingly specify natural flavor declarations for export-bound products.
All-Natural Flavors System Market Competitive Environment
Capability concentration sits with specialized extraction technology operators; scale advantage sits with integrated taste and nutrition platforms. The vendor base organizes around three tiers: captive botanical supply chain operators, fermentation-derived molecule specialists, and integrated taste-nutrition platforms. Dominant competitive moves include direct-sourcing contract establishment with botanical originators and supercritical CO2 extraction technology licensing.
Within the integrated platform tier, Kerry Group and Givaudan exemplify archetypes combining regulatory dossier depth with beverage client relationships. Symrise occupies a position representing fermentation-derived natural molecule production reducing agricultural yield dependency. Among specialized extraction operators, Robertet Group anchors the botanical-originator direct-sourcing model. These three entities collectively illustrate the capability-scale spectrum shaping supplier qualification outcomes for multinational beverage procurement teams.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| International Flavors & Fragrances |
| Firmenich |
| Sensient Technologies Corporation |
| Kerry Group |
| Takasago International Corporation |
| MANE |
| Robertet Group |
| Others |
Value Chain & Pricing Dynamics
The Antwerp-Rotterdam-Amsterdam chemical corridor moves vanilla oleoresins and citrus terpenes from Madagascar and Indonesia to European flavor houses, with freight cost volatility amplifying price spreads between certified organic extracts and conventional grades. This logistics backbone concentrates procurement power among Rotterdam-based traders who arbitrage agricultural yield fluctuations across the growing season.
Pricing Analysis
Long-term offtake contracts dominate vanilla and spice extract procurement, locking in multi-year supply for beverage multinationals while spot markets handle shortfall coverage during poor harvests. Three-tier pricing structure across premium, standard, and economy levels separates certified organic extracts with full EFSA dossiers from conventional ethanol-extracted grades and solvent-recovered commodity flavors. Pricing pressure stems from fermentation-derived molecule platforms eroding agricultural premium capture for vanillin and citrus terpenes. Cost-sensitive beverage categories in emerging markets exhibit highest price sensitivity, while German premium soft drink manufacturers absorb organic certification premiums with minimal volume elasticity.
Supply Chain Analysis
Madagascar, Indonesia, and Uganda concentrate global vanilla orchid cultivation, with agricultural yield dependency creating structural vulnerability to cyclone damage and fungal blight outbreaks. Supercritical CO2 extraction equipment, organic certification infrastructure, and analytical chemistry capability constitute critical input dependencies for qualified suppliers. Single-source vulnerability runs through Madagascar's vanilla belt, where climate-induced harvest failures trigger cascading price spikes across downstream formulations. Distribution runs through direct-sourcing contracts between beverage manufacturers and botanical originators, displacing traditional multi-tier distributor relationships and concentrating volume among vertically integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory dossier maintenance and extraction technology licensing represent expanding service-attach revenue layers growing faster than base ingredient sales, as beverage manufacturers outsource compliance documentation and yield optimization consulting.
For Market Incumbents: Insulate margin position by deepening captive agronomy programs in Madagascar and Indonesia that secure vanilla and spice extract volumes against climate volatility. Accelerate in-house analytical chemistry investment to maintain qualified supplier status under tightening ECHA dossier requirements for botanical-derived substances. These defensive moves counter fermentation-derived molecule substitution threats from bioprocess engineering specialists. For New Entrants and Emerging Players: Establish a beachhead in India's dry-mix beverage segment where FSSAI enforcement of stricter additive disclosure rules creates first-mover advantage for shelf-stable powdered flavor alternatives. Target Maharashtra industrial corridor manufacturers seeking spray-dried formulations bypassing liquid carrier logistics. A regulatory compliance-first go-to-market angle differentiates against commodity traders lacking EFSA-aligned botanical safety assessments. For Investors and Strategic Acquirers: Fermentation-derived natural molecule specialists with microbial vanillin and citrus terpene platforms offer the strongest long-term viability framing across a five-to-ten year window, as agricultural yield dependency becomes structurally uncompetitive. The signal to watch is METI bioprocess engineering subsidy allocation trends indicating Japanese government prioritization of domestic capacity expansion for natural flavor precursors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Agronomy Program Establishment | Direct vanilla orchid cultivation contracts in Madagascar reduce climate-induced supply volatility for beverage clients. |
| Supercritical CO2 Technology Licensing | Mid-tier North American houses adopt clean-label extraction systems to meet solvent residue specifications under FDA guidance. |
| EFSA-Compliant Botanical Dossier Expansion | German and French flavor houses invest in analytical chemistry to maintain qualified supplier status under REACH registration. |
| Fermentation-Derived Molecule Platform Scale-Up | Microbial vanillin production reduces agricultural yield dependency for citrus terpene and spice extract alternatives. |
| Spray-Dried Formulation Partnership Development | Dry-mix beverage manufacturers in India seek shelf-stable alternatives to liquid carriers for instant coffee applications. |
Study Parameters
Desk research of FDA flavoring regulation filings, EFSA Novel Food catalog entries, and EU customs trade data preceded structured interviews with extraction technology engineers, beverage procurement directors, botanical supply chain managers, and regulatory affairs specialists at flavor houses. Primary fieldwork across Madagascar, Indonesia, Germany, and the United States validated secondary estimates of vanilla bean harvest volumes and supercritical CO2 equipment deployment rates. Bottom-up volume aggregation across product type and application segments was cross-checked against top-down market sizing from trade association disclosures.
Assumptions around EFSA botanical safety assessment timelines, fermentation-derived molecule cost curves, and clean-label procurement mandate adoption rates were held fixed across baseline scenarios while agricultural yield volatility and regulatory enforcement intensity were varied in sensitivity testing. Segmentation modeling incorporated extraction technology type, formulation physics, end-use application intensity, and regional regulatory maturity. CAGRs were derived from fitted growth curves applied to normalized base-year estimates, with cross-validation against historical volume trajectories in comparable ingredient markets.
Stress conditions across vanilla bean harvest failure frequency, supercritical CO2 equipment lead times, and EFSA Novel Food authorization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about biotechnology-conventional extraction convergence rates and beverage manufacturer direct-sourcing adoption curves. Cross-checking against FAO agricultural production statistics and Cefic chemical industry output benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Carotenoids Pigment Market