
 Powdered Beverages Market | 2026-2036
Powdered Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Powdered Beverages Market Analysis
Fitness enthusiasts and busy professionals is recalibrating demand toward protein powders and meal replacements with minimal preparation friction. Nestlé leverages its R&D intensity to anchor shelf-stable formulations across multiple functional categories. PepsiCo competes through channel control, sustaining broad retail penetration in supermarkets and online retail. Mondelez International specializes in flavor-forward instant coffee variants that occupy premium positioning in specialty stores.
Powdered beverages are dry, shelf-stable drink preparations manufactured through spray-drying, freeze-drying, or roller-drying of liquid concentrates, then blended with functional additives, sweeteners, and flavor compounds for reconstitution with water or milk. Their primary commercial purpose centers on delivering convenience, portability, and extended stability for consumers seeking on-demand hydration, nutrition, or energy without refrigeration dependency. Instant Coffee commands mature volume pools across Europe and Latin America, while Protein Powder captures margin concentration through sports nutrition positioning in North American and Asian markets. Meal Replacement represents the fastest-growing structural segment as busy professionals prioritize complete-nutrition formats with controlled caloric profiles.
FDA food additive regulations and EFSA novel food assessments shape ingredient approval timelines and clean-label migration across the United States and European markets. China's SAMR enforces GB standards for solid beverage safety and labeling, creating compliance thresholds for imported formulations. Stakeholders must monitor evolving sweetener classifications and carbon-footprint disclosure requirements as procurement criteria tighten across retail and foodservice channels.
Market Dynamics
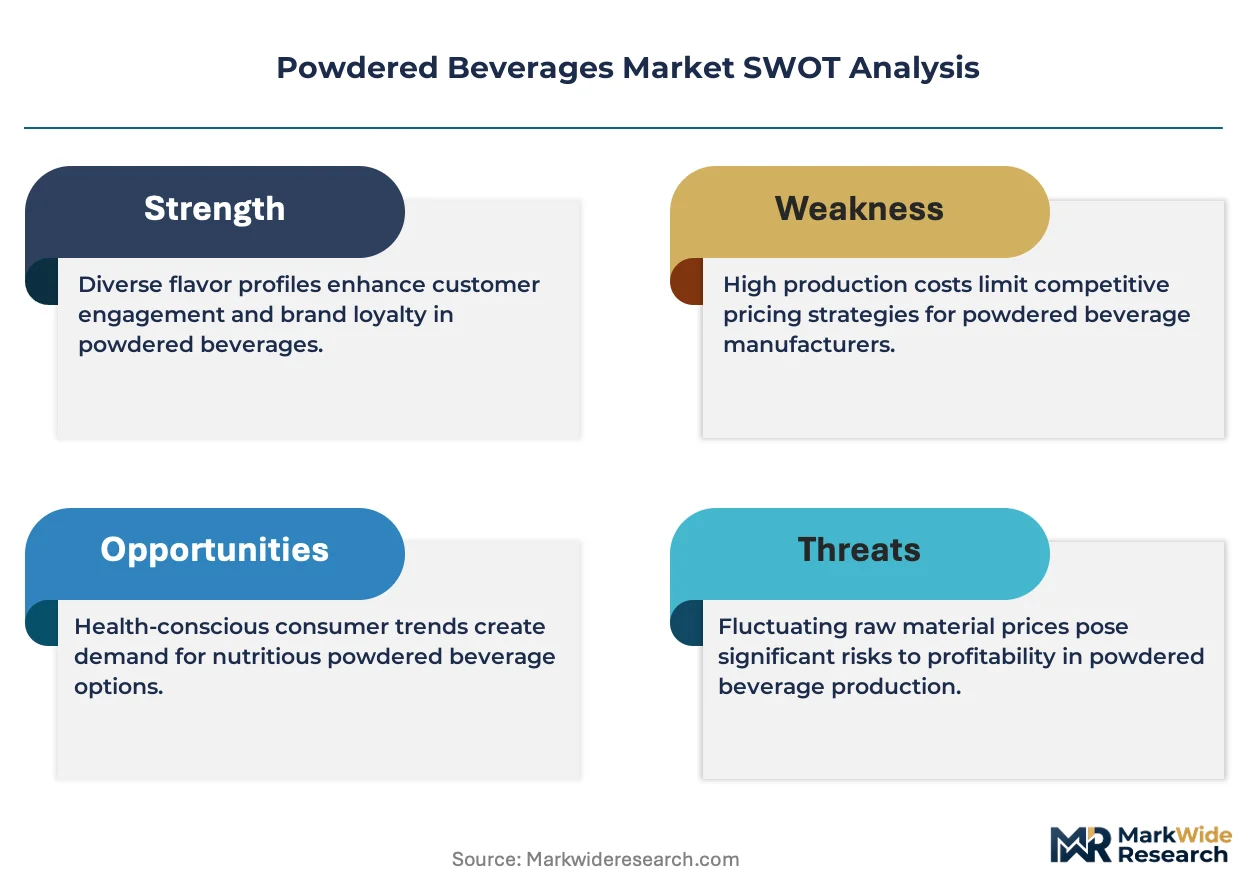
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to reformulate entire additive portfolios, compressing R&D timelines while elevating natural sweetener sourcing costs across all production tiers.
Growth Catalysts
- Fitness-Driven Protein Demand:Sports nutrition positioning in North American and Asian markets pulls whey and plant-based isolates into mainstream retail channels. Gym operators and athletic clubs now stock powdered formats as standard amenity offerings.
- EFSA Novel Food Pathways:Accelerated approval timelines for fermentation-derived proteins and novel botanical extracts enable faster product line extensions. European manufacturers leverage this regulatory clarity to launch functional positioning claims ahead of competitors.
- Meal Replacement Convenience:Busy professionals in urban China and Germany adopt complete-nutrition powders to compress meal preparation time. Workplace pantries and corporate wellness programs drive institutional procurement volumes.
Market Restraints
- Natural Sweetener Cost Volatility:Stevia and monk fruit extract prices fluctuate with agricultural yields in Southeast Asian growing regions. Formulators face margin compression when substituting for artificial alternatives.
- Spray-Drying Energy Intensity:Thermal processing requirements concentrate production in regions with subsidized natural gas or renewable electricity access. Smaller manufacturers lack capital for efficiency retrofits.
- GB Standards Compliance Burden:China's SAMR labeling and safety requirements for solid beverages create documentation overhead for imported formulations. Foreign entrants must establish local testing partnerships.
Strategic Opportunities
- Geriatric Nutrition Gaps:Japan's aging demographic presents underpenetrated demand for protein-fortified and texture-modified powdered beverages. Hospital discharge protocols increasingly prescribe oral nutritional supplements.
- Direct-to-Consumer Subscription Models:Powdered beverage brands bypass traditional retail markups through personalized formulation portals. Recurring revenue structures improve customer lifetime value metrics.
- EU Green Deal Carbon Disclosure:Mandatory Scope 3 emissions reporting creates competitive advantage for manufacturers with verified low-carbon supply chains. Retail procurement criteria now weight environmental metrics alongside price.
Industry Challenges
- Clean-Label Reformulation Expertise:Food scientists capable of stabilizing natural emulsions without synthetic additives command premium compensation. Talent scarcity delays product launches.
- Legacy Equipment Retrofit Costs:Existing spray-drying infrastructure requires substantial modification to handle heat-sensitive bioactive compounds. Capital allocation debates slow technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powdered Beverages Market |
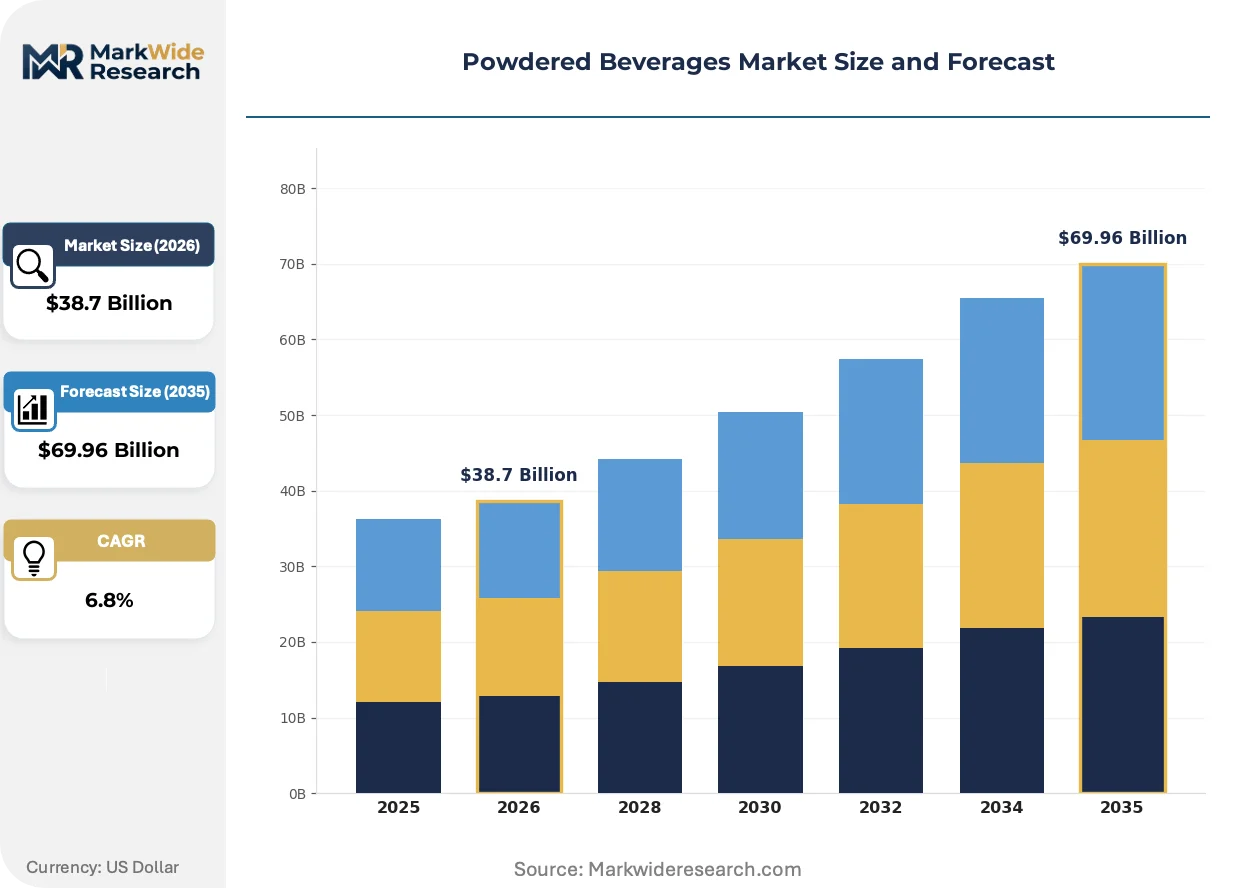
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee, Protein Powder, Sports Drinks, Meal Replacement End User: Fitness Enthusiasts, Athletes, Busy Professionals, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Flavor Profile: Chocolate, Vanilla, Strawberry, Others |
| Companies Covered | Mondelez International, Keurig Dr Pepper, Nestlé, Cargill, Tate & Lyle, PepsiCo, The Kraft Heinz Company, Insta Foods, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powdered Beverages Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how powdered beverages reach end consumers. Three developments dominate competitive differentiation.
Microencapsulation technology protects probiotic and vitamin payloads through gastric transit, extending functional claims to shelf-stable formats. Sports nutrition brands in the United States adopt this capability fastest. The technology is decentralizing production authority away from centralized pharmaceutical-grade facilities toward mid-sized co-manufacturers with flexible batch capabilities.
REACH chemical registration requirements in Europe now capture novel flavor compounds and processing aids previously exempt from full dossier submission. Manufacturers reformulating for clean-label positioning face unexpected compliance costs. Instant coffee and flavored protein segments absorb the heaviest documentation burden, with some suppliers withdrawing marginal SKUs rather than pursuing registration.
Corporate procurement departments now mandate carbon footprint disclosures as standard vendor qualification criteria. Foodservice distributors and retail chains in Germany and the Netherlands lead this behavioral shift. Powdered beverage suppliers compete on verified lifecycle data rather than ingredient specifications alone, with sustainability certifications displacing traditional quality seals in buyer decision hierarchies.
Powdered Beverages Market Segmentation
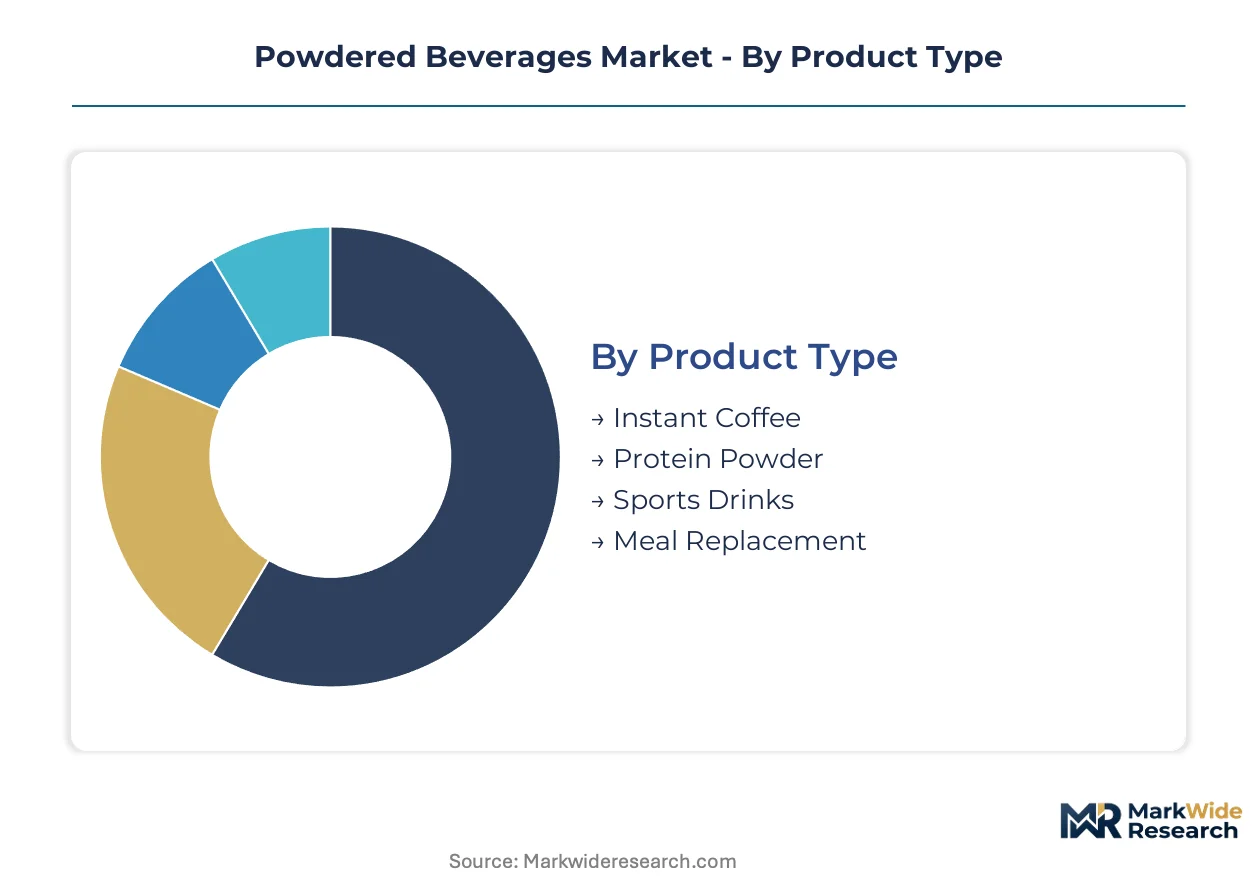
Powdered beverage manufacturers calibrate formulation investments and channel strategies against distinct demand pockets. Segment boundaries determine where spray-drying capacity concentrates and which flavor compounds justify dedicated production lines.
Product Type:
Spray-drying infrastructure clusters around segments with volume scale and thermal stability requirements, locking in supply-side specialization.
- Instant Coffee:Spray-dried and freeze-dried arabica and robusta concentrates dominate European and Latin American retail shelves. Nestlé and JDE Peet's control roasting and extraction infrastructure in Brazil and Vietnam, locking in raw material access. Mature demand in Italy and Germany sustains dedicated production facilities with 24-hour operational cycles.
- Meal Replacement:Complete-nutrition formulations combine protein isolates, micronutrient premixes, and lipid powders for controlled-calorie consumption. Urban professionals in Shanghai and Berlin compress lunch preparation through workplace pantry procurement. This segment climbs the fastest as corporate wellness programs institutionalize powdered nutrition.
- Protein Powder:Whey concentrates and plant-based isolates serve sports nutrition positioning in North American and Asian gym channels.
- Sports Drinks:Electrolyte and carbohydrate powders target hydration recovery in athletic settings with shorter purchase cycles.
Today's leader: Instant Coffee. Tomorrow's challenger: Meal Replacement.
End User:
Customer archetypes dictate formulation complexity and price tier acceptance across retail and institutional channels.
- Busy Professionals:Time-constrained knowledge workers in metropolitan China and Germany prioritize single-serve sachets and subscription replenishment. Corporate procurement departments negotiate bulk contracts for workplace pantry stocking, bypassing traditional retail markups. This group expands most quickly as hybrid work arrangements normalize at-home consumption.
- Fitness Enthusiasts:Gym members and home workout practitioners drive protein powder and pre-workout formulation demand. Athletic clubs in the United States now stock branded pouches as standard amenity offerings, converting casual exercisers into repeat purchasers through convenience placement.
- Athletes:Competitive sports participants require batch-tested formulations with banned-substance certification.
- Health-Conscious Consumers:Clean-label seekers favor natural sweeteners and reduced additive portfolios in specialty retail.
Volume concentrates with Busy Professionals. Margin concentrates with Fitness Enthusiasts.
Distribution Channel:
Channel selection determines packaging format, margin structure, and customer data capture capabilities for powdered beverage brands.
- Online Retail:Direct-to-consumer platforms enable subscription models and personalized formulation portals. Amazon and specialized sports nutrition sites capture repeat purchase data that informs R&D pipeline decisions. This channel gains share fastest as younger demographics bypass traditional grocery routines.
- Supermarkets:Mass retail chains in the United States and Germany anchor instant coffee and mainstream protein powder volumes. PepsiCo and Nestlé leverage existing beverage aisle relationships to secure end-cap placement and promotional calendars.
- Specialty Stores:Premium positioning in organic and sports-focused retail supports higher price points for clean-label variants.
- Direct Sales:Multi-level marketing and institutional contracts serve corporate wellness and healthcare channels with customized bulk formats.
Supermarkets defend volume leadership. Online Retail captures the steepest expansion trajectory.
Flavor Profile:
Flavor compound sourcing and stability testing allocate R&D resources across sensory preference clusters.
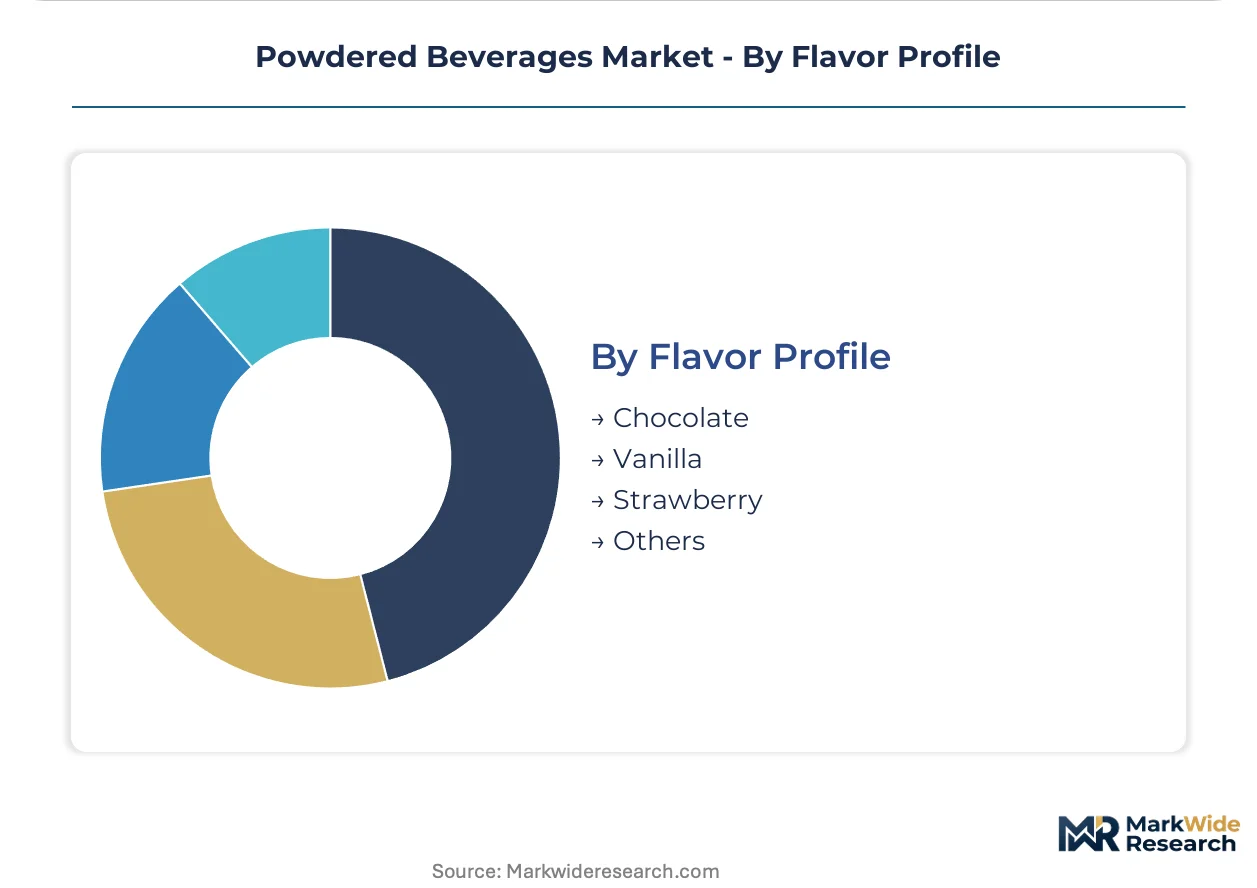
- Chocolate:Cocoa powder and alkalized cacao formulations dominate protein powder and meal replacement applications. Swiss and Belgian chocolate suppliers provide premium positioning credentials for European manufacturers targeting North American export markets.
- Vanilla:Natural and synthetic vanillin variants offer formulation flexibility across instant coffee and sports drink categories. Madagascar and Indonesian vanilla bean harvest volatility drives price hedging strategies for clean-label product lines.
- Strawberry:Fruit powder and natural flavor systems serve younger demographics and pediatric nutrition applications.
- Others:Matcha, turmeric, and botanical extracts capture functional positioning premiums in Asian and wellness-focused markets.
Chocolate commands current formulation spend. Others capture emerging functional positioning premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-drying infrastructure in Vietnam anchors global instant coffee powder output. Nestlé and JDE Peet's operate roasting and extraction facilities in the Central Highlands region. Brazil and Indonesia compete for arabica and robusta sourcing dominance.
United States
Fitness enthusiasts and busy professionals drive protein powder and meal replacement consumption through gym channels and corporate wellness programs. FDA food additive regulations shape clean-label reformulation timelines for natural sweetener adoption. California hosts the densest concentration of sports nutrition brands and co-manufacturing facilities serving North American distribution networks.
Germany
Urban professionals in Berlin and Munich adopt complete-nutrition powders for workplace pantry consumption. EFSA novel food assessments accelerate approval pathways for fermentation-derived proteins and botanical extracts. The Hamburg-Bremen port cluster handles bulk ingredient imports for Central European spray-drying operations.
China
Meal replacement powders gain traction among time-constrained knowledge workers in Shanghai and Shenzhen. SAMR enforces GB standards for solid beverage safety and labeling compliance. The Yangtze River Delta concentrates contract manufacturing capacity for both domestic brands and export-oriented formulations.
Japan
Aging demographics create underpenetrated demand for protein-fortified and texture-modified powdered beverages in hospital discharge protocols. METI oversees functional food claims and novel ingredient assessments. The Kanto region around Tokyo anchors geriatric nutrition product development and specialized distribution partnerships.
Brazil
Instant coffee culture sustains mature volume consumption across retail and foodservice channels. ANVISA regulates food additive safety and labeling standards for domestic and imported formulations. The Minas Gerais coffee belt supplies raw material to São Paulo-based spray-drying facilities serving Latin American export markets.
Powdered Beverages Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers expand across functional categories. The market structure consolidates around multinational conglomerates with integrated ingredient sourcing and global distribution networks. Three archetypes define competitive positioning: diversified nutrition conglomerates, beverage-focused multinationals, and specialized flavor houses. M&A activity and capacity expansion in Southeast Asian spray-drying facilities represent the primary competitive moves reshaping supply-side geography.
Within the diversified nutrition tier, Nestlé and Mondelez International exemplify integrated players spanning instant coffee, meal replacement, and functional beverage categories. PepsiCo occupies a position among beverage-centric multinationals leveraging retail channel control. Tate & Lyle represents specialty ingredient suppliers enabling clean-label reformulation for downstream brand owners.
| Leading Market Players |
|---|
| Mondelez International |
| Keurig Dr Pepper |
| Nestlé |
| Cargill |
| Tate & Lyle |
| PepsiCo |
| The Kraft Heinz Company |
| Insta Foods |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into spray-drying infrastructure anchors pricing power for multinational conglomerates while compressing margins for outsourced brands dependent on Vietnamese and Brazilian toll manufacturers. Nestlé and JDE Peet's captive roasting facilities in Brazil's Minas Gerais belt and Vietnam's Central Highlands insulate them from arabica price spikes that ripple through commodity spot markets.
Pricing Analysis
Input-cost pass-through from natural sweetener and cocoa powder volatility shapes margin structures across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates clean-label organic variants from conventional formulations, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from stevia and monk fruit extract harvest variability in Southeast Asian growing regions. Corporate wellness programs demonstrate lowest price sensitivity while individual retail consumers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Certification gating through FDA food additive approvals and EFSA novel food assessments filters supplier eligibility for North American and European procurement. Spray-drying capacity concentrates in Vietnam, Brazil, and Germany, with raw material dependencies on Colombian arabica, Indonesian robusta, and New Zealand whey isolates. Single-source vulnerability runs through Vietnam's Central Highlands coffee belt where climate disruption threatens harvest consistency. Distribution runs through supermarket chains in Germany and the United States, with direct-to-consumer subscription models capturing fastest channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The powdered beverages market functions as a stable compounder anchored by structural convenience demand from time-constrained professionals and fitness enthusiasts across urban centers.
For Market Incumbents: Lock in spray-drying capacity through long-term offtake agreements with Vietnamese and Brazilian facilities before capacity constraints tighten. Deepen backward integration into natural sweetener cultivation partnerships to hedge agricultural yield volatility threatening margin stability. Prioritize clean-label certification investment as FDA and EFSA reformulation mandates accelerate.
For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models targeting busy professionals in secondary Chinese cities where corporate wellness penetration remains incomplete. Exploit white-space in geriatric nutrition formulations for Japan's aging demographic, where hospital discharge protocols increasingly prescribe oral nutritional supplements. Deploy personalized formulation portals as primary go-to-market mechanism.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized co-manufacturers with flexible batch capabilities because microencapsulation technology is decentralizing production authority away from centralized pharmaceutical-grade facilities. Target specialists with verified low-carbon supply chains as EU Green Deal carbon disclosure mandates reshape procurement criteria. Watch for inflection when Scope 3 emissions reporting becomes mandatory across German and Dutch retail chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA and EFSA additive restrictions force natural sweetener migration across entire portfolios. |
| Spray-Drying Capacity Expansion | Vietnamese and Brazilian facilities anchor global instant coffee powder output for Nestlé and JDE Peet's. |
| Direct-to-Consumer Subscription Launch | Amazon and specialized sports nutrition sites capture repeat purchase data informing R&D pipelines. |
| Carbon Footprint Certification | EU Green Deal disclosure requirements displace traditional quality seals in German buyer hierarchies. |
| Microencapsulation Technology Adoption | Probiotic and vitamin payload protection extends functional claims to shelf-stable formats for sports nutrition brands. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with brand managers, category buyers at retailers, supply planners, and sports nutrition formulators with secondary validation. FDA filings, EFSA novel food registers, SAMR GB standard updates, and Nielsen retail audit data provided cross-reference points. Bottom-up volume modeling and top-down value reconciliation ensured triangulation integrity.
Granularity-level modeling operated at product type, end user archetype, distribution channel, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated gym channel expansion rates, corporate wellness program adoption curves, and clean-label reformulation timelines.
Several conditions sit outside the modeled scope, including abrupt regulatory reclassifications of novel sweeteners and extreme climate events disrupting Southeast Asian agricultural yields. Forecasts reflect documented assumptions about continued urbanization and hybrid work normalization. A model refresh is warranted upon material change in EFSA novel food approval velocity or SAMR enforcement intensity for imported solid beverage formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Whole Grain Drinks Market
Beverages
Premium Water Market
Beverages
Recovery Drinks Market
Beverages
Sparkling Water Market
Beverages
Crystal Boba Market
Beverages
Herb Infused Water Market
Beverages
Relaxation Beverages Market
Beverages
Bottled Water Processing Market
Beverages
United States Smoothie Market
Beverages
Ginger Ale Market
Beverages
Collagen Drinks Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Chill Block Market
Beverages
Beverages Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
United States Recovery Drinks Market