
 United Kingdom Food Acidulants Market | 2026-2036
United Kingdom Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Acidulants Market Analytics
Modular ingredient bundling is decoupling acidulant procurement from traditional full-service distribution contracts. Tate & Lyle leverages its British heritage and starch-derived acidulant portfolio to sustain long-standing relationships with domestic bakery chains. Corbion specializes in fermentation-based lactic acid solutions that differentiate its offering for clean-label dairy applications. ADM controls extensive European supply infrastructure that anchors its competitive position across British beverage accounts.
Food acidulants comprise organic and inorganic compounds—citric acid (C6H8O7), lactic acid (C3H6O3), malic acid (C4H6O5), and phosphoric acid (H3PO4)—that lower pH, enhance flavor profiles, extend shelf stability, and control microbial activity in processed foods. Citric acid dominates volume demand through its ubiquity in carbonated beverages and fruit preparations, while malic acid captures premium positioning in sugar-free confectionery where its milder tartness enables reduced-sodium formulations. Beverage applications command the largest value pool, though dairy acidification represents the fastest-growing segment as British yogurt and fermented milk producers reformulate for probiotic stability.
The Food Standards Agency enforces strict purity specifications under retained EU food additive regulations, while the Health and Safety Executive governs occupational exposure limits during acidulant handling and storage. British Retail Consortium certification requirements further constrain supplier eligibility, pushing smaller acidulant distributors toward third-party audited manufacturing partnerships. Stakeholders must monitor how post-Brexit divergence from EFSA guidance affects maximum permitted levels and labeling obligations for phosphate-based acidulants.
Market Dynamics
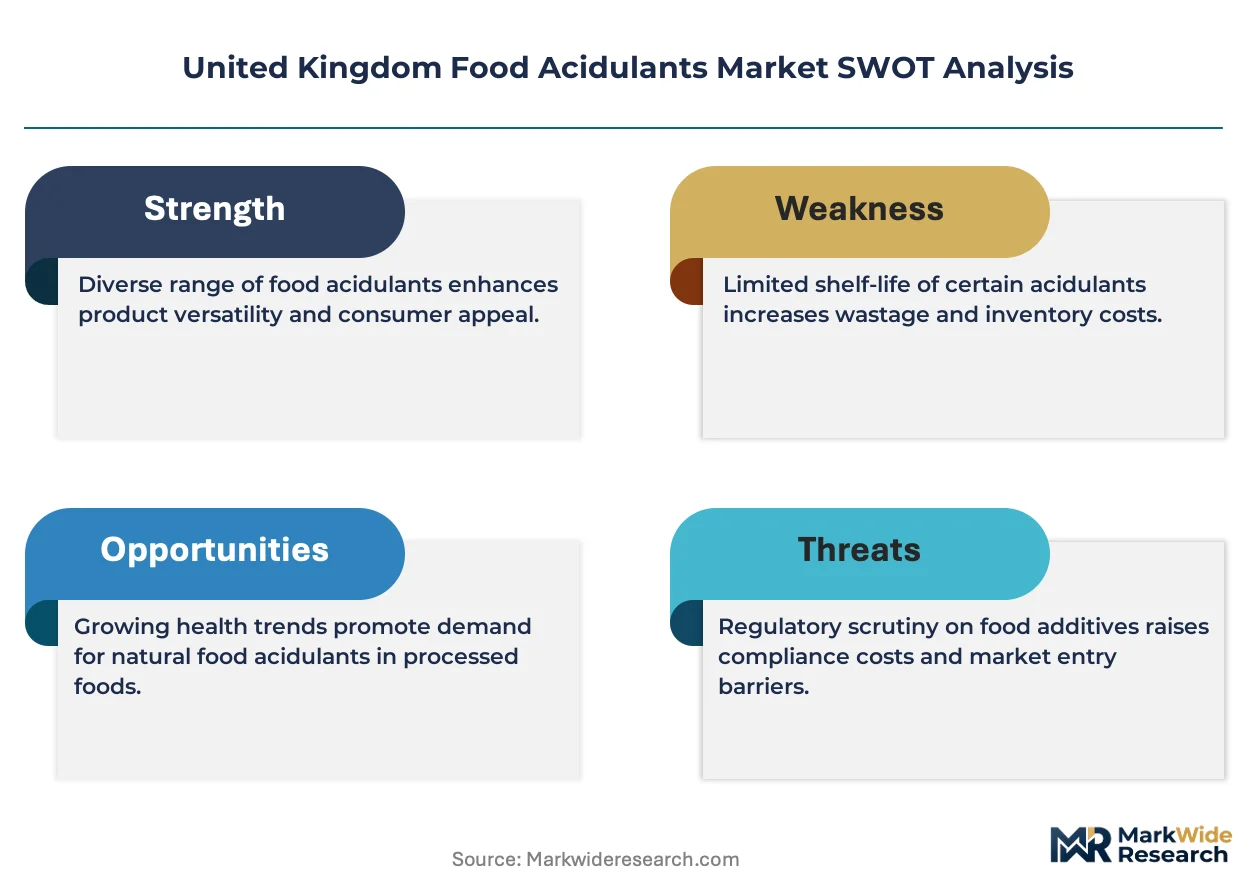
British food manufacturers face mounting pressure to reformulate around clean-label acidulants as the Food Standards Agency tightens additive transparency requirements and retailers demand shorter ingredient declarations.
Growth Catalysts
- Clean-label reformulation mandates:Major British supermarket chains now require phosphate-free acidulant alternatives in private-label beverages, accelerating citric acid and malic acid substitution for phosphoric acid in carbonated drinks.
- Fermentation technology maturation:Advances in microbial fermentation platforms enable cost-competitive production of bio-based lactic acid, supporting probiotic dairy expansion across Yorkshire and the East Midlands processing corridor.
- England's food processing concentration:Dense clustering of beverage and dairy manufacturers around Leeds, Sheffield, and Nottingham creates localized demand density that reduces logistics costs for acidulant suppliers.
Market Restraints
- Corn starch feedstock volatility:Citric acid production depends heavily on maize-derived glucose, exposing British manufacturers to global agricultural commodity price swings and currency fluctuation against the US dollar.
- Single-source fermentation capacity:Specialty organic acid production concentrates among a limited cohort of European fermentation facilities, creating geographic supply risk for UK buyers seeking lactic and malic acids.
- Retained EU additive purity standards:Post-Brexit maintenance of EFSA-aligned maximum permitted levels for phosphoric acid in infant foods limits formulation flexibility for certain acidulant combinations.
Strategic Opportunities
- Scottish and Welsh dairy penetration:Underdeveloped acidulant sourcing infrastructure in Scotland and Wales offers first-mover advantage for suppliers establishing regional blending and distribution nodes.
- Plant-based beverage acidification:Oat, pea, and almond milk formulations require tailored pH control systems that differ from dairy protocols, opening technical service-based revenue streams.
- British Retail Consortium certification leverage:Achieving BRCGS certification creates qualification fast-track for suppliers targeting the six major UK grocery retailers with combined acidulant procurement exceeding mid-market volumes.
Industry Challenges
- Fermentation specialist scarcity:UK universities produce limited graduates with industrial microbiology expertise applicable to acidulant strain optimization and bioprocess engineering.
- Legacy phosphate system retrofit costs:Beverage bottling lines configured for phosphoric acid handling require capital-intensive equipment modification to accommodate organic acid alternatives with different corrosion profiles.
- Dual regulatory tracking burden:Manufacturers must simultaneously monitor Food Standards Agency retained EU regulations and emerging Great Britain-specific divergence, complicating compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Acidulants Market |
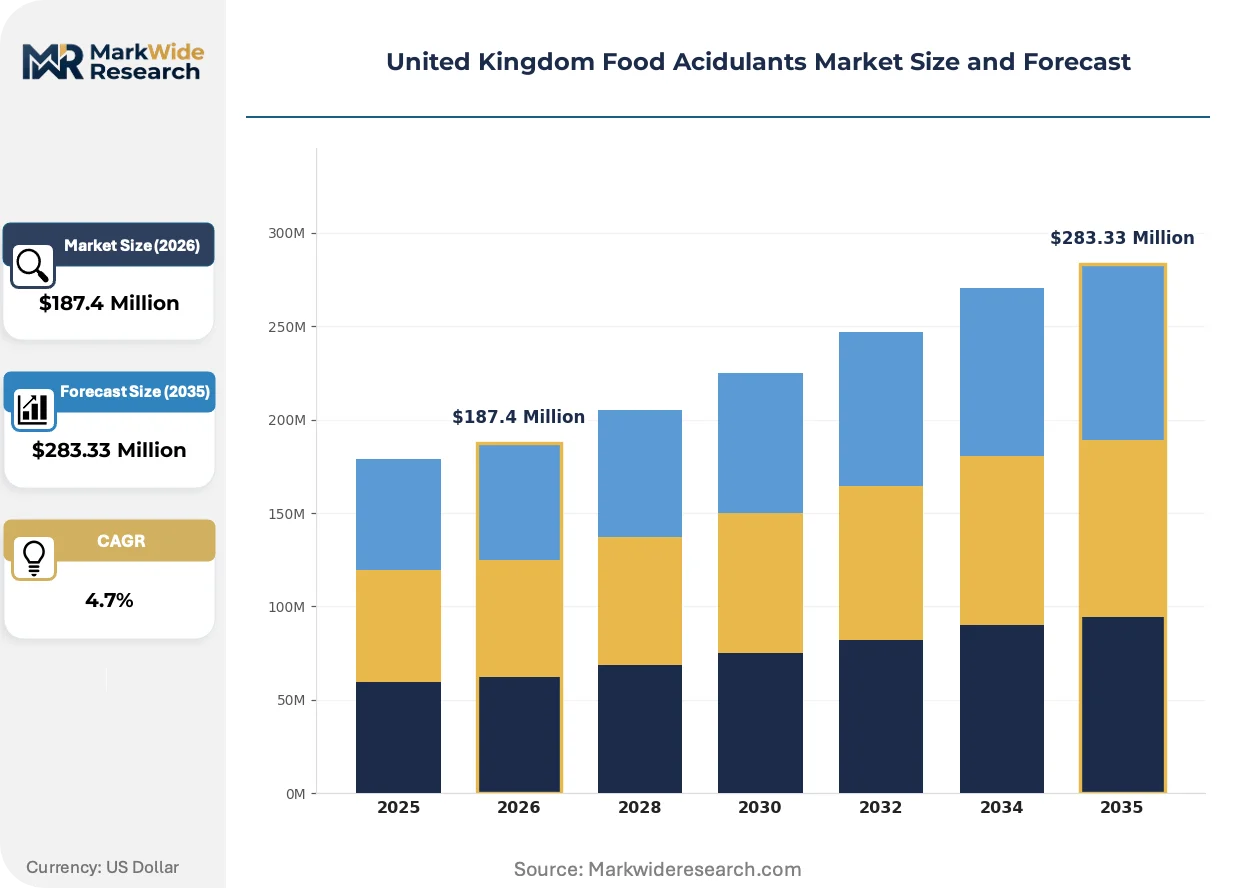
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Phosphoric Acid Application: Dairy Products, Beverages, Bakery, Confectionery End User: Food Manufacturers, Beverage Companies, Restaurants, Retailers Packaging Type: Bulk Containers, Bags, Bottles, Sachets |
| Companies Covered | Cargill, Tate & Lyle, ADM, BASF, DSM, Corbion, Jungbunzlauer Suisse AG, Celanese Corporation, FBC Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Acidulants Market Evolving Landscape
Electrification of production methods and digital traceability systems are compressing acidulant development cycles while reshaping how British manufacturers qualify and monitor suppliers.
Precision fermentation platforms is electrifying organic acid manufacturing by enabling strain-engineered production of malic and citric acids with reduced energy inputs. Mid-sized British dairy processors are piloting these systems at demonstration scale, attracted by carbon footprint reduction claims. The technology is compressing traditional chemical synthesis margins and forcing incumbent suppliers to defend position through backward integration into feedstock agriculture.
The Food Standards Agency's evolving guidance on post-Brexit additive labeling is compelling manufacturers to revalidate acidulant sourcing documentation. Industrial consequence includes mandatory supply chain digitization to demonstrate compliance with retained EU purity specifications. Beverage applications face the most acute adjustment burden, as phosphoric acid content declarations now trigger enhanced consumer scrutiny in sugar-reduced product categories.
Direct supplier relationships are displacing traditional distribution intermediaries as Yorkshire-based food manufacturers seek technical collaboration on clean-label reformulation. Ingredient bundling contracts that combine acidulants with complementary hydrocolloids or preservatives are consolidating procurement decisions around fewer qualified partners. This concentration is most visible among England's bakery and confectionery sectors, where BRCGS-certified suppliers capture disproportionate volume allocation.
United Kingdom Food Acidulants Market Segmentation
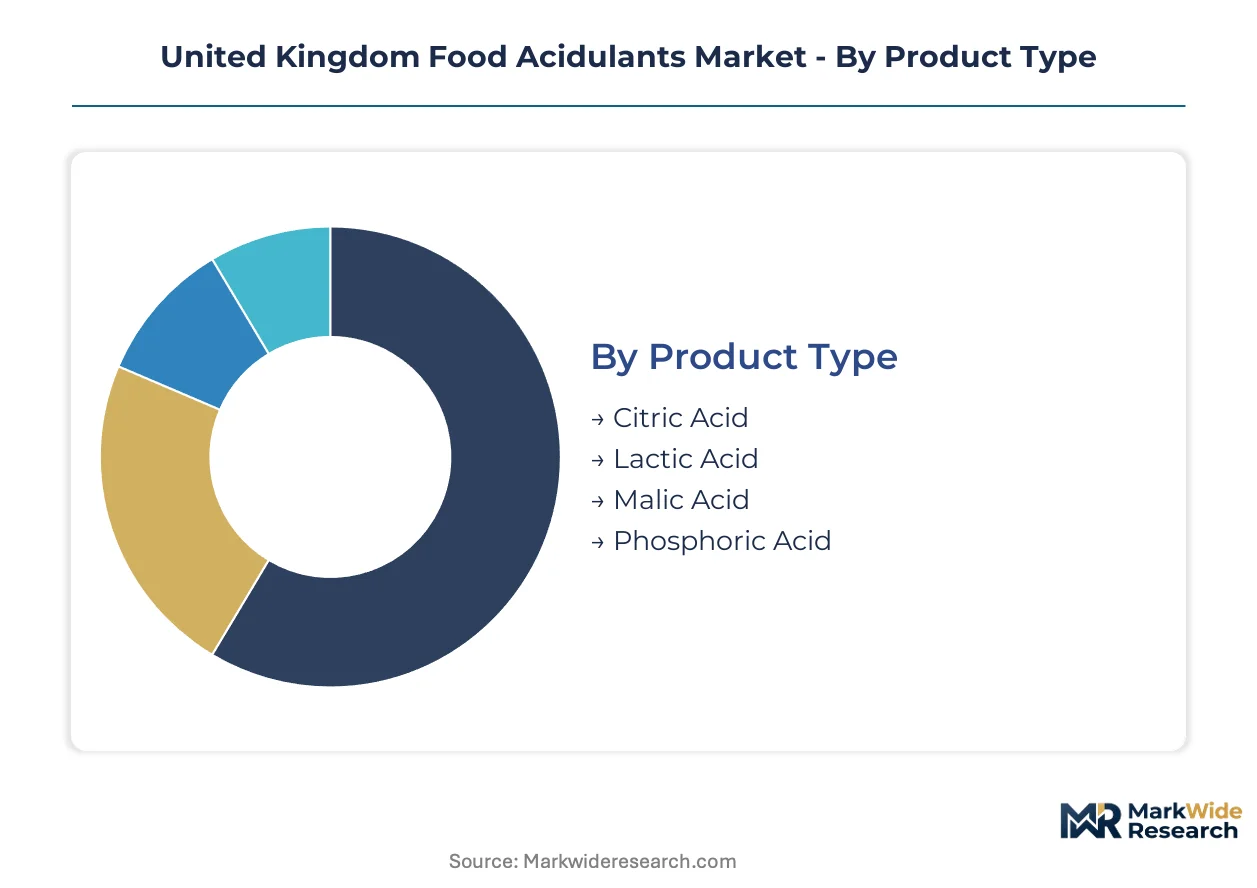
Acidulant procurement patterns in the United Kingdom diverge sharply across product chemistry and end-use specifications. British food manufacturers configure sourcing strategies around formulation flexibility, regulatory compliance thresholds, and supply security rather than commodity pricing alone.
Product Type:
Customization intensity escalates from commodity citric acid through specialty fermentation-derived alternatives, with each tier demanding distinct technical service relationships and purity certification protocols.
- Citric Acid:Anhydrous and monohydrate grades dominate volume procurement through their ubiquity in carbonated beverages and fruit preparations. Yorkshire-based beverage bottlers consume the largest share, though corn starch feedstock volatility exposes buyers to currency fluctuation against the US dollar.
- Lactic Acid:Fermentation-based production platforms enable clean-label positioning for probiotic dairy applications across the East Midlands processing corridor. Corbion's British manufacturing footprint anchors supply security for domestic yogurt reformulation projects.
- Malic Acid:Captures premium positioning in sugar-free confectionery where milder tartness enables reduced-sodium formulations.
- Phosphoric Acid:Faces displacement pressure as major British supermarket chains mandate phosphate-free alternatives in private-label beverages.
Most installed capacity flows through citric acid. Expansion is steepest in lactic acid.
Application:
Margin structures compress from high-volume beverage contracts through fragmented foodservice channels, with technical service intensity inversely tracking transaction scale.
- Beverages:Carbonated drinks and fruit preparations command the largest value pool, with phosphoric acid substitution accelerating citric and malic acid uptake. Clean-label mandates from British Retail Consortium-certified retailers reshape formulation protocols.
- Dairy Products:Fermented milk and yogurt acidification represents the most rapidly expanding segment as processors optimize pH for probiotic stability. Precision fermentation pilots in Leeds and Sheffield reduce energy inputs for lactic acid integration.
- Bakery:Dough conditioning and shelf-life extension drive acidulant blending with complementary preservatives.
- Confectionery:Sugar-free formulations favor malic acid's milder sensory profile.
Beverage applications concentrate procurement volume. Dairy commands the steepest technical service premiums.
End User:
Scale economies fragment across customer tiers, with multinational beverage companies extracting supply security guarantees unavailable to independent food manufacturers.
- Food Manufacturers:Integrated processors across Yorkshire and the East Midlands bundle acidulants with hydrocolloids and preservatives under consolidated procurement contracts. BRCGS certification requirements constrain supplier eligibility to audited partners.
- Beverage Companies:Multinational accounts leverage European supply infrastructure for volume security, while mid-sized British bottlers seek regional blending capabilities.
- Restaurants:Foodservice distributors handle fragmented demand through converted packaging formats.
- Retailers:Private-label specifications drive phosphate-free reformulation mandates across supplier bases.
Food manufacturers anchor installed demand. Beverage companies are gaining share fastest on clean-label conversion.
Packaging Type:
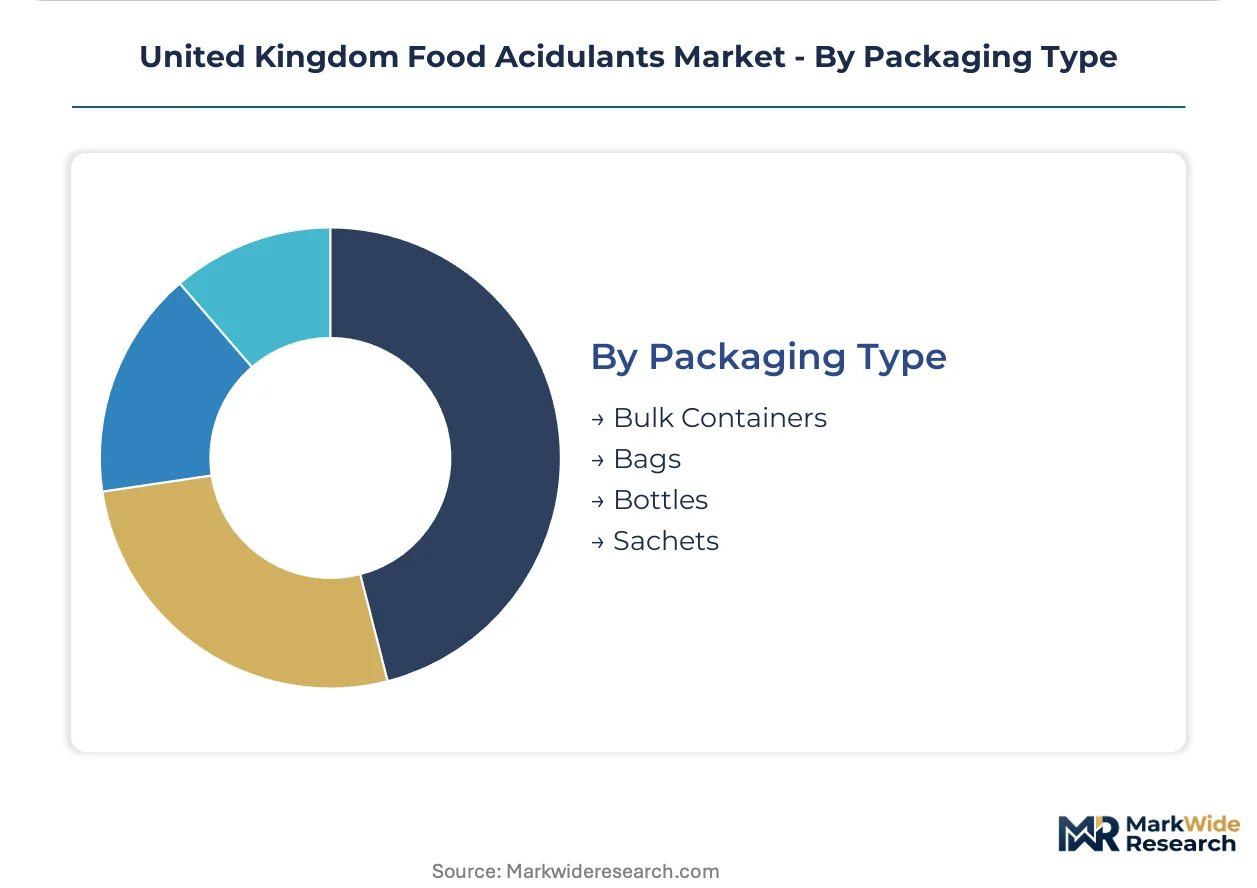
Logistics cost structures stratify by handling automation compatibility, with bulk formats rewarding dense geographic clustering and sachet formats penetrating underdeveloped regional markets.
- Bulk Containers:Tanker and intermediate bulk container deliveries serve high-volume beverage and dairy processors concentrated around Leeds, Sheffield, and Nottingham. Localized demand density reduces per-unit logistics costs for qualified suppliers.
- Bags:Multi-wall paper and polyethylene formats accommodate mid-scale bakery and confectionery manufacturers.
- Bottles:Liquid acidulant concentrates target small-batch food manufacturers.
- Sachets:Single-use portions penetrate Scottish and Welsh markets lacking regional blending infrastructure.
Bulk containers dominate throughput. Sachet formats show the steepest expansion trajectory in peripheral regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom food acidulants industry traces its modern scale to post-war industrial food processing expansion concentrated in England's manufacturing belt. Yorkshire and the East Midlands emerged as the primary processing corridor where beverage and dairy acidification demand first achieved critical mass. Scotland and Wales developed more fragmented sourcing infrastructure, creating persistent regional asymmetries in supplier access.
England
Beverage bottlers and dairy processors around Leeds, Sheffield, and Nottingham generate the densest acidulant consumption cluster in the UK. The Food Standards Agency enforces retained EU additive purity specifications that constrain supplier qualification to audited manufacturing partners. Yorkshire-based manufacturers are piloting precision fermentation platforms for lactic acid production at demonstration scale.
Scotland
Scottish dairy processors and craft beverage producers operate with limited regional acidulant blending infrastructure, forcing reliance on English supply corridors. The country's environmental regulator maintains strict discharge limits on fermentation effluent that affect acidulant manufacturing economics. Edinburgh and Glasgow food manufacturers face higher logistics costs for citric acid and malic acid deliveries.
Wales
Welsh food manufacturing concentrates in South Wales around Cardiff and Newport, with acidulant demand fragmented across small-scale dairy and bakery operations. The Welsh Government's food and drink strategy emphasizes supply chain resilience without dedicated acidulant production investment. First-mover suppliers establishing regional distribution nodes capture underserved procurement volume.
Northern Ireland
Cross-border regulatory alignment with the Republic of Ireland complicates acidulant sourcing for Belfast-area food processors navigating dual compliance frameworks. The region's dairy sector expansion drives lactic acid demand for yogurt and fermented milk applications. Limited local storage capacity forces just-in-time delivery arrangements with mainland British suppliers.
United Kingdom Food Acidulants Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with backward integration into fermentation feedstocks and starch processing. Market concentration remains moderate, with four to six suppliers capturing the majority of volume contracts while specialist fermentation houses occupy premium niches. Two archetypes dominate: integrated agricultural processors controlling glucose supply chains, and biotechnology-focused acidulant specialists leveraging proprietary strain platforms. Capacity expansion and clean-label portfolio diversification represent the primary competitive vectors as phosphate displacement accelerates.
Among British-heritage suppliers, Tate & Lyle occupies a position exemplifying the integrated agricultural processor archetype through its starch-derived acidulant capabilities. Corbion represents the biotechnology specialist tier with fermentation-based lactic acid production. ADM anchors the multinational conglomerate segment with European supply infrastructure extending into British beverage accounts. These three entities collectively illustrate the competitive spectrum from domestic manufacturing heritage to continental scale.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| ADM |
| BASF |
| DSM |
| Corbion |
| Jungbunzlauer Suisse AG |
| Celanese Corporation |
| FBC Industries |
| Others |
Value Network & Pricing Analysis
Clean-label reformulation mandates from British Retail Consortium-certified retailers are compressing procurement flexibility, forcing acidulant suppliers to absorb certification costs while defending position through volume-tiered contracting structures that penalize small-batch buyers.
Pricing Analysis
Contract-based long-term offtake with volume-scaled rebates dominates procurement relationships between Yorkshire beverage bottlers and fermentation houses. Price differentiation hinges on BRCGS certification tier and geographic delivery density, with uncertified suppliers facing exclusion from private-label beverage contracts. Cost compression in citric acid is intensifying because corn starch feedstock volatility transfers currency risk to British buyers. Mid-sized dairy processors show highest price sensitivity due to fragmented order sizes, while multinational beverage accounts extract supply security premiums through dedicated capacity arrangements.
Supply Chain Analysis
Freight costs from mainland European fermentation facilities to British ports constitute 8-12% of delivered lactic acid and malic acid prices, with Yorkshire-based processors bearing lower per-unit logistics than Scottish or Welsh buyers lacking regional blending nodes. Supply concentrates in the Netherlands, Germany, and Belgium for fermentation-derived organic acids, while citric acid production draws from Chinese and Brazilian maize-processing corridors. Single-source vulnerability pervades specialty acidulant categories where Corbion and Jungbunzlauer control limited European capacity. Distribution runs through qualified ingredient distributors with BRCGS-certified warehousing, though direct supplier relationships are displacing traditional intermediaries among England's largest food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scotland and Wales present geographic-arbitrage opportunities where underdeveloped acidulant infrastructure forces buyers to absorb cross-border logistics premiums unavailable to Yorkshire-based competitors.
For Market Incumbents: Hedge phosphate displacement risk by accelerating backward integration into fermentation feedstock agriculture and securing dedicated capacity agreements with East Midlands dairy processors reformulating for probiotic stability. Tate & Lyle and ADM should reinforce their Yorkshire distribution nodes against regional blending competition while monitoring precision fermentation pilots that threaten chemical synthesis margins. For New Entrants and Emerging Players: Launch via regional distribution partnerships targeting Scottish dairy processors and Welsh bakery manufacturers currently served through English supply corridors with extended lead times. Plant-based beverage acidification offers the most penetrable white-space segment, with oat and pea milk formulations requiring technical service capabilities that incumbent suppliers have not fully developed. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation technology specialists possessing proprietary strain platforms for malic acid and bio-based lactic acid production. Long-term viability in this market depends on clean-label certification depth and regional logistics infrastructure rather than commodity scale alone. Watch for Food Standards Agency divergence from EFSA guidance on phosphate maximum permitted levels as an inflection indicator for reformulation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Corbion's demonstration pilots in Leeds reduce energy inputs for lactic acid manufacturing. |
| BRCGS Certification Investment | Third-party audited manufacturing partnerships unlock qualification for six major UK grocery retailers. |
| Regional Distribution Node Establishment | Scottish and Welsh infrastructure gaps create first-mover advantage for qualified suppliers. |
| Plant-Based Beverage Technical Service | Tailored pH control systems for oat and pea milk open service-based revenue streams. |
| Backward Integration into Feedstock Agriculture | Starch-derived acidulant producers secure maize supply chains against currency fluctuation. |
Research Methodology
Multiple input streams — procurement director interviews, fermentation technology assessments, and regulatory documentation reviews — were reconciled against customs trade data and Food Standards Agency guidance publications. Primary discussions with acidulant procurement leads at Yorkshire beverage bottlers, East Midlands dairy processors, and BRCGS-certified ingredient distributors were validated through secondary analysis of British Retail Consortium certification databases and retained EU additive purity specifications. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Data-stream reconciliation applied a structured analytical framework across the projection horizon, segmenting by acidulant chemistry, application intensity, end-user scale tier, and packaging automation compatibility. CAGRs were derived from trend extrapolation of clean-label reformulation adoption curves and fermentation technology cost reduction trajectories. Forecast inputs incorporated Food Standards Agency regulatory divergence scenarios and precision fermentation demonstration scale outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated phosphate displacement or post-Brexit regulatory divergence scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Lake Food Colors Market