
 Beverage Premix Market | 2026-2036
Beverage Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Premix Market Analysis
The EU Green Deal is decoupling beverage premix demand from conventional single-use packaging formats across European foodservice channels. Nestlé S.A. anchors its position through backward integration into soluble coffee sourcing in Vietnam and Brazil. Starbucks Corporation leverages its direct-store-delivery infrastructure to control premium instant beverage distribution. PepsiCo Inc. competes aggressively in juice powder segments through expanded manufacturing scale in Mexico and Thailand.
Beverage premix denotes concentrated or powdered formulations requiring only water or milk reconstitution, typically containing spray-dried extracts, flavor compounds, and functional additives at moisture levels below five percent to ensure shelf stability and transport efficiency. Instant Coffee dominates product type revenue due to entrenched consumption rituals in Brazil, Japan, and Italy, while Protein Shakes represent the fastest-expanding category as fitness centers and hotel gyms expand their grab-and-go offerings. Online Retail channels capture disproportionate margin pools through subscription models, though Supermarkets retain volume leadership in emerging markets where tactile product evaluation still drives purchase decisions.
FDA oversight of nutritional labeling and health claims shapes product positioning in the United States, while EFSA novel food assessments govern functional ingredient introductions across European markets. India's FSSAI mandates increasingly scrutinize artificial sweetener thresholds in sugar-free premix formulations. Stakeholders must monitor divergence between organic certification standards and sugar-free formulation requirements as formulation complexity escalates and ingredient sourcing costs fluctuate.
Market Dynamics
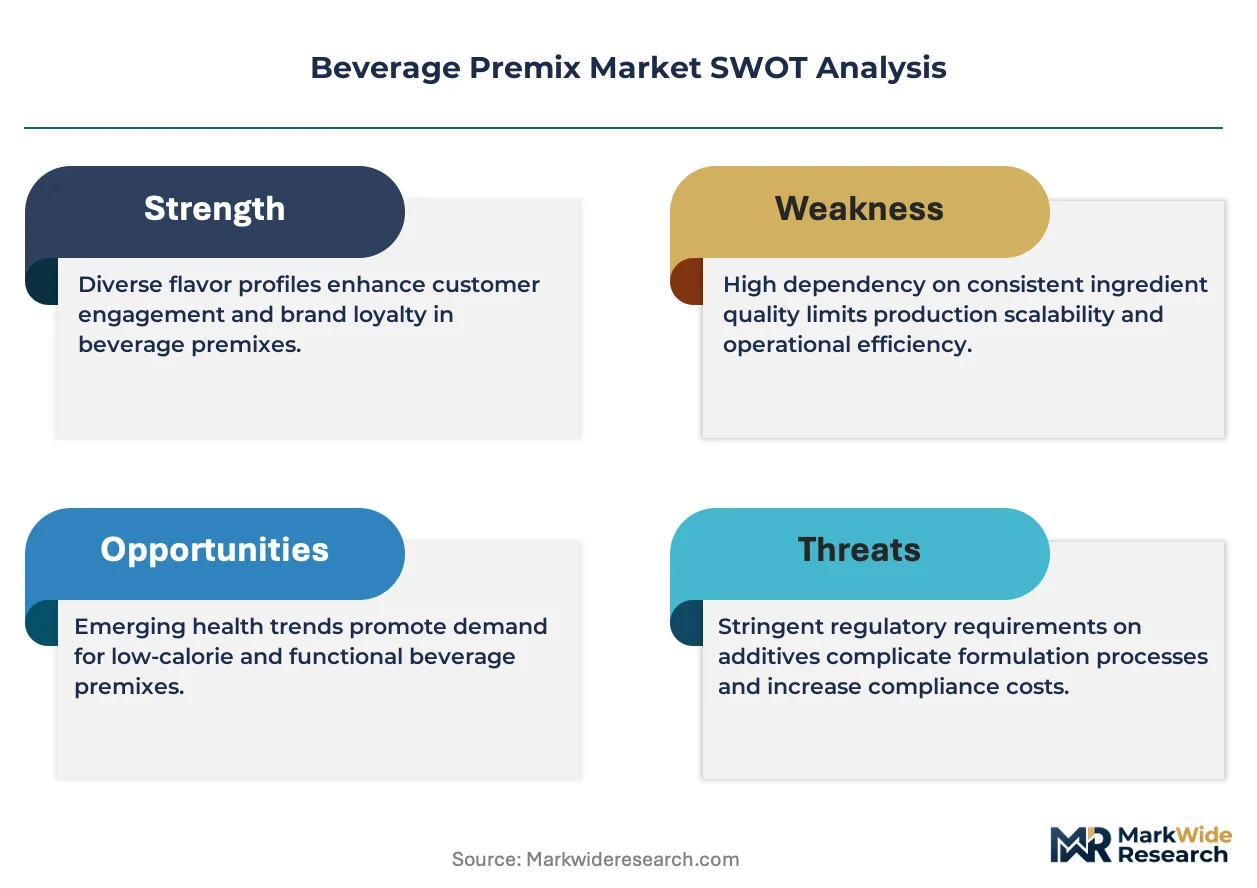
The EU Green Deal's packaging waste directives are forcing beverage premix manufacturers to abandon conventional single-use formats and adopt compostable or recyclable alternatives, fundamentally altering formulation stability requirements and supply chain configurations across European foodservice channels.
Growth Catalysts
- Foodservice labor shortages:Operators in the United States and Germany are deploying premix solutions to reduce preparation time and training requirements for front-of-house staff.
- FSSAI sweetener scrutiny:India's tightening thresholds on artificial sweeteners in sugar-free formulations are accelerating clean-label reformulation investments by domestic manufacturers.
- Spray-drying efficiency gains:Advances in low-temperature spray-drying technology are expanding the viable ingredient base for heat-sensitive functional additives.
Market Restraints
- Robusta coffee price volatility:Instant coffee premix margins compress when Vietnamese and Brazilian arabica-robusta spreads widen unpredictably.
- Single-origin concentration risk:Soluble coffee supply chains depend heavily on Mekong Delta and Minas Gerais sourcing clusters vulnerable to climate disruption.
- Moisture barrier limitations:Biodegradable packaging films still fail to match aluminum laminate shelf-life performance for tropical distribution.
Strategic Opportunities
- Hotel gym channel expansion:Protein shake premix vendors can capture incremental volume through direct procurement partnerships with hospitality chains.
- PLI scheme alignment:India's production-linked incentive scheme for food processing offers capital cost offsets for domestic spray-drying capacity.
- Subscription model penetration:Online retail channels in Japan and South Korea demonstrate viable recurring revenue frameworks for functional beverage premixes.
Industry Challenges
- Clean-label formulation expertise:Replacing artificial stabilizers with natural alternatives requires flavor chemists and food scientists in short supply across Southeast Asian manufacturing hubs.
- Dual certification complexity:Simultaneous organic and sugar-free claims demand divergent sourcing protocols that strain procurement coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Premix Market |
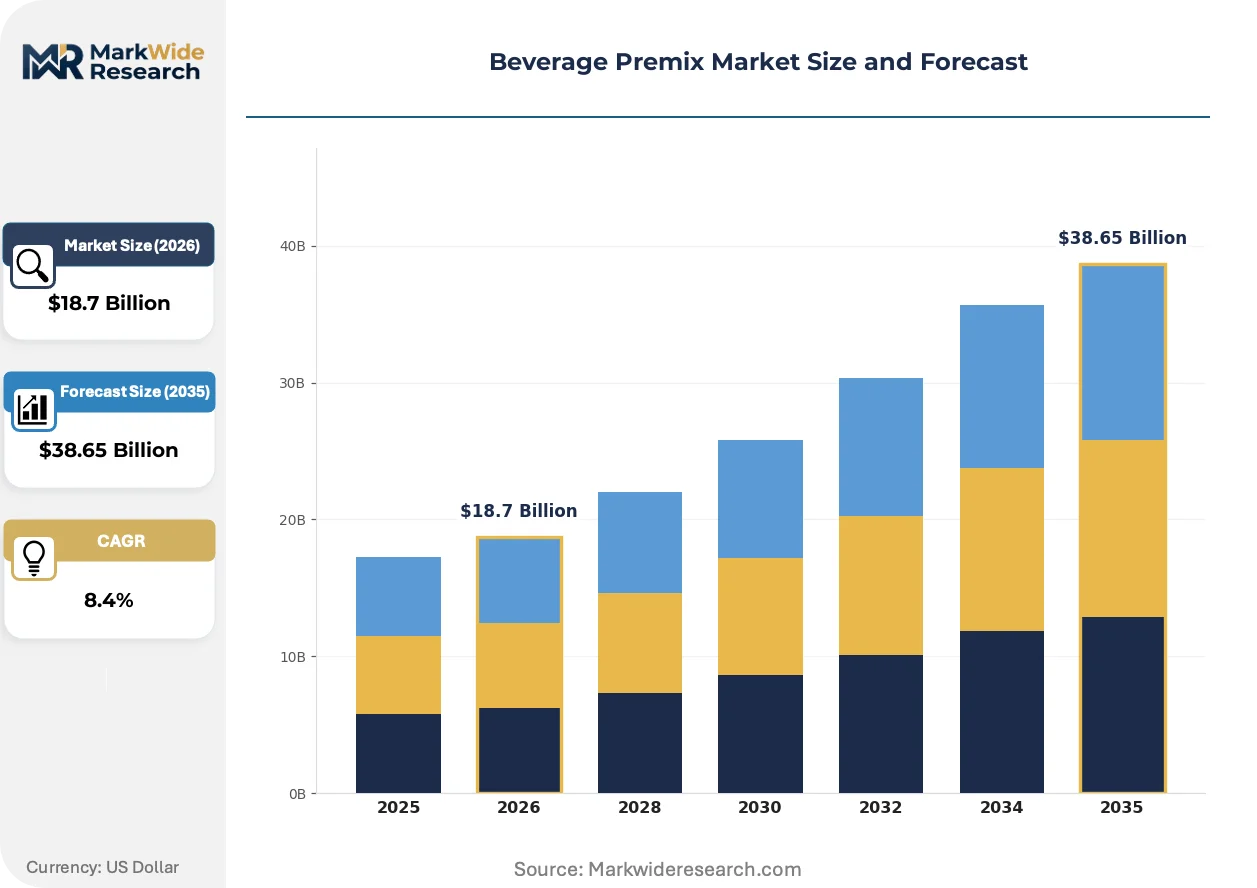
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee, Tea Mixes, Juice Powders, Protein Shakes End User: Retail Consumers, Foodservice, Fitness Centers, Hotels Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Vending Machines Formulation: Organic, Sugar-Free, Halal, Gluten-Free |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Nestlé S.A., Mondelez International, Unilever, Starbucks Corporation, Keurig Dr Pepper Inc., Ito En Ltd., Ajinomoto Co Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Premix Market Emerging Trajectories
Cold-water soluble technology, regulatory packaging mandates, and channel-specific formulation strategies are converging to reshape how beverage premixes reach end consumers.
Encapsulation technology using modified starch matrices is overtaking traditional spray-dried formats for probiotic and vitamin fortification. Functional beverage manufacturers in Germany and Japan are adopting these systems to preserve viability through hot-fill processes. The shift is overtaking conventional fortification methods by enabling shelf-stable claims previously restricted to refrigerated distribution.
REACH restrictions on microplastics are compelling European premix suppliers to eliminate synthetic glitter and decorative particulates from visual differentiation strategies. The ECHA evaluation process is forcing reformulation timelines that compress product development cycles. Premium instant coffee and celebratory beverage categories face the steepest compliance costs as natural mineral alternatives command price premiums.
Direct-store-delivery networks are consolidating procurement decisions for foodservice premix categories previously fragmented across multiple distributor tiers. Large coffeehouse and quick-service chains in Brazil and Italy are centralizing specification authority at regional headquarters. This concentration is most visible in urban corridors where real estate costs justify consolidated inventory management systems.
Beverage Premix Market Segmentation
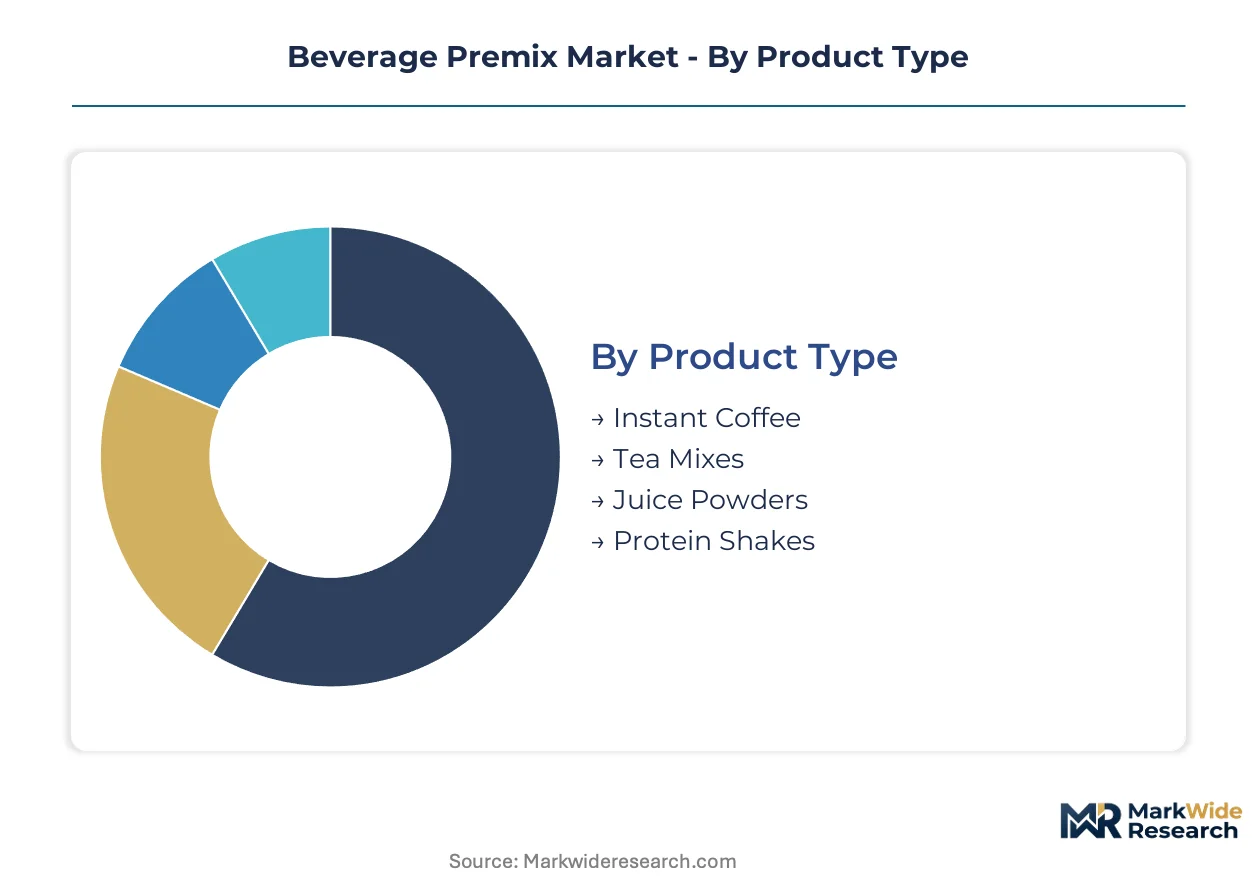
Beverage premix segmentation reveals divergent margin architectures across consumption contexts. Product type stratification reflects entrenched ritual behaviors versus emerging functional demand. Channel and formulation splits expose where pricing power concentrates versus where volume scales.
Product Type:
Buyers differentiate by preparation ritual depth versus functional outcome urgency.
- Instant Coffee:Spray-dried soluble extracts formulated at sub-five-percent moisture for shelf stability. Demand concentrates in Brazil, Japan, and Italy where entrenched consumption rituals sustain premium positioning despite commodity input volatility.
- Protein Shakes:Whey or plant-based concentrates fortified with amino acid profiles targeting post-workout recovery windows. Fitness centers and hotel gyms in urban China and Germany drive adoption as grab-and-go formats displace fresh-blended alternatives.
- Tea Mixes:Black, green, and herbal extracts standardized for hot or cold reconstitution. Japanese and British foodservice channels favor unsweetened variants for customization flexibility.
- Juice Powders:Fruit concentrate solids with vitamin retention through low-temperature dehydration. Mexican and Thai manufacturing clusters supply tropical flavor profiles for emerging market expansion.
Volume sits with Instant Coffee; growth tilts toward Protein Shakes.
End User:
Procurement authority splits between individual discretion and institutional specification.
- Foodservice:Operators in the United States and Germany deploy premix solutions to compress training requirements and standardize output across distributed locations. Labor shortage pressures accelerate specification consolidation at regional headquarters.
- Retail Consumers:Individual purchasers in China and South Korea favor subscription models for functional beverage categories. Tactile evaluation still dominates emerging market supermarket selection.
- Fitness Centers:Gym operators in Japan and Germany source protein shake premixes through direct procurement partnerships. Post-workout consumption rituals create recurring volume commitments.
- Hotels:Hospitality chains in Brazil and Italy centralize in-room and breakfast service specifications. Minibar and breakfast buffet applications demand format flexibility.
Foodservice commands procurement scale; Fitness Centers expand most quickly.
Distribution Channel:
Margin capture diverges between inventory-light digital models and tactile-dependent physical retail.
- Online Retail:Subscription frameworks in Japan and South Korea demonstrate recurring revenue viability for functional premix categories. Customer acquisition costs concentrate in first-order fulfillment economics.
- Supermarkets:Volume leadership persists in India and Brazil where shelf visibility and sampling drive trial conversion. Private label penetration pressures branded margin structures.
- Specialty Stores:Curated assortments in Germany and Italy emphasize organic and single-origin credentials. Staff consultation justifies price premiums over mass retail.
- Vending Machines:Hot and cold dispensing formats dominate Japanese workplace and transit corridors. Machine density creates localized replenishment complexity.
Supermarkets retain volume dominance; Online Retail gains share fastest.
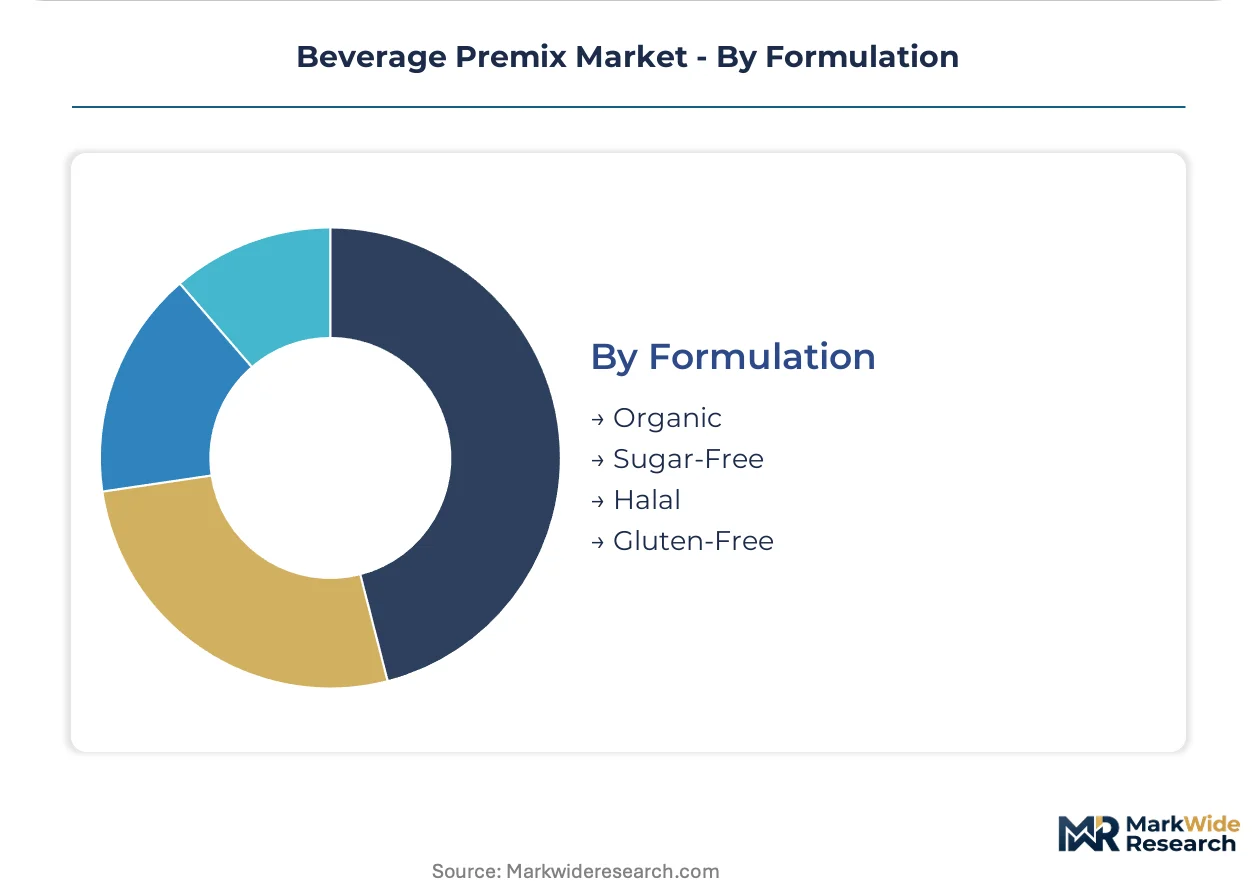
Formulation:
Certification requirements fragment sourcing protocols and constrain supplier flexibility.
- Organic:Certification demands segregated supply chains from agricultural input through spray-drying. European and North American consumers absorb price premiums for pesticide-free claims.
- Sugar-Free:India's FSSAI scrutinizes artificial sweetener thresholds, accelerating clean-label reformulation. Stevia and monk fruit extracts displace aspartame in premium positioning.
- Halal:Religious compliance requires alcohol-free flavor carriers and segregated production lines. Indonesian and Malaysian markets mandate certification for import clearance.
- Gluten-Free:Oat-based and malt-free formulations address celiac and sensitivity segments. European labeling standards enforce strict cross-contamination thresholds.
Organic claims anchor premium tiers; Sugar-Free climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Vietnam and Brazil supply soluble coffee extracts to consumption markets in Japan, Italy, and urban China where convenience rituals drive premix adoption. This geographic split creates divergent regulatory exposure and logistics requirements across the value chain.
United States
Foodservice operators deploy premix solutions to compress training timelines amid persistent labor shortages in quick-service and coffeehouse channels. FDA nutritional labeling requirements shape product positioning for functional and sugar-free formulations. Manufacturing scale concentrates in Midwestern processing corridors serving national distribution networks.
Germany
Fitness centers and hotel gyms in Berlin and Munich expand grab-and-go protein shake offerings to capture post-workout consumption rituals. EFSA novel food assessments govern functional ingredient introductions and probiotic fortification claims. Encapsulation technology specialists in Bavaria pioneer modified starch matrices for heat-sensitive additives.
China
Urban consumers in Shanghai and Beijing favor convenience-oriented drink formats driving protein shake and instant coffee premix expansion. SAMR food safety standards scrutinize imported spray-dried extracts and cross-border e-commerce channels. Yangtze River Delta manufacturing hubs scale domestic spray-drying capacity for regional supply security.
Japan
Vending machine density in Tokyo and Osaka corridors sustains hot and cold premix dispensing formats for workplace and transit consumption. METI standards influence functional beverage labeling and health claim substantiation requirements. Kansai-based suppliers refine low-temperature dehydration systems for vitamin retention in juice powder categories.
India
FSSAI tightening of artificial sweetener thresholds in sugar-free formulations accelerates clean-label reformulation investments by domestic manufacturers. The PLI scheme for food processing offers capital cost offsets for spray-drying capacity expansion in Gujarat and Maharashtra. Supermarket channels in Delhi-NCR and Mumbai retain volume leadership through tactile product evaluation.
Beverage Premix Market Vendor Landscape
The competitive structure tilts toward diversified multinational conglomerates with captive ingredient sourcing and established distribution infrastructure. Tiered specialization separates soluble coffee specialists from functional beverage innovators and private-label manufacturers. Strategic moves concentrate on backward integration into agricultural inputs and direct-store-delivery network consolidation to capture foodservice procurement decisions.
Among diversified beverage conglomerates, Nestlé S.A., PepsiCo Inc., and Starbucks Corporation exemplify distinct competitive archetypes. Nestlé S.A. anchors the soluble coffee segment through upstream control over Vietnamese and Brazilian sourcing clusters. PepsiCo Inc. occupies a scale-driven position in juice powder manufacturing across Mexican and Thai production bases. Starbucks Corporation leverages captive retail infrastructure to control premium instant beverage distribution through direct-store-delivery systems.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Nestlé S.A. |
| Mondelez International |
| Unilever |
| Starbucks Corporation |
| Keurig Dr Pepper Inc. |
| Ito En Ltd. |
| Ajinomoto Co Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between organic and sugar-free formulations splits procurement protocols and cost structures across the beverage premix value chain. Premium tiers absorb segregated supply chain premiums for pesticide-free agricultural inputs, while commodity instant coffee segments compete on Vietnamese and Brazilian arabica-robusta spread arbitrage.
Pricing Analysis
Cost-down pressure on standard-tier instant coffee accelerates because Vietnamese robusta price volatility compresses margins unpredictably. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, spray-drying technology grade, and brand heritage depth. Price differentiation hinges on organic certification and single-origin provenance claims. Foodservice buyers exhibit highest price sensitivity due to volume procurement scale, while fitness center operators accept premiums for protein bioavailability guarantees.
Supply Chain Analysis
Soluble coffee extract supply rests on Vietnamese Mekong Delta and Brazilian Minas Gerais sourcing clusters vulnerable to climate disruption. Spray-dried inputs draw from tropical fruit concentrate corridors in Mexico and Thailand, with modified starch encapsulation matrices increasingly sourced from Bavarian specialty chemical producers. Single-origin concentration risk dominates upstream exposure. Distribution runs through direct-store-delivery networks for foodservice consolidation and subscription logistics platforms for functional beverage categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage premix market is consolidating around backward-integrated multinationals with captive agricultural sourcing, forcing private-label manufacturers and regional spray-drying specialists toward acquisition or niche specialization.
For Market Incumbents: Deepen upstream control over Vietnamese and Brazilian coffee clusters to defend margin position against robusta price volatility. Expand low-temperature spray-drying capacity in India under PLI scheme offsets to capture clean-label reformulation demand. Prioritize encapsulation technology R&D for probiotic fortification viability through hot-fill processes. For New Entrants and Emerging Players: Enter via hotel gym direct procurement partnerships in urban China and Germany where protein shake premix penetration remains fragmented. Target sugar-free formulation segments in India ahead of FSSAI sweetener threshold tightening. Deploy subscription-first go-to-market models in Japan and South Korea where recurring revenue frameworks demonstrate viability. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified beverage conglomerates seeking spray-drying capacity and regional formulation expertise. Long-term viability favors targets with dual organic and halal certification capabilities spanning European and Southeast Asian demand. Monitor EFSA novel food assessment timelines as inflection indicator for functional ingredient premiumization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Nestlé's Vietnamese and Brazilian soluble coffee clusters demonstrate margin defense against commodity volatility. |
| Encapsulation Technology Investment | Modified starch matrix systems enable probiotic viability claims previously restricted to refrigerated distribution. |
| Direct-Store-Delivery Network Consolidation | Starbucks' captive retail infrastructure controls premium instant beverage distribution and specification authority. |
| Clean-Label Reformulation Acceleration | India's FSSAI sweetener scrutiny forces stevia and monk fruit displacement of aspartame in premium positioning. |
| Subscription Model Platform Development | Online retail channels in Japan and South Korea demonstrate recurring revenue frameworks for functional categories. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this beverage premix market assessment. Primary interviews with spray-drying plant managers, foodservice procurement directors, fitness center operators, and flavor compound suppliers combined with FDA, EFSA, and FSSAI regulatory documentation. Secondary sources included customs import records, coffee exchange price data, and food processing industry association reports. Bottom-up capacity modeling and top-down consumption estimation triangulated volume and value outputs.
Segment-level granularity modeled product type splits across instant coffee, protein shakes, tea mixes, and juice powders; end-user categories spanning foodservice, retail consumers, fitness centers, and hotels; and formulation distinctions including organic, sugar-free, halal, and gluten-free certifications. CAGRs derived from trend extrapolation of spray-drying capacity expansion, vending machine density trajectories, and subscription penetration curves. Forecast inputs incorporated EU Green Deal packaging mandate compliance timelines and PLI scheme utilization rates for Indian manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt coffee commodity price spikes or biodegradable packaging film performance failures in tropical distribution. Forecasts reflect documented assumptions on spray-drying technology adoption rates and regulatory enforcement intensity. A small set of named triggers warrants ongoing watch: FSSAI sweetener threshold finalization, REACH microplastic restriction implementation, and Mekong Delta climate disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Plant-Based Energy Drink Market
Beverages
Beverage Multipacks Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Sparkling Soda Market
Beverages
Oat Based Beverages Market
Beverages
Apple Juice Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Ready to Drink Premixes Market
Beverages
Recovery Drinks Market
Beverages
Foaming Creamer Market
Beverages
Extra Virgin Olive Oil Market
Beverages
CBD-Infused Beverages Market
Beverages
Caffeine-Based Drinks Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Hot Beverages Market