
 Radio Modem Market | 2026-2036
Radio Modem Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Modem Market Analysis
Platform licensing revenue is reshaping competitive economics as vendors bundle firmware subscriptions with hardware sales. Motorola Solutions leverages its public safety installed base to extend recurring service contracts across federal and municipal agencies. Digi International anchors its position through edge-computing integration within industrial IoT gateways. FreeWave Technologies specializes in long-range unlicensed spectrum solutions for oilfield and agricultural telemetry.
A radio modem is a wireless transceiver module that modulates digital data onto radio frequency carriers for transmission across unguided media, typically operating in sub-GHz or 2.4 GHz ISM bands with output power ranging from milliwatts to several watts depending on regulatory limits. The device enables serial or IP-based communication between geographically dispersed assets without wired infrastructure, serving critical roles in SCADA backhaul, fleet tracking, and remote sensor networks. Spread Spectrum technology dominates unit shipments owing to its interference resilience and regulatory acceptance across multiple jurisdictions, while LoRa segments are capturing disproportionate growth in low-bandwidth utility metering applications. Point-to-Multipoint architectures concentrate margin pools through hub-and-spoke network management software rather than endpoint hardware alone.
FCC Part 90 rules govern licensed land mobile operations in the United States, mandating emission masks and coordination procedures that shape product certification timelines and geographic deployment rights. ETSI EN 300 220 standards in Europe enforce spectrum efficiency and coexistence protocols, directly influencing transceiver design choices for manufacturers seeking CE marking. The EU Radio Equipment Directive imposes cybersecurity and interoperability requirements that vendors must address before market access. Stakeholders should monitor spectrum reallocation proceedings and emerging cyber certification mandates as these will determine which product architectures retain competitive viability.
Market Dynamics
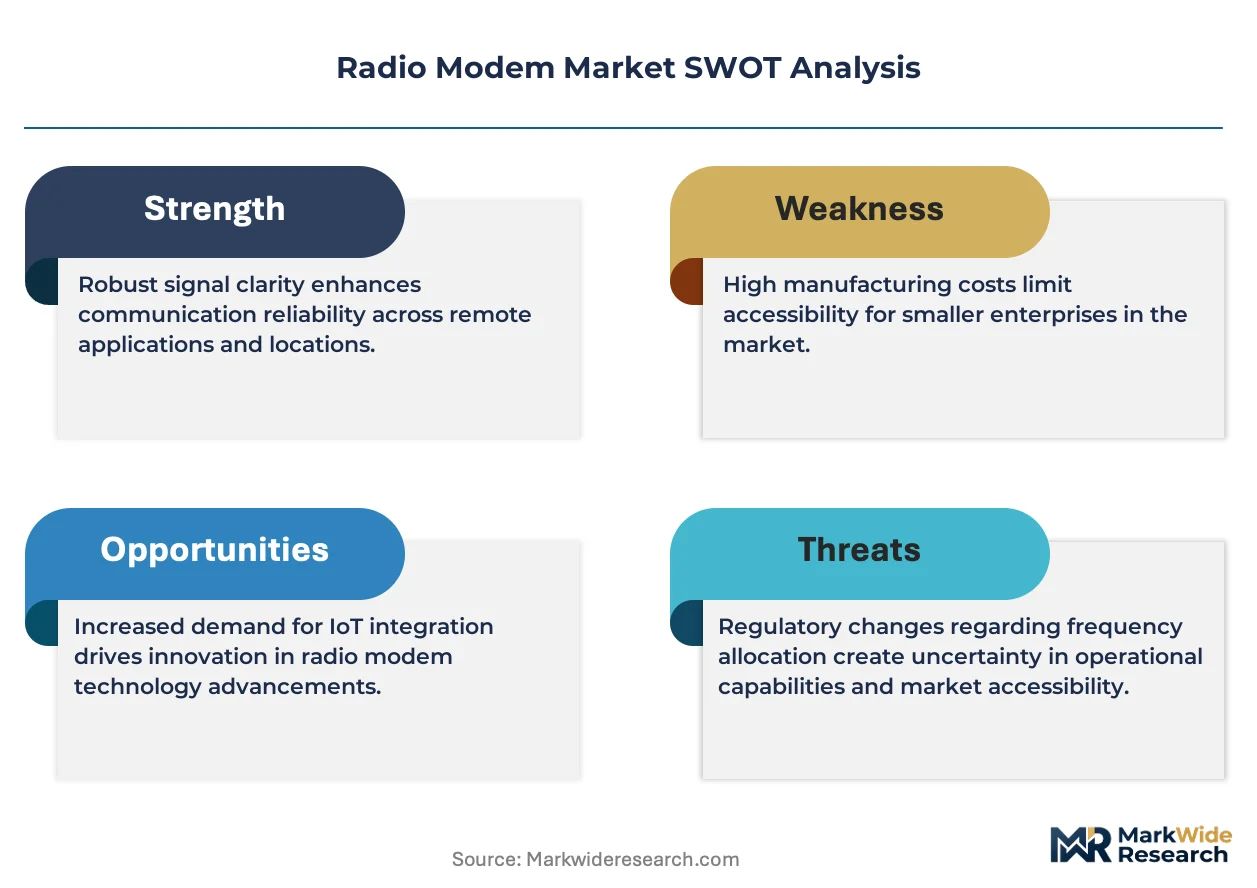
Platform licensing revenue is compressing hardware margins while extending customer lifetime value through recurring firmware subscriptions. Vendors now bundle edge-computing capabilities with radio modem hardware to capture service contract renewals across utility and industrial IoT deployments.
Growth Catalysts
- FCC Part 90 licensing reforms:Expanded spectrum access for critical infrastructure operators in the United States accelerates deployment across distribution automation networks.
- Grid hardening investments:Utility capital programs for storm resilience and wildfire mitigation drive sustained procurement of long-range telemetry hardware.
- Spread Spectrum interference resilience:Regulatory acceptance across multiple jurisdictions enables single-SKU product strategies that reduce certification costs.
Market Restraints
- Semiconductor supply concentration:RF front-end component sourcing from limited foundry capacity creates lead time volatility for sub-GHz transceiver modules.
- Licensed spectrum coordination costs:FCC Part 90 geographic coordination procedures extend deployment timelines and raise upfront project economics.
- Cellular LPWAN substitution:NB-IoT and LTE-M modules from telecom carriers capture low-bandwidth metering applications previously served by unlicensed radio.
Strategic Opportunities
- Rural agricultural telemetry:Unpenetrated farmland monitoring in Brazil and Australia creates demand for solar-powered, long-range unlicensed spectrum endpoints.
- Cybersecurity certification tailwinds:EU Radio Equipment Directive mandates for network resilience create premium positioning for vendors with pre-certified secure boot architectures.
- Edge-AI convergence:Integration of inference engines within radio gateways enables localized anomaly detection without cloud backhaul latency.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in antenna design and propagation modeling concentrates among legacy defense contractors, constraining vendor hiring pipelines.
- Multi-protocol integration complexity:Utility customers demand seamless coexistence of DNP3, Modbus, and MQTT within single gateway platforms, extending firmware development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Modem Market |
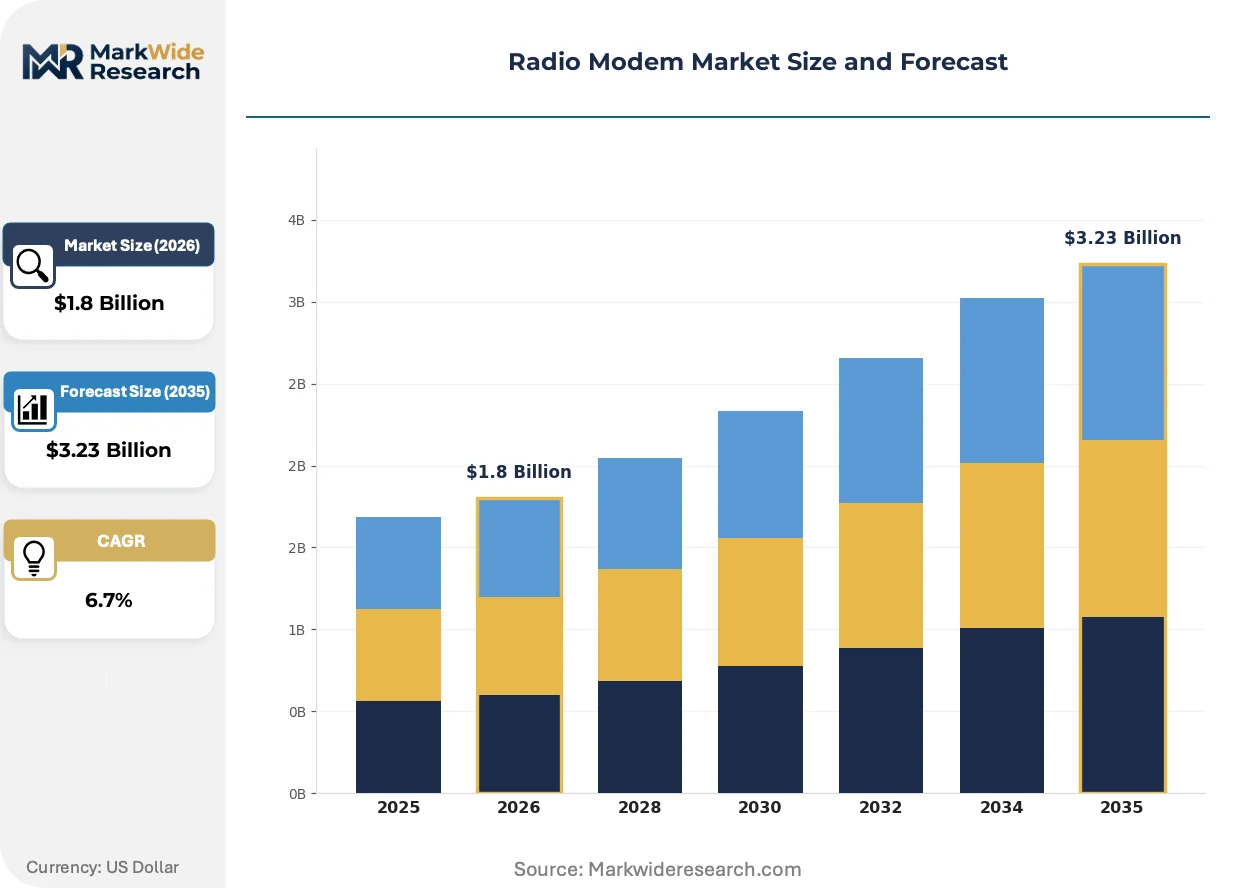
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-to-Point, Point-to-Multipoint, Serial, Ethernet Technology: Spread Spectrum, Frequency Hopping, LoRa, Zigbee End User: Aerospace, Telecommunications, Utilities, Transportation Installation: Fixed, Portable, Mobile, Indoor |
| Companies Covered | Motorola Solutions, Digi International, Schneider Electric, Satel Oy, Campbell Scientific, Cohda Wireless, Arada Systems, Advantech B+B SmartWorx, FreeWave Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Modem Market Emerging Trajectories
Radio modem architectures are fragmenting between licensed and unlicensed spectrum strategies as regulatory clarity and total cost of ownership trade-offs reshape procurement criteria across vertical markets.
Multi-protocol firmware stacks are hybridizing legacy serial SCADA interfaces with native IP transport layers. Water utilities in the United States are deploying these transitional gateways to bridge decades-old RTU infrastructure with modern AMI backbones. This hybridizing approach compresses replacement capex while extending service life of stranded field assets.
ETSI EN 300 220 spectrum efficiency mandates are tightening emission mask requirements for European deployments. Manufacturers must redesign power amplifier stages to meet adjacent channel power ratios, directly impacting transceiver BOM costs. Industrial IoT vendors targeting CE marking are prioritizing pre-certified module sourcing over discrete RF designs to accelerate market entry.
Service contract unbundling is separating hardware procurement from network management software subscriptions. Municipal water districts now evaluate radio modem vendors on recurring platform fees rather than upfront equipment costs alone. This behavioral shift concentrates margin capture in hub-and-spoke network management suites across North American utility verticals.
Radio Modem Market Segmentation
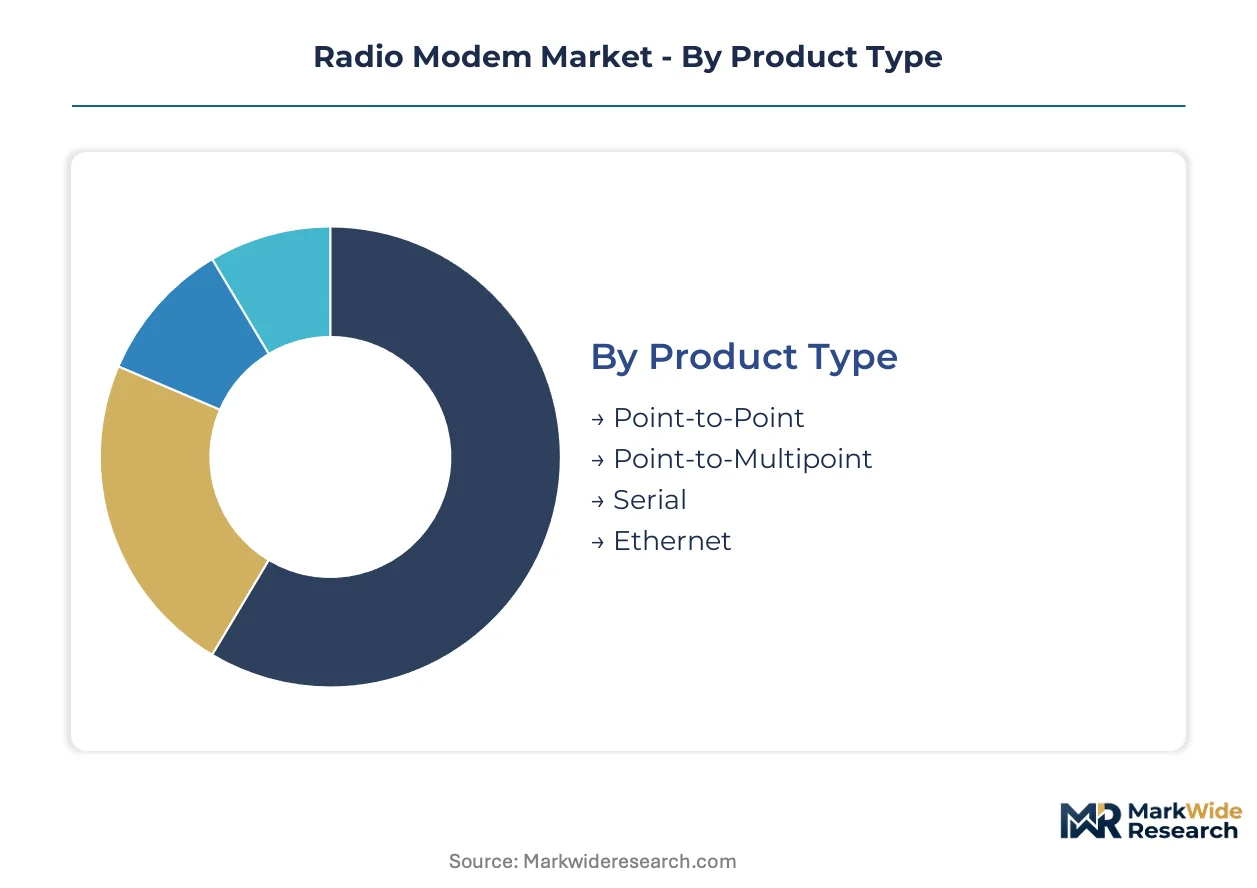
Radio modem procurement cycles vary dramatically by deployment context. Fixed infrastructure installations lock capital for seven to ten years. Portable and mobile units turn over every three to five years as field teams refresh fleets. Understanding these replacement rhythms shapes inventory planning and service contract pricing.
Product Type:
Replacement cycles stretch longest for hub infrastructure and shortest for edge connectivity modules. Point-to-Multipoint hubs dominate depreciation schedules while Serial adapters face the most frequent obsolescence pressure from protocol migration.
- Point-to-Point:Dedicated radio links modulate data across paired transceivers for high-reliability backhaul. Electric utilities in Texas and California deploy these for substation interconnects where fiber trenching costs prove prohibitive. FCC Part 90 licensing constraints limit geographic deployment flexibility.
- Point-to-Multipoint:Hub-and-spoke architectures concentrate network intelligence in central gateways serving dozens of remote endpoints. Water utilities across the United States favor this topology for AMI backhaul, capturing recurring software subscription revenue through centralized management platforms.
- Serial:Legacy RS-232/RS-485 interface modules bridge decades-old RTU infrastructure. Demand concentrates in brownfield industrial sites where full replacement capex remains unjustified.
- Ethernet:Native IP transport modules enable direct integration with modern SCADA and IoT platforms. Grid modernization programs in Florida and Arizona drive procurement for greenfield distribution automation networks.
Point-to-Multipoint anchors the volume base while Ethernet gains share at the steepest rate.
Technology:
Cost tiers separate premium licensed-spectrum solutions from economy unlicensed alternatives. Spread Spectrum and Frequency Hopping command hardware premiums for interference immunity. LoRa and Zigbee compete on module cost for high-volume, low-bandwidth deployments.
- Spread Spectrum:Direct-sequence modulation spreads signal energy across wide bandwidth for regulatory resilience and coexistence robustness. FCC acceptance across multiple rule parts enables single-SKU manufacturing strategies that compress certification overhead.
- Frequency Hopping:Rapid carrier switching defeats narrowband interference and eavesdropping attempts. Military and critical infrastructure operators in the United States specify these transceivers for electromagnetic threat environments.
- LoRa:Chirp spread spectrum enables kilometer-range links at milliwatt power budgets. Utility metering applications in rural service territories exploit unlicensed sub-GHz bands to avoid recurring spectrum fees.
- Zigbee:Mesh networking protocol stacks optimize for low-latency, short-range sensor clusters. Building automation and indoor industrial monitoring represent primary demand pockets.
Spread Spectrum dominates current procurement volumes while LoRa expands most quickly in utility metering verticals.
End User:
Application requirements dictate ruggedization, certification, and protocol support. Aerospace and Transportation demand MIL-STD environmental testing. Utilities prioritize NERC CIP cybersecurity compliance. Telecommunications carriers emphasize spectral efficiency for license economics.
- Aerospace:Avionics-grade transceivers withstand extreme temperature cycling and vibration profiles. Satellite ground stations and unmanned aerial system telemetry represent concentrated demand in the United States.
- Telecommunications:Tower backhaul and remote site monitoring drive volume for carrier-grade reliability specifications. Network operators specify hot-standby redundancy for five-nines availability targets.
- Utilities:Electric, water, and gas distribution operators form the largest vertical demand pool. Grid hardening investments and smart metering mandates across the United States sustain multi-year procurement cycles.
- Transportation:Fleet management and rail signaling applications require mobile roaming capabilities. Positive train control systems and highway tolling infrastructure anchor deployment scale.
Utilities anchor the volume base while Transportation climbs the fastest as connected vehicle mandates proliferate.
Installation:
Customer type separates capital-intensive infrastructure owners from operational expenditure-driven field service organizations. Fixed installations involve utility engineering departments with multi-year planning horizons. Portable and Mobile procurement flows through operations budgets with annual refresh cycles.
- Fixed:Pole-mounted or tower-integrated transceivers with grid-tied power and directional antennas. Electric cooperatives across the Midwest deploy these for distribution automation backhaul.
- Portable:Battery-powered units with integrated antennas for temporary deployment. Emergency response agencies and construction site managers drive replacement demand.
- Mobile:Vehicle-mounted transceivers with roaming handoff capabilities. Municipal fleet operators and rail systems specify these for wide-area coverage.
- Indoor:Low-power modules for building automation and factory floor sensor networks. Manufacturing facilities in the southeastern United States favor these for environmental monitoring.
Fixed installations anchor the volume base while Portable units gain share at the steepest rate as emergency preparedness budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in the United States demonstrate the lowest price elasticity, absorbing premium hardware for licensed-spectrum reliability, while agricultural operators in Brazil and Australia prioritize unit economics over feature depth.
United States
Electric cooperatives across Texas and California deploy point-to-point radio links for substation interconnects where fiber trenching costs prove prohibitive. FCC Part 90 licensing reforms expand spectrum access for critical infrastructure operators, accelerating distribution automation procurement cycles. Storm-hardening capital programs in Florida and Arizona drive sustained demand for ruggedized hub-and-spoke architectures.
Germany
Industrial IoT vendors targeting CE marking prioritize pre-certified module sourcing over discrete RF designs to accelerate market entry. ETSI EN 300 220 spectrum efficiency mandates tighten emission mask requirements, forcing power amplifier stage redesigns that impact transceiver BOM costs. Manufacturing facilities in Bavaria favor low-power indoor modules for environmental monitoring and factory floor sensor networks.
Brazil
Unpenetrated farmland monitoring creates demand for solar-powered, long-range unlicensed spectrum endpoints among agricultural cooperatives. The country's national telecommunications regulator governs sub-GHz band allocations for rural telemetry applications. Soybean and sugarcane operations in Mato Grosso and São Paulo states deploy chirp spread spectrum links to avoid recurring spectrum fees.
Australia
Remote mining operations and pastoral stations require kilometer-range connectivity without cellular infrastructure. The national communications authority manages spectrum coordination for unlicensed land mobile services in the outback. Western Australia and Queensland host concentrated deployments of battery-powered portable units for temporary construction and emergency response use.
China
Smart grid investments by state-owned utilities drive volume procurement for native IP transport modules. MIIT sets transceiver certification timelines and geographic deployment parameters for licensed land mobile operations. Yangtze River Delta manufacturing clusters produce cost-optimized mesh networking protocol stacks for building automation and indoor industrial monitoring.
Radio Modem Market Vendor Landscape
Capability concentration sits with defense-heritage RF engineering specialists; scale advantage sits with diversified industrial automation conglomerates. The vendor base organizes into three tiers: licensed-spectrum incumbents with public safety installed bases, unlicensed-spectrum specialists targeting agricultural and oilfield telemetry, and industrial IoT platform vendors bundling edge computing with connectivity hardware. Dominant competitive moves include strategic partnerships between modem manufacturers and network management software providers, plus portfolio diversification into cybersecurity-certified product lines.
Within the licensed-spectrum tier, Motorola Solutions anchors positions through public safety relationships extending into federal and municipal agencies. Digi International exemplifies the industrial IoT platform archetype, bundling firmware subscriptions with gateway hardware. FreeWave Technologies occupies a specialist position in long-range unlicensed spectrum solutions. These three represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| Motorola Solutions |
| Digi International |
| Schneider Electric |
| Satel Oy |
| Campbell Scientific |
| Cohda Wireless |
| Arada Systems |
| Advantech B+B SmartWorx |
| FreeWave Technologies |
| Others |
Supply Flow & Price Mechanics
Semiconductor foundry concentration in RF front-end component sourcing determines both pricing tier spreads and supply chain shape across licensed and unlicensed spectrum product lines. FCC Part 90 certification timelines and geographic coordination procedures compress margins on project-based deployments while extending customer lifetime value through recurring firmware subscriptions.
Pricing Analysis
After-sales service contracts and network management platform subscriptions now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium licensed-spectrum, standard unlicensed, and economy module levels separates vendors by certification depth and interference resilience. Cost compression in unlicensed segments is intensifying because cellular LPWAN modules capture low-bandwidth metering applications. Agricultural operators in Brazil demonstrate the highest price sensitivity while electric cooperatives across Texas absorb premium hardware for grid-hardening reliability.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Foxconn, Jabil, and Flex holding RF module assembly lines across Shenzhen, Penang, and Guadalajara. Discrete power amplifier components and sub-GHz transceiver silicon draw from Taiwan, South Korea, and China. Single-source vulnerability in gallium arsenide foundry capacity threatens lead time stability for military-grade frequency hopping modules. Distribution runs through authorized industrial automation distributors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing revenue layers are expanding faster than hardware shipments as municipal water districts evaluate vendors on recurring network management fees rather than upfront equipment costs.
For Market Incumbents: Harden firmware subscription attach rates through edge-computing integration that locks utility customers into centralized management platforms. Deepen backward integration into secure boot architectures to capture EU Radio Equipment Directive certification premiums before cybersecurity mandates tighten. Cellular LPWAN substitution in metering verticals represents the most acute substitution threat requiring defensive bundling responses.
For New Entrants and Emerging Players: Pursue unpenetrated agricultural telemetry in Mato Grosso and Queensland where solar-powered, long-range unlicensed spectrum endpoints face minimal incumbent saturation. Target portable emergency response units as emergency preparedness budgets expand faster than fixed infrastructure cycles. Lead with solar-powered deployment kits that eliminate grid-tied installation complexity for remote pastoral stations.
For Investors and Strategic Acquirers: FCC Part 90 licensing reforms reshape the acquisition landscape by expanding addressable market for licensed-spectrum specialists with existing geographic coordination expertise. Long-term viability centers on vendors with recurring revenue exceeding hardware depreciation cycles. Prioritize targets with pre-certified module sourcing relationships that compress ETSI EN 300 220 compliance timelines. Watch spectrum reallocation proceedings as the critical inflection signal for product architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Gateway Integration | Localized inference engines reduce cloud backhaul latency for utility anomaly detection. |
| Cybersecurity Certification Investment | Pre-certified secure boot architectures command premium positioning under EU Radio Equipment Directive. |
| Multi-Protocol Firmware Stack Development | Hybrid DNP3-Modbus-MQTT bridging extends service life of stranded RTU infrastructure. |
| Rural Agricultural Telemetry Expansion | Solar-powered unlicensed spectrum endpoints address unpenetrated farmland monitoring in Brazil and Australia. |
| Service Contract Unbundling | Separating hardware procurement from network management subscriptions concentrates margin capture in software. |
Methodological Framework
A standing panel of utility engineering directors, RF procurement managers, SCADA integration specialists, and agricultural telemetry operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized standards listings, utility capital expenditure filings, and industrial IoT platform subscription disclosures. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts across distribution automation and AMI backhaul verticals.
Scenario-bracketing anchored projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include product architecture, spectrum licensing regime, end-use vertical, and geographic regulatory cluster. CAGRs derived from replacement cycle analysis and infrastructure modernization program timelines. Forecast inputs incorporated FCC Part 90 licensing reform implementation pace and EU cybersecurity certification adoption curves.
Sensitivities concentrate around semiconductor foundry capacity allocation, spectrum reallocation proceedings, and cellular LPWAN pricing trajectories. Quarterly review of utility capital program announcements and regulatory docket filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wi-Fi Extender Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Global Active Network Management Market
Network Technology
Industrial Wireline Networking Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Virtual Router Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Protocol Analyzer Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Global Private 5G Network Market