
 Global Heterogeneous Network Market | 2026-2036
Global Heterogeneous Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heterogeneous Network Market Foresight
Industrial automation is expanding as the fastest-growing end-use vertical for heterogeneous network infrastructure, displacing traditional campus network deployments in vendor priority queues. Cisco Systems leverages its enterprise routing heritage to anchor indoor small cell integration for manufacturing floors. Nokia Corporation competes through R&D intensity in macro-femtocell orchestration platforms. Samsung Electronics dominates 5G radio unit supply for Korean industrial parks, extending its geographic concentration into Southeast Asian smart factory projects.
A heterogeneous network integrates dissimilar radio access technologies—small cells, macro cells, Wi-Fi access points, femtocells, distributed antenna systems, and repeaters—into a unified coverage and capacity layer managed through common orchestration protocols. These architectures typically operate across licensed and unlicensed spectrum bands from 600 MHz to 6 GHz, with sub-6 GHz small cells providing 100-250 meter radius coverage and millimeter-wave nodes handling high-density zones below 200 meters. The technology dimension shows small cell deployments capturing the dominant share of new capital expenditure as operators densify urban grids, while distributed antenna systems retain premium margin pools in transportation tunnels and stadium venues. Application segmentation reveals smart cities and public safety networks as the structural growth corridor, with industrial automation trailing closely as private 5G HetNet adoption accelerates in European and East Asian manufacturing belts.
The FCC spectrum auction framework and the EU Radio Equipment Directive shape product certification requirements for multi-technology base stations entering North American and European markets. China's MIIT imposes domestic GB standards on radio transmission equipment, creating parallel compliance pathways that influence vendor product roadmaps. Japan's METI spectrum coordination rules for shared small cell bands add a third regulatory vector affecting Asia-Pacific deployment timelines. Stakeholders must monitor evolving national security review thresholds for foreign network equipment as these determine supply eligibility across the three largest addressable markets.
Market Dynamics
Small cell densification is compressing traditional macro-cell deployment cycles as mobile operators in China, Germany, and the United States layer dissimilar radio access technologies into unified coverage architectures. This structural force is reordering capital allocation across licensed and unlicensed spectrum bands.
Growth Catalysts
- FCC Spectrum Auction Framework:The United States regulator's auction mechanisms for mid-band and millimeter-wave frequencies are accelerating small cell siting approvals in dense urban corridors. Municipal permitting timelines have compressed in response.
- Industrial Automation Demand:Manufacturing floors in Germany's Ruhr Valley and South Korea's Gyeonggi Province are deploying private 5G HetNet architectures for deterministic latency control. This end-use vertical is pulling vendor roadmaps toward indoor radio unit integration.
- Wi-Fi 6E Convergence:Unlicensed 6 GHz spectrum integration with licensed small cells is enabling seamless handoff protocols. Enterprise buyers are consolidating vendor relationships around dual-technology access points.
Market Restraints
- Semiconductor Supply Concentration:Advanced radio frequency front-end modules depend on concentrated foundry capacity in Taiwan. Geographic supply risk is elevating equipment lead times for European and North American operators.
- EU Radio Equipment Directive Compliance:Multi-technology base stations face extended certification timelines for CE marking. The directive's evolving cybersecurity annexes are adding six-to-nine month validation periods.
- Passive Optical Network Substitution:Fiber-to-the-premises deployments in Japan and South Korea are absorbing capex that might otherwise flow to wireless densification. Fixed wireless access is losing share in greenfield residential developments.
Strategic Opportunities
- India Smart City Deployments:The country's urban infrastructure mission is creating demand for integrated small cell and distributed antenna systems in transportation hubs. Municipal corporations are issuing multi-technology tenders.
- AI-Driven Network Orchestration:Machine learning-based radio resource management is converging with HetNet controllers. This technology pairing is opening premium pricing tiers for software-defined coverage optimization.
- Japan METI Shared Spectrum Rules:The ministry's local 5G licensing framework is enabling enterprise self-build networks. Manufacturing consortia in Aichi Prefecture are securing dedicated spectrum blocks.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave propagation modeling and interference coordination require specialized electromagnetic simulation expertise. Universities in Western Europe are producing insufficient graduates for deployment scale.
- Multi-Vendor Interoperability:Legacy macro-cell infrastructure from incumbent suppliers resists seamless integration with open RAN small cell architectures. Operators are absorbing integration testing costs.
- Site Acquisition Complexity:Urban small cell siting requires negotiations with municipal governments, utility pole owners, and private landlords. Right-of-way fees are inflating total cost of ownership in London and New York.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heterogeneous Network Market |
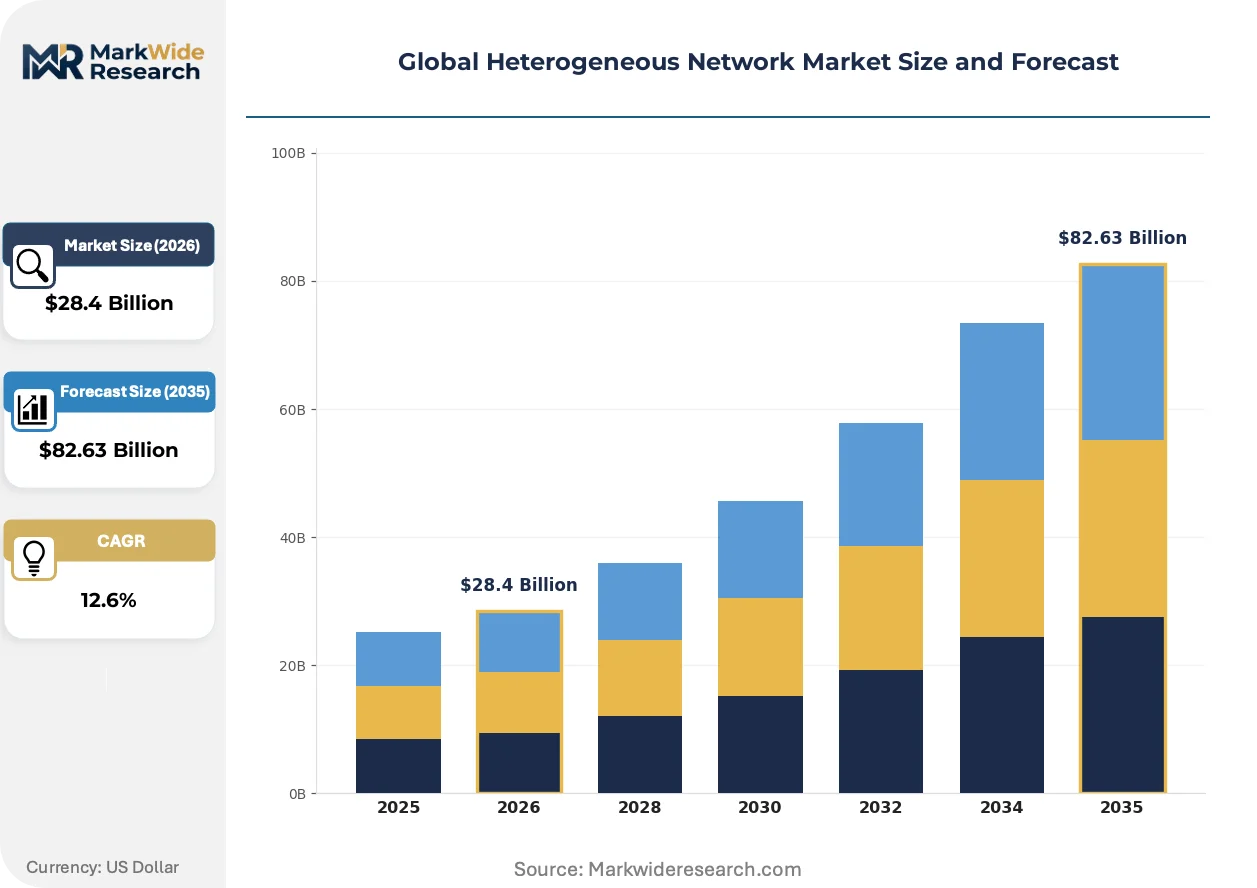
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $82.63 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
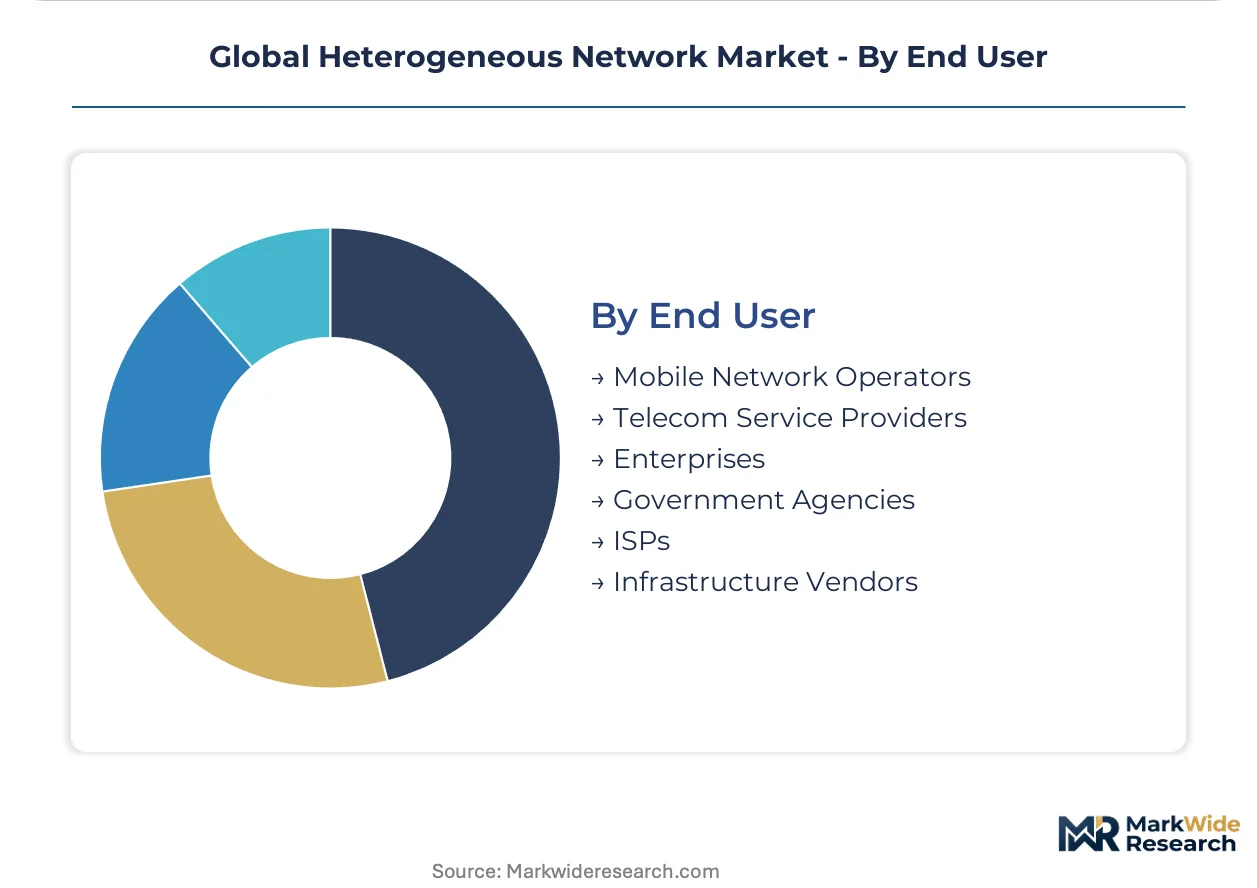
| Segmentation | Technology: Small Cell, Macro Cell, Wi-Fi, Femtocell, Distributed Antenna System, Repeaters Application: Smart Cities, Transportation Networks, Public Safety, Industrial Automation, Campus Networks, Event Coverage Deployment: Indoor, Outdoor, Urban, Suburban, Rural, Enterprise End User: Mobile Network Operators, Telecom Service Providers, Enterprises, Government Agencies, ISPs, Infrastructure Vendors |
| Companies Covered | Cisco Systems, Inc., NEC Corporation, Nokia Corporation, Qualcomm, Ericsson, Huawei Technologies Co., Ltd., ZTE Corporation, CommScope Holding Company, Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heterogeneous Network Market Shifts & Advancements
Open RAN disaggregation is fragmenting traditional integrated base station supply chains, forcing incumbent vendors to modularize hardware and software stacks. This architectural shift is redistributing value capture toward specialized radio unit suppliers and cloud-native software vendors.
Millimeter-wave radio units are expanding into indoor manufacturing environments where deterministic latency requirements exceed what sub-6 GHz small cells can deliver. German automotive suppliers are piloting 28 GHz private networks for robotic control systems. This frequency migration is compressing the addressable market for traditional Wi-Fi in high-interference industrial settings.
The EU AI Act's risk classification framework is imposing documentation burdens on network management systems that automate radio resource allocation. Vendors serving European mobile operators must now maintain algorithmic transparency logs for self-optimizing network controllers. This compliance requirement is favoring established suppliers with dedicated regulatory affairs functions over emerging software entrants.
Enterprise buyers are consolidating procurement around managed service contracts that bundle hardware, spectrum access, and network operations. This purchasing pattern is displacing capital expenditure models in the United States healthcare and logistics verticals. Hospital systems in Texas and distribution centers in Pennsylvania are outsourcing HetNet deployment to specialized infrastructure-as-a-service providers.
Global Heterogeneous Network Market Segmentation
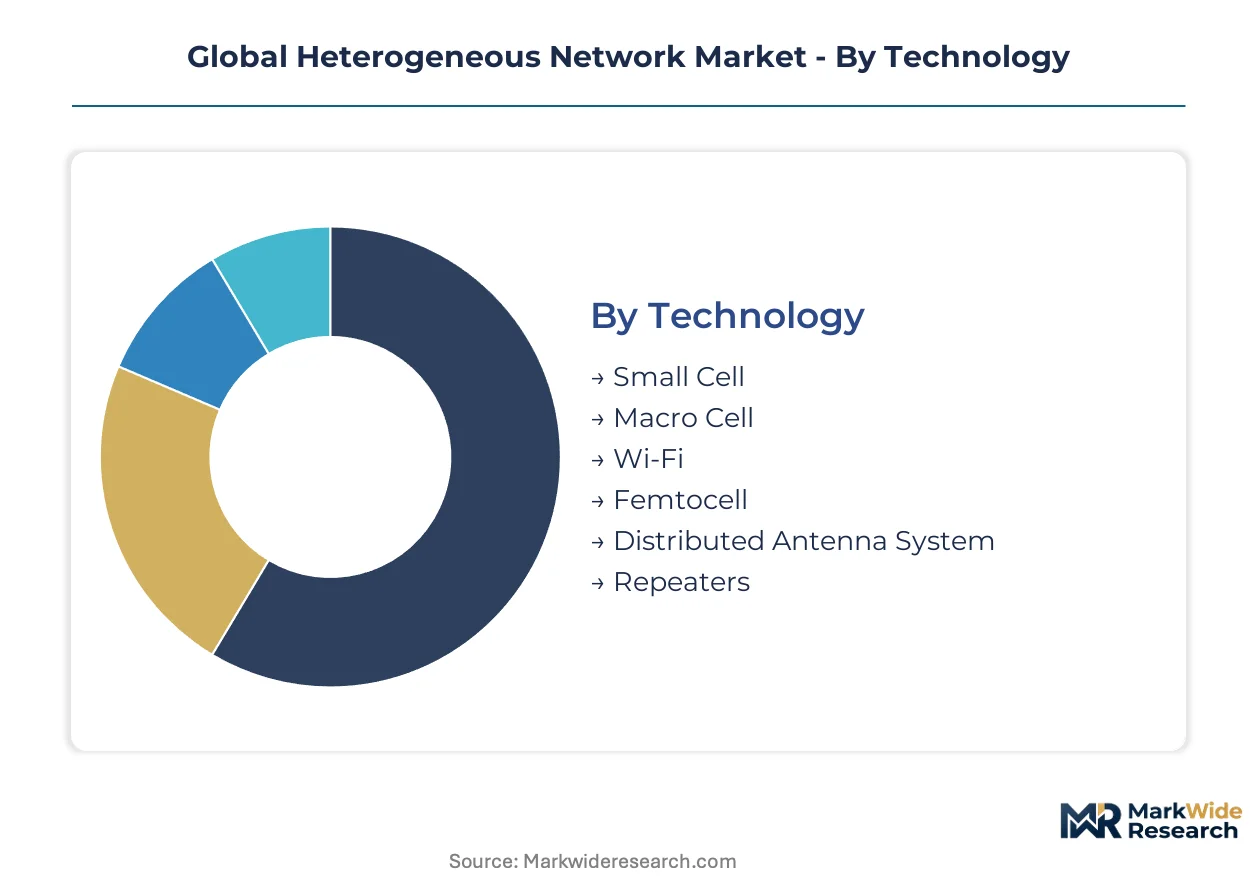
Heterogeneous network procurement varies sharply across deployment contexts. Certification pathways from the FCC, EU Radio Equipment Directive, and China's MIIT create divergent compliance costs that reshape vendor prioritization and operator capex allocation.
Technology:
FCC Part 27 and EU RED certifications apply differentially across radio access types, with millimeter-wave small cells facing the most stringent electromagnetic compatibility testing.
- Small Cell:Low-power base stations operating below 10 watts ERP densify urban grids through sub-6 GHz and millimeter-wave configurations. Chinese mobile operators in Beijing and Shanghai are layering these units for 5G capacity expansion, driven by MIIT spectrum allocation mandates for mid-band deployment.
- Macro Cell:High-power wide-area infrastructure provides foundational coverage layers across licensed spectrum blocks. German operators in the Ruhr Valley maintain these as backhaul anchors for industrial HetNet architectures, constrained by extended CE marking timelines under evolving EU cybersecurity annexes.
- Wi-Fi:Unlicensed 2.4 GHz, 5 GHz, and 6 GHz access points integrate with licensed small cells for seamless handoff.
- Femtocell:Residential and enterprise picocells extend coverage through consumer-grade installations.
- Distributed Antenna System:Fiber-fed antenna arrays serve transportation tunnels and stadium venues with uniform signal distribution.
- Repeaters:Signal amplification devices extend coverage into dead zones without additional baseband processing.
Leading the category by volume: Small Cell. Growing fastest: Distributed Antenna System.
Application:
End-use contexts determine whether deployments prioritize latency determinism, coverage uniformity, or capacity density.
- Smart Cities:Integrated sensor backhaul and public Wi-Fi networks require multi-technology coordination across municipal infrastructure. Indian urban missions in Mumbai and Delhi are issuing bundled tenders for small cell and DAS deployment in transportation corridors.
- Industrial Automation:Private 5G HetNet architectures deliver deterministic latency for robotic control systems. South Korean manufacturing consortia in Gyeonggi Province are deploying 28 GHz private networks, displacing traditional Wi-Fi in high-interference factory environments.
- Transportation Networks:Continuous coverage for rail, aviation, and maritime corridors.
- Public Safety:Mission-critical voice and data networks for first responder coordination.
- Campus Networks:Enterprise-grade coverage for educational and corporate facilities.
- Event Coverage:Temporary capacity augmentation for stadiums and convention centers.
Smart Cities commands the largest installed base. Industrial Automation shows the steepest expansion trajectory.
Deployment:
Site acquisition complexity and power availability vary dramatically across physical installation environments.
- Urban:Dense small cell layering on utility poles and building facades faces right-of-way fee inflation in London and New York. Municipal permitting compression in response to FCC framework acceleration is shortening deployment timelines in US metropolitan corridors.
- Indoor:Manufacturing floors and healthcare facilities require specialized radio unit integration for coverage penetration. German automotive suppliers are piloting millimeter-wave indoor networks for robotic control, where sub-6 GHz propagation proves insufficient.
- Outdoor:Exposed installations requiring weatherproofing and vandal resistance.
- Suburban:Moderate-density coverage extensions between urban cores and rural peripheries.
- Rural:Low-density wide-area coverage with extended inter-site distances.
- Enterprise:Private network buildouts with dedicated spectrum or licensed small cell leasing.
Urban deployment absorbs the majority of annual capex. Enterprise buildouts are climbing the fastest.
End User:
Procurement authority and spectrum access rights segment buyer sophistication and contract structures.
- Mobile Network Operators:Licensed spectrum holders with nationwide deployment mandates. Japanese operators are leveraging METI local 5G licensing frameworks to support enterprise self-build networks in Aichi Prefecture manufacturing clusters.
- Enterprises:Private network adopters seeking deterministic performance for operational technology integration. US hospital systems in Texas and distribution centers in Pennsylvania are outsourcing HetNet deployment to infrastructure-as-a-service providers, consolidating procurement around managed service contracts.
- Telecom Service Providers:Fixed and mobile converged operators with wholesale network access.
- Government Agencies:Public safety and municipal infrastructure authorities with dedicated funding streams.
- ISPs:Internet service providers extending fixed wireless access offerings.
- Infrastructure Vendors:Equipment manufacturers with captive deployment capabilities for proof-of-concept networks.
Mobile Network Operators dominate procurement volume. Enterprises are gaining share fastest through private 5G adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate small cell manufacturing capacity, while India's dedicated telecom equipment parks attract assembly investment. Spectrum allocation reforms in Germany and South Korea are accelerating private 5G deployment timelines.
United States
FCC auction mechanisms for mid-band frequencies compress municipal permitting timelines in dense urban corridors. The regulator's Part 27 certification framework shapes electromagnetic compatibility requirements for millimeter-wave small cells entering commercial deployment. Hospital systems in Texas outsource HetNet infrastructure to managed service providers, consolidating procurement around bundled hardware and operations contracts.
China
MIIT spectrum allocation mandates drive mid-band 5G capacity expansion across Beijing and Shanghai metropolitan grids. GB standards on radio transmission equipment create parallel compliance pathways that influence vendor product roadmaps for domestic market entry. Mobile operators in the Yangtze River Delta layer sub-6 GHz small cells for urban densification, absorbing the majority of regional capital expenditure.
Germany
Automotive suppliers in the Ruhr Valley pilot 28 GHz private networks for robotic control systems requiring deterministic latency. The EU Radio Equipment Directive's evolving cybersecurity annexes extend CE marking validation periods for multi-technology base stations. Manufacturing consortia in Baden-Württemberg deploy industrial HetNet architectures with macro cells serving as backhaul anchors.
South Korea
Gyeonggi Province manufacturing clusters adopt private 5G HetNet architectures, displacing traditional Wi-Fi in high-interference factory environments. METI spectrum coordination rules in neighboring Japan create reference frameworks for shared small cell band licensing. Samsung Electronics anchors 5G radio unit supply for domestic industrial parks, extending geographic concentration into Southeast Asian smart factory projects.
India
Urban infrastructure missions in Mumbai and Delhi issue bundled tenders for integrated small cell and distributed antenna systems in transportation corridors. TRAI spectrum management frameworks influence operator deployment priorities for licensed and unlicensed band integration. Municipal corporations accelerate right-of-way negotiations for utility pole siting, though fee structures remain unresolved in dense metropolitan districts.
Global Heterogeneous Network Market Competitive Landscape
Top-tier vendors anchor integrated base station supply, while specialized radio unit suppliers and cloud-native software vendors capture value from Open RAN disaggregation. The vendor base stratifies across three tiers: incumbent integrated equipment manufacturers, modular hardware specialists, and software-defined orchestration providers. Strategic moves concentrate on modularizing legacy stacks and forming cross-tier partnerships for multi-vendor interoperability.
Within the integrated infrastructure tier, Cisco Systems, Nokia Corporation, and Samsung Electronics occupy positions spanning enterprise routing heritage, macro-femtocell orchestration platforms, and 5G radio unit manufacturing respectively. These entities exemplify divergent competitive vectors: Cisco leverages indoor small cell integration for manufacturing floors, Nokia competes through R&D intensity in unified coverage management, and Samsung dominates supply for Korean industrial parks with extension into Southeast Asian deployments. Their collective positioning illustrates how vendor heritage shapes capture of industrial automation demand.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| NEC Corporation |
| Nokia Corporation |
| Qualcomm |
| Ericsson |
| Huawei Technologies Co., Ltd. |
| ZTE Corporation |
| CommScope Holding Company, Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Mobile network operators in China, Germany, and the United States concentrate procurement authority through multi-year framework agreements, locking in contract-based long-term offtake pricing that favors incumbent integrated equipment manufacturers over modular specialists.
Pricing Analysis
Premium pricing for sub-90-day lead times on advanced radio frequency front-end modules commands 15-25% markups over standard 180-day delivery windows, while spot inventory clearing in Taiwan and South Korea absorbs residual demand. Pricing stratifies across premium, standard, and economy tiers based on certification grade—FCC Part 27 and EU RED compliance tiers—and volume scale commitments above 10,000 units annually. Cost compression in the economy tier is intensifying because foundry capacity constraints in Taiwan force European and North American operators to absorb expedited shipping premiums. Mobile network operators exhibit the highest price sensitivity due to capex cycle pressures, while enterprise private network adopters in manufacturing verticals prioritize deterministic performance over unit economics.
Supply Chain Analysis
Container freight rates from Taiwan and South Korea to Hamburg and Los Angeles have normalized from pandemic peaks but remain elevated versus historical baselines, compressing margins on bulky radio unit shipments. Geographic supply concentration centers on Taiwan for advanced RF front-end module foundry capacity, South Korea for 5G radio unit final assembly, and China for passive component and printed circuit board fabrication. Raw material dependencies include gallium nitride substrates for power amplifiers, high-frequency laminates for antenna substrates, and rare earth elements for magnetics in filter assemblies. Single-source vulnerability in Taiwan's concentrated foundry capacity presents the dominant structural risk. Distribution runs through direct OEM relationships with mobile network operators, supplemented by value-added distributors serving enterprise and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity bottlenecks in Taiwan's concentrated semiconductor manufacturing base prop pricing power for integrated equipment manufacturers, creating a supply-constrained market structure that favors incumbents with captive supplier relationships.
For Market Incumbents: Anchor defensive positioning through backward integration into RF front-end module design and captive foundry allocation agreements in Taiwan and South Korea. Invest in CE marking pre-certification under evolving EU cybersecurity annexes to compress validation timelines and lock out modular competitors. The priority lever rests on controlling the radio unit supply bottleneck that constrains Open RAN deployment timelines. For New Entrants and Emerging Players: Launch via cloud-native orchestration software subscriptions targeting enterprise private 5G deployments in India's smart city infrastructure missions and Japan's METI local 5G licensing framework. The most penetrable white space sits in AI-driven network optimization software for industrial automation verticals in Germany's Ruhr Valley and South Korea's Gyeonggi Province. A direct enterprise sales model bypassing incumbent operator channels captures margin otherwise absorbed by systems integration markups. For Investors and Strategic Acquirers: The window for entry favors specialized radio unit suppliers with proven millimeter-wave indoor propagation expertise and established regulatory affairs functions in the EU and North American markets. Long-term viability hinges on consolidation of modular hardware specialists into platform plays capable of multi-vendor interoperability certification. Watch for FCC spectrum auction velocity and municipal permitting compression in dense US urban corridors as the inflection signal for deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Front-End Design | Captive foundry allocation in Taiwan secures supply priority during capacity crunches. |
| Multi-Vendor Interoperability Certification | Open RAN disaggregation in Germany's industrial parks demands proven integration testing capabilities. |
| AI-Driven Network Orchestration Platform Launch | Machine learning radio resource management commands premium pricing in South Korean manufacturing clusters. |
| Enterprise Private 5G Managed Service Offering | Texas hospital systems and Pennsylvania distribution centers outsource deployment to infrastructure-as-a-service providers. |
| EU Cybersecurity Annex Pre-Certification | Compressed CE marking timelines lock out emerging competitors lacking dedicated regulatory affairs functions. |
Research Methodology
SEC 10-K filings, FCC spectrum auction records, and EU Radio Equipment Directive certification databases formed the secondary backbone, supplemented by customs and trade data tracking radio equipment flows through major port complexes. Primary interviews with mobile network operator procurement executives, industrial automation plant engineers, and regulatory affairs specialists at equipment manufacturers validated deployment timelines and compliance cost structures. Bottom-up triangulation across operator capex disclosures and top-down reconciliation against MIIT and METI spectrum allocation frameworks anchored volume estimates.
Historical trendline analysis of small cell deployment velocity across Beijing, Shanghai, and the Yangtze River Delta established baseline penetration curves, extended through the projection horizon using modeled segmentation across technology type, deployment environment, and end-user category. CAGRs derived from regression analysis of licensed spectrum allocation trajectories and unlicensed band convergence adoption curves. Forecast inputs incorporated foundry capacity utilization rates from Taiwan and South Korea, plus municipal permitting timeline compression observed under FCC framework acceleration.
Foundry capacity constraints, spectrum auction schedule delays, and municipal right-of-way fee inflation are the dominant revision risks that could compress or extend deployment timelines. Forecasts reflect assumptions about regulatory coordination continuity and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context and supplier relationship structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Spain Data Center Networking Market