
 Network Emulator Market | 2026-2036
Network Emulator Market Size, Share, and Industry Trends Forecast 2026-2036
Network Emulator Market Intelligence
A shortage of RF systems engineers with 5G protocol expertise is unwinding product release timelines across the vendor base. Keysight Technologies leverages its calibration laboratory network to sustain premium positioning in high-frequency emulation. Spirent Communications anchors its competitive stance through deep partnerships with tier-one telecom operators in North America and Europe. VIAVI Solutions differentiates via integrated optical and wireless test portfolios that span lab validation through live network monitoring.
A network emulator is a test instrument or software platform that replicates real-world network conditions—latency, jitter, packet loss, bandwidth constraints, and protocol behaviors—within controlled laboratory environments, typically supporting frequency ranges from sub-6 GHz to millimeter-wave bands and throughput scales from megabits to hundreds of gigabits per second. Its primary commercial purpose is to validate device and application performance before deployment in live networks, reducing field failure costs and accelerating certification cycles. Hardware-based systems dominate capital-intensive telecom operator labs where signal fidelity and repeatability command priority, while cloud-based deployments represent the fastest-expanding segment as IT enterprises adopt distributed DevOps pipelines for continuous application testing. The 5G technology segment concentrates R&D investment owing to complexity in massive MIMO and network slicing validation, whereas Ethernet emulation maintains mature, margin-compressed demand driven by data center interconnect testing.
FCC equipment authorization rules and the ETSI EN 303 413 standard for 5G base stations shape product development roadmaps by mandating pre-certification test documentation, effectively filtering market access to vendors with validated emulation toolchains. The EU AI Act and emerging cybersecurity frameworks from ENISA are extending compliance burdens into network testing workflows, particularly for cybersecurity simulation applications where adversarial condition replication must demonstrate traceability. Stakeholders must monitor how spectrum policy fragmentation across national regulators reshapes the addressable test-case universe for multi-market product launches.
Market Dynamics
Telecom operators are compressing lab-to-field validation cycles for 5G massive MIMO deployments, forcing emulation vendors to integrate real-time spectrum environment replication with automated compliance documentation pipelines.
Growth Catalysts
- ETSI EN 303 413:The European standard for 5G base stations mandates pre-certification test documentation, filtering market access to vendors with validated emulation toolchains and expanding procurement of compliant platforms.
- Semiconductor clusters:Dense R&D operations by network equipment manufacturers in California and Texas concentrate demand for high-frequency emulation systems with millimeter-wave fidelity.
- Cloud-native DevOps:IT enterprises are embedding network emulation into distributed CI/CD pipelines, accelerating adoption of containerized test environments for continuous application validation.
Market Restraints
- RF systems engineer scarcity:A shortage of specialists with 5G protocol expertise is unwinding product release timelines across the vendor base and inflating labor costs.
- Hardware capex intensity:Signal fidelity requirements in telecom operator labs demand capital-intensive chassis-based systems with specialized RF front-ends, creating entry barriers for mid-scale buyers.
- EU AI Act compliance:Emerging cybersecurity frameworks from ENISA extend traceability burdens into adversarial condition replication workflows, lengthening development cycles for simulation software vendors.
Strategic Opportunities
- India:TRAI's spectrum auction frameworks and domestic 5G rollout timelines create procurement windows for emulation platforms supporting sub-6 GHz and millimeter-wave validation.
- Open RAN integration:Disaggregation of baseband and radio units is creating demand for multi-vendor interoperability testing, requiring emulation systems that replicate heterogeneous network element behaviors.
- Subscription-based delivery:Cloud-based consumption models are penetrating enterprise IT segments previously priced out of hardware-based systems, expanding addressable market beyond capital-intensive telecom labs.
Industry Challenges
- Calibration complexity:Maintaining measurement traceability across distributed laboratory networks demands continuous investment in metrology infrastructure and certified reference materials.
- Legacy Ethernet integration:Data center interconnect testing requires bridging mature copper-based validation workflows with emerging optical and coherent DSP emulation capabilities.
- Multi-standard harmonization:Spectrum policy fragmentation across national regulators is reshaping the addressable test-case universe, forcing vendors to maintain parallel certification tracks for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Emulator Market |
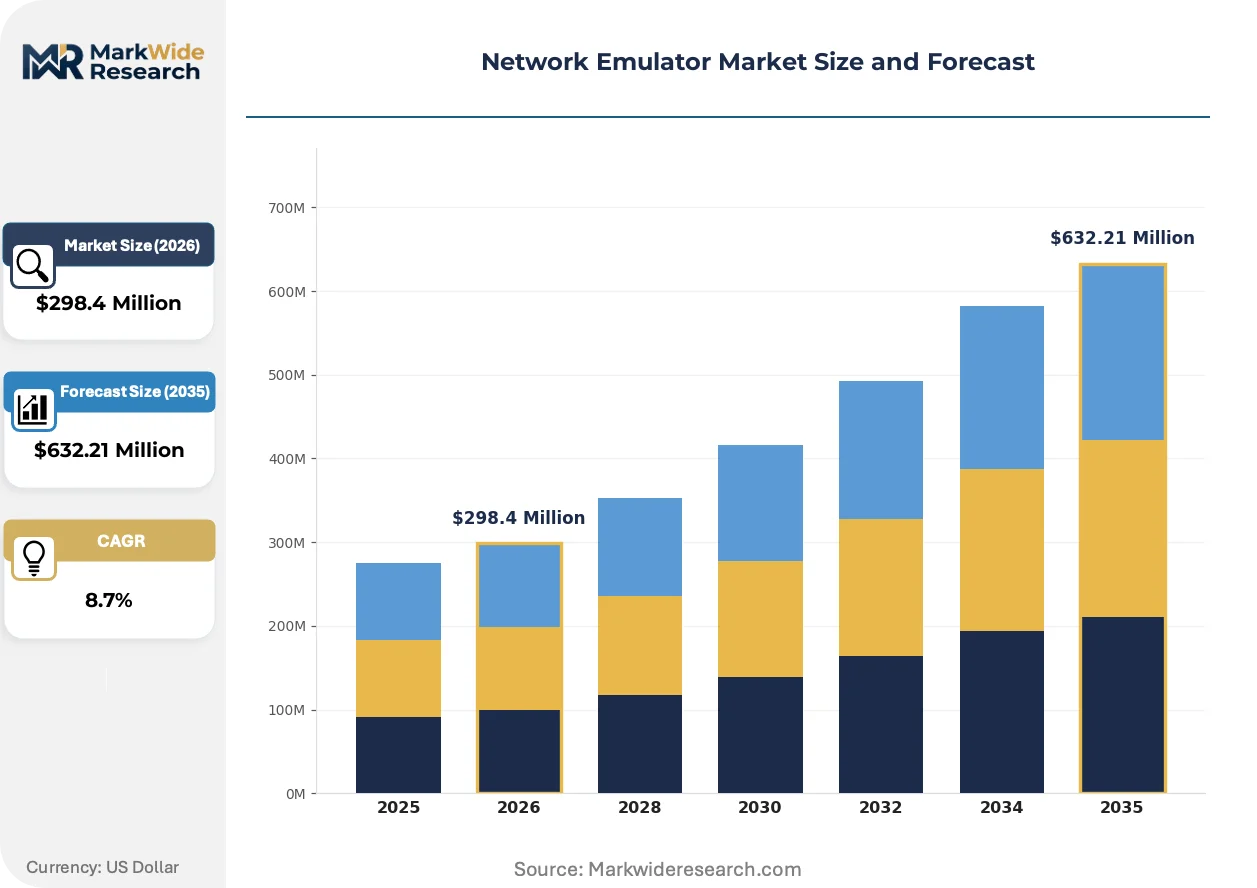
| Market Size in 2026 | $298.4 Million |
| Market Size in 2035 | $632.21 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Based, Software Based, Cloud Based, Hybrid Solutions Technology: LTE, 5G, Wi-Fi, Bluetooth, ZigBee, Ethernet Application: Network Testing, Performance Analysis, Cybersecurity Simulation, Protocol Development, Application Testing End User: Telecom Operators, Network Equipment Manufacturers, IT Enterprises, Research Institutions |
| Companies Covered | Spirent Communications, Keysight Technologies, VIAVI Solutions, Calnex Solutions, Apposite Technologies, Rohde & Schwarz, Polaris Networks, PacketStorm Communications, Aukua Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Emulator Market Strategic Shifts & Innovations
Software-defined emulation architectures are displacing fixed-function hardware, compressing cost structures while expanding test scenario programmability for DevOps-native buyers.
Containerized network emulation is displacing monolithic chassis deployments in enterprise IT environments. DevOps teams at financial services and SaaS providers are adopting Kubernetes-orchestrated test pods that spin up latency, jitter, and packet loss conditions on demand. This shift is displacing capital-intensive procurement cycles with metered consumption models that align test infrastructure spend with release velocity.
The FCC's equipment authorization rules are tightening pre-market validation requirements for 5G NR devices, mandating documented test coverage across specified channel conditions. Vendors must now submit traceable emulation protocols as part of certification filings. Equipment manufacturers in the United States are responding by embedding compliance-grade test automation into R&D workflows rather than treating certification as a final-stage gate.
Buyer concentration among hyperscale cloud operators is compressing sales cycles and unbundling traditional hardware-software bundles. Amazon Web Services and Microsoft Azure are procuring emulation capabilities as managed services rather than capital assets, forcing incumbent vendors to restructure pricing around throughput-based metering. This pattern is most visible in North American enterprise segments where IT infrastructure budgets are migrating from CapEx to OpEx frameworks.
Network Emulator Market Segmentation
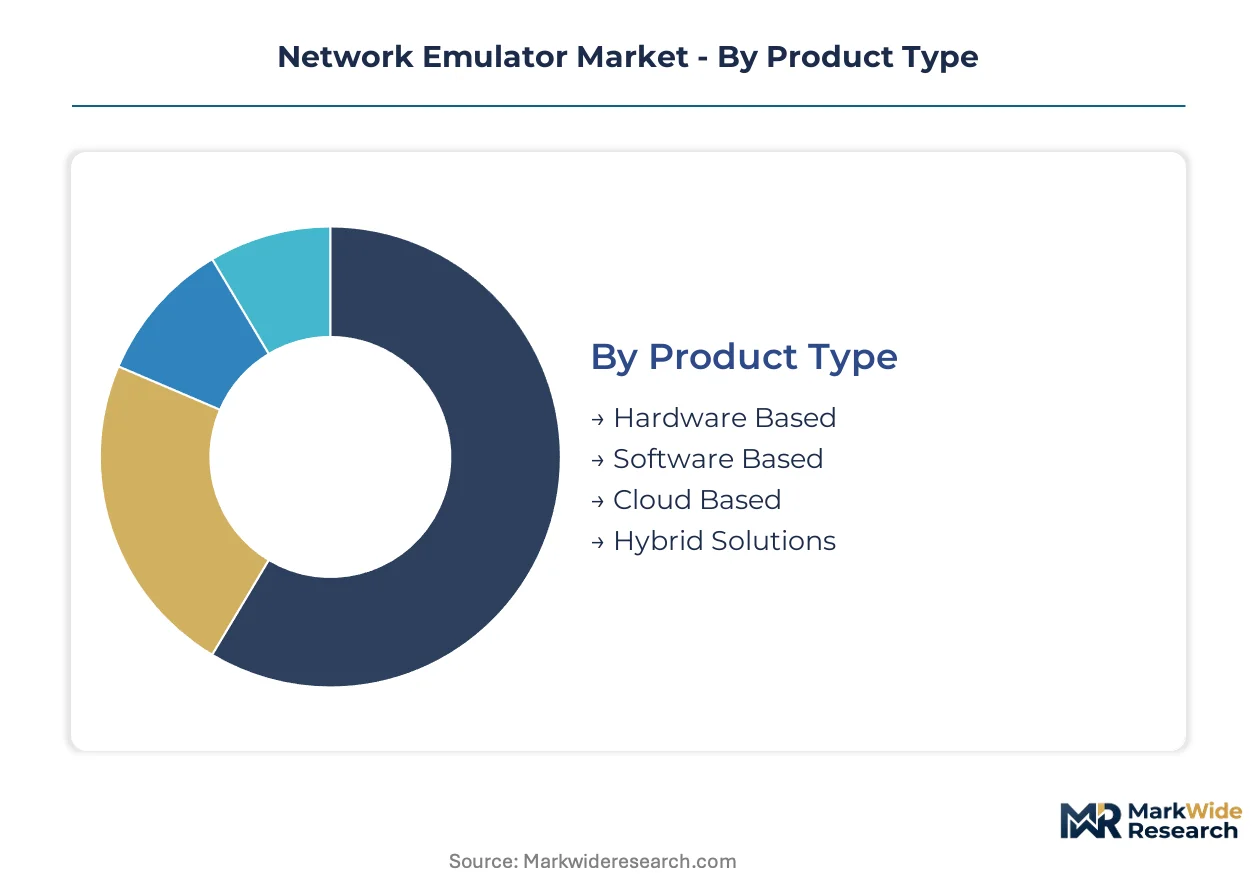
Network emulator procurement patterns diverge sharply across deployment contexts. Telecom operators prioritize signal fidelity and calibration traceability, while IT enterprises optimize for programmatic test orchestration and consumption elasticity.
Product Type:
Hardware-based systems command premium margins in capital-intensive lab environments where measurement repeatability determines contract awards.
- Hardware Based:Chassis-based platforms with specialized RF front-ends deliver sub-6 GHz through millimeter-wave fidelity for telecom operator validation cycles. Dense R&D clusters in California and Texas concentrate procurement of these systems where Keysight Technologies and Spirent Communications maintain calibration laboratory networks.
- Cloud Based:Containerized test environments spin up latency, jitter, and packet loss conditions on demand for DevOps pipelines. Financial services and SaaS providers in the United States are adopting metered consumption models that align infrastructure spend with release velocity, expanding fastest among product types.
- Software Based:Licensed emulation platforms deploy on commodity servers for mid-scale protocol validation workflows.
- Hybrid Solutions:Mixed deployments bridge on-premises signal generation with cloud-based scenario orchestration for distributed engineering teams.
Hardware-based systems hold installed capacity. Cloud-based solutions are rotating up the share rankings.
Technology:
5G emulation concentrates R&D investment and vendor roadmap prioritization owing to massive MIMO complexity and network slicing validation requirements.
- 5G:Massive MIMO beamforming and network slicing validation demand real-time spectrum environment replication with automated compliance documentation. FCC equipment authorization rules mandate traceable test protocols as part of certification filings, filtering procurement to vendors with validated toolchains.
- Ethernet:Data center interconnect testing drives mature demand for copper-based and coherent DSP emulation capabilities. The segment faces margin compression as hyperscale operators unbundle hardware-software bundles and procure managed services from Amazon Web Services and Microsoft Azure.
- LTE:Legacy network validation maintains steady replacement demand among tier-two operators completing 4G coverage obligations.
- Wi-Fi:Enterprise WLAN performance testing supports Wi-Fi 6 and Wi-Fi 7 device certification cycles.
- Bluetooth:Low-power device interoperability validation serves consumer electronics and automotive peripheral ecosystems.
- ZigBee:Industrial IoT and smart home protocol testing maintains niche procurement from sensor network developers.
5G commands the steepest expansion trajectory. Ethernet maintains revenue scale through data center refresh cycles.
Application:
Network testing anchors procurement volume, though cybersecurity simulation is gaining budget allocation from compliance-driven buyers.
- Network Testing:Lab-to-field validation for base station and device certification compresses release timelines for telecom operators. ETSI EN 303 413 standard compliance mandates pre-certification test documentation, expanding procurement of platforms with automated reporting pipelines.
- Cybersecurity Simulation:Adversarial condition replication for threat modeling and resilience validation is extending traceability burdens under ENISA frameworks. EU AI Act compliance requirements are lengthening development cycles for simulation software vendors serving European defense and critical infrastructure sectors.
- Performance Analysis:Throughput and latency benchmarking supports quality-of-service guarantees in service level agreements.
- Protocol Development:Pre-standard validation for 3GPP and IEEE working group contributions drives research institution procurement.
- Application Testing:Continuous integration pipelines for cloud-native services embed network condition emulation into deployment workflows.
Network testing holds installed capacity. Cybersecurity simulation is rotating up the share rankings.
End User:
Telecom operators represent the capital-intensive core, while IT enterprises are expanding the addressable market through subscription-based delivery models.
- Telecom Operators:Verizon, AT&T, and T-Mobile in the United States compress lab-to-field validation cycles for 5G massive MIMO deployments. Procurement prioritizes real-time spectrum environment replication with automated FCC compliance documentation.
- IT Enterprises:DevOps teams at financial services and SaaS providers adopt Kubernetes-orchestrated test pods for continuous application validation. Cloud-native consumption models penetrate segments previously priced out of hardware-based systems.
- Network Equipment Manufacturers:Ericsson, Nokia, and Samsung R&D facilities in California and Texas concentrate demand for high-frequency emulation with millimeter-wave fidelity.
- Research Institutions:University labs and standards bodies maintain foundational protocol development and early-stage technology exploration.
Telecom operators hold installed capacity. IT enterprises are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules anchor procurement intensity in the United States, where spectrum auction frameworks and semiconductor R&D clusters concentrate demand for millimeter-wave validation systems.
United States
Verizon, AT&T, and T-Mobile compress lab-to-field cycles for 5G massive MIMO deployments. FCC equipment authorization rules mandate documented test coverage across specified channel conditions. Dense R&D operations in California and Texas concentrate procurement of high-frequency emulation systems with signal fidelity requirements.
China
MIIT spectrum allocations and domestic 5G base station rollout timelines drive procurement of sub-6 GHz validation platforms. GB standards for telecommunications equipment shape compliance documentation requirements. Yangtze River Delta and Pearl River Delta manufacturing clusters anchor demand from network equipment producers.
Germany
Deutsche Telekom and Vodafone procurement cycles prioritize ETSI EN 303 413 compliance for 5G base station certification. EU AI Act and ENISA cybersecurity frameworks extend traceability burdens into adversarial simulation workflows. Bavaria and North Rhine-Westphalia host automotive and industrial IoT testing facilities requiring protocol validation.
India
TRAI spectrum auction frameworks and domestic 5G rollout timelines create procurement windows for emulation platforms. BIS telecommunications equipment standards filter market access to vendors with validated toolchains. Karnataka and Maharashtra technology corridors concentrate R&D operations from network equipment manufacturers.
Japan
NTT Docomo and KDDI validation cycles emphasize real-time spectrum environment replication for network slicing. METI industrial standards and JIS certification requirements shape procurement documentation. Kanto and Kansai metropolitan areas concentrate semiconductor and telecommunications R&D facilities.
Network Emulator Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in network emulation. Hardware-based chassis platforms with specialized RF front-ends command premium positioning in telecom operator labs, while cloud-native containerized solutions penetrate enterprise IT segments. Two strategic archetypes dominate: calibration-anchored instrument vendors and DevOps-native software platforms. Competitive moves center on automated compliance documentation pipelines and subscription-based consumption models.
Within the integrated instrument tier, Keysight Technologies and Spirent Communications exemplify calibration-anchored positioning through laboratory network density. VIAVI Solutions occupies a position spanning optical and wireless test portfolios. These three represent the dominant competitive anchors against which specialist and cloud-native entrants define differentiation strategies.
| Leading Market Players |
|---|
| Spirent Communications |
| Keysight Technologies |
| VIAVI Solutions |
| Calnex Solutions |
| Apposite Technologies |
| Rohde & Schwarz |
| Polaris Networks |
| PacketStorm Communications |
| Aukua Systems |
| Others |
Cost & Logistics Intelligence
FCC equipment authorization rules gate both supplier qualification and price differentiation in network emulation, filtering procurement to vendors with validated calibration laboratory networks while compressing margins for uncertified entrants attempting commodity positioning.
Pricing Analysis
North American telecom operators pay 40-60% premiums over IT enterprise buyers for hardware-based chassis systems with millimeter-wave fidelity. Three-tier pricing structure across premium, standard, and economy levels separates calibration-anchored instruments from containerized DevOps-native platforms. Pricing pressure stems from hyperscale cloud operators unbundling hardware-software bundles and procuring emulation as metered managed services. IT enterprises exhibit highest price sensitivity, while telecom operators prioritize signal traceability over unit cost.
Supply Chain Analysis
Port congestion on Trans-Pacific lanes elevates inbound logistics costs for specialized RF front-end components sourced from Taiwan, South Korea, and Japan. Manufacturing draws from precision semiconductor foundries, high-frequency connector suppliers, and certified reference material providers. Single-source vulnerability concentrates in millimeter-wave signal generator modules. Distribution runs through direct field engineering teams for telecom operator labs and cloud marketplaces for enterprise IT segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from the DevOps-native buyer segment, where incumbent instrument vendors under-serve containerized test orchestration demand and subscription pricing creates entry points for software-first specialists.
For Market Incumbents: Fortify calibration laboratory network density in California and Texas semiconductor clusters to defend premium positioning against cloud-native entrants. Deepen backward integration into RF front-end manufacturing to offset component supply risk. Prioritize automated compliance documentation pipelines that embed FCC and ETSI EN 303 413 traceability into customer R&D workflows. For New Entrants and Emerging Players: Kubernetes-orchestrated test pod deployment represents the most penetrable service-layer gap, as incumbent hardware vendors lack cloud-native consumption models. Target financial services and SaaS providers in the United States with metered throughput pricing. Lead with CI/CD pipeline integration partnerships rather than standalone product sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based emulation sub-segments as containerization displaces chassis-based systems. Five-to-ten year viability favors software-defined architectures with recurring revenue profiles over hardware-dependent vendors facing margin compression. Monitor hyperscale cloud operator procurement patterns as the inflection signal—managed service adoption accelerates valuation multiple divergence between cloud-native and legacy instrument vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Keysight Technologies sustains premium positioning through metrology infrastructure density in California and Texas. |
| Cloud-Native Platform Integration | DevOps pipeline embedding enables metered consumption models that align spend with release velocity. |
| Automated Compliance Documentation | FCC equipment authorization rules mandate traceable test protocols as part of certification filings. |
| Strategic Partnership with Hyperscale Operators | Amazon Web Services and Microsoft Azure procurement as managed services forces pricing restructuring. |
| Acquisition of Containerized Test Specialists | Kubernetes-orchestrated emulation capabilities address IT enterprise segments previously priced out of hardware systems. |
Research Approach
Cross-validation between primary interviews with RF systems engineers, telecom operator lab directors, DevOps team leads, and network equipment manufacturer R&D heads anchors the qualitative findings against secondary validation from FCC equipment authorization filings, ETSI EN 303 413 documentation databases, hyperscaler capex disclosures, and semiconductor trade flow data. Bottom-up and top-down triangulation reconciles vendor shipment estimates with end-user procurement patterns.
Sensitivity analysis frames volume and value outputs across the projection horizon by modeling deployment model, organization size, technology generation, application intensity, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectory synthesis. Industry-specific forecast inputs include 5G massive MIMO deployment timelines and cloud-native DevOps adoption curves in financial services.
Underlying assumptions cover spectrum policy stability, RF engineering labor supply recovery, and container orchestration platform standardization, with deviation risk concentrated in regulatory fragmentation across national equipment authorization regimes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Home Networking Device Market
Network Technology
IT Connector Market
Network Technology
Network Management Solutions Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Passive Optical Network Market
Network Technology
Microduct Market
Network Technology
Global Private 5G Network Market
Network Technology
Managed MPLS Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Network Packet Broker Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Internet Transit Market
Network Technology
Network Telemetry Market