
 Structured Cabling Market | 2026-2036
Structured Cabling Market Size, Share, and Industry Trends Forecast 2026-2036
Structured Cabling Market Analysis
Market Context
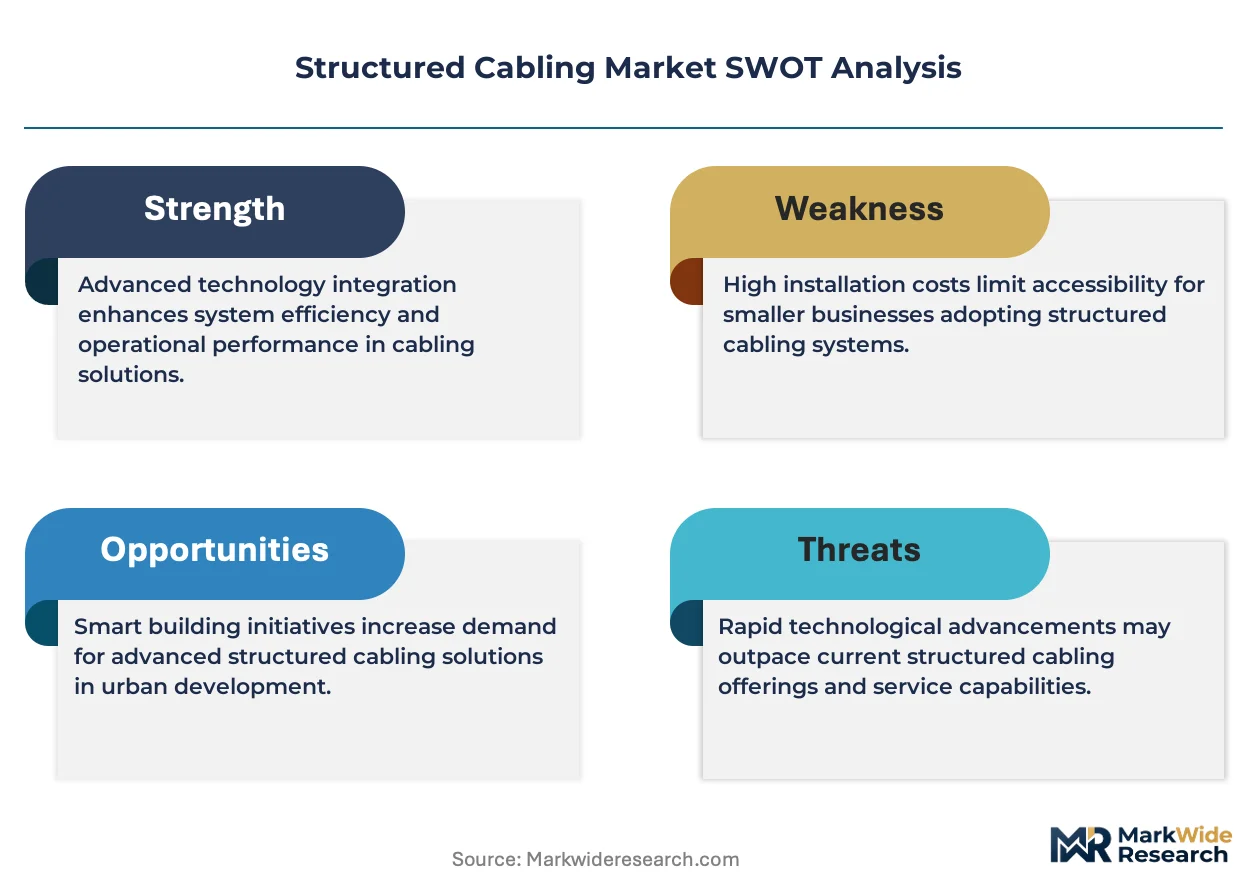
ISO/IEC 11801 certification is reorganizing competitive tiers in structured cabling, forcing smaller contractors toward accredited partnerships or exit. Corning Incorporated leverages its optical fiber manufacturing depth to dominate premium data center projects. CommScope Holding Company anchors North American enterprise builds through extensive distributor relationships. Belden Inc. differentiates in industrial environments with ruggedized copper cable portfolios.
Technical Foundation and Segment Dynamics
Structured cabling comprises standardized subsystems of copper twisted-pair and optical fiber elements, organized into backbone and horizontal distribution layers per TIA-568 hierarchy, designed to deliver scalable telecommunications infrastructure across commercial facilities. Fiber optic cable commands the fastest expansion as hyperscale data centers deploy single-mode fiber for terabit-scale interconnects, while copper cable retains cost advantages in short-reach enterprise LANs where Power over Ethernet loads are intensifying. Installation method segmentation shows in-building deployments generating the densest margin pools due to complex pathway engineering and code compliance, whereas outdoor and underground methods face commodity pricing pressure from utility-scale competition.
Regulatory Environment and Strategic Outlook
NFPA 70 National Electrical Code in the United States, EU Construction Products Regulation with CE marking requirements, and China's GB standards administered by SAMR collectively dictate fire safety ratings, electromagnetic compatibility thresholds, and material composition limits that determine product market access. TIA and ISO standards further segment procurement eligibility by certifying installer competency and system performance tiers. Stakeholders must monitor evolving low-smoke zero-halogen mandates in European jurisdictions and China's dual carbon goals affecting polymer compound specifications.
Market Dynamics
Hyperscale data center buildouts for artificial intelligence training clusters are compressing deployment timelines from 18 months to under 12 months, forcing cabling contractors to pre-certify installation crews and stock regional fiber inventories ahead of signed contracts.
Growth Catalysts
- Single-mode fiber density:AI workloads in United States and China hyperscale facilities are mandating 1728-fiber count cables, pulling demand for MPO-16 and MPO-32 connector ecosystems.
- NFPA 70 National Electrical Code:Updated fire safety ratings for plenum spaces in commercial buildings are accelerating replacement cycles of legacy PVC-jacketed copper installations.
- Power over Ethernet evolution:IEEE 802.3bt Type 4 delivering 90W per port is extending copper utility in smart building retrofits across Germany and Japan.
Market Restraints
- Optical fiber preform supply:Concentration of synthetic quartz crucible manufacturing in Japan and Germany creates bottleneck vulnerability for single-mode fiber production.
- Copper conductor volatility:LME copper price swings above 15% annually compress margin visibility for fixed-bid commercial installation contracts.
- EU Construction Products Regulation:CE marking delays for new low-smoke zero-halogen compounds extend product certification cycles by 8-14 months.
Strategic Opportunities
- India data center corridor:Mumbai-Chennai-Delhi fiber routes remain underbuilt relative to projected AI cloud demand, creating first-mover pathway engineering contracts.
- Edge computing micro-data centers:5G base station fiber backhaul in Germany and Japan requires ruggedized outdoor-rated cabling absent incumbent supplier dominance.
- China dual carbon goals:SAMR mandates on recycled polymer content in cable jackets favor domestic compounders with circular supply chain certifications.
Industry Challenges
- Certified installer scarcity:TIA-568 and ISO/IEC 14763-2 competency requirements outpace vocational training program output in United States and United Kingdom markets.
- Legacy building integration:25-year-old Category 5 copper plant in European commercial real estate conflicts with Power over Ethernet thermal load specifications.
- Multi-standard compliance:Simultaneous pursuit of BICSI, TIA, and ISO certifications fragments quality assurance documentation for multinational installation firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structured Cabling Market |
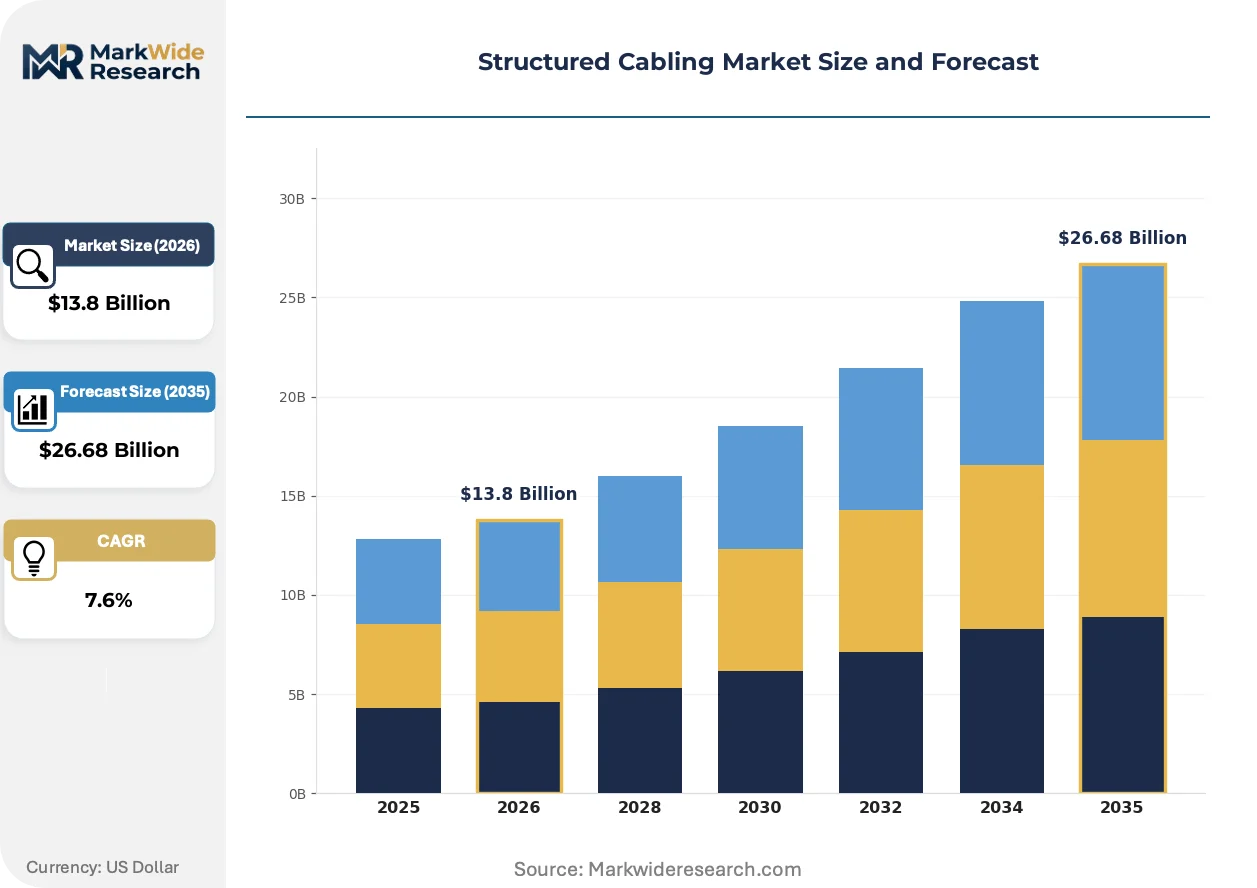
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Copper Cable, Patch Panels, Connectors Installation Method: In-Building, Outdoor, Aerial, Underground End User: Telecommunication Providers, Commercial Enterprises, Data Centers, Residential Application Area: Networking, Voice Communication, Video Surveillance, Building Automation |
| Companies Covered | Corning Incorporated, CommScope Holding Company, Belden Inc., Legrand SA, Nexans, Furukawa Electric Co., Ltd., Schneider Electric, TE Connectivity Ltd., Panduit Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structured Cabling Market Emerging Trajectories
Deployment velocity requirements from AI infrastructure are fragmenting traditional specification hierarchies, with performance certification displacing brand loyalty in contractor procurement decisions.
Single-mode fiber is bifurcating into two performance tiers: ultra-low-loss G.654.E for inter-data center links up to 100km, and bend-insensitive G.657.A2 for intra-facility dense patching. Hyperscale operators in United States and China are specifying G.654.E exclusively for training cluster backbones, compressing demand for intermediate-performance fiber grades. This technology stratification is bifurcating supplier portfolios into premium optical specialists versus commodity fiber converters.
EU Construction Products Regulation fire safety classifications are tightening smoke density and halogen emission thresholds for indoor cable deployments. Manufacturers serving Germany and France must reformulate jacket compounds to meet CPR Class B2ca ratings, eliminating legacy PVC formulations from premium specification tiers. The regulatory pressure is accelerating compounder consolidation as smaller material suppliers lack testing infrastructure for extended fire performance validation.
Specification authority is migrating from general contractors to data center owner-operators with captive engineering teams. Direct procurement of fiber trunks and pre-terminated assemblies is displacing traditional distributor-mediated purchasing in United States hyperscale builds. This channel compression is most visible in Northern Virginia and Dallas-Fort Worth markets, where Meta, Microsoft, and Google facility teams issue material call-offs against master service agreements rather than per-project bids.
Structured Cabling Market Segmentation
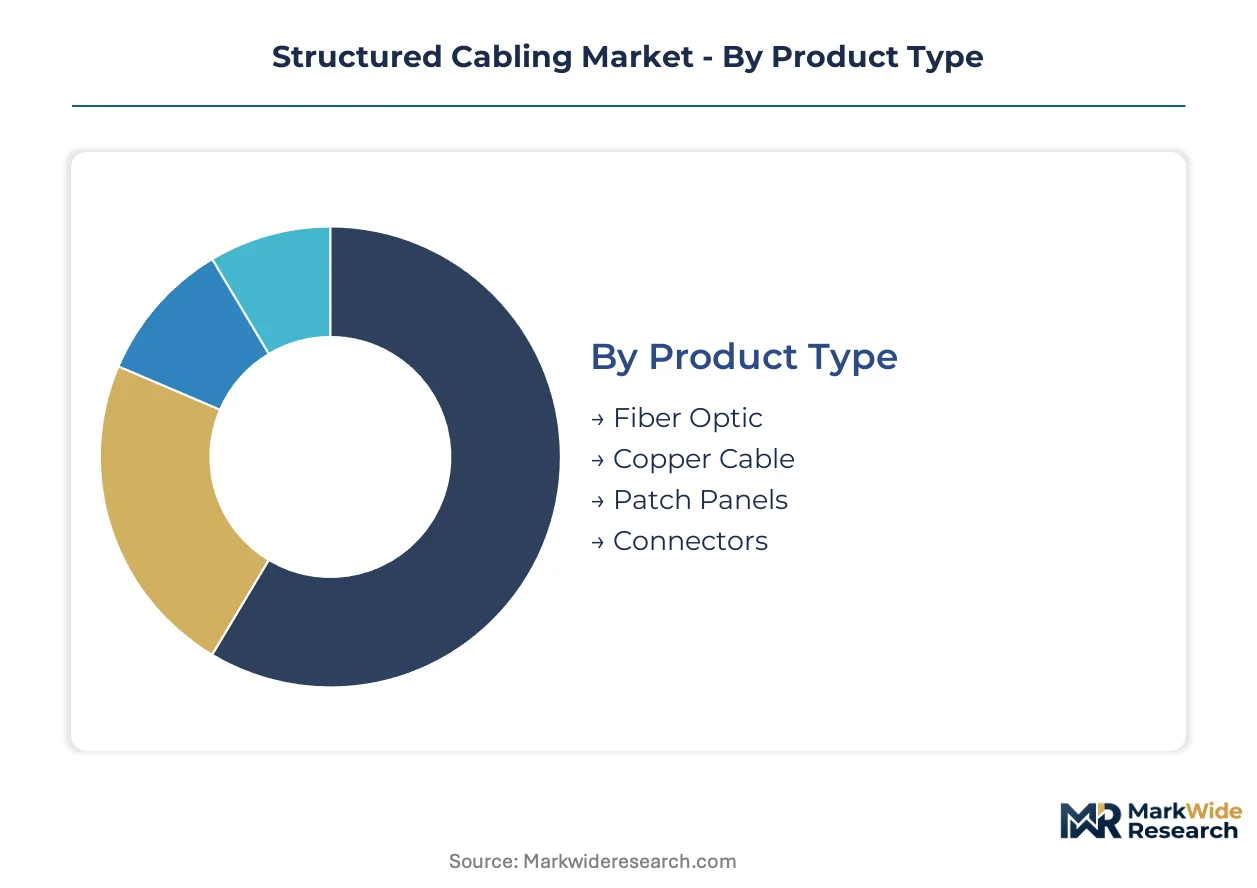
Structured cabling procurement patterns diverge sharply across product technologies and deployment contexts, with AI infrastructure investments redrawing traditional specification hierarchies. Understanding segment-level substitution dynamics reveals where incumbent technologies face displacement versus defensive consolidation.
Product Type:
Fiber optic cable exerts the strongest substitution pressure on legacy copper installations, particularly as hyperscale data centers mandate single-mode fiber for terabit-scale interconnects while Power over Ethernet temporarily extends copper relevance in smart building retrofits.
- Fiber Optic:Single-mode and multimode silica glass fiber elements deliver bandwidth scalability for backbone and horizontal distribution layers. Demand concentrates in United States and China hyperscale facilities deploying 1728-fiber count cables for AI training clusters, with G.654.E ultra-low-loss specifications dominating inter-data center links.
- Copper Cable:Twisted-pair unshielded and shielded copper conductors remain cost-advantaged for short-reach enterprise LANs. IEEE 802.3bt Type 4 delivering 90W per port sustains utility in Germany and Japan smart building retrofits where fiber conversion costs prove prohibitive.
- Patch Panels:Modular termination assemblies enable cross-connect flexibility in telecommunications rooms.
- Connectors:MPO-16 and MPO-32 multifiber push-on interfaces support high-density fiber patching in data center environments.
Copper cable retains volume leadership; fiber optic holds the steepest expansion curve.
Installation Method:
Margin structures vary dramatically by deployment environment, with pathway engineering complexity creating defensive moats for specialized contractors against commodity pricing pressure.
- In-Building:Horizontal and backbone distribution through plenum, riser, and general-purpose pathways within commercial facilities. Densest margin pools accrue to contractors mastering NFPA 70 fire safety compliance and TIA-568 pathway engineering in United States commercial real estate.
- Outdoor:Aerial and direct-buried deployments connecting facilities across campus or metropolitan footprints. Germany and Japan 5G base station fiber backhaul demands ruggedized outdoor-rated cabling where incumbent supplier positions remain unsettled.
- Aerial:Messenger-supported cable strands spanning utility poles or dedicated infrastructure.
- Underground:Conduit and direct-buried methods face utility-scale competition compressing pricing power.
In-Building commands premium pricing; Outdoor offers the most open competitive terrain.
End User:
Specification authority migration from general contractors to captive engineering teams fragments traditional channel structures unevenly across customer categories.
- Data Centers:Hyperscale owner-operators with internal engineering capabilities increasingly bypass distributor networks for direct fiber trunk procurement. Northern Virginia and Dallas-Fort Worth markets exhibit master service agreement call-off patterns against 12-month compressed deployment timelines.
- Telecommunication Providers:Carrier backbone and access network investments drive standardized high-volume fiber deployments.
- Commercial Enterprises:Corporate LAN refresh cycles balance Power over Ethernet thermal loads against legacy Category 5 plant constraints.
- Residential:Multi-dwelling unit fiber-to-the-home deployments lag commercial infrastructure investment intensity.
Data Centers drive technology specification; Commercial Enterprises sustain volume scale.
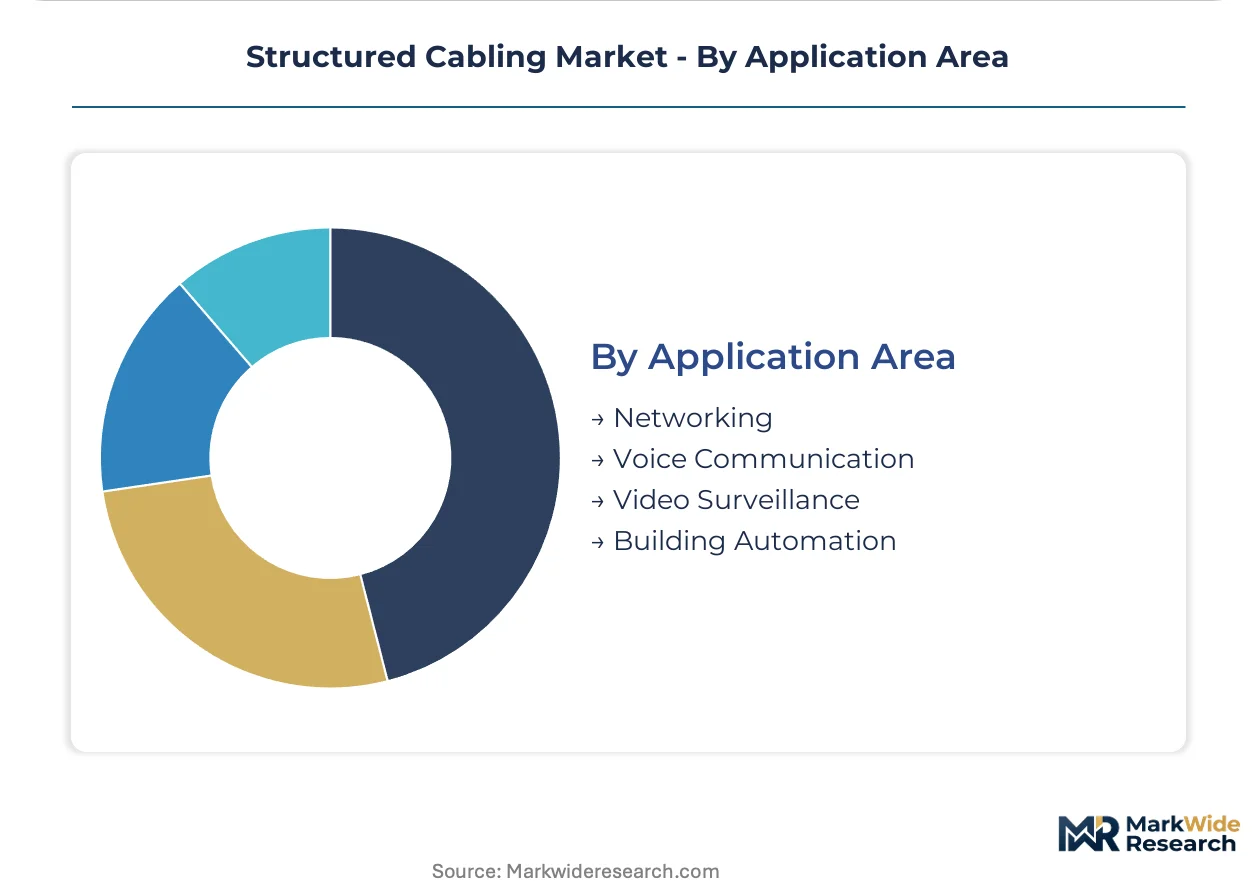
Application Area:
Functional performance requirements stratify procurement criteria, with latency-sensitive workloads commanding distinct material specifications from administrative infrastructure.
- Networking:Data transmission infrastructure supporting enterprise and cloud connectivity. United States hyperscale operators specify bend-insensitive G.657.A2 fiber for intra-facility dense patching where space constraints dominate pathway design.
- Building Automation:Sensor and control system cabling integrates Power over Ethernet with environmental monitoring. Germany's EU Construction Products Regulation low-smoke zero-halogen mandates reshape compound specifications for indoor automation deployments.
- Voice Communication:Traditional telephony infrastructure faces convergence pressure from unified communications over IP networks.
- Video Surveillance:High-definition camera backhaul demands bandwidth scaling beyond legacy coaxial plant capabilities.
Networking anchors technology investment; Building Automation gains regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NFPA 70 National Electrical Code revisions and EU Construction Products Regulation fire safety mandates are accelerating infrastructure replacement cycles across major economies. Data center operators in the United States, Germany, China, India, and Japan are compressing deployment timelines to capture AI-driven capacity expansions.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth are issuing master service agreement call-offs against 12-month compressed deployment timelines. NFPA 70 plenum space fire safety ratings are accelerating replacement of legacy PVC-jacketed copper installations. Ashburn-Loudoun County hosts the densest fiber concentration for AI training cluster backbones.
Germany
EU Construction Products Regulation CPR Class B2ca ratings are eliminating legacy PVC formulations from premium specification tiers. IEEE 802.3bt Type 4 Power over Ethernet sustains copper utility in smart building retrofits where fiber conversion costs prove prohibitive. Frankfurt's data center corridor drives G.654.E ultra-low-loss fiber demand for inter-facility links.
China
SAMR-administered GB standards and dual carbon goals are reshaping polymer compound specifications for cable jackets. Domestic compounders with circular supply chain certifications capture preference for recycled polymer content mandates. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate hyperscale buildouts for AI training infrastructure.
India
Mumbai-Chennai-Delhi fiber routes remain underbuilt relative to projected AI cloud demand, creating first-mover pathway engineering contracts. TRAI infrastructure sharing regulations influence deployment economics for carrier-neutral facilities. Hyderabad and Bengaluru data center parks are attracting pre-certified installation crew investments ahead of signed contracts.
Japan
Synthetic quartz crucible manufacturing concentration creates bottleneck vulnerability for single-mode fiber production serving domestic and export markets. METI industrial standards govern electromagnetic compatibility thresholds for commercial building installations. Tokyo-Osaka corridor 5G base station fiber backhaul demands ruggedized outdoor-rated cabling where supplier positions remain unsettled.
Structured Cabling Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage dimensions. The vendor base organizes around optical fiber manufacturing depth, distributor network scale, and industrial environment specialization. Three archetypes dominate: premium optical specialists with captive preform supply, enterprise-focused distributors with specification authority, and ruggedized cable fabricators serving factory automation. Consolidation pressure favors M&A activity among compounders lacking fire performance testing infrastructure, while strategic partnerships between installers and manufacturers accelerate pre-certification crew deployment.
Among diversified electrical infrastructure conglomerates, Schneider Electric and Legrand SA exemplify scale-driven portfolio breadth across building automation and data center power distribution. Corning Incorporated anchors the premium optical specialist tier through manufacturing depth in silica glass fiber elements. These three entities represent contrasting competitive positions: specification authority through electrical infrastructure integration, versus materials science dominance in high-fiber-count cable production.
| Leading Market Players |
|---|
| Corning Incorporated |
| CommScope Holding Company |
| Belden Inc. |
| Legrand SA |
| Nexans |
| Furukawa Electric Co., Ltd. |
| Schneider Electric |
| TE Connectivity Ltd. |
| Panduit Corp. |
| Others |
Supply Flow & Price Mechanics
Master service agreement call-off structures lock in both fiber trunk supply access and price visibility for United States hyperscale operators compressing deployment timelines below 12 months. This contract pattern shields buyers from LME copper volatility while tethering pricing to ISO/IEC 11801 certification tiers and pre-certified installation crew availability.
Pricing Analysis
Certification level creates the primary spread between TIA-568 accredited installations and non-certified contractor bids. Project-based pricing dominates data center builds, with differentiation driven by fiber count density and plenum-rated fire safety compliance under NFPA 70. Cost compression in copper cable installations is intensifying because legacy PVC-jacketed plant faces accelerated replacement cycles. Commercial enterprises exhibit highest price sensitivity due to fixed LAN refresh budgets, while hyperscale operators prioritize performance certification over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes compound lead time uncertainty for MPO-16 connector assemblies sourced from Chinese manufacturing clusters. Synthetic quartz crucible production concentrates in Japan and Germany, creating single-source vulnerability for single-mode fiber preform supply. Cable jacket polymer compounds draw from petrochemical feedstocks subject to SAMR dual carbon mandates. Distribution runs through manufacturer-direct channels for hyperscale data centers and electrical distributor networks for commercial enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators with captive engineering teams, fragmenting traditional distributor-mediated procurement channels and compressing margin pools for installation contractors without direct manufacturer relationships.
For Market Incumbents: Consolidate compounder partnerships ahead of EU Construction Products Regulation Class B2ca fire safety mandates eliminating legacy PVC formulations. Acquire pre-certified installation crews in India and United States markets to defend against certified installer scarcity. Deepen backward integration into optical fiber preform supply to mitigate synthetic quartz crucible bottleneck exposure.
For New Entrants and Emerging Players: Differentiate on ruggedized outdoor-rated cabling for Germany and Japan 5G base station fiber backhaul where incumbent supplier positions remain unsettled. Target edge computing micro-data center deployments requiring bend-insensitive G.657.A2 fiber for space-constrained pathway engineering. Pursue direct procurement relationships with data center owner-operators bypassing traditional distributor networks.
For Investors and Strategic Acquirers: Regional compounders with circular supply chain certifications represent attractive acquisition targets as China's SAMR recycled polymer mandates reshape jacket material specifications. Long-term viability hinges on fire performance testing infrastructure capable of validating low-smoke zero-halogen formulations across European jurisdictions. Watch for TIA-568 training program output expansion as inflection indicator for installer scarcity resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Crew Deployment | Compresses data center installation timelines below 12 months for AI infrastructure. |
| Backward Integration into Preform Supply | Mitigates synthetic quartz crucible concentration risk in Japan and Germany. |
| Fire Safety Compound Reformulation | Enables EU Construction Products Regulation Class B2ca compliance for premium tier access. |
| Direct Procurement Channel Development | Bypasses distributor networks for hyperscale operator master service agreements. |
| Circular Supply Chain Certification | Captures preference under China's SAMR recycled polymer content mandates. |
Methodological Framework
Operator-level perspectives from data center engineering directors, cabling contractor project managers, electrical distributor procurement leads, and compounder technical R&D heads anchored the qualitative base. Primary interview insights combined with TIA standards documentation, NFPA 70 code revision records, EU Construction Products Regulation certification databases, and SAMR GB standards filings for secondary validation. Bottom-up fiber count deployment estimates triangulated against top-down hyperscale capex disclosures across the analysis window.
Sensitivity analysis tested fiber optic versus copper substitution elasticity, installer wage inflation scenarios, and fire safety regulatory acceleration patterns. Segmentation dimensions modeled include product technology, installation method complexity, end-user specification authority, and regional regulatory cluster. CAGRs derived from deployment timeline compression rates and AI infrastructure investment trajectories. Industry-specific forecast inputs incorporated MPO-16 and MPO-32 connector ecosystem adoption curves alongside Power over Ethernet thermal load specifications.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale data center investment intensity or accelerated EU fire safety mandate timelines would require recalibration. Forecasts reflect assumptions regarding synthetic quartz crucible supply continuity and vocational training program expansion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Mobile Network Optimization Market
Network Technology
Global Network Management Market
Network Technology
Enterprise Routers Market
Network Technology
North America Structured Cabling Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Managed Switches Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Germany Residential Gateway Market
Network Technology
5G CPE Device Market
Network Technology
Europe Private 5G Network Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Private 5G Network Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Wimax Solutions Market
Network Technology
Passive Optical LAN (POL) Market