
 Anti-Arrhythmic Drugs Market | 2026-2036
Anti-Arrhythmic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Arrhythmic Drugs Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing how combination drug-device therapies reach European patients. Pfizer Inc. leverages its manufacturing scale to supply amiodarone across multiple dosage forms globally. Sanofi S.A. anchors its anti-arrhythmic portfolio through established hospital formulary relationships in Western Europe. Bristol-Myers Squibb Company differentiates via its legacy presence in Class IC sodium channel blockers.
Anti-arrhythmic drugs are pharmacological agents that modulate cardiac ion channels to restore normal sinus rhythm, with formulations specified by Vaughan-Williams classification based on electrophysiological mechanism of action. These compounds serve the primary commercial purpose of reducing stroke risk and mortality in patients with sustained ventricular or supraventricular tachyarrhythmias. Class III agents, particularly those targeting potassium channel blockade, command the deepest margin pools due to complex formulation requirements and narrower therapeutic indices. Oral delivery mode dominates prescription volumes for chronic maintenance therapy, while injectable formulations capture acute care settings where rapid bioavailability determines clinical outcomes.
The FDA enforces stringent QT prolongation risk assessments through its Integrated Nonclinical-Clinical QT assessment framework, shaping which candidates advance from Phase II trials. EMA's Committee for Medicinal Products for Human Use applies similar cardiac safety thresholds under ICH E14 guidelines, creating transatlantic harmonization in development costs. Stakeholders must monitor how pharmacovigilance databases flag proarrhythmic signals, as these regulatory actions directly reshape prescribing guidelines and reimbursement decisions.
Market Dynamics
The FDA's Breakthrough Therapy designation pathway is compressing development timelines for novel anti-arrhythmic formulations, forcing incumbent manufacturers to accelerate reformulation cycles or cede first-mover advantage to nimble competitors with differentiated delivery mechanisms.
Growth Catalysts
- Catheter ablation referral networks:Hospital-based electrophysiology programs in the United States are expanding procedural capacity, creating downstream prescription demand for peri-procedural anti-arrhythmic coverage.
- REACH cardiac safety harmonization:The EMA's alignment with ICH E14 guidelines reduces redundant QT assessment costs for sponsors pursuing transatlantic development strategies.
- Amiodarone formulation diversification:Multi-dosage-form manufacturing capabilities enable acute-to-chronic therapy continuity across inpatient and outpatient settings.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for Class III potassium channel blockers clusters among a limited set of contract manufacturers in India and China.
- QT prolongation liability:The FDA's Integrated Nonclinical-Clinical QT assessment framework eliminates candidates with even marginal torsade de pointes risk before Phase III entry.
- Generic substitution pressure:Patent expirations on legacy sodium channel blockers enable pharmacy-level therapeutic substitution without prescriber consultation.
Strategic Opportunities
- Combination drug-device therapies:CE marking under the EU Medical Device Regulation creates a regulatory pathway for integrated anti-arrhythmic-eluting catheter systems in Western Europe.
- Pediatric arrhythmia indications:Orphan drug incentives for rare congenital channelopathies offer extended exclusivity periods with reduced trial enrollment requirements.
- Remote patient monitoring integration:Wearable ECG patch data streams enable real-world efficacy validation that supports label expansion and payer negotiations.
Industry Challenges
- Electrophysiologist training bottlenecks:Fellowship program capacity constraints limit the pool of specialists qualified to manage complex anti-arrhythmic titration protocols.
- Pharmacovigilance signal management:Proarrhythmic event clustering in FAERS and EudraVigilance databases triggers label restrictions that reshape prescribing guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Arrhythmic Drugs Market |
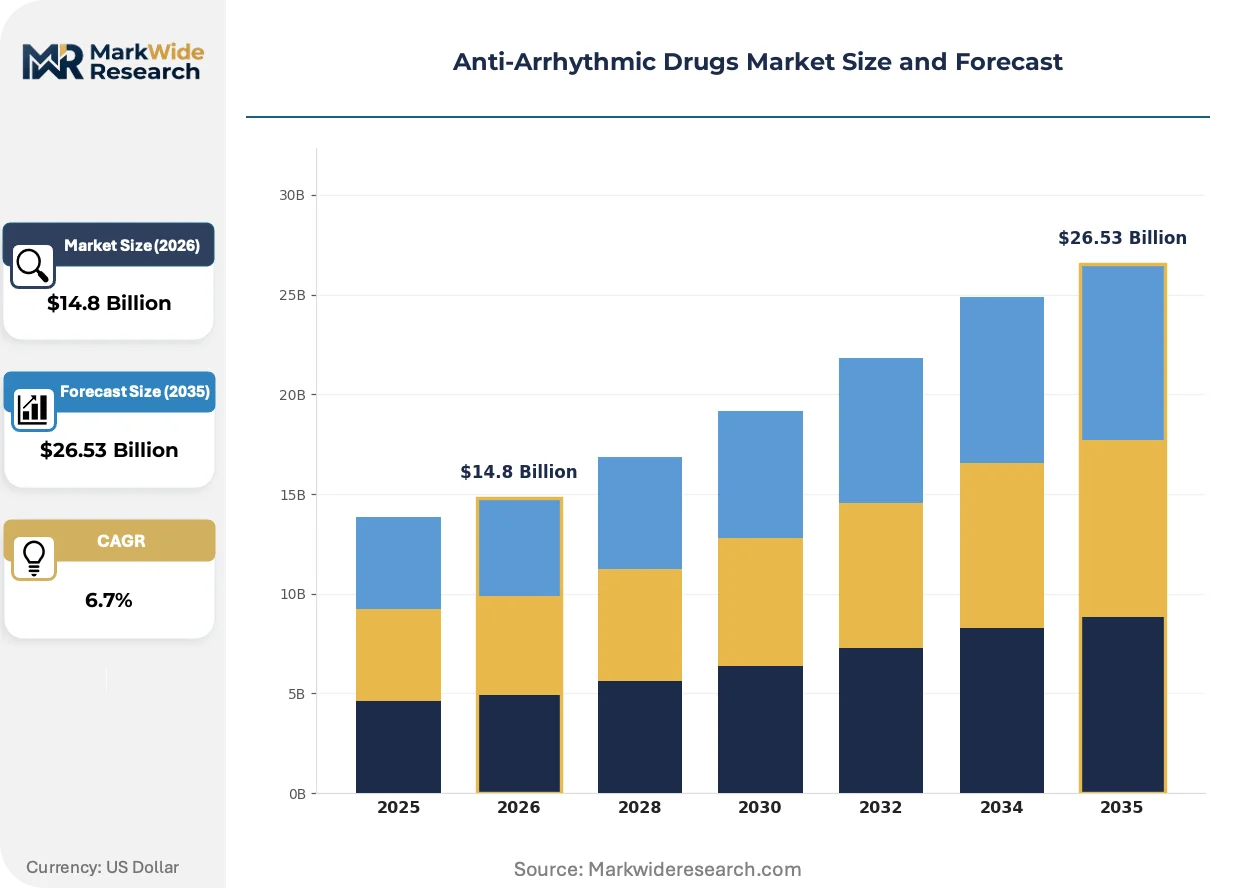
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class IA, Class IB, Class IC, Class III End User: Cardiology Centers, Hospitals, Clinics, Homecare Delivery Mode: Oral, Injectable, Transdermal, Inhalation Therapy Area: Atrial Fibrillation, Ventricular Tachycardia, Supraventricular Tachycardia, Other Conditions |
| Companies Covered | Pfizer Inc., Sanofi S.A., Bristol-Myers Squibb Company, Viatris Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Bayer AG, GlaxoSmithKline plc, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Arrhythmic Drugs Market Strategic Shifts
Cardiac ion channel pharmacology is undergoing a platform shift toward precision electrophysiology, where patient-specific arrhythmia substrate profiling determines agent selection rather than empirical Vaughan-Williams classification.
Microsphere-based extended-release injectable formulations are fragmenting the acute care market for ventricular tachyarrhythmia termination. Emergency medicine departments in tertiary hospitals are adopting these depot systems to reduce nursing burden and dosing errors. The technology is fragmenting traditional IV push protocols into protocolized loading sequences that require specialized pharmacy compounding infrastructure.
The FDA's Integrated Nonclinical-Clinical QT assessment framework is tightening cardiac safety thresholds for all new molecular entities with systemic exposure. Sponsors now conduct thorough QT studies earlier in development, increasing Phase II attrition but reducing late-stage failure costs. Small-molecule anti-arrhythmic programs with hERG channel activity are most affected, pivoting toward structural cardiac modeling to de-risk candidates before human dosing.
Hospital formulary committees are consolidating anti-arrhythmic purchasing through therapeutic class reviews that favor agents with bundled electrophysiology service contracts. Integrated delivery networks in the United States are replacing individual physician preference items with system-wide protocols tied to ablation volume commitments. This concentration is most visible in Medicare Advantage–dominated markets where total cost of care contracts align pharmacy and procedural spending.
Anti-Arrhythmic Drugs Market Segmentation
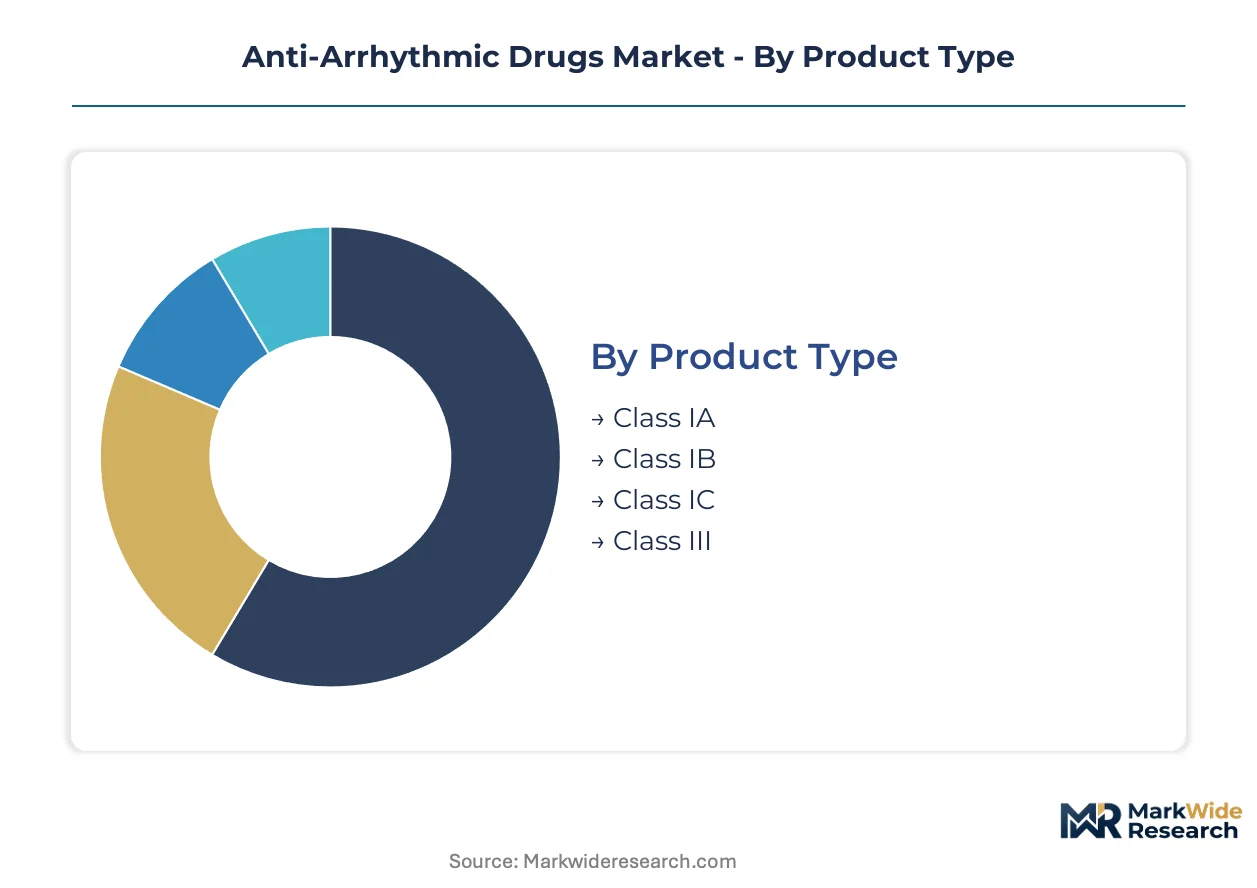
Segmentation in anti-arrhythmic drugs determines reimbursement pathways, formulary placement, and regulatory scrutiny intensity. Vaughan-Williams classification shapes clinical trial design, while delivery mode dictates manufacturing complexity and margin structure.
Product Type:
FDA's Integrated Nonclinical-Clinical QT assessment framework applies differential safety thresholds across electrophysiological classes, elevating development costs for hERG-active candidates.
- Class IA:Sodium channel blockers with intermediate kinetics prolong repolarization variably. Demand concentrates in hospital emergency departments managing acute atrial flutter where rapid cardioversion is required. QT prolongation liability limits outpatient expansion despite generic price erosion.
- Class III:Potassium channel blockades command premium positioning due to complex formulation requirements and narrower therapeutic indices. Oral amiodarone dominates maintenance therapy in United States Medicare populations with recurrent atrial fibrillation post-ablation.
- Class IB:Rapid sodium channel dissociation kinetics suit acute ventricular arrhythmia termination in coronary care units.
- Class IC:Marked conduction slowing effects restrict use to structurally normal hearts with supraventricular tachycardia.
Established volume favors Class III; emerging adoption favors Class IC precision indications.
End User:
Procurement authority concentrates with integrated delivery networks consolidating purchasing across inpatient and outpatient settings.
- Hospitals:Tertiary medical centers anchor acute anti-arrhythmic consumption through emergency department and coronary care unit formularies. Injectable loading protocols for ventricular tachycardia termination require 24-hour pharmacy coverage and telemetry infrastructure that smaller facilities cannot replicate.
- Cardiology Centers:Specialized electrophysiology programs drive peri-procedural anti-arrhythmic prescribing tied to ablation volume commitments. United States-based centers with Medicare Advantage contracts bundle drug costs into procedural reimbursement, shifting margin capture toward integrated service models.
- Clinics:Community-based cardiology practices manage chronic atrial fibrillation with oral agents under protocolized dosing algorithms.
- Homecare:Infusion nursing services administer outpatient IV loading for patients with refractory arrhythmias and transportation barriers.
Margin capture concentrates in Cardiology Centers; prescription volume concentrates in Hospitals.
Delivery Mode:
Manufacturing complexity scales inversely with patient self-administration capability, creating three distinct competitive arenas.
- Injectable:IV push and infusion protocols dominate acute care where bioavailability determines mortality outcomes. Microsphere-based extended-release depot formulations are fragmenting traditional nursing protocols in United States tertiary emergency departments.
- Oral:Tablet and capsule formulations sustain chronic maintenance therapy volumes across aging demographics. Loading dose regimens with narrow therapeutic indices require specialized pharmacy consultation that retail chains increasingly provide.
- Transdermal:Patch-based delivery remains investigational for anti-arrhythmic applications due to skin permeability limitations with polar compounds.
- Inhalation:Pulmonary delivery routes target ultra-rapid systemic absorption for pre-hospital arrhythmia termination.
Revenue stability favors Oral; technology differentiation favors Injectable.
Therapy Area:
Clinical trial endpoints and regulatory pathways diverge sharply between atrial and ventricular indications.
- Atrial Fibrillation:The most prevalent sustained arrhythmia drives chronic prescription volumes and catheter ablation referral networks. United States-based electrophysiology programs expand procedural capacity, creating downstream demand for peri-procedural anti-arrhythmic coverage and rhythm control maintenance.
- Ventricular Tachycardia:Life-threatening substrate commands premium pricing for acute termination agents despite smaller addressable populations. Implantable cardioverter-defibrillator back-up requirements shape prescribing patterns in post-MI populations.
- Supraventricular Tachycardia:Younger patient demographics and curative ablation rates limit chronic drug exposure.
- Other Conditions:Rare congenital channelopathies and drug-induced arrhythmias qualify for orphan drug incentives with reduced enrollment requirements.
Commercial scale favors Atrial Fibrillation; unmet need intensity favors Ventricular Tachycardia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Breakthrough Therapy designation accelerates novel anti-arrhythmic access in the United States, while EMA's MDR pathway reorganizes combination drug-device approvals across Western Europe. National reimbursement policies and catheter ablation infrastructure determine prescription concentration.
United States
Medicare Advantage contracts bundle anti-arrhythmic costs into procedural reimbursement across electrophysiology networks. The FDA enforces QT prolongation assessments through ICH E14-aligned frameworks that elevate cardiac safety thresholds. Cleveland Clinic and Mayo Clinic anchor tertiary electrophysiology capacity in Ohio and Minnesota respectively.
Germany
Hospital formulary committees consolidate purchasing through therapeutic class reviews favoring bundled service contracts. EMA's Committee for Medicinal Products for Human Use applies stringent proarrhythmic signal thresholds under centralized marketing authorization. Berlin and Munich host concentration of contract manufacturing for potassium channel blocker APIs.
Japan
PMDA's Sakigake designation pathway compresses review timelines for innovative anti-arrhythmic formulations. METI's pharmaceutical pricing reforms adjust reimbursement every two years based on therapeutic value assessments. Osaka-Kobe pharmaceutical cluster sustains formulation R&D for extended-release injectable microspheres.
India
CDSCO's accelerated approval pathway for orphan indications targets rare congenital channelopathies with reduced enrollment requirements. PLI scheme incentives for active pharmaceutical ingredients expand domestic manufacturing of Class III blocker precursors. Hyderabad and Ahmedabad anchor contract synthesis capacity for hERG-targeting small molecules.
Switzerland
Swissmedic's reliance recognition procedure fast-tracks approvals for agents already authorized through EMA centralized procedures. Basel's pharmaceutical corridor concentrates headquarters operations for global anti-arrhythmic portfolios. Geneva hosts specialized electrophysiology referral centers serving cross-border French and Italian patient flows.
Anti-Arrhythmic Drugs Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with legacy cardiovascular franchises. Tiered competitive structure separates global manufacturers with multi-dosage-form capabilities from regional generic specialists. Strategic archetypes include hospital formulary incumbents, API-integrated formulation developers, and electrophysiology service bundlers. Dominant competitive moves encompass therapeutic class consolidation through formulary committee capture and geographic expansion via regulatory reliance pathways.
Within the diversified pharmaceutical tier, Pfizer Inc. and Sanofi S.A. occupy positions as hospital formulary anchors with established electrophysiology service relationships. Bristol-Myers Squibb Company exemplifies the legacy Class IC specialist archetype, while Novartis AG and Bayer AG sit within the cardiovascular portfolio diversification segment. These entities represent the competitive concentration around sodium and potassium channel modulation expertise.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi S.A. |
| Bristol-Myers Squibb Company |
| Viatris Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with Indian and Chinese API manufacturers lock in multi-year supply access for Class III potassium channel blockers while capping price escalation through raw material indexation clauses tied to acetone and pyridine derivatives. Hospital formulary committees in the United States leverage these contracted volumes to negotiate bundled electrophysiology service pricing that compresses per-dose margins for acute injectable formulations.
Pricing Analysis
Cost-plus contracts with acetone and pyridine derivative indexation dominate active pharmaceutical ingredient procurement for potassium channel blockers. Three-tier pricing structure across premium patented agents, standard branded generics, and economy unbranded generics separates margin pools by therapeutic index complexity and formulation sophistication. Pricing pressure stems from Medicare Advantage bundled reimbursement models that fold drug costs into procedural episode payments. Community cardiology clinics exhibit highest price sensitivity due to thin operating margins and pharmacy benefit manager rebate clawback exposure.
Supply Chain Analysis
Inventory buffers for hERG-targeting small molecule precursors stretch to six months given regulatory qualification requirements for alternative suppliers. API synthesis concentrates in India, China, and Switzerland, with Hyderabad and Ahmedabad anchoring contract manufacturing for amiodarone intermediates while Basel hosts formulation R&D for extended-release microspheres. Supply chain risk centers on single-source dependency for high-purity potassium iodide used in amiodarone synthesis. Distribution runs through specialized pharmaceutical wholesalers with cold-chain capabilities for temperature-sensitive injectable depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation across United States electrophysiology markets, with three national systems now controlling formulary access for over forty percent of Medicare Advantage arrhythmia procedures.
For Market Incumbents: Secure backward integration into Indian API manufacturing through equity stakes or long-term offtake guarantees to defend against generic substitution pressure on legacy sodium channel blockers. Lock in exclusive electrophysiology service bundling with Medicare Advantage–dominated health systems before catheter ablation volume commitments crystallize competitor relationships. Monitor FDA pharmacovigilance signals for proarrhythmic clustering that triggers label restrictions reshaping prescribing guidelines. For New Entrants and Emerging Players: Lead with pediatric congenital channelopathy indications where orphan drug incentives offer extended exclusivity and reduced trial enrollment requirements against entrenched adult atrial fibrillation competition. Target Western European cardiology centers pursuing CE-marked combination drug-device therapies under EU Medical Device Regulation pathways. Deploy real-world evidence partnerships with wearable ECG patch manufacturers to bypass traditional Phase III cost barriers. For Investors and Strategic Acquirers: Electrophysiology service bundlers with captive formulary access represent the most defensible acquisition archetype in a market shifting toward total cost of care contracting. Frame five-to-ten year viability around catheter ablation procedural growth sustaining peri-procedural drug demand rather than chronic oral maintenance exposure. Watch FDA Breakthrough Therapy designation awards as inflection signals for pipeline candidates capable of compressing incumbent reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation accelerates novel anti-arrhythmic access ahead of standard review timelines. |
| Backward Integration | Equity stakes in Indian API manufacturers secure supply continuity for potassium channel blocker precursors. |
| Hospital System Partnership | Bundled electrophysiology service contracts with Medicare Advantage networks lock in formulary placement. |
| Manufacturing Scale-Up | Multi-dosage-form capabilities enable acute-to-chronic therapy continuity across inpatient and outpatient settings. |
| Pipeline Diversification | Pediatric congenital channelopathy programs exploit orphan drug incentives with reduced enrollment requirements. |
Study Parameters
A spread of perspectives from electrophysiology fellowship directors, hospital formulary pharmacists, regulatory affairs leads at cardiovascular drug developers, and Medicare Advantage contracting officers converged on the working assumptions shaping this analysis. Primary interview insights triangulated against FDA Integrated Nonclinical-Clinical QT assessment filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS Medicare Part D claims extracts. Bottom-up prescription volume modeling and top-down therapeutic class expenditure reconciliation validated segmentation splits across Vaughan-Williams classes and delivery modes.
Segmentation dimensions modeled include electrophysiological mechanism class, administration route, patient age stratum, and regional regulatory cluster across the projection horizon. CAGRs derived from spline-interpolated annual growth rates applied to base-year prescription volumes adjusted for patent expiration cliffs and generic entry timing. Forecast inputs incorporated catheter ablation procedural growth trajectories, electrophysiologist fellowship graduation rates, and pharmacovigilance signal frequency thresholds from FAERS and EudraVigilance databases.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage penetration, stable FDA cardiac safety thresholds, or intact Indian API export capacity would require recalibration. Forecasts reflect documented assumptions regarding electrophysiology program expansion and generic substitution elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Small Volume Parenteral Market