
 Hydroxycarbamide Market | 2026-2036
Hydroxycarbamide Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxycarbamide Market Analysis
Oncology procurement departments is reorganizing purchasing priorities toward oral cytotoxic agents that reduce infusion center burden. Bristol Myers Squibb sustains manufacturing scale across its hydroxycarbamide portfolio through vertically integrated active pharmaceutical ingredient production. Teva Pharmaceutical Industries Ltd. competes on cost positioning in generic hydroxycarbamide tablets across North American and European hospital contracts. Dr. Reddy's Laboratories Ltd. anchors supply to emerging markets through differentiated packaging and stability profiles suited to tropical distribution.
Hydroxycarbamide, also known as hydroxyurea, is a synthetic antimetabolite with the molecular formula CH4N2O2 that inhibits ribonucleotide reductase and disrupts DNA synthesis in rapidly dividing cells. The compound serves primarily as a disease-modifying therapy for sickle cell disease and as a cytoreductive agent in myeloproliferative neoplasms, with dosing typically calibrated to patient weight and blood count monitoring. Tablet formulations dominate current volume due to established bioequivalence data and patient familiarity, while oral solutions represent the fastest-expanding category as pediatric sickle cell programs expand home administration protocols. Therapy area segmentation shows sickle cell disease commanding the largest patient base in the United States, whereas myeloproliferative disorder applications sustain higher per-patient value in European specialist settings.
The US FDA governs hydroxycarbamide approval pathways through its Office of Hematology and Oncology Products, with orphan drug designations accelerating pediatric sickle cell indications. The European Medicines Agency enforces Good Manufacturing Practice standards that constrain API sourcing to qualified suppliers, while REACH chemical registration requirements affect hydroxycarbamide import volumes into EU member states. Stakeholders must monitor evolving pharmacovigilance obligations and biosimilar substitution policies that could reshape reimbursement and prescribing dynamics for oral cytotoxic therapies.
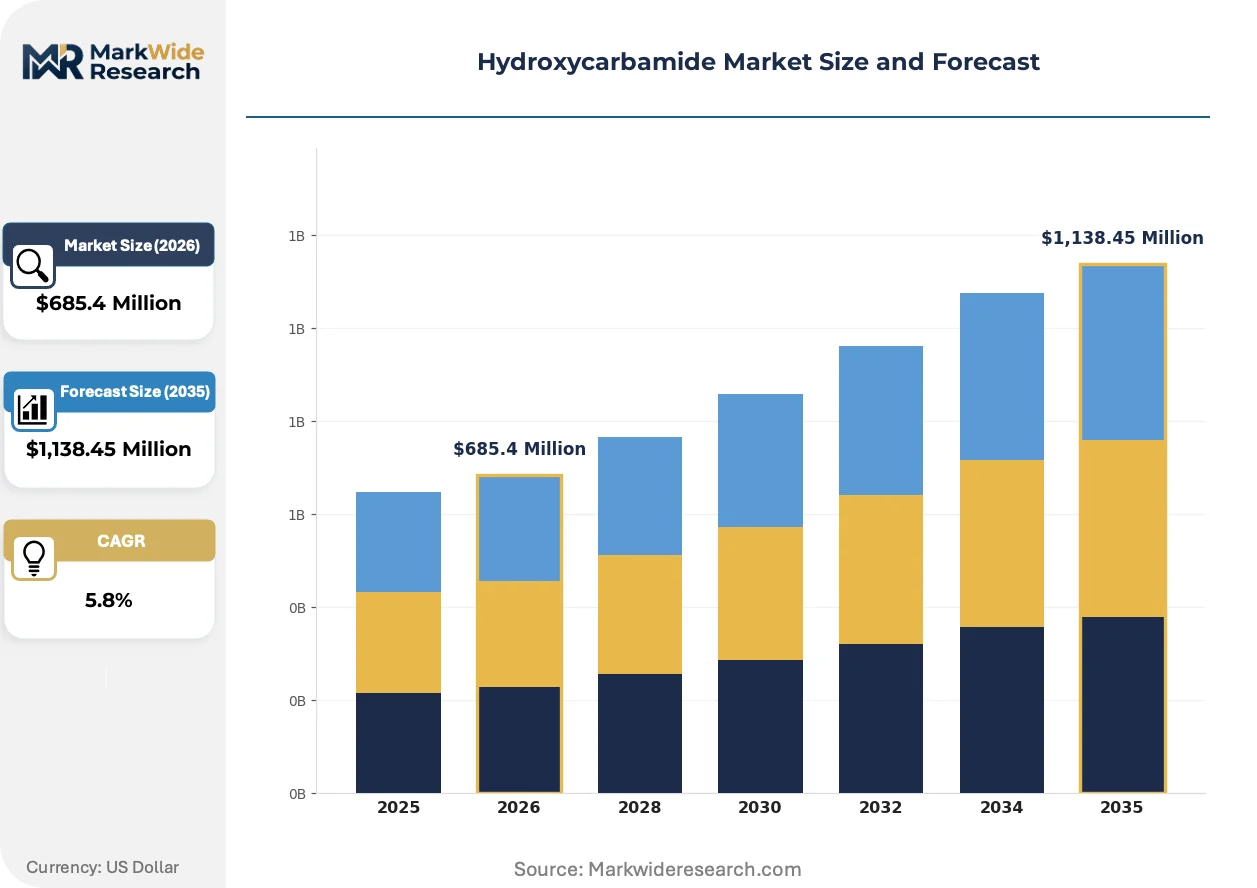
Market Dynamics
FDA orphan drug incentives and accelerated approval pathways for hematologic therapies are compressing commercialization timelines and reshaping how manufacturers prioritize pediatric sickle cell formulations over adult oncology indications.
Growth Catalysts
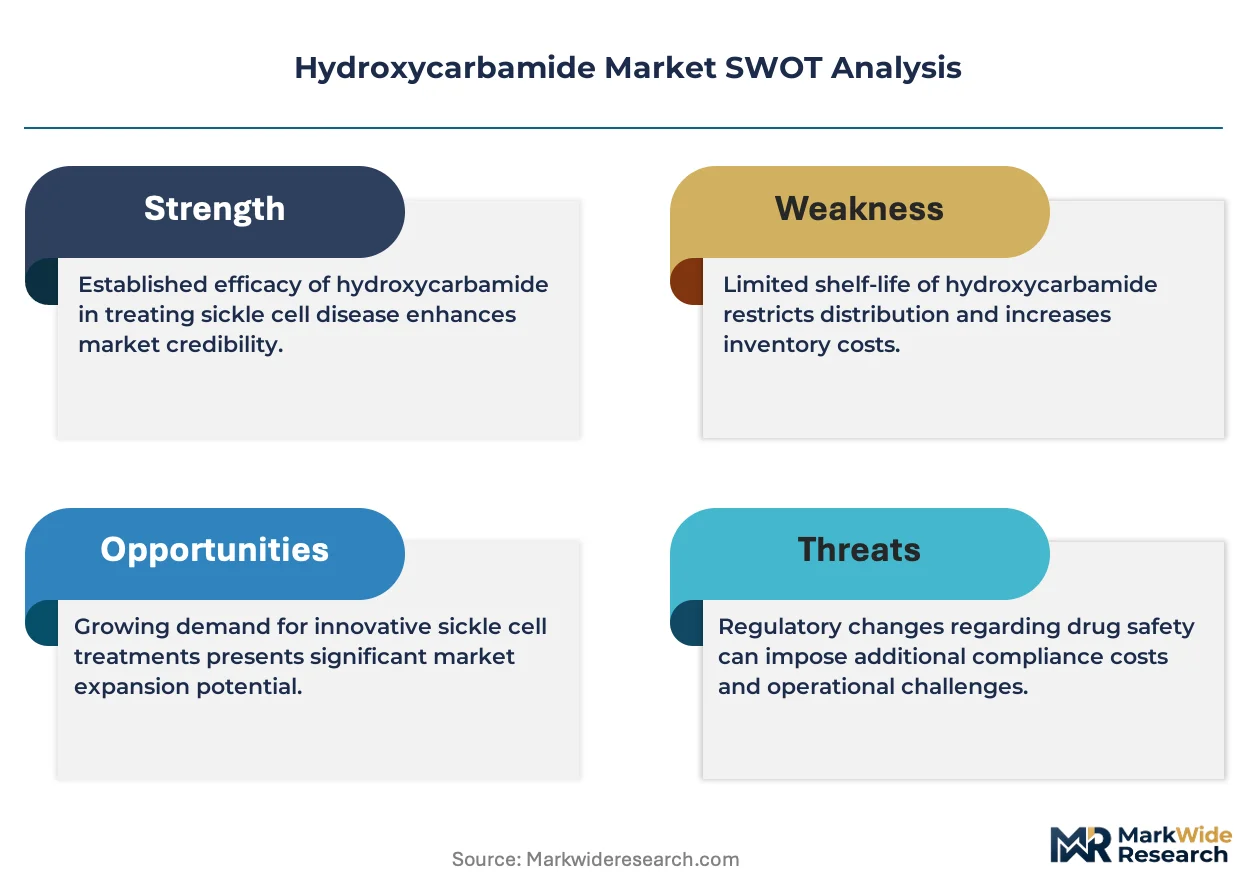
- Orphan Drug Act incentives:The FDA's tax credits and seven-year exclusivity provisions accelerate pediatric sickle cell development programs. Manufacturers prioritize these indications over mature oncology markets.
- Home administration protocols:Pediatric hematology clinics are expanding oral solution dispensing to reduce infusion center burden. This shift drives formulation diversification and patient adherence improvements.
- Sickle cell disease prevalence:United States patient registries show sustained diagnostic expansion. Specialist prescribing networks and hospital formulary adoption concentrate demand in high-volume treatment centers.
Market Restraints
- API sourcing concentration:European EMA Good Manufacturing Practice standards constrain qualified suppliers to a narrow base of vertically integrated manufacturers. Single-source dependencies create vulnerability.
- REACH chemical registration:EU import volumes face documentation burdens and substance evaluation timelines. Registration costs disproportionately affect smaller generic entrants.
- Substitution by gene therapies:Emerging CRISPR-based sickle cell treatments threaten long-term hydroxycarbamide maintenance protocols. Payers are already conditioning reimbursement on prior authorization requirements.
Strategic Opportunities
- Sub-Saharan Africa penetration:Nigeria and Democratic Republic of Congo present underpenetrated sickle cell populations with limited access to disease-modifying therapy. Differentiated heat-stable packaging addresses tropical distribution gaps.
- Myeloproliferative neoplasm expansion:European specialist settings sustain higher per-patient value applications. Cytoreductive protocols in polycythemia vera represent underserved dosing optimization needs.
- Pharmacovigilance data monetization:Long-term safety databases from sickle cell registries create real-world evidence assets. Payers and regulators value these datasets for label expansion negotiations.
Industry Challenges
- Specialized hematology pharmacist scarcity:Dose titration protocols require expertise in myelosuppression monitoring. Training pipelines have not kept pace with expanding sickle cell program volumes.
- Bioequivalence study complexity:Oral solution formulations face dissolution profile variability challenges. Generic sponsors struggle with reference product matching for pediatric bioequivalence trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxycarbamide Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable Forms, Oral Solutions Therapy Area: Sickle Cell Disease, Myeloproliferative Disorders, Thalassemia, Cancer Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare Settings, Research Institutions |
| Companies Covered | Ciplia Limited, Hikma Pharmaceuticals PLC, Bristol Myers Squibb, Qilu Pharmaceutical, Beijing Jialin Pharma, Teva Pharmaceutical Industries Ltd., Taj Pharmaceuticals Ltd., Dr. Reddy’s Laboratories Ltd., Zydus Lifesciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxycarbamide Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape how hydroxycarbamide reaches patients, with oral solutions displacing tablets in pediatric protocols and real-world evidence requirements tightening across jurisdictions.
Oral solution manufacturing is fragmenting established tablet dominance in pediatric sickle cell care. Compounding pharmacies and specialty manufacturers are scaling liquid production to support home administration protocols. Hospital formularies are splitting procurement between solid and liquid presentations based on patient age stratification.
EMA pharmacovigilance obligations are tightening post-market surveillance requirements for cytotoxic therapies. Periodic safety update reports now mandate real-world utilization data from national registries. Generic sponsors in Germany and France are investing in patient support programs to satisfy these documentation burdens.
Specialty pharmacy distribution is capturing sickle cell dispensing from traditional hospital outpatient pharmacies. CVS Specialty and Accredo are building dedicated hematology teams to manage prior authorization and adherence monitoring. United States Medicaid programs are increasingly mandating specialty pharmacy lock-in for oral oncology agents.
Hydroxycarbamide Market Segmentation
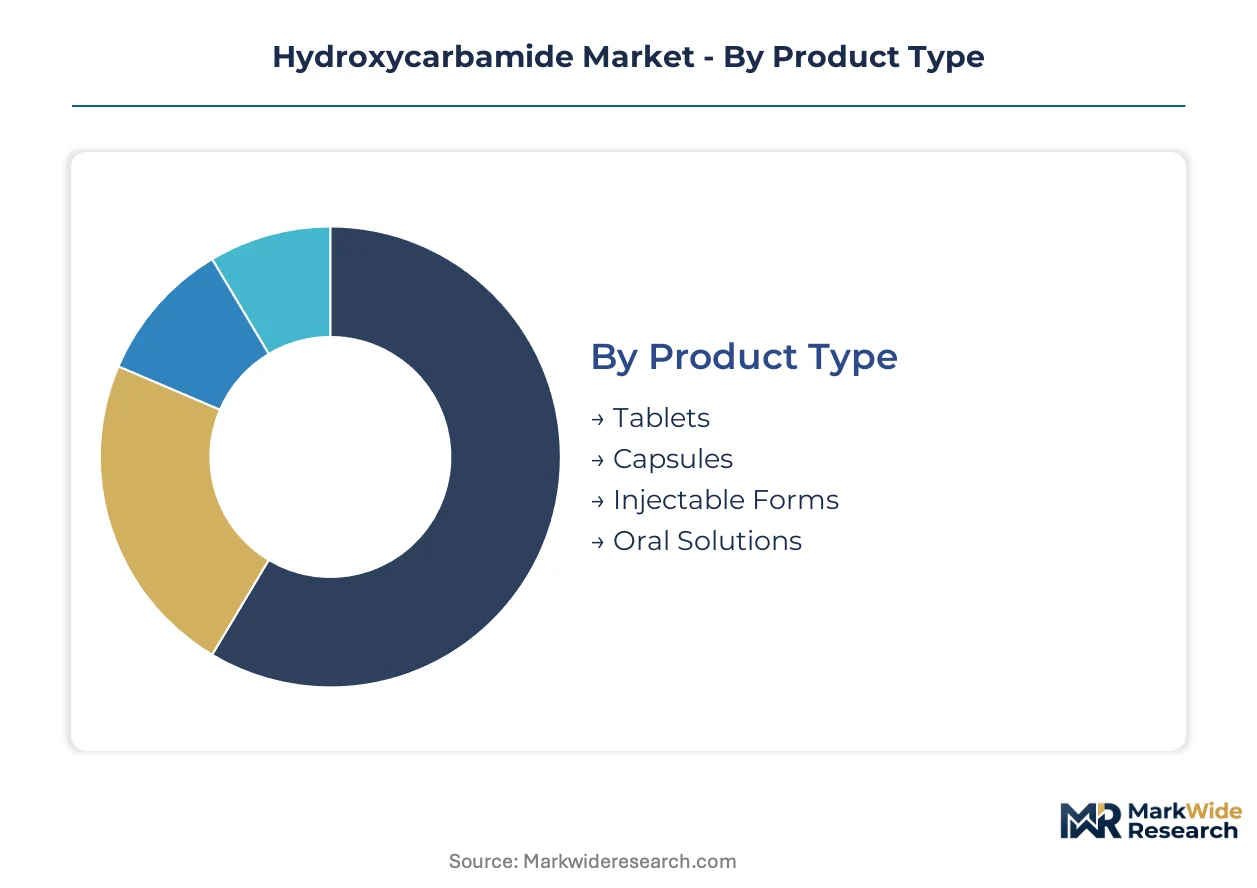
Hydroxycarbamide demand fragments across formulation types, therapy areas, and care settings that each carry distinct regulatory pathways and margin profiles. Understanding these segment boundaries clarifies where manufacturers must build distinct capabilities versus where scale economies apply.
Product Type:
Domestic manufacturing dominates tablet and capsule supply chains in the United States and European Union, while oral solutions and injectable forms rely more heavily on export-oriented production from Indian and Chinese API hubs.
- Tablets:Compressed solid dosage forms containing hydroxycarbamide with established dissolution profiles and bioequivalence documentation. Demand concentrates in United States hospital formularies where sickle cell disease protocols favor weight-based titration familiarity. Manufacturing scale at Bristol Myers Squibb and Teva anchors supply security.
- Oral Solutions:Liquid formulations enabling precise pediatric dosing through measurable volume administration. Pediatric hematology clinics in the United States are expanding home administration programs fastest, driving formulation diversification. Heat-stable packaging variants address tropical distribution gaps in emerging markets.
- Capsules:Gelatin-shell presentations offering taste masking and moisture protection. European EMA stability requirements favor these for myeloproliferative neoplasm maintenance therapy.
- Injectable Forms:Sterile parenteral preparations for inpatient cytoreductive protocols. Hospital procurement in Germany and France concentrates demand in academic medical centers with compounding pharmacy capabilities.
Tablets hold the largest share; momentum sits with oral solutions.
Therapy Area:
Cost tier differentiation separates chronic disease-modifying applications from acute cytoreductive protocols, with per-patient value varying substantially across indications.
- Sickle Cell Disease:Chronic fetal hemoglobin induction therapy requiring lifelong administration with myelosuppression monitoring. United States patient registries drive the largest addressable population, with FDA orphan drug incentives compressing development timelines for pediatric formulations.
- Myeloproliferative Disorders:Cytoreductive management of polycythemia vera and essential thrombocythemia with higher per-patient value in European specialist settings. EMA pharmacovigilance obligations tighten post-market surveillance for these long-duration protocols.
- Thalassemia:Transfusion-dependent patient management with hydroxycarbamide as adjunctive therapy. Mediterranean basin countries including Italy and Greece concentrate diagnostic prevalence.
- Cancer:Adjunctive use in solid tumor and hematologic malignancy protocols. Declining share as targeted therapies displace cytotoxic maintenance regimens.
Sickle cell disease commands the largest patient base; myeloproliferative disorders sustain premium pricing.
Administration Route:
Volume concentration follows patient age stratification, with oral routes dominating pediatric populations and parenteral forms capturing inpatient acute care.
- Oral:Swallowed tablets, capsules, or solutions enabling outpatient self-administration. Homecare protocols in the United States Medicaid system drive volume concentration.
- Intravenous:Direct vascular delivery for hospitalized patients with acute complications or nil-per-os status. Academic medical centers in France and Germany anchor demand.
- Subcutaneous:Tissue depot administration for patients with compromised gastrointestinal absorption. Limited niche in palliative care settings.
- Intramuscular:Skeletal muscle injection for rapid systemic exposure. Rarely utilized outside emergency department bridging protocols.
Oral administration holds the largest share; intravenous maintains critical infrastructure role.
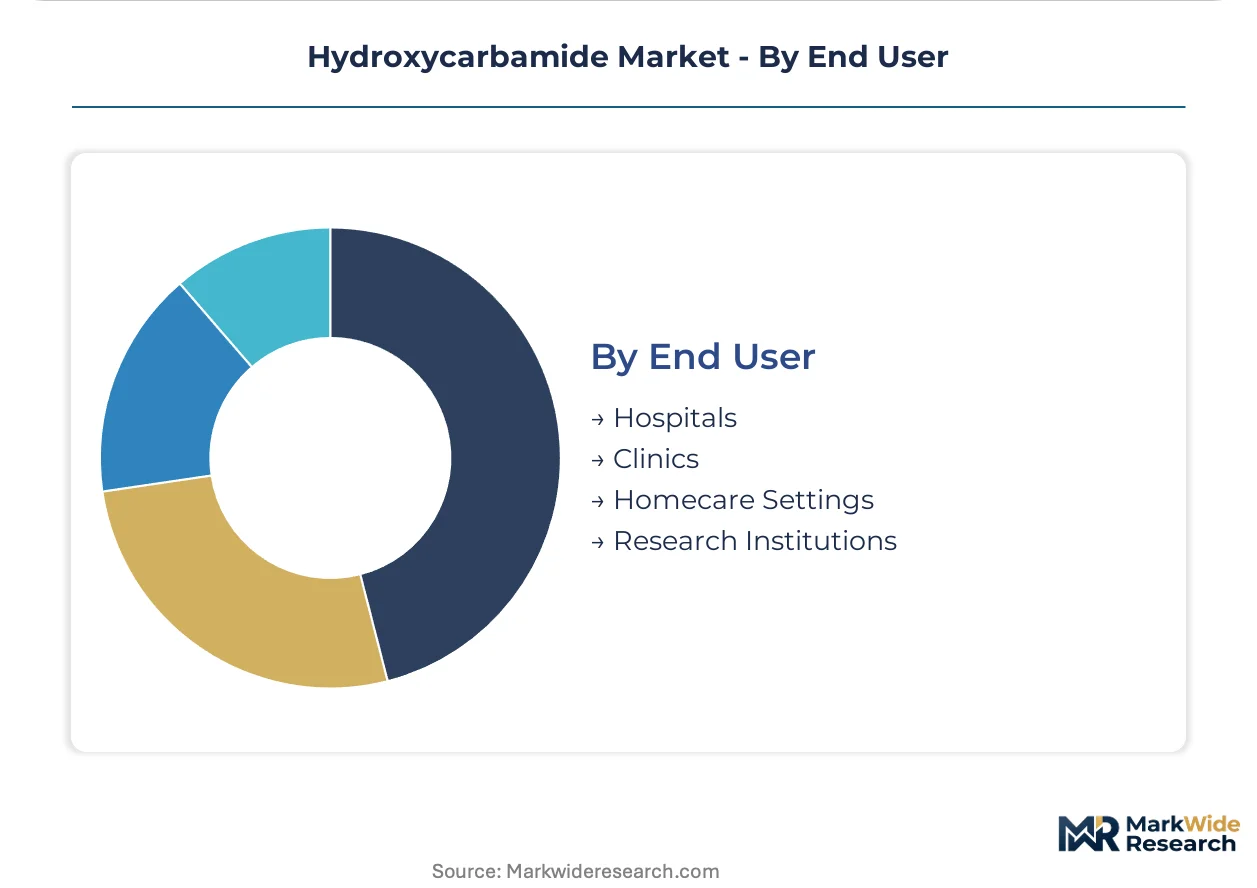
End User:
Customer type fragmentation reflects care setting reimbursement differentiation, with hospital outpatient departments historically dominating but specialty pharmacy channels gaining share.
- Hospitals:Inpatient and outpatient departments managing acute sickle cell complications and initiating chronic therapy. United States 340B program pricing shapes procurement economics.
- Clinics:Dedicated hematology and pediatric specialty practices conducting dose titration and monitoring. Nurse practitioner scope expansion enables protocol delegation.
- Homecare Settings:Patient residence administration supported by visiting nursing and specialty pharmacy distribution. United States Medicaid lock-in mandates accelerate channel shift.
- Research Institutions:Academic medical centers conducting clinical trials and compassionate use protocols. FDA expanded access programs concentrate investigative demand.
Hospitals hold the largest share; homecare settings are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for hydroxycarbamide concentrates in India and China, with formulation finishing and regulatory dossier preparation anchored in the United States and Western Europe. Patient access patterns diverge sharply between mature markets with established sickle cell protocols and emerging regions where diagnostic infrastructure limits therapy initiation.
United States
Sickle cell disease patient registries drive the world's largest addressable population for hydroxycarbamide maintenance therapy. The FDA's Office of Hematology and Oncology Products administers orphan drug incentives that compress pediatric formulation development timelines. Specialist prescribing networks in Atlanta, Baltimore, and Memphis anchor hospital formulary adoption for disease-modifying protocols.
Germany
Myeloproliferative neoplasm applications sustain premium per-patient value in academic hematology centers across Bavaria and North Rhine-Westphalia. The Federal Institute for Drugs and Medical Devices enforces EMA pharmacovigilance obligations that tighten post-market surveillance documentation. Heidelberg and Berlin medical centers concentrate compassionate use protocols and bioequivalence study infrastructure.
India
Thalassemia and sickle cell disease burden in Maharashtra and Gujarat drives demand for heat-stable oral formulations suited to tropical distribution. The Central Drugs Standard Control Organization regulates manufacturing facility inspections and export license issuance. Hyderabad and Mumbai anchor API production clusters supplying generic hydroxycarbamide to African and Southeast Asian markets.
Nigeria
The world's highest sickle cell disease birth prevalence creates substantial unmet need for disease-modifying therapy access. The National Agency for Food and Drug Administration and Control oversees import registration for essential medicines including hydroxycarbamide. Lagos and Abuja academic medical centers are expanding newborn screening programs that will expand diagnostic-identified patient pools.
United Kingdom
National Health Service specialist commissioning drives concentrated procurement through designated hemoglobinopathy centers in London, Birmingham, and Manchester. The Medicines and Healthcare products Regulatory Agency coordinates with NICE technology appraisals for rare disease therapies. Oxford and Cambridge research institutions anchor gene therapy clinical trials that may reshape long-term hydroxycarbamide positioning.
Hydroxycarbamide Market Vendor Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates that control API production and finished dosage supply. Three to four manufacturers anchor global volume through captive manufacturing and established regulatory dossiers. The competitive terrain separates into originator-level specialists with orphan drug portfolios, scaled generic manufacturers with hospital contract dominance, and emerging market-focused suppliers with tropical stability expertise. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves.
Among North American and European pharmaceutical conglomerates, Bristol Myers Squibb and Teva Pharmaceutical Industries Ltd. exemplify the vertically integrated archetype with established sickle cell formulation portfolios. Dr. Reddy's Laboratories Ltd. represents the emerging market-focused supplier segment with differentiated packaging capabilities for tropical distribution. These three anchors illustrate how competitive positioning fragments across regulatory sophistication, manufacturing scale, and geographic specialization vectors.
| Leading Market Players |
|---|
| Cipla Limited |
| Hikma Pharmaceuticals PLC |
| Bristol Myers Squibb |
| Qilu Pharmaceutical |
| Beijing Jialin Pharma |
| Teva Pharmaceutical Industries Ltd. |
| Taj Pharmaceuticals Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Zydus Lifesciences Limited |
| Others |
Supply Flow & Price Mechanics
Gene therapy substitution for sickle cell disease simultaneously redraws API sourcing geography and compresses pricing economics for chronic maintenance therapies. Manufacturers now face margin pressure as payers condition hydroxycarbamide reimbursement on documented failure of disease-modifying protocols, forcing supply chain reconfiguration toward lower-cost production hubs.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure for pediatric formulations in the United States, while European EMA pharmacovigilance obligations sustain premium positioning for myeloproliferative neoplasm applications. Three-tier pricing separates originator-grade orphan indications from standard generic tablets and economy-tier tropical-stability exports. Cost compression in the generic tablet segment intensifies as Indian API suppliers expand qualified manufacturer lists for hospital contracts. Medicaid programs exhibit highest price sensitivity through mandatory specialty pharmacy lock-in, whereas European specialist centers maintain lowest sensitivity due to indication-specific premium protocols.
Supply Chain Analysis
Single-source API qualification through EMA Good Manufacturing Practice audits creates chokepoint vulnerability for European formulation finishers. Active pharmaceutical ingredient production draws from India, China, and the United States, with Hyderabad and Mumbai anchoring export-oriented supply for tropical-distribution markets. Hydroxycarbamide synthesis rests on urea derivative feedstocks and specialized catalytic hydrogenation equipment subject to chemical registration documentation burdens. Tariff exposure on Chinese-sourced intermediates threatens margin stability for generic tablet manufacturers. Distribution runs through vertically integrated pharmaceutical conglomerates with captive warehouse networks and specialty pharmacy partnerships for direct patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters cyclical recovery as gene therapy substitution delays create extended revenue windows for maintenance therapy suppliers. Sickle cell disease prevalence expansion and newborn screening program growth sustain patient pool replenishment.
For Market Incumbents: Compound formulary lock-in through 340B program pricing dominance and pediatric oral solution portfolio breadth. Bristol Myers Squibb and Teva should deepen backward integration into API production to defend against Indian generic entrants qualifying under FDA accelerated approval pathways. Prioritize heat-stable packaging certification for sub-Saharan African tender opportunities before tropical-distribution specialists capture institutional procurement.
For New Entrants and Emerging Players: Lead with differentiated stability profiles for Nigerian and Democratic Republic of Congo sickle cell programs where diagnostic infrastructure expansion outpaces established supplier distribution reach. Target myeloproliferative neoplasm dosing optimization in German and French academic centers as the most penetrable premium segment. Pursue licensing agreements with Indian API manufacturers to bypass EMA qualified supplier qualification timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmacy platforms building dedicated hematology teams for prior authorization and adherence monitoring. Long-term viability hinges on five-to-ten-year gene therapy substitution curves and real-world evidence monetization from sickle cell registries. Watch CRISPR-based treatment FDA approval timelines as the critical inflection signal for hydroxycarbamide maintenance protocol displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Oral Solution Manufacturing Scale-Up | Pediatric home administration protocols at United States hematology clinics drive formulation diversification. |
| EMA Pharmacovigilance Database Investment | Periodic safety update reports satisfy tightening post-market surveillance for cytotoxic therapies in Germany and France. |
| Tropical Stability Packaging Certification | Heat-stable variants address distribution gaps in Nigerian and Indian sub-Saharan supply corridors. |
| Specialty Pharmacy Distribution Partnership | CVS Specialty and Accredo hematology teams capture sickle cell dispensing from hospital outpatient pharmacies. |
| Indian API Hub Backward Integration | Hyderabad and Mumbai production clusters supply generic hydroxycarbamide to African and Southeast Asian markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA pharmacovigilance filings, ClinicalTrials.gov pediatric sickle cell protocols, and national formulary databases. Drug development executives at vertically integrated manufacturers, regulatory affairs leads navigating REACH chemical registration, hospital procurement managers managing 340B program pricing, and payer access specialists conditioning reimbursement on prior authorization provided qualitative input. Bottom-up patient registry analysis triangulates against top-down API production capacity assessments from Indian and Chinese customs records.
Segmentation dimensions modeled span formulation type, therapy area, administration route, and end-user care setting across the projection horizon. Sickle cell disease prevalence trajectories, myeloproliferative neoplasm diagnostic rates, and pediatric oral solution adoption curves inform volume and value outputs. CAGRs derive from weighted regression across historical utilization patterns and regulatory approval pathway timelines. Orphan drug exclusivity periods and gene therapy clinical trial readouts constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or EMA qualified supplier list stability would require recalibration. Forecasts reflect assumptions regarding sickle cell disease patient registry growth and substitution timeline delays from emerging gene therapies. Revision becomes warranted when CRISPR-based treatment approval crosses commercialization thresholds or when Indian API manufacturers achieve EMA Good Manufacturing Practice qualification at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Botulinum Toxin Market