
 Cefdinir API Market | 2026-2036
Cefdinir API Market Size, Share, and Industry Trends Forecast 2026-2036
Cefdinir API Market Insights
Indian bulk drug manufacturers is shifting toward dedicated cephalosporin fermentation corridors to secure long-term API supply continuity. Aurobindo Pharma Limited leverages backward integration into penicillin and cephalosporin intermediates to control input costs across its oral formulation portfolio. Lupin Ltd anchors its position through sustained R&D investment in complex generic injectable lines derived from Cefdinir API. Teva Pharmaceutical Industries Ltd competes on manufacturing scale, operating multi-ton API reactors across Eastern European and Israeli sites.
Cefdinir API refers to the active pharmaceutical ingredient of the third-generation cephalosporin antibiotic, synthesized through multi-step fermentation followed by chemical acylation to achieve NMR-verified purity exceeding 99.5% for pharmaceutical-grade batches. Its primary commercial purpose centers on supplying finished-dose manufacturers producing oral suspensions and capsules for community-acquired respiratory and skin infections. Tablets and capsules command the largest share of API offtake, reflecting entrenched outpatient prescribing patterns for uncomplicated bacterial sinusitis and otitis media. Injectable formulations represent the fastest-expanding product category, driven by hospital formulary shifts toward IV-to-oral step-down protocols in respiratory infection management.
FDA, EMA, and CDSCO each enforce distinct impurity profiling and residual solvent limits for cephalosporin APIs, with post-ICH Q3D elemental impurity guidelines now mandatory for export-oriented Indian and Chinese suppliers. REACH registration requirements in Europe further constrain market access for unregistered third-country manufacturers lacking toxicological dossiers. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and IP standards, as divergence in acceptance criteria directly determines batch release eligibility across major destination markets.
Market Dynamics
Fermentation-to-API manufacturing corridors in India and China now dictate supply continuity for third-generation cephalosporin antibiotics, with regulatory divergence between FDA, EMA, and CDSCO forcing parallel compliance investments from export-oriented suppliers.
Growth Catalysts
- Hospital IV-to-oral step-down protocols:Formulary managers in acute care settings are expanding oral cephalosporin coverage to reduce length-of-stay costs, directly lifting Cefdinir API offtake for suspension and capsule formulations.
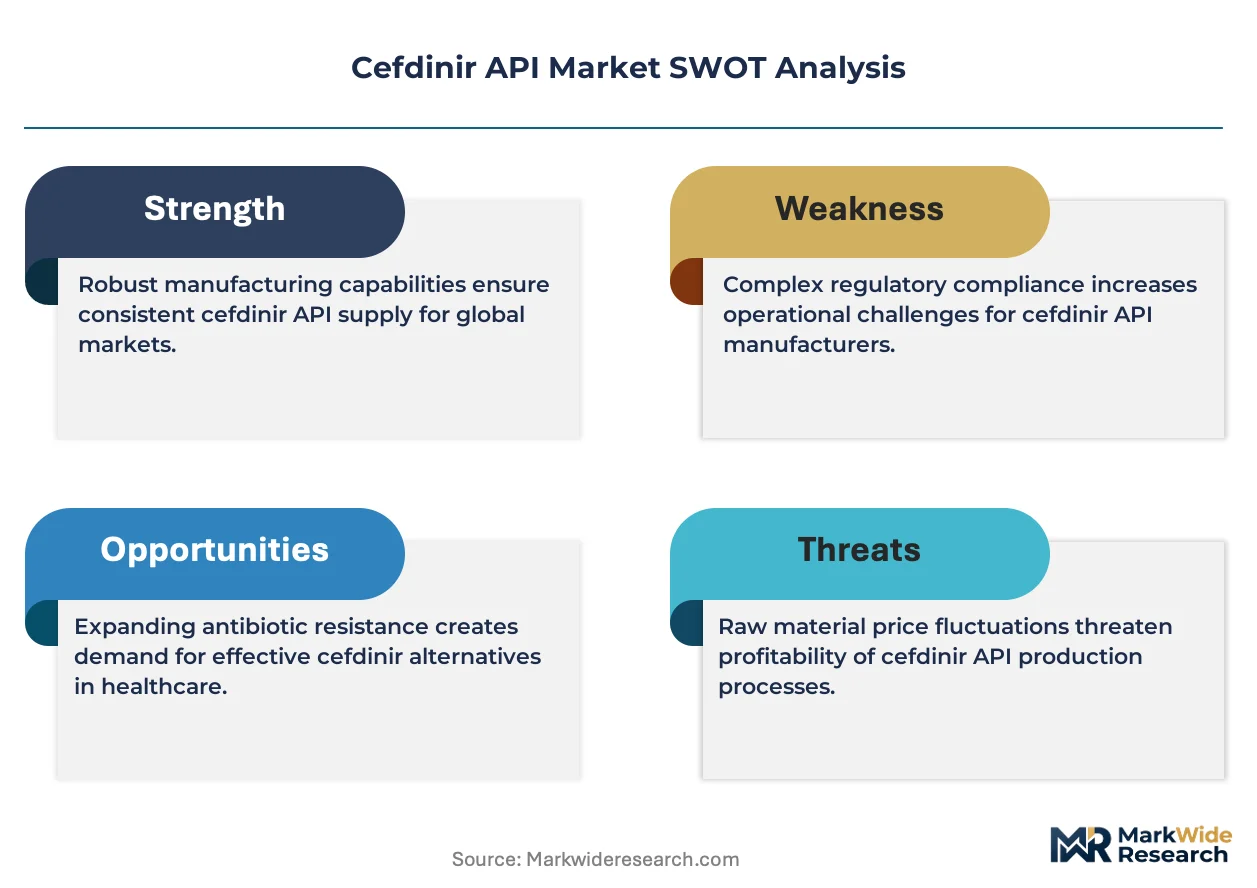
- REACH registration tailwinds:European toxicological dossier requirements, once barriers, now confer competitive moats for Indian and Chinese manufacturers that secured early ECHA compliance, locking out unregistered rivals.
- CDSCO export certification harmonization:India's national regulator has aligned impurity profiling protocols with ICH Q3D guidelines, reducing batch rejection rates at destination ports and accelerating working capital cycles for domestic API producers.
Market Restraints
- D-7-ACA intermediate price volatility:The key cephalosporin nucleus derived from penicillin G fermentation fluctuates with agricultural input costs and environmental enforcement cycles in Shandong and Hebei provinces, compressing margin predictability for non-integrated formulators.
- Residual solvent specification tightening:USP Chapter 467 and EP 5.4 have lowered acceptance thresholds for Class 2 solvents like dichloromethane and acetonitrile, forcing capital-intensive solvent recovery system upgrades at legacy fermentation sites.
- Carbapenem and respiratory fluoroquinolone substitution:Hospital antimicrobial stewardship committees in Germany and the United States are narrowing oral cephalosporin formularies where resistance surveillance data favors alternative agents.
Strategic Opportunities
- Complex generic injectable lines:Lupin Ltd and comparable specialists are filing ANDAs for Cefdinir-based IV formulations targeting post-surgical prophylaxis, a category with fewer approved generics than oral segments.
- PLI scheme fermentation capacity:India's Production Linked Incentive program for bulk drugs is subsidizing greenfield cephalosporin corridors in Andhra Pradesh and Gujarat, offering 20% cost offsets on capital expenditure for qualifying projects.
- Continuous manufacturing adoption:Teva Pharmaceutical Industries and Eastern European contract manufacturers are piloting flow chemistry for acylation steps, promising yield improvements and reduced solvent waste versus batch reactors.
Industry Challenges
- Analytical method transfer complexity:Moving NMR and HPLC impurity validation protocols between USP, EP, and IP pharmacopoeial standards requires 12-18 month timeline extensions that delay commercial launches.
- Specialized fermentation engineering talent scarcity:Large-scale aerobic bioprocess expertise for cephalosporin C production concentrates at a handful of Indian and Chinese technical institutes, constraining workforce expansion at new manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cefdinir API Market |
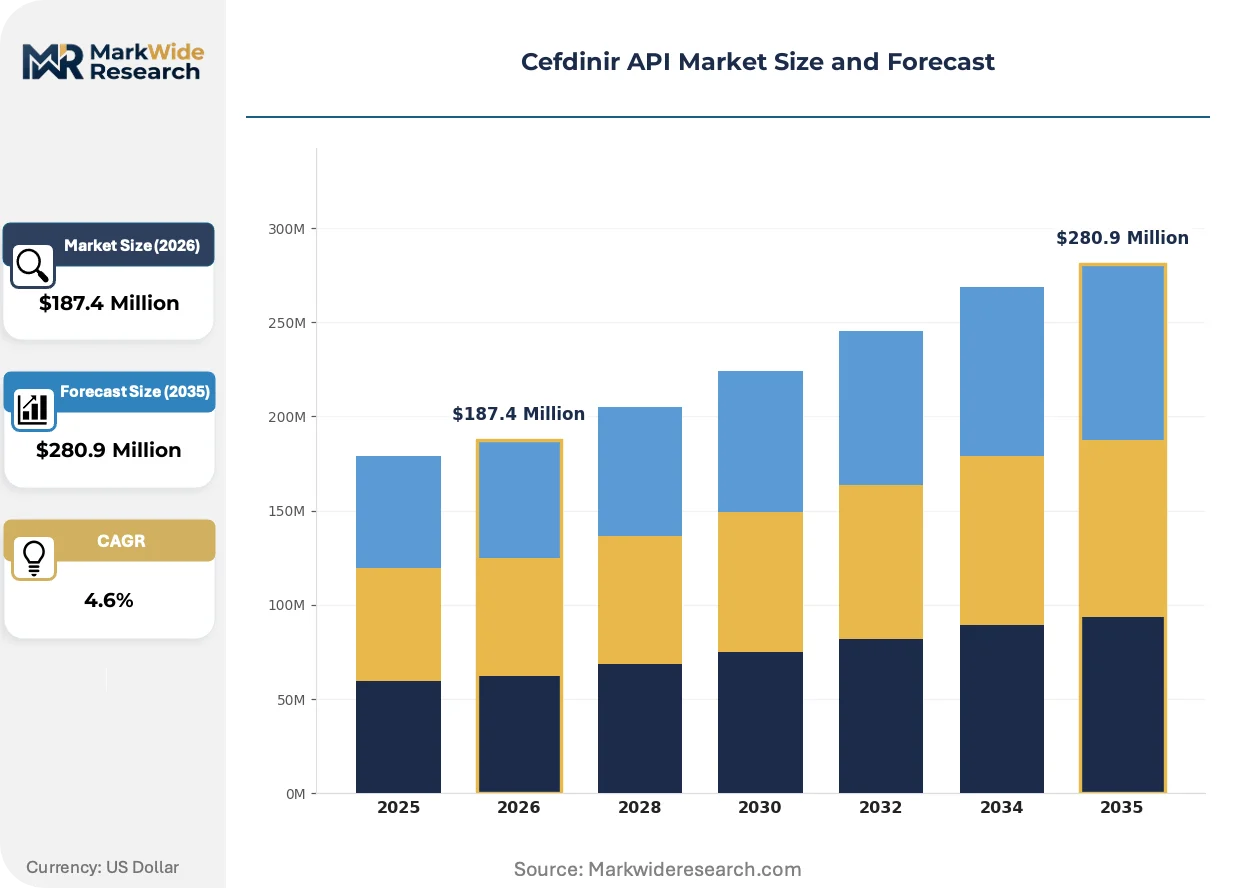
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Suspension, Tablets, Capsules Application: Bacterial Infections, Respiratory Infections, Skin Infections, Ear Infections End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online, Wholesalers, Retail, Direct Sales |
| Companies Covered | Aurobindo Pharma Limited, Lupin Ltd, Sandoz GmbH, Orchid Pharma Ltd, Nectar Lifesciences Ltd, China Union Chempharma (Suzhou) Co., Ltd, Qilu Pharmaceutical, Akums Lifesciences, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cefdinir API Market Trends and Innovations
Multi-step chemical acylation and downstream purification technologies are converging with digital process analytical technology, compressing batch release timelines while pharmacopoeial harmonization efforts force simultaneous compliance investments across three major regulatory jurisdictions.
Single-use bioreactor systems are unifying upstream fermentation operations with closed-system downstream processing, eliminating cross-contamination risks between cephalosporin and penicillin production lines. Aurobindo Pharma and comparable integrated manufacturers are deploying these systems at greenfield Andhra Pradesh sites, reducing clean-in-place downtime by 40% and enabling faster product changeovers between API grades.
EMA's 2023 revision to the Guideline on the Specification Limits for Residues of Metal Catalysts has tightened elemental impurity thresholds for palladium and nickel in cephalosporin APIs, forcing suppliers to validate alternative hydrogenation catalysts or install advanced scavenging resins. German and Italian finished-dose manufacturers are now requiring Certificate of Analysis amendments documenting catalyst residue testing under the updated framework, with non-compliant batches facing import holds at Rotterdam and Hamburg ports.
Formulary preference is rotating toward high-purity API grades with documented elemental impurity dossiers, displacing commodity-tier suppliers that lack ICH Q3D compliance infrastructure. Hospital procurement committees in Tel Aviv and Warsaw are inserting pharmacopoeial-grade certification requirements into tender documents, channeling volume toward manufacturers with in-house USP and EP reference standard capabilities.
Cefdinir API Market Segmentation
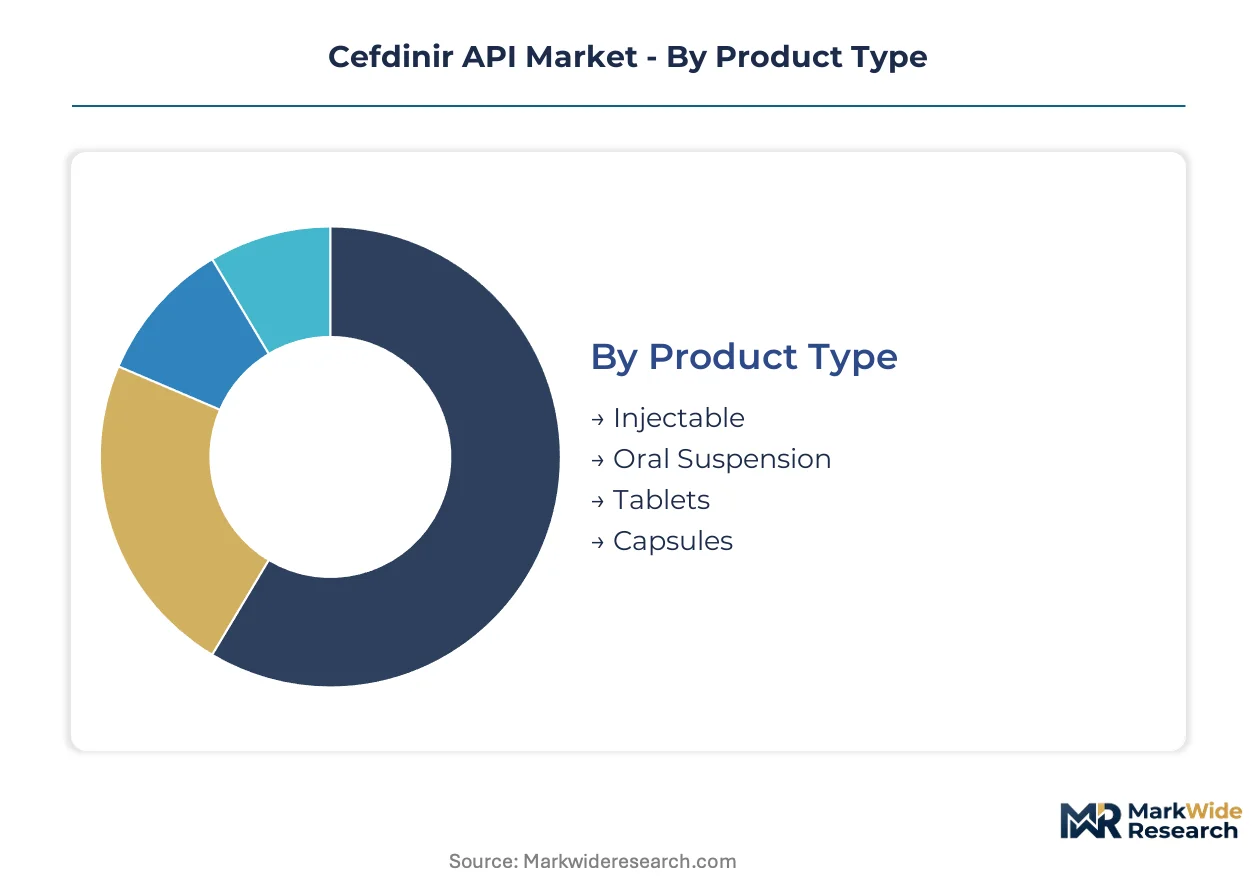
Segmentation in the Cefdinir API Market reflects divergent purity specifications, formulation complexity, and regulatory pathways that separate hospital-grade from retail-channel supply. Understanding these divisions enables suppliers to align fermentation capacity with precise end-use certification requirements.
Product Type:
Formulation chemistry dictates the acylation precision and residual solvent thresholds required at the API stage.
- Tablets:Compressed solid dosage forms require API with controlled particle size distribution and polymorphic stability to ensure dissolution profile consistency. Demand concentrates in retail pharmacy networks across India and the United States, where outpatient prescribing for sinusitis and otitis media drives volume offtake under FDA and CDSCO oversight.
- Capsules:Gelatin-encapsulated formulations accommodate moisture-sensitive API batches with enhanced stability packaging. Manufacturers in Eastern Europe and Israel prioritize capsule-grade supply for markets with stringent USP Chapter 905 uniformity requirements, particularly where temperature-controlled distribution infrastructure remains limited.
- Oral Suspension:Reconstitutable powder formulations for pediatric populations demand micronized API with enhanced flow properties and taste-masking compatibility.
- Injectable:Sterile-grade API for IV-to-oral step-down protocols requires endotoxin-controlled manufacturing corridors and validated aseptic processing lines.
Tablets lead on scale; Injectable leads on momentum.
Application:
Clinical indication determines the potency grading and impurity profiling protocols imposed by hospital formulary committees.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis represent the primary prescription drivers, requiring API batches with documented efficacy against Streptococcus pneumoniae and Haemophilus influenzae isolates. Hospital procurement in Tel Aviv and Warsaw prioritizes suppliers with pharmacopoeial-grade certification for this indication.
- Ear Infections:Pediatric otitis media prescriptions concentrate API demand in suspension-grade specifications, with clinics in India and the United States representing the dominant offtake channels where CDSCO and FDA bioequivalence standards apply.
- Skin Infections:Uncomplicated skin and soft tissue infections drive demand for oral formulations with rapid absorption profiles.
- Bacterial Infections:Broad-spectrum coverage applications span multiple anatomical sites, requiring versatile API grades adaptable across formulation types.
Respiratory Infections commands the largest revenue pool; Ear Infections is climbing the fastest on pediatric formulation expansion.
End User:
Procurement authority and reimbursement pathways segment the market by certification burden and contract structure.
- Hospitals:Acute care institutions with antimicrobial stewardship committees impose the most stringent API documentation requirements, including elemental impurity dossiers under ICH Q3D and validated catalyst residue testing. German and Italian finished-dose manufacturers direct volume toward suppliers with EMA-aligned Certificate of Analysis amendments.
- Pharmacies:Retail dispensaries operate under less intensive documentation protocols but require consistent batch-to-batch availability for chronic prescription fulfillment. Indian retail networks in Andhra Pradesh and Gujarat source from domestic fermentation corridors subsidized under PLI scheme provisions.
- Clinics:Outpatient facilities bridge hospital and retail channels with mixed procurement patterns.
- Home Care:Self-administered oral therapies for post-discharge patients demand patient-compliant packaging and reconstitution instructions.
Hospitals lead on certification premium; Pharmacies lead on volume throughput.
Distribution Channel:
Channel selection determines working capital cycles, traceability requirements, and geographic reach.
- Wholesalers:Aggregator intermediaries consolidate API volumes from multiple fermentation sites for redistribution to finished-dose manufacturers, offering inventory pooling that reduces working capital requirements for mid-scale formulators in Eastern Europe and Israel.
- Direct Sales:Long-term supply agreements between integrated API producers and multinational finished-dose manufacturers eliminate intermediary margins and enable co-development of customized impurity specifications. Aurobindo Pharma and comparable Indian suppliers leverage backward integration into penicillin and cephalosporin intermediates to secure these direct relationships.
- Retail:Pharmacy-direct distribution serves localized formulation operations with smaller batch requirements.
- Online:Digital procurement platforms facilitate spot-market transactions for non-contracted API volumes.
Wholesalers lead on reach; Direct Sales leads on margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA, EMA, and CDSCO compliance costs is redirecting fermentation capacity toward jurisdictions where subsidy regimes offset certification investments. Indian and Chinese manufacturers exploit this gap to supply finished-dose formulators in regulated markets.
India
Domestic generic consumption and export-oriented API production sustain demand for cephalosporin-grade fermentation output. CDSCO's alignment with ICH Q3D guidelines has reduced port-of-entry rejection rates for Indian suppliers shipping to Rotterdam and Hamburg. The Hyderabad-Vizag corridor in Andhra Pradesh concentrates greenfield capacity subsidized under PLI scheme provisions.
China
Integrated penicillin-to-cephalosporin fermentation clusters supply D-7-ACA intermediates to global formulators. NMPA enforcement of environmental standards in Shandong and Hebei provinces has consolidated production at larger, compliant sites. Suzhou and Shandong Peninsula facilities now dominate export-grade API output for European and Israeli finished-dose manufacturers.
United States
Hospital formulary shifts toward IV-to-oral step-down protocols drive demand for high-purity oral suspension and capsule grades. FDA's tightened USP Chapter 467 residual solvent thresholds favor suppliers with validated solvent recovery infrastructure. Finished-dose manufacturing concentrates in Puerto Rico and New Jersey, sourcing API through direct agreements with Indian and Chinese producers.
Germany
EMA's 2023 revision to metal catalyst residue guidelines has elevated documentation requirements for cephalosporin API imports. German hospital procurement committees now mandate ICH Q3D-compliant elemental impurity dossiers in tender specifications. The Rhine-Ruhr and Bavarian pharmaceutical manufacturing regions channel volume toward ECHA-registered suppliers with REACH-compliant toxicological dossiers.
Israel
Teva Pharmaceutical Industries anchors regional demand through multi-ton API reactor operations serving internal formulation requirements and third-party supply. Israeli hospital procurement in Tel Aviv and Haifa prioritizes pharmacopoeial-grade certification for respiratory infection indications. The Negev and central Israel corridor concentrates sterile-grade API finishing capacity for injectable formulations.
Cefdinir API Market Competitive Landscape
Indian producers anchor the volume tier through backward integration into penicillin and cephalosporin intermediates; Chinese specialists hold intermediate supply positions. The vendor base fragments across integrated fermentation-to-API manufacturers, intermediate-focused suppliers, and formulation-only offtakers. Two archetypes dominate: subsidy-leveraged greenfield developers in Andhra Pradesh and Gujarat, and legacy multi-site operators with EMA-registered dossiers. Competitive moves center on PLI scheme capacity expansion and REACH registration acquisition to lock out unregistered rivals.
Within the integrated manufacturer tier, Aurobindo Pharma Limited and Lupin Ltd represent archetypes of backward integration strategies controlling input costs across oral and injectable formulation portfolios. Teva Pharmaceutical Industries occupies a position at the scale-driven end, with multi-site API reactor operations spanning Eastern European and Israeli manufacturing locations. China Union Chempharma (Suzhou) Co., Ltd exemplifies the Chinese specialist model focused on fermentation corridor supply to export markets.
| Leading Market Players |
|---|
| Aurobindo Pharma Limited |
| Lupin Ltd |
| Sandoz GmbH |
| Orchid Pharma Ltd |
| Nectar Lifesciences Ltd |
| China Union Chempharma (Suzhou) Co., Ltd |
| Qilu Pharmaceutical |
| Akums Lifesciences |
| Teva Pharmaceutical Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Large-scale aerobic bioprocess engineering talent concentrated at Indian technical institutes in Hyderabad and Pune widens labor-cost differentials between integrated fermentation corridors and non-integrated formulators, compressing pricing-tier spreads for commodity-grade Cefdinir API while sustaining premiums for pharmacopoeial-certified batches.
Pricing Analysis
Distributor margin layers in the Cefdinir API market typically capture 8-12% of ex-works value, with direct-to-manufacturer agreements eliminating this spread for volume offtakers. Three-tier pricing structure across pharmacopoeial-grade, technical-grade, and feedstock-grade levels separates hospital-certified supply from retail-channel commodity volumes. Cost compression in technical-grade tiers is intensifying because Shandong-based D-7-ACA intermediate suppliers face cyclical environmental enforcement. Retail pharmacy networks in India exhibit highest price sensitivity, while German hospital procurement committees prioritize certification premiums over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Hebei and Shandong province fermentation clusters that supply the bulk of D-7-ACA cephalosporin nucleus to global formulators. Active pharmaceutical ingredient output draws from India, China, and Israel, with penicillin G fermentation, chemical acylation catalysts, and endotoxin-controlled finishing capacity as critical input dependencies. Tariff exposure on Chinese-origin intermediates threatens margin predictability for Eastern European formulators lacking backward integration. Distribution runs through wholesaler aggregators in Rotterdam and Hamburg for European offtake, direct sales agreements for Israeli and Indian integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cefdinir API margin expansion rests on fermentation-to-API integration subsidies and pharmacopoeial-grade certification premiums that widen spreads between commodity and hospital-certified supply tiers.
For Market Incumbents: Hedge against carbapenem substitution threats by securing PLI scheme capacity in Andhra Pradesh and validating continuous manufacturing flows for acylation yield improvements. Lock in ECHA-registered REACH dossiers to exclude unregistered Chinese rivals from German hospital tenders. Prioritize in-house USP and EP reference standard capabilities to defend pharmacopoeial-grade pricing premiums. For New Entrants and Emerging Players: The price-point gap between EMA-certified premium supply and CDSCO-registered economy volumes creates entry space for mid-tier specialists with partial pharmacopoeial alignment. Target oral suspension-grade specifications for Indian pediatric clinic networks where bioequivalence documentation requirements remain less intensive than hospital injectable segments. Pursue toll manufacturing partnerships with established fermentation corridors to bypass capital-intensive greenfield buildouts. For Investors and Strategic Acquirers: Indian bulk drug manufacturers with backward integration into penicillin and cephalosporin intermediates represent the most active acquirer category in this space, consolidating fragmented fermentation capacity. Five-to-ten year viability favors subsidy-leveraged greenfield developers in Gujarat with validated ICH Q3D infrastructure over legacy operators dependent on spot-market intermediate sourcing. Watch for CDSCO-EMA harmonization announcements as inflection signals for export-oriented capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cephalosporin Intermediates | Aurobindo Pharma controls D-7-ACA input costs across oral formulation portfolios. |
| PLI Scheme Fermentation Capacity Expansion | Andhra Pradesh greenfield corridors secure 20% capital expenditure offsets for qualifying projects. |
| REACH Registration Acquisition | Early ECHA compliance locks out unregistered rivals from Rotterdam and Hamburg port entry. |
| Continuous Manufacturing Pilot Programs | Teva Pharmaceutical Industries deploys flow chemistry to reduce solvent waste versus batch reactors. |
| Complex Generic Injectable ANDA Filings | Lupin Ltd targets post-surgical prophylaxis segments with fewer approved generics than oral categories. |
Research Methodology
Direct dialogue with fermentation plant managers, regulatory affairs leads at Indian and Chinese API exporters, hospital formulary directors in Germany and Israel, and finished-dose procurement officers grounded qualitative findings. Secondary validation drew from FDA 483 inspection observations, EMA cephalosporin guideline revisions, CDSCO export certification bulletins, and USP Chapter 467 pharmacopoeial updates. Bottom-up capacity assessments at Shandong and Andhra Pradesh manufacturing sites were triangulated against top-down prescription volume estimates from hospital procurement databases.
Bottom-up modeling tracked fermentation reactor utilization, acylation yield rates, and batch release timelines across the projection horizon. Segmentation dimensions included formulation chemistry, clinical indication, procurement authority, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical API offtake patterns and formulary shift trajectories. Forecast inputs incorporated antimicrobial stewardship committee protocols and pharmacopoeial harmonization milestones between USP, EP, and IP standards.
Caveats apply where D-7-ACA intermediate price volatility, REACH registration timeline extensions, or carbapenem formulary substitution could materially shift the outlook. Forecasts reflect assumptions about environmental enforcement cycles in Hebei province and PLI scheme continuation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Capecitabine Market