
 Global Bronchodilators Market | 2026-2036
Global Bronchodilators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bronchodilators Market Foresight
Hospital procurement consolidation is realigning how bronchodilator contracts are negotiated across integrated delivery networks. AstraZeneca leverages its respiratory biologics portfolio to sustain formulary positioning amid this buyer concentration. Teva Pharmaceutical Industries Ltd. competes through its generics-heavy inhaler lineup, while Boehringer Ingelheim International GmbH anchors premium segments with its long-acting muscarinic antagonist franchise.
Bronchodilators are pharmacological agents that relax airway smooth muscle through beta-2 receptor agonism, anticholinergic blockade, or phosphodiesterase inhibition, typically formulated as metered-dose suspensions, micronized dry powders, or nebulized solutions for direct pulmonary deposition. Their primary purpose is reversing bronchospasm in obstructive lung diseases to restore expiratory flow and reduce hyperinflation. Combination drugs pairing long-acting beta-2 agonists with corticosteroids capture the deepest margin pools, while dry powder inhalers displace pressurized metered-dose formats as propellant regulations tighten. Nebulizer-compatible formulations retain stubborn volume in pediatric and geriatric populations where hand-breath coordination fails.
The FDA's bioequivalence requirements for inhaled products and the EMA's MDR-aligned clinical evidence standards for combination therapies shape development costs and generic substitution timelines. WHO's Essential Medicines List inclusion of salbutamol and ipratropium drives procurement volumes in low-income country programs. Stakeholders must monitor how regulator divergence between the FDA and EMA on in vitro-in vivo correlation studies fragments global development strategies.
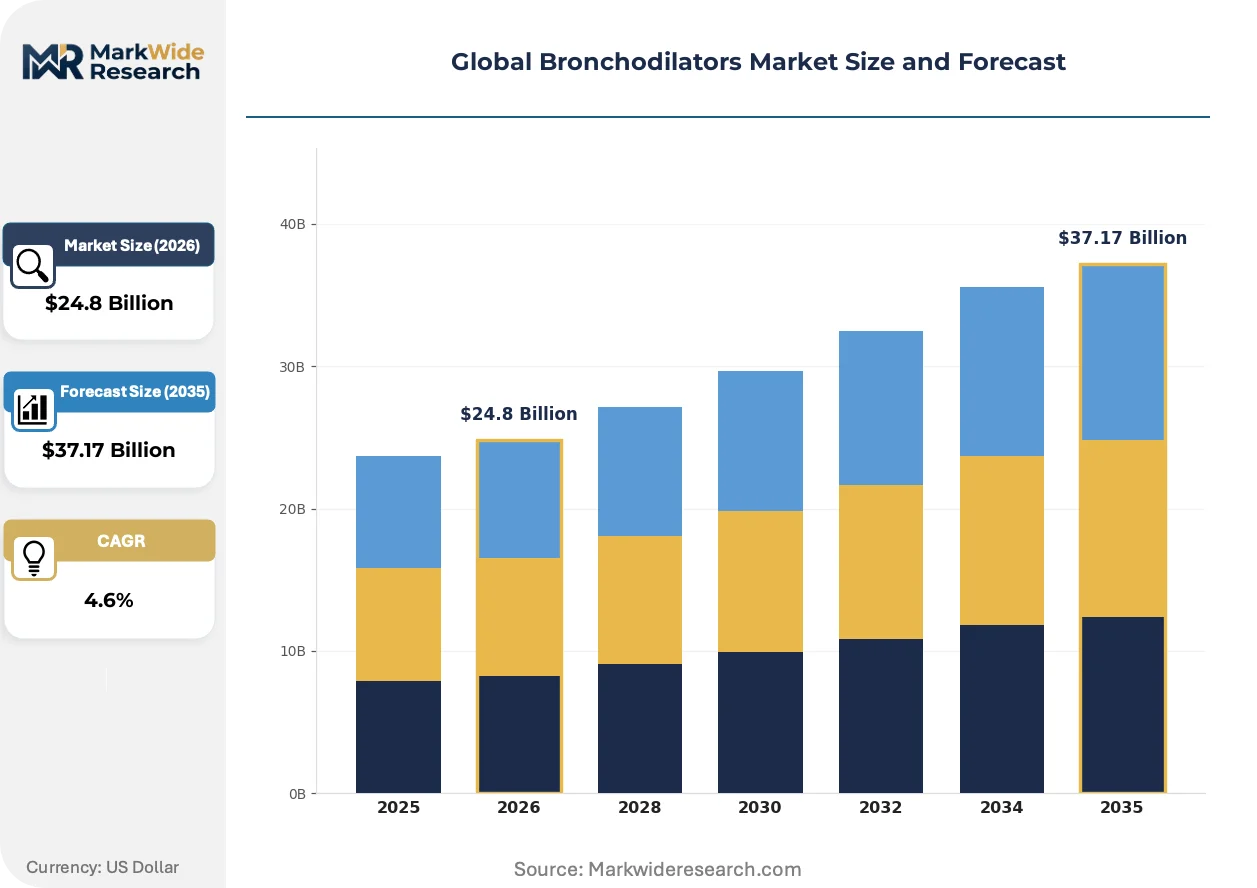
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing contract negotiation timelines and favoring suppliers with broad respiratory portfolios capable of serving centralized formularies.
Growth Catalysts
- MDR-aligned clinical evidence standards:The EMA's tightened requirements for combination therapies are accelerating investment in differentiated dry powder inhaler platforms that demonstrate superior lung deposition profiles.
- Pediatric nebulization demand:Geriatric populations with failed hand-breath coordination sustain stubborn volume in nebulizer-compatible formulations across long-term care facilities.
- India:WHO Essential Medicines List procurement programs for salbutamol and ipratropium are driving volume commitments through centralized government tenders.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for anticholinergic compounds clusters in specific coastal manufacturing zones, exposing formulators to single-source disruption risk.
- FDA bioequivalence complexity:The agency's in vitro-in vivo correlation requirements for inhaled generics extend development timelines and elevate clinical trial costs beyond small-molecule oral benchmarks.
- Propellant transition costs:Hydrofluoroalkane reformulation mandates under the EPA's phasedown program force capital-intensive manufacturing line conversions for pressurized metered-dose formats.
Strategic Opportunities
- Connected inhaler platforms:Bluetooth-enabled adherence monitoring devices are converging with dry powder mechanisms to capture real-world evidence contracts with payers seeking outcome-based reimbursement structures.
- Brazil:ANVISA's streamlined pathway for essential medicines creates entry potential for nebulized bronchodilator portfolios in public hospital procurement.
- Direct-to-patient pharmacy channels:Specialty mail-order distribution is bypassing traditional wholesale intermediaries for maintenance therapy refills in chronic obstructive pulmonary disease populations.
Industry Challenges
- Inhaler engineering talent scarcity:The specialized mechanical design expertise required for powder dispersion mechanisms and plume geometry optimization concentrates within a limited pool of device engineering consultancies.
- Legacy system integration:Pharmaceutical manufacturers face friction connecting connected inhaler data streams to existing pharmacovigilance databases and patient support program infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bronchodilators Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-2 Agonists, Anticholinergics, Methylxanthines, Combination Drugs Delivery Mode: Inhalers, Nebulizers, Oral Tablets, Injectables, Dry Powder Inhalers Therapy Area: Asthma, Chronic Obstructive Pulmonary Disorder, Bronchitis, Emphysema, Bronchiectasis End User: Hospitals, Pulmonary Clinics, Ambulatory Care Centers, Specialty Pharmacies |
| Companies Covered | GSK plc, AstraZeneca, Teva Pharmaceutical Industries Ltd., Novartis AG, Boehringer Ingelheim International GmbH, Cipla Inc., Sun Pharmaceutical Industries Ltd., Merck & Co., Inc., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bronchodilators Market Shifts & Advancements
Dry powder inhaler technology is actively reshaping competitive positioning as propellant regulations tighten and lung deposition science advances, while digital connectivity and procurement centralization create parallel transformation vectors.
Soft-mist inhaler technology is decentralizing treatment administration from clinical settings toward home-based self-management. Elderly patients with arthritis-reduced manual dexterity adopt these devices at accelerating rates in Germany and Japan. The shift is compressing hospital pharmacy revenue per patient while expanding retail pharmacy script volume.
The FDA's 505(b)(2) pathway for inhaled generics is compressing abbreviated new drug application timelines for established bronchodilator molecules. Generic sponsors now pursue bioequivalence through pharmacokinetic bridging studies rather than full clinical efficacy trials. Long-acting beta-agonist monotherapies face the steepest price erosion as multiple abbreviated applications queue for review.
Integrated delivery network procurement officers now demand outcome guarantees for biologic-bronchodilator combination regimens. Traditional fee-for-service distributor relationships are yielding to performance-based contracts with shared risk provisions. The United States exhibits the most advanced contracting sophistication, with Medicare Advantage plans piloting adherence-linked rebate structures.
Global Bronchodilators Market Segmentation
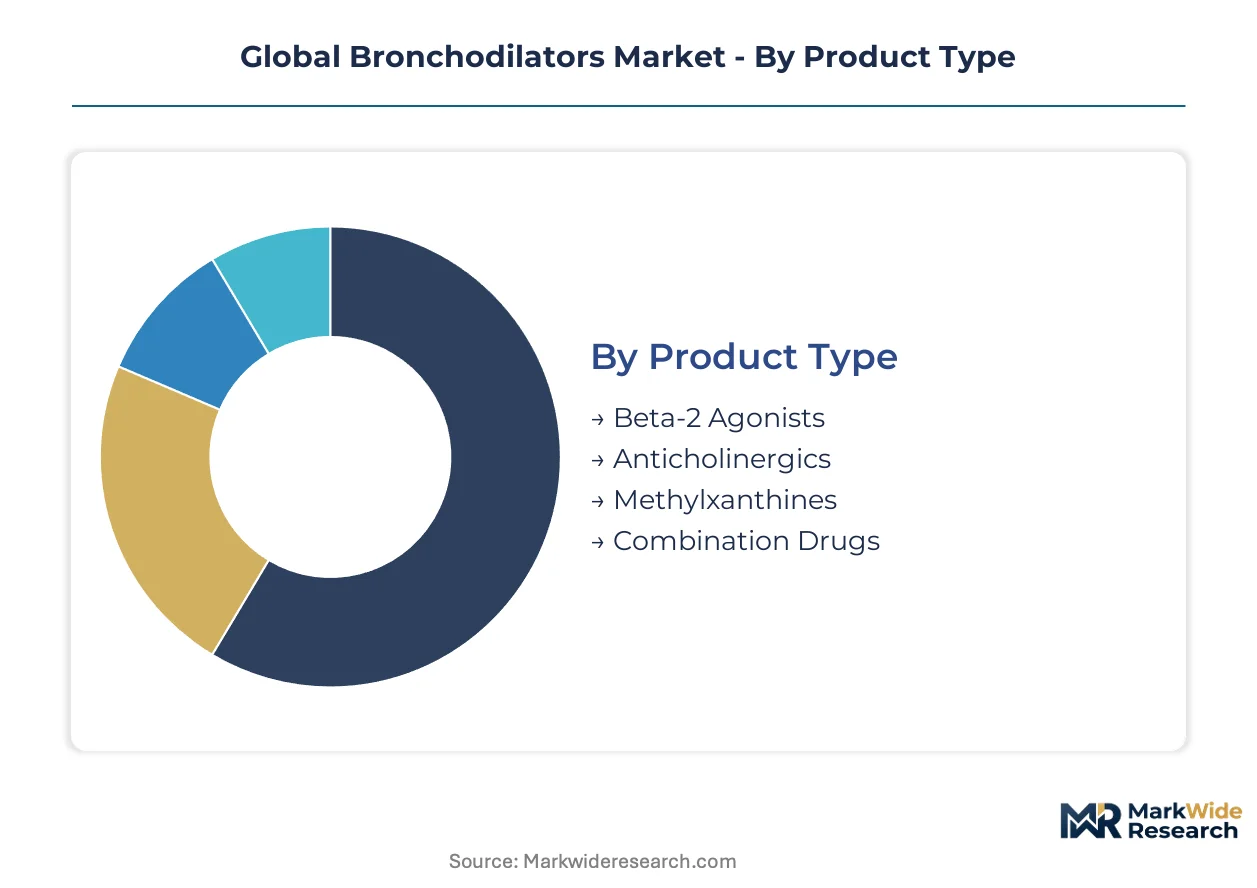
Bronchodilator segmentation reveals how formulation chemistry, device engineering, and care setting economics create distinct competitive arenas. Each category carries unique regulatory burdens and reimbursement logic that reshape manufacturer investment priorities.
Product Type:
Standardization dominates commodity bronchodilators while combination platforms demand bespoke clinical evidence packages and complex manufacturing integration.
- Beta-2 Agonists:Short-acting salbutamol and long-acting formoterol formulations activate adrenergic receptors to relax airway smooth muscle. Demand concentrates in United States Medicare Part B nebulization claims and Indian government essential medicines tenders where WHO List inclusion drives volume procurement.
- Anticholinergics:Ipratropium bromide and tiotropium block muscarinic receptors to reduce vagal tone in obstructed airways. Germany's statutory health insurance funds favor these for COPD maintenance therapy, though API manufacturing concentration in coastal Chinese zones exposes supply continuity risk.
- Methylxanthines:Theophylline derivatives inhibit phosphodiesterase enzymes to produce bronchodilation.
- Combination Drugs:Fixed-dose pairings of long-acting beta-2 agonists with corticosteroids or muscarinic antagonists command premium reimbursement through demonstrated exacerbation reduction.
Most installed capacity flows through Beta-2 Agonists. Expansion is steepest in Combination Drugs.
Delivery Mode:
Cost tier stratification separates capital-intensive device platforms from commodity formulation supply, with reimbursement codes determining viable entry points.
- Inhalers:Pressurized metered-dose devices suspend drug in hydrofluoroalkane propellant for lung deposition. United States EPA phasedown mandates force costly reformulation investments, while India's CDSCO streamlines approvals for essential medicine categories.
- Nebulizers:Compressor-driven or vibrating mesh systems aerosolize solutions for patients lacking hand-breath coordination. Japanese long-term care insurance sustains stubborn volume in elderly populations with arthritis-reduced dexterity.
- Oral Tablets:Systemic absorption routes bypass pulmonary deposition challenges for patients with severe cognitive impairment.
- Injectables:Subcutaneous or intravenous routes reserve for acute exacerbations in intensive care settings.
- Dry Powder Inhalers:Micronized drug blended with lactose carrier requires patient-generated airflow for dispersion.
Most installed capacity flows through Inhalers. Expansion is steepest in Dry Powder Inhalers.
Therapy Area:
Application severity determines whether maintenance therapy or rescue intervention dominates prescribing patterns, with biologic eligibility thresholds reshaping addressable markets.
- Asthma:Reversible airway obstruction in allergic and non-allergic phenotypes drives pediatric and adolescent volume. United Kingdom NICE guidelines prioritize inhaled corticosteroid-containing regimens, compressing monotherapy share.
- Chronic Obstructive Pulmonary Disorder:Progressive airflow limitation with incomplete reversibility anchors adult and geriatric demand. Brazil's SUS public procurement channels concentrate volume for nebulized formulations in hospital settings.
- Bronchitis:Acute and chronic airway inflammation with productive cough.
- Emphysema:Destruction of alveolar walls producing gas exchange impairment.
- Bronchiectasis:Permanent bronchial dilation with recurrent infection cycles.
Most installed capacity flows through Asthma. Expansion is steepest in Chronic Obstructive Pulmonary Disorder.
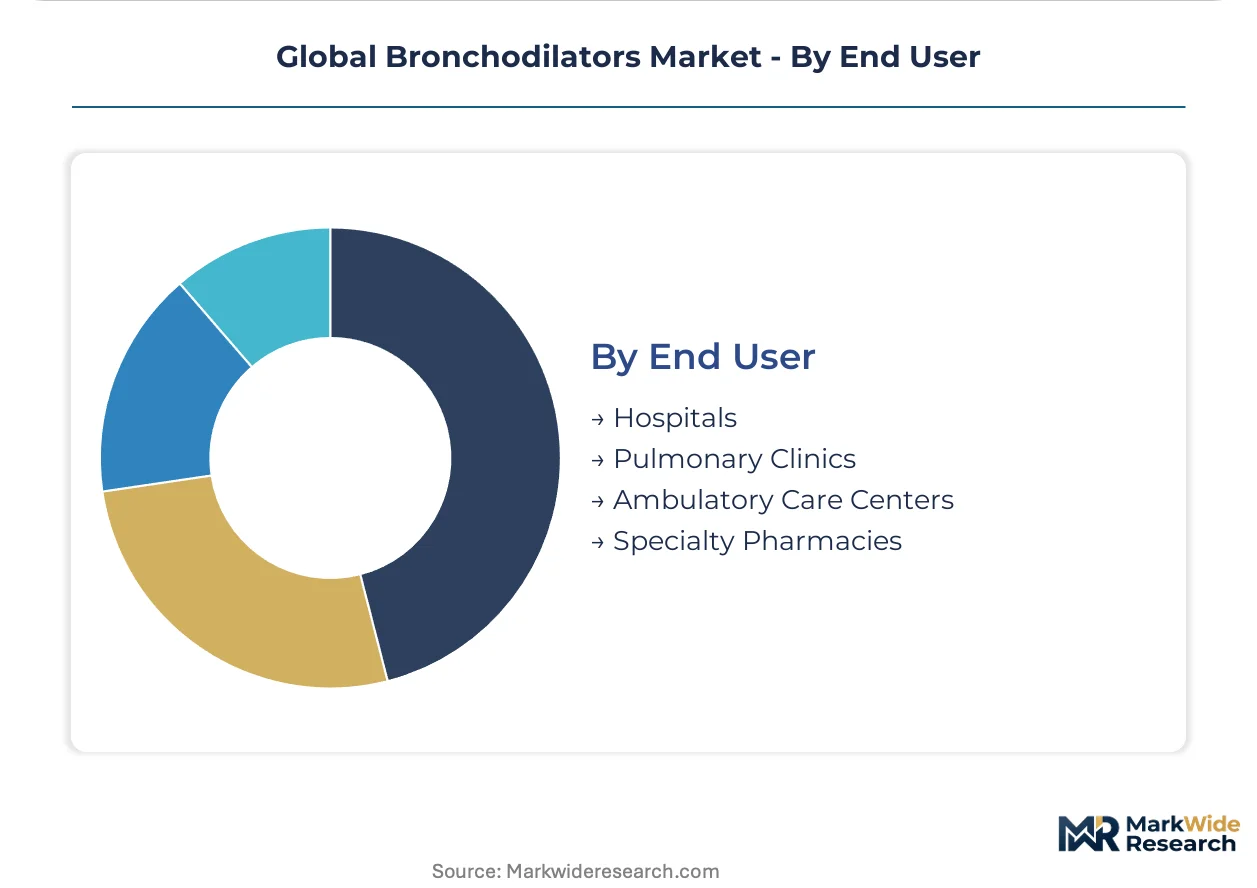
End User:
Customer type fragmentation separates centralized procurement power from dispersed retail prescribing, with integrated delivery networks consolidating contract leverage.
- Hospitals:Inpatient and emergency department administration of nebulized and injectable bronchodilators. United States integrated delivery network formularies increasingly demand outcome guarantees for biologic-bronchodilator combinations.
- Pulmonary Clinics:Specialist-directed optimization of inhaler technique and disease control. France's ANSM pharmacovigilance requirements shape post-market surveillance obligations for device-related adverse events.
- Ambulatory Care Centers:Same-day procedure settings with limited pharmacy infrastructure.
- Specialty Pharmacies:Mail-order and high-touch distribution for maintenance therapy refills.
Most installed capacity flows through Hospitals. Expansion is steepest in Specialty Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation in the United States generates contract leverage that Germany's statutory health insurance funds have begun emulating, while India's government tender systems create volume concentration through entirely different mechanisms.
United States
Medicare Part B reimbursement for nebulized therapies sustains volume leadership in COPD maintenance populations. The FDA's 505(b)(2) pathway accelerates abbreviated new drug applications for inhaled generics. Integrated delivery networks in Texas and Florida centralize formulary decisions toward outcome-based contracts.
Germany
Statutory health insurance funds prioritize long-acting muscarinic antagonists for COPD maintenance in elderly populations with arthritis-reduced dexterity. The country's national pharmaceutical regulator enforces MDR-aligned clinical evidence standards for combination therapies. Device engineering consultancies in Baden-Württemberg concentrate powder dispersion mechanism expertise.
India
WHO Essential Medicines List procurement programs for salbutamol and ipratropium drive volume through centralized government tenders. CDSCO streamlines approvals for essential medicine categories in metered-dose and dry powder formats. Active pharmaceutical ingredient manufacturing clusters in Gujarat and Maharashtra supply anticholinergic compounds to domestic formulators.
Japan
Long-term care insurance sustains stubborn volume in nebulizer-compatible formulations for geriatric populations. METI standards shape connected inhaler platform development for real-world evidence collection. Pharmaceutical device development concentrates in the Kanto region around Tokyo-based engineering partnerships.
Brazil
ANVISA's streamlined pathway for essential medicines creates entry potential for nebulized bronchodilator portfolios in public hospital procurement. The SUS public procurement channels concentrate volume for hospital-administered formulations. Manufacturing partnerships in São Paulo state serve domestic demand and Mercosur distribution.
Global Bronchodilators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and device engineering competencies. The market structure tiers between premium biologic-bronchodilator combinations and commoditized generic inhalers. Three archetypes dominate: multinational respiratory portfolios, generics-heavy device manufacturers, and regional API-to-formulation integrators. Competitive moves center on connected inhaler platform development and backward integration into active pharmaceutical ingredient supply.
Among UK-based pharmaceutical conglomerates, GSK plc and AstraZeneca occupy positions anchoring premium respiratory biologics portfolios. Teva Pharmaceutical Industries Ltd. represents the generics-heavy inhaler manufacturer archetype competing through abbreviated new drug application volume. Boehringer Ingelheim International GmbH exemplifies the family-owned German specialist model with concentrated long-acting muscarinic antagonist expertise.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Cipla Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Mylan N.V. |
| Others |
Supply & Pricing Matrix
Integrated delivery network procurement officers in the United States and statutory health insurance funds in Germany concentrate contract leverage toward centralized formularies, compressing supplier margins and forcing tiered pricing stratification across premium biologic combinations, standard maintenance therapies, and economy generic inhalers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for commodity bronchodilator APIs while premium segments defend margins through FDA 505(b)(2) pathway exclusivity and connected inhaler platform differentiation. Pricing stratifies across premium biologic-bronchodilator combinations, standard long-acting muscarinic antagonist maintenance therapies, and economy generic salbutamol inhalers. Cost compression in the generic beta-2 agonist tier intensifies because abbreviated new drug application queues extend price erosion timelines. Hospital procurement managers exhibit the highest price sensitivity, while specialty pharmacies capturing mail-order maintenance refills show greater willingness to absorb premium pricing for adherence-linked outcomes contracts.
Supply Chain Analysis
Device refurbishment and inhaler recycling programs remain underdeveloped across European markets, though Japanese long-term care facilities increasingly return nebulizer components for sterilization and redeployment. Active pharmaceutical ingredient manufacturing for anticholinergic compounds concentrates in coastal Chinese zones, Gujarat, and Maharashtra, while device engineering expertise clusters in Baden-Württemberg and the Kanto region. Formulation supply draws from hydrofluoroalkane propellant stocks subject to EPA phasedown mandates, micronized lactose carriers, and precision-milled powder blends. Single-source vulnerability in coastal Chinese API zones exposes formulators to disruption risk. Distribution runs through integrated delivery network central warehouses in North America, statutory health insurance fund regional depots in Germany, and government tender distribution channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry powder inhaler platform transitions and connected device adherence monitoring create dual margin-expansion vectors as manufacturers capture outcome-based reimbursement premiums while reducing propellant-dependent cost structures.
For Market Incumbents: Acquire connected inhaler engineering consultancies to secure scarce mechanical design expertise for powder dispersion mechanisms and plume geometry optimization. Consolidate backward integration into active pharmaceutical ingredient supply for anticholinergic compounds to mitigate single-source concentration risk in coastal Chinese manufacturing zones. Defend formulary positioning through real-world evidence contracts with Medicare Advantage plans piloting adherence-linked rebate structures, countering generic substitution pressure from FDA 505(b)(2) pathway entrants. For New Entrants and Emerging Players: Specialty pharmacy mail-order channels offer the most penetrable entry vector for bypassing traditional wholesale intermediaries in COPD maintenance therapy refills. Target Brazilian public hospital procurement through ANVISA's streamlined essential medicines pathway for nebulized bronchodilator portfolios, where SUS volume concentration creates scale opportunities without incumbent formulary lock-in. Pursue white-space positioning in pediatric nebulization segments where hand-breath coordination failures sustain stubborn demand for compressor-driven and vibrating mesh systems. For Investors and Strategic Acquirers: Generics-heavy inhaler manufacturers with abbreviated new drug application pipelines are the most active acquirer targets in this space as diversified conglomerates seek volume scale to offset biologic-bronchodilator combination pricing pressure. Long-term viability over the five-to-ten year horizon rests on connected inhaler platform differentiation and backward API integration depth rather than formulation chemistry alone. Monitor FDA 505(b)(2) approval velocity and EMA MDR-aligned clinical evidence standard divergence as early signals of generic entry timing and development cost trajectory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Inhaler Platform Development | Bluetooth-enabled adherence monitoring captures real-world evidence contracts with Medicare Advantage plans. |
| Backward API Integration | In-house anticholinergic compound production mitigates coastal Chinese single-source disruption risk. |
| Dry Powder Inhaler Manufacturing Scale-Up | Propellant-free platforms align with EPA hydrofluoroalkane phasedown mandates and EMA bioequivalence standards. |
| Specialty Pharmacy Distribution Partnership | Direct-to-patient mail-order channels bypass wholesale intermediaries for COPD maintenance therapy refills. |
| Real-World Evidence Generation Program | Outcome data from connected devices supports integrated delivery network outcome guarantee contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists with secondary validation against FDA 505(b)(2) filings, EMA MDR submission databases, ClinicalTrials.gov protocols, and CMS Medicare Part B claims data. Bottom-up volume modeling across dosage forms and administration routes triangulated against top-down market sizing from pharmaceutical manufacturer revenue disclosures and government tender award announcements.
Segment-weighting approaches distributed value across beta-2 agonist, anticholinergic, methylxanthine, and combination drug chemistry classes, further subdivided by inhaler, nebulizer, dry powder, and oral tablet delivery modes. Patient population severity tiers and regional regulatory clusters shaped adoption curve assumptions across the projection horizon. CAGRs derived from historical volume trajectories adjusted for propellant transition timelines, generic entry waves, and procurement centralization velocity. Forecast inputs incorporated WHO Essential Medicines List procurement program commitments, EPA hydrofluoroalkane phasedown schedules, and integrated delivery network formulary consolidation patterns.
Revisions become necessary when FDA-EMA regulatory divergence on in vitro-in vivo correlation studies deepens, API supply disruptions materialize in coastal Chinese manufacturing zones, or connected inhaler real-world evidence standards shift among Medicare Advantage plans. Practitioners should monitor abbreviated new drug application queue lengths, propellant reformulation capital expenditure announcements, and integrated delivery network outcome-based contract penetration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Kidney Cancer Drugs Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
HPV Vaccines Market