
 Powder-Filled Hard Gelatin Capsules Market | 2026-2036
Powder-Filled Hard Gelatin Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Powder-Filled Hard Gelatin Capsules Market Analytics
Pharmaceutical-grade capsule specifications is rotating toward higher-barrier, lower-permeability configurations as chronic-dose therapies multiply. Lonza Group leverages its integrated gelatin-to-capsule supply chain to sustain quality consistency across high-volume contracts. ACG Worldwide anchors its position through dedicated capsule-shell manufacturing campuses serving Indian pharmaceutical exporters. Qualicaps differentiates via precision-filling technology leadership in low-dose, high-potency applications.
Powder-filled hard gelatin capsules are two-piece cylindrical shells composed primarily of animal-derived collagen hydrolysate, typically bovine or porcine, with moisture content controlled between 13% and 16% to maintain shell elasticity and prevent brittleness during high-speed filling operations; their primary commercial purpose is to enclose dry powder, granule, or pellet formulations for oral administration, offering taste masking and dose uniformity in pharmaceutical and nutraceutical products. Enteric-coated capsules command premium positioning as proton-pump inhibitors and enzyme therapies expand, while controlled-release capsules represent the fastest-growing configuration driven by once-daily dosing protocols in cardiovascular and psychiatric applications. Pharmaceutical-grade gelatin dominates margin pools due to validated supply chains and regulatory documentation burdens that exclude lower-tier competitors.
FDA dissolution standards and EMA cross-linking guidelines enforce gelatin-shell performance thresholds that filter subscale manufacturers from regulated markets, while India's CDSCO and China's NMPA are aligning local pharmacopeial requirements with ICH stability protocols to facilitate export certification. ISO 9001 and EXCiPACT certification now function as baseline market-access credentials rather than competitive differentiators. Stakeholders must monitor how plant-based capsule alternatives and revised pharmacopeial monographs reshape raw-material sourcing strategies and capital allocation for shell-manufacturing assets.
Market Dynamics
FDA and EMA tightening of dissolution and cross-linking standards is filtering subscale gelatin capsule manufacturers from regulated markets, while nutraceutical unit-dose demand and chronic-dose pharmaceutical protocols reshape capacity allocation across shell-production assets.
Growth Catalysts
- CDSCO-NMPA alignment with ICH stability protocols:Indian and Chinese regulators harmonizing export certification requirements enable contract manufacturers to access FDA and EMA markets without redundant stability testing, accelerating cross-border volume flows.
- Once-daily cardiovascular and psychiatric dosing protocols:Controlled-release capsule configurations capture preference from tablet and liquid formulations as patient adherence programs prioritize simplified regimens.
- Enteric-coated enzyme therapies:Proton-pump inhibitor expansion and digestive health positioning drive premium shell configurations that protect acid-labile actives through gastric transit.
Market Restraints
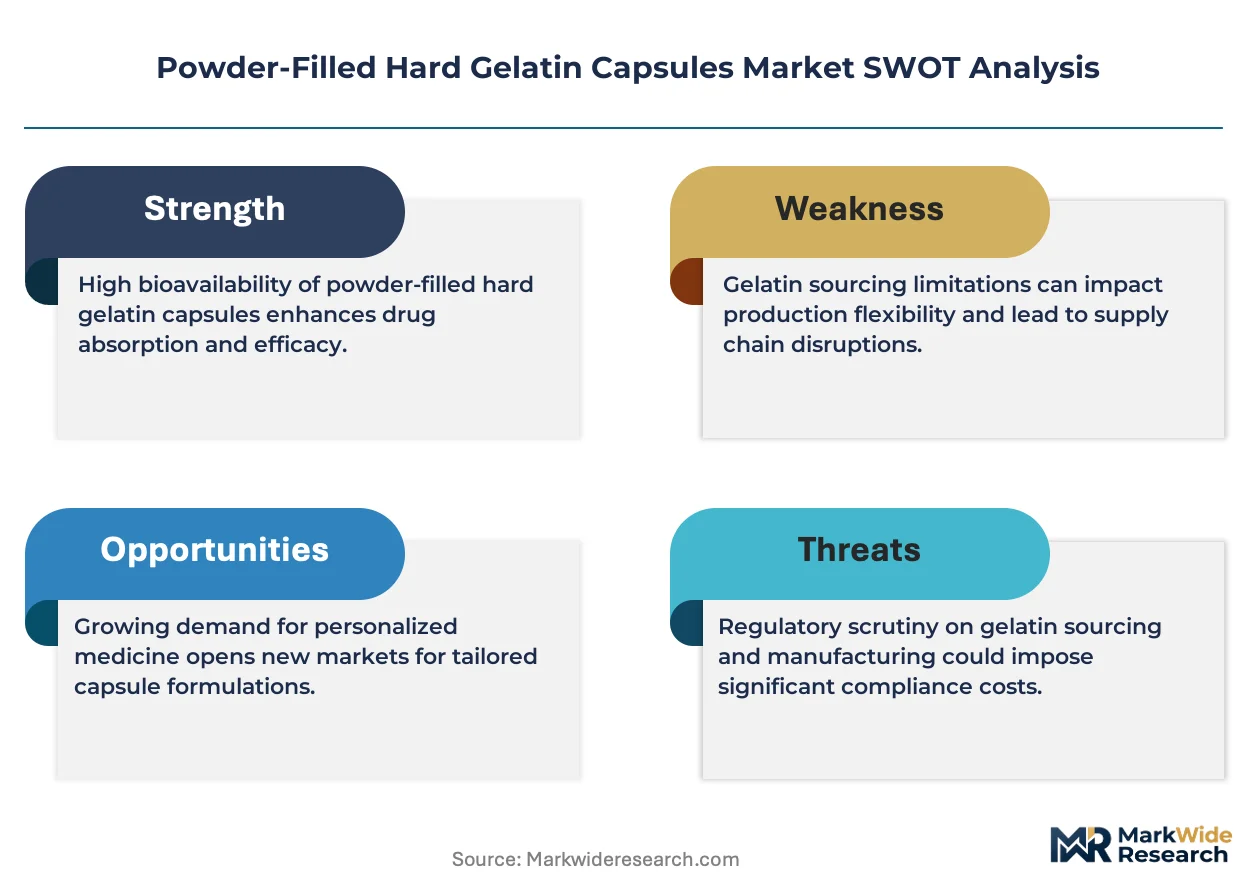
- Bovine and porcine gelatin supply concentration:Collagen hydrolysate raw material dependence on livestock processing creates input cost volatility and religious-dietary market exclusion risks.
- Plant-based capsule substitution:HPMC and pullulan alternatives displace gelatin in vegan-positioned nutraceuticals, compressing addressable share in wellness segments.
- EXCiPACT and ISO 9001 documentation burdens:Baseline certification requirements for regulated market access impose fixed compliance costs that exclude capital-constrained regional entrants.
Strategic Opportunities
- Precision-filling technology for high-potency APIs:Low-dose oncology and hormone therapies demand micro-dosing accuracy that conventional tamping cannot achieve, opening equipment-upgrade revenue streams.
- Direct-to-consumer nutraceutical channels:Subscription and e-commerce fulfillment models bypass wholesale pharmacy distribution, enabling capsule-format customization and shorter production runs.
- EU Green Deal sustainable sourcing mandates:Pharmaceutical-grade gelatin with verified supply-chain traceability captures premium positioning as ESG procurement criteria harden across European formulators.
Industry Challenges
- High-speed filling line technician scarcity:Automated capsule-filling equipment operation and die maintenance require specialized training pipelines that vocational programs have not scaled to match equipment deployment rates.
- Moisture-content validation complexity:Maintaining 13-16% shell elasticity across climate-variable manufacturing environments demands environmental control capital that mid-scale facilities struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder-Filled Hard Gelatin Capsules Market |
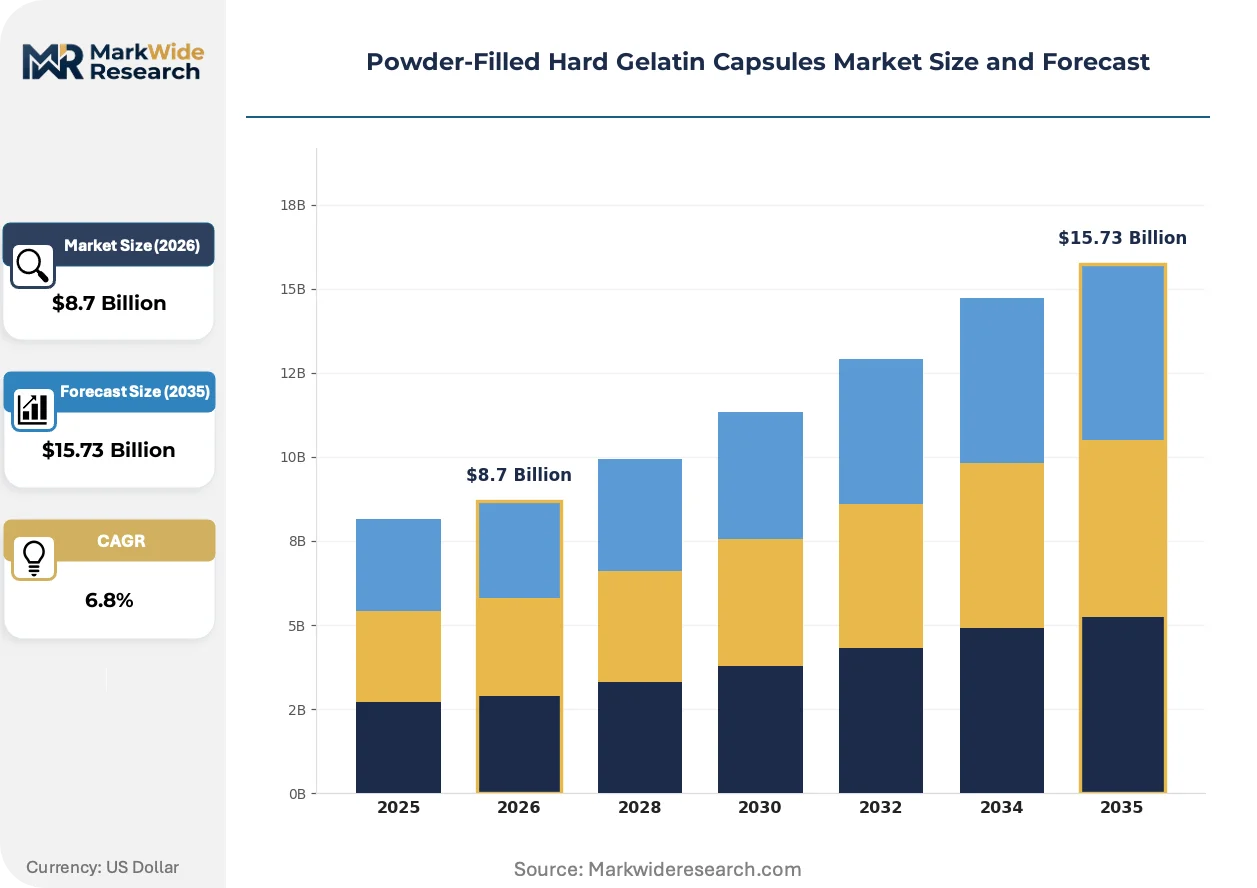
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Capsules, Enteric-Coated Capsules, Controlled-Release Capsules, Gelatin Capsules Grade: Pharmaceutical Grade, Food Grade, USP Grade, Custom Grade Application: Nutraceuticals, Pharmaceuticals, Dietary Supplements, Herbal Products Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Lonza Group, ACG Worldwide, Qualicaps, CapsCanada, Suheung Co., Ltd., Gelita AG, Bright Pharma Caps, Rottendorf Pharma, Sirio Pharma Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder-Filled Hard Gelatin Capsules Market Evolving Landscape
Shell-manufacturing technology, regulatory documentation protocols, and procurement criteria are converging to reward integrated supply-chain control and displace fragmented, specification-only suppliers from premium contract opportunities.
Precision-filling systems with real-time weight-check feedback loops are decomposing the traditional trade-off between throughput and dose uniformity. Oncology and hormone therapy formulators in Germany and Switzerland are adopting these systems for batch sizes below 50,000 units. The technology is compressing minimum efficient scale thresholds, enabling captive manufacturing for orphan-dose products that previously required tolling arrangements.
EMA revised pharmacopeial monographs on gelatin cross-linking are forcing accelerated stability protocol adoption across European manufacturing sites. The industrial consequence is a documentation burden shift from finished-product manufacturers to shell suppliers, who must now provide batch-specific dissolution performance data. Enteric-coated configurations face the tightest compliance timelines, with German and French regulators prioritizing proton-pump inhibitor capsule inspections.
Formulator procurement criteria now weight supply-chain traceability and ESG documentation alongside unit cost, displacing pure price-based vendor selection. Large pharmaceutical buyers in the United States and Netherlands are consolidating supplier panels to those with captive gelatin production or certified sustainable sourcing. This preference shift is most visible in cardiovascular chronic-dose contracts, where multi-year agreements increasingly specify bovine-source verification and carbon-footprint disclosure.
Powder-Filled Hard Gelatin Capsules Market Segmentation
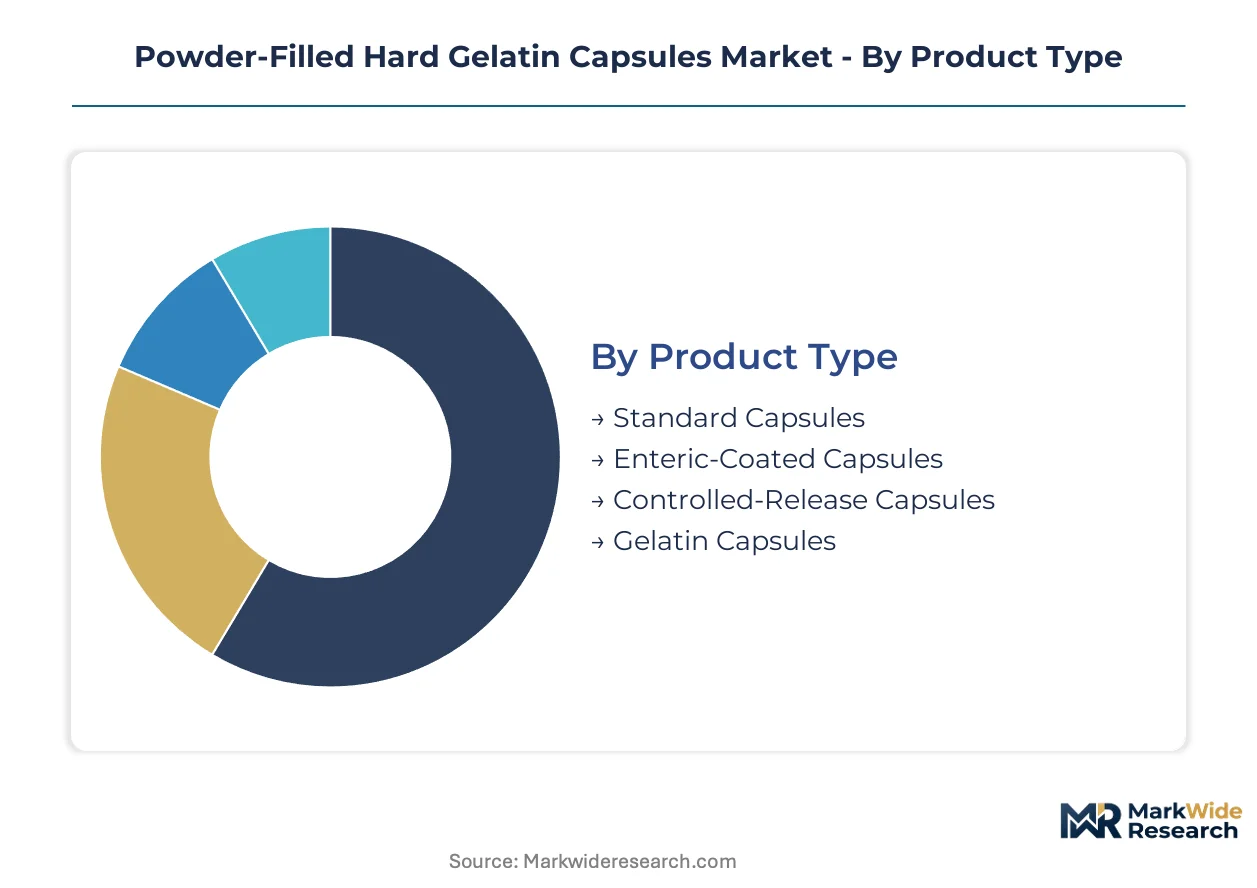
Segmentation in the Powder-Filled Hard Gelatin Capsules Market reflects divergent regulatory burdens and end-use specifications that reshape manufacturing priorities. Pharmaceutical-grade contracts demand validated supply chains and batch-specific dissolution documentation, while nutraceutical channels reward format flexibility and shorter production runs.
Product Type:
Domestic production concentrates on standard configurations for high-volume nutraceutical contracts, whereas export-led demand pulls toward specialized coatings that meet FDA and EMA dissolution thresholds.
- Standard Capsules:Two-piece cylindrical shells with 13-16% controlled moisture content serve as the baseline configuration for high-speed filling operations. Indian and Chinese contract manufacturers deploy these for bulk nutraceutical exports to North American and European direct-to-consumer channels where unit-cost sensitivity dominates procurement.
- Enteric-Coated Capsules:pH-resistant polymer coatings protect acid-labile actives through gastric transit for proton-pump inhibitors and enzyme therapies. German and Swiss formulators specify these for premium cardiovascular and digestive health portfolios where EMA cross-linking compliance commands supplier consolidation.
- Controlled-Release Capsules:Matrix or reservoir designs enable once-daily dosing protocols in psychiatric and cardiovascular applications.
- Gelatin Capsules:Animal-derived collagen hydrolysate shells retain cost advantages in pharmaceutical-grade contracts requiring validated bovine or porcine sourcing documentation.
Standard capsules hold the largest share; momentum sits with controlled-release configurations.
Grade:
Cost tiers separate validated pharmaceutical supply chains from commodity nutraceutical inputs, with documentation burdens determining market access rather than material composition alone.
- Pharmaceutical Grade:Bovine-derived collagen hydrolysate with complete batch traceability and regulatory documentation satisfies FDA and EMA stability requirements for chronic-dose therapies. CDSCO-aligned Indian exporters and NMPA-certified Chinese manufacturers concentrate capacity here to capture multi-year cardiovascular contracts from European formulators.
- USP Grade:United States Pharmacopeia-monographed specifications enable direct entry into regulated distribution without redundant testing. North American compounding pharmacies and institutional buyers specify this tier for hormone replacement and oncology micro-dosing applications where precision-filling technology intersects with documentation standards.
- Food Grade:Lower documentation burden suits wellness-positioned nutraceuticals with shorter shelf-life requirements.
- Custom Grade:Tailored moisture content and dissolution profiles address orphan-dose or niche therapeutic applications.
Pharmaceutical grade dominates revenue concentration; USP grade is expanding most quickly as harmonization reduces redundant certification costs.
Application:
Volume concentration in nutraceuticals contrasts with margin concentration in prescription pharmaceuticals, reshaping how shell manufacturers allocate coating and filling capacity.
- Pharmaceuticals:Chronic-dose cardiovascular and psychiatric protocols demand controlled-release and enteric-coated configurations with validated stability data. German, Swiss, and Dutch formulators consolidate supplier panels to integrated gelatin-to-capsule manufacturers who can provide batch-specific cross-linking performance documentation under EMA revised pharmacopeial monographs.
- Nutraceuticals:Unit-dose convenience positioning in subscription and e-commerce channels rewards format customization and shorter production runs. Indian and Chinese contract manufacturers scale standard capsule output here for North American and European direct-to-consumer wellness brands.
- Dietary Supplements:Mineral and vitamin formulations prioritize cost-efficient standard configurations with taste-masking functionality.
- Herbal Products:Traditional medicine positioning in Asian markets favors gelatin shells over plant-based alternatives for moisture-barrier performance.
Pharmaceuticals command premium positioning; nutraceuticals drive volume scale.
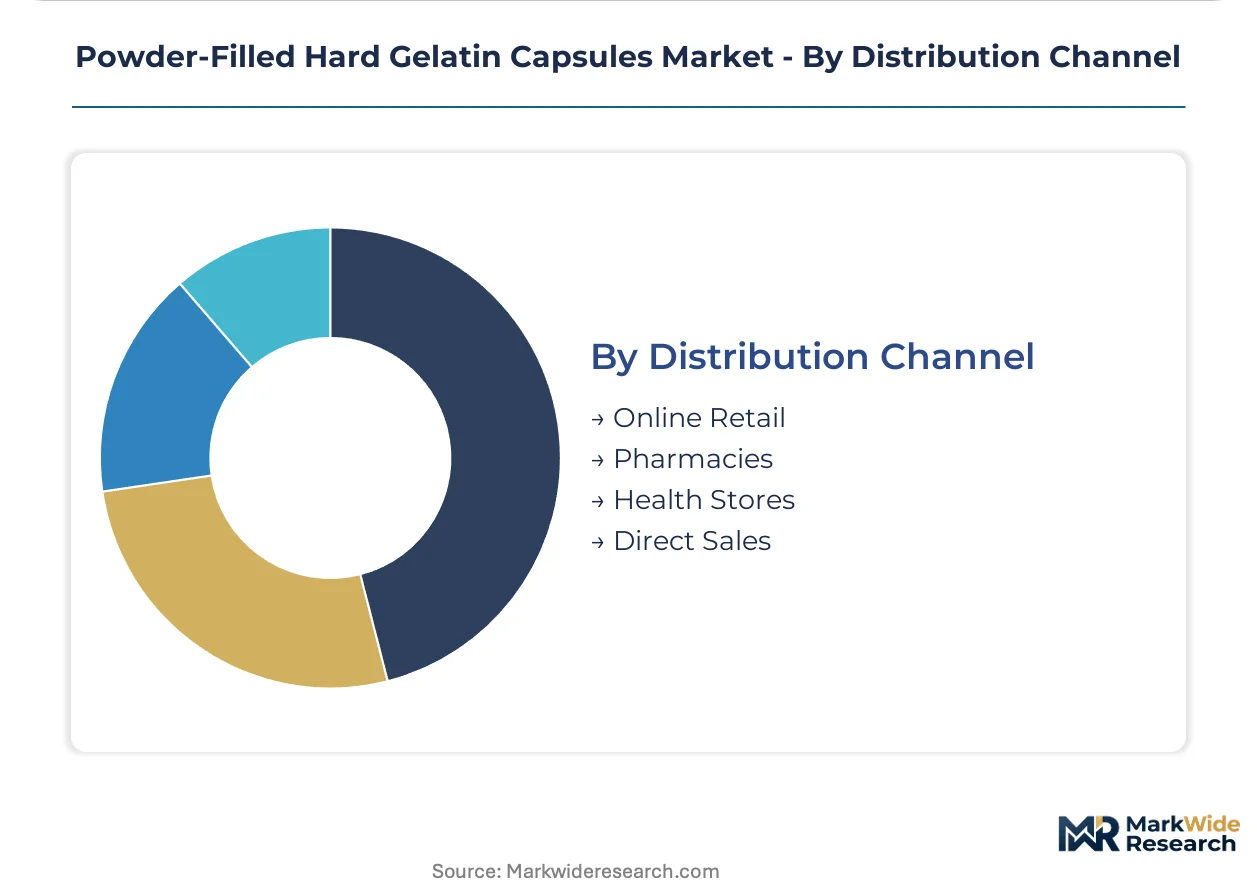
Distribution Channel:
Customer type fragmentation between institutional procurement and direct-to-consumer fulfillment reshapes order patterns from bulk long-term contracts to customized short runs.
- Pharmacies:Regulated dispensing channels in Germany, France, and the Netherlands require pharmaceutical-grade documentation and cold-chain stability validation. Multi-year agreements here increasingly specify bovine-source verification and carbon-footprint disclosure under EU Green Deal procurement criteria.
- Online Retail:Subscription and e-commerce fulfillment models enable capsule-format customization with shorter lead times. North American and European direct-to-consumer nutraceutical brands bypass wholesale pharmacy distribution to capture preference for unit-dose convenience.
- Health Stores:Wellness-focused retail positioning concentrates demand for food-grade and standard configurations.
- Direct Sales:Practitioner and clinic channels serve compounding pharmacies with USP-grade specifications for hormone and oncology applications.
Pharmacies anchor the largest volume commitment; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification requirements are redrawing regional production footprints as Indian and Chinese contract manufacturers scale capacity for FDA and EMA markets, while European formulators consolidate supplier panels around integrated gelatin-to-capsule producers with verified traceability documentation.
United States
Chronic-dose cardiovascular and psychiatric protocols drive demand for controlled-release configurations with validated dissolution profiles. FDA tightening of cross-linking standards filters subscale suppliers from multi-year pharmaceutical contracts. New Jersey and North Carolina manufacturing clusters concentrate precision-filling capacity for oncology micro-dosing applications.
Germany
EMA revised pharmacopeial monographs on gelatin cross-linking force accelerated stability protocol adoption across Bavarian and North Rhine-Westphalian manufacturing sites. The country's national pharmaceutical regulator prioritizes proton-pump inhibitor capsule inspections. Frankfurt and Munich formulators consolidate supplier panels to integrated manufacturers with batch-specific performance data.
India
CDSCO alignment with ICH stability protocols enables contract manufacturers to access regulated markets without redundant testing. The central drug regulator harmonizes export certification requirements with FDA and EMA standards. Gujarat and Maharashtra capsule-shell manufacturing campuses scale output for North American and European direct-to-consumer nutraceutical channels.
China
NMPA-certified manufacturers concentrate capacity on pharmaceutical-grade contracts requiring complete batch traceability documentation. The national medical products administration tightens local pharmacopeial requirements to facilitate export certification. Yangtze River Delta production clusters serve European formulators with validated bovine-sourcing disclosure under EU Green Deal procurement criteria.
Switzerland
Precision-filling technology adoption for low-dose oncology and hormone therapies reshapes equipment investment patterns. Swissmedic maintains stringent dissolution performance thresholds for enteric-coated configurations. Basel and Zurich pharmaceutical clusters specify shell suppliers with captive gelatin production and carbon-footprint documentation.
Powder-Filled Hard Gelatin Capsules Market Competitive Landscape
Concentration sits with integrated gelatin-to-capsule manufacturers who control upstream collagen hydrolysate supply chains and downstream filling capacity. The vendor base stratifies across three tiers: multinational integrated producers with captive raw material sourcing, regional specialists with coating and modification capabilities, and commodity standard-capsule fabricators serving high-volume nutraceutical contracts. Two dominant competitive moves define current positioning: backward integration into pharmaceutical-grade gelatin production to secure validated supply chains, and precision-filling technology licensing to capture orphan-dose and high-potency API contracts.
Within the integrated supply chain tier, Lonza Group and ACG Worldwide exemplify archetypes of vertically controlled production from collagen hydrolysate through finished shell manufacturing. Qualicaps occupies a position representing precision-filling technology leadership for low-dose, high-potency pharmaceutical applications. These three anchors demonstrate how regulatory documentation burdens and ESG procurement criteria are consolidating contract awards toward suppliers with verified traceability and batch-specific performance data rather than specification-only vendors.
| Leading Market Players |
|---|
| Lonza Group |
| ACG Worldwide |
| Qualicaps |
| CapsCanada |
| Suheung Co., Ltd. |
| Gelita AG |
| Bright Pharma Caps |
| Rottendorf Pharma |
| Sirio Pharma Co., Ltd. |
| Others |
Value Network & Pricing Analysis
High-volume filling-line throughput at Indian and Chinese contract manufacturers creates scale economies that compress unit costs for standard nutraceutical capsules while elevating price floors for pharmaceutical-grade configurations requiring validated bovine-sourcing documentation and batch-specific dissolution data.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Pharmaceutical-grade gelatin capsules with complete FDA and EMA documentation command substantial premiums over food-grade alternatives, while certification tier and volume scale serve as the primary price differentiation drivers. Cost compression in standard nutraceutical configurations is intensifying because Indian and Chinese manufacturers compete aggressively for North American direct-to-consumer contracts. Subscription wellness brands exhibit the highest price sensitivity, whereas European cardiovascular formulators purchasing multi-year controlled-release agreements demonstrate minimal elasticity.
Supply Chain Analysis
Inventory cycles for pharmaceutical-grade gelatin extend lead times beyond standard configurations due to batch-specific cross-linking validation requirements. Raw material supply concentrates in India, China, and Brazil as dominant sources of collagen hydrolysate from bovine and porcine processing. Shell manufacturing draws from livestock-derived gelatin, precision-filling equipment components, and pH-resistant polymer coatings for enteric configurations. Single-source vulnerability in bovine gelatin sourcing from specific geographic regions creates exposure to religious-dietary market exclusions and livestock disease outbreaks. Distribution runs through direct-to-e-commerce fulfillment for nutraceuticals and long-term pharmaceutical supply agreements with integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician pipelines for high-speed filling-line operation and die maintenance represent a critical capability gap that constrains capacity expansion across mid-scale manufacturing facilities in India and China.
For Market Incumbents: Compound defensive positioning through backward integration into pharmaceutical-grade gelatin production and precision-filling technology licensing. Lonza Group's captive collagen hydrolysate supply chain offers a template for insulating margin pools from raw material volatility. Plant-based capsule substitution from HPMC and pullulan alternatives threatens wellness-segment share, making certification investment in EMA-aligned stability protocols the essential lever for retaining European pharmaceutical contracts. For New Entrants and Emerging Players: Lead with precision-filling equipment deployment for orphan-dose oncology and hormone therapies where incumbent capacity concentrates on high-volume runs. The German and Swiss micro-dosing segments remain underpenetrated by mid-scale specialists lacking real-time weight-check feedback systems. Direct-to-consumer nutraceutical subscription channels offer the most penetrable entry point, with format customization and shortened production runs as the primary go-to-market angle against integrated giants optimized for bulk contracts. For Investors and Strategic Acquirers: Integrated shell manufacturers with captive gelatin production and verified EU Green Deal traceability documentation represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory documentation burdens hardening rather than easing across FDA, EMA, CDSCO, and NMPA jurisdictions. Watch for EMA revised pharmacopeial monograph implementation timelines as the inflection signal indicating accelerated supplier consolidation toward documented-batch providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gelatin Production | Captive bovine-sourcing documentation secures multi-year European cardiovascular contracts under EU Green Deal procurement criteria. |
| Precision-Filling Technology Licensing | Real-time weight-check systems capture German and Swiss orphan-dose oncology applications below 50,000-unit batch thresholds. |
| EMA Stability Protocol Acceleration | Batch-specific cross-linking performance data displaces specification-only vendors from proton-pump inhibitor capsule inspections. |
| Direct-to-Consumer Channel Expansion | Subscription fulfillment models bypass wholesale pharmacy distribution for North American nutraceutical unit-dose convenience positioning. |
| Certified Sustainable Sourcing Program | Carbon-footprint disclosure and bovine-source verification satisfy Dutch and German formulator ESG procurement requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA dissolution guidance documents, EMA pharmacopeial monograph revisions, CDSCO export certification protocols, and NMPA stability alignment notices. Primary interviews engaged capsule-shell manufacturing executives, pharmaceutical formulator procurement directors, high-speed filling-line equipment engineers, and nutraceutical brand supply chain managers. Secondary validation incorporated customs trade data for gelatin imports, SEC filings from integrated manufacturers, and ICH stability protocol documentation. Bottom-up capacity estimates from Indian and Chinese manufacturing campuses triangulate against top-down demand projections from cardiovascular and psychiatric therapy expansion.
Segmentation dimensions modeled include product type configuration, grade tier certification, therapeutic application, and distribution channel structure across the projection horizon. The analytical framework applies growth rate derivation from therapy-line expansion in chronic-dose cardiovascular and psychiatric protocols, precision-filling equipment deployment trajectories, and regulatory harmonization timelines between CDSCO-NMPA and ICH standards. CAGRs reflect volume-weighted capacity utilization assumptions and export certification flow acceleration from contract manufacturers to regulated markets.
Forecasts assume regulatory continuity in FDA, EMA, CDSCO, and NMPA jurisdictions; material policy shifts in cross-linking standards or gelatin sourcing restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Urinary Retention Drugs Market