
 Global Fondaparinux Market | 2026-2036
Global Fondaparinux Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fondaparinux Market Foresight
The gap between branded originator supply and commodity generic output is realigning competitive economics in the anticoagulant injectable space. Boehringer Ingelheim leverages its legacy chemistry expertise to sustain premium positioning against commoditized alternatives. Dr. Reddy's Laboratories anchors volume supply through aggressive cost positioning in regulated export markets. Jiangsu Hengrui Medicine differentiates via integrated heparinoid raw material access and captive fermentation capacity.
Fondaparinux is a synthetic pentasaccharide anticoagulant that selectively inhibits factor Xa without requiring antithrombin III cofactor activity, manufactured through multi-step carbohydrate synthesis with defined stereochemistry at five critical anomeric centers. Its primary purpose is prophylaxis and treatment of thromboembolic disorders in patients contraindicated for heparin therapy. The branded-generic split within product type shows margin pools concentrating in pre-filled syringe formats where delivery mode convergence reduces dosing error liability. Application demand clusters around venous thromboembolism prophylaxis as orthopedic and cancer surgery volumes expand, while biosimilar development remains structurally constrained by complex synthetic chemistry barriers.
FDA cGMP enforcement and EMA's MDR requirements for pre-filled injection devices are elevating validation burdens and extending approval timelines for new entrants. The EU F-Gas Regulation and US EPA solvent emission standards are reshaping manufacturing location decisions for multi-step organic synthesis operations. Stakeholders must monitor evolving pharmacovigilance requirements for generic injectable equivalence as regulators tighten immunogenicity surveillance thresholds.
Market Dynamics
Hospital formulary committees are consolidating anticoagulant purchasing around pre-filled syringe formats as liability concerns and dosing precision requirements intensify across acute care networks. This procurement convergence is compressing competitive differentiation to manufacturing reliability and regulatory pedigree rather than clinical messaging.
Growth Catalysts
- EMA MDR compliance deadlines:Device-level validation requirements for pre-filled injection systems are filtering out marginal suppliers and concentrating volume among qualified manufacturers.
- Orthopedic surgery expansion:Rising joint replacement volumes in aging populations are expanding prophylactic anticoagulant protocols in tertiary care centers.
- Heparin-induced thrombocytopenia protocols:Clinical guidelines recommending fondaparinux as first-line alternative in HIT-suspected patients are expanding addressable patient populations.
Market Restraints
- Carbohydrate precursor scarcity:Defined stereochemistry at five anomeric centers requires specialized starting materials with limited qualified suppliers.
- Multi-step synthesis cost structure:The 60-plus step manufacturing sequence creates fixed cost barriers that commodity chemistry cannot easily replicate.
- Direct oral anticoagulant substitution:Apixaban and rivaroxaban are capturing select VTE prophylaxis indications with oral convenience advantages.
Strategic Opportunities
- India CDSCO accelerated approval pathways:Streamlined generic injectable review timelines are opening faster market access for qualified exporters.
- Oncology surgery expansion:Cancer-related thrombosis prophylaxis represents an underpenetrated indication with distinct dosing regimens.
- EU F-Gas Regulation manufacturing relocation:Solvent emission constraints are incentivizing production migration to jurisdictions with compliant chemical processing infrastructure.
Industry Challenges
- Synthetic carbohydrate chemist scarcity:The specialized skill set for complex stereoselective synthesis commands premium compensation and limited talent pools.
- FDA cGMP inspection intensity:Heightened post-market surveillance of generic injectable facilities is extending remediation cycles and constraining capacity expansion timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fondaparinux Market |
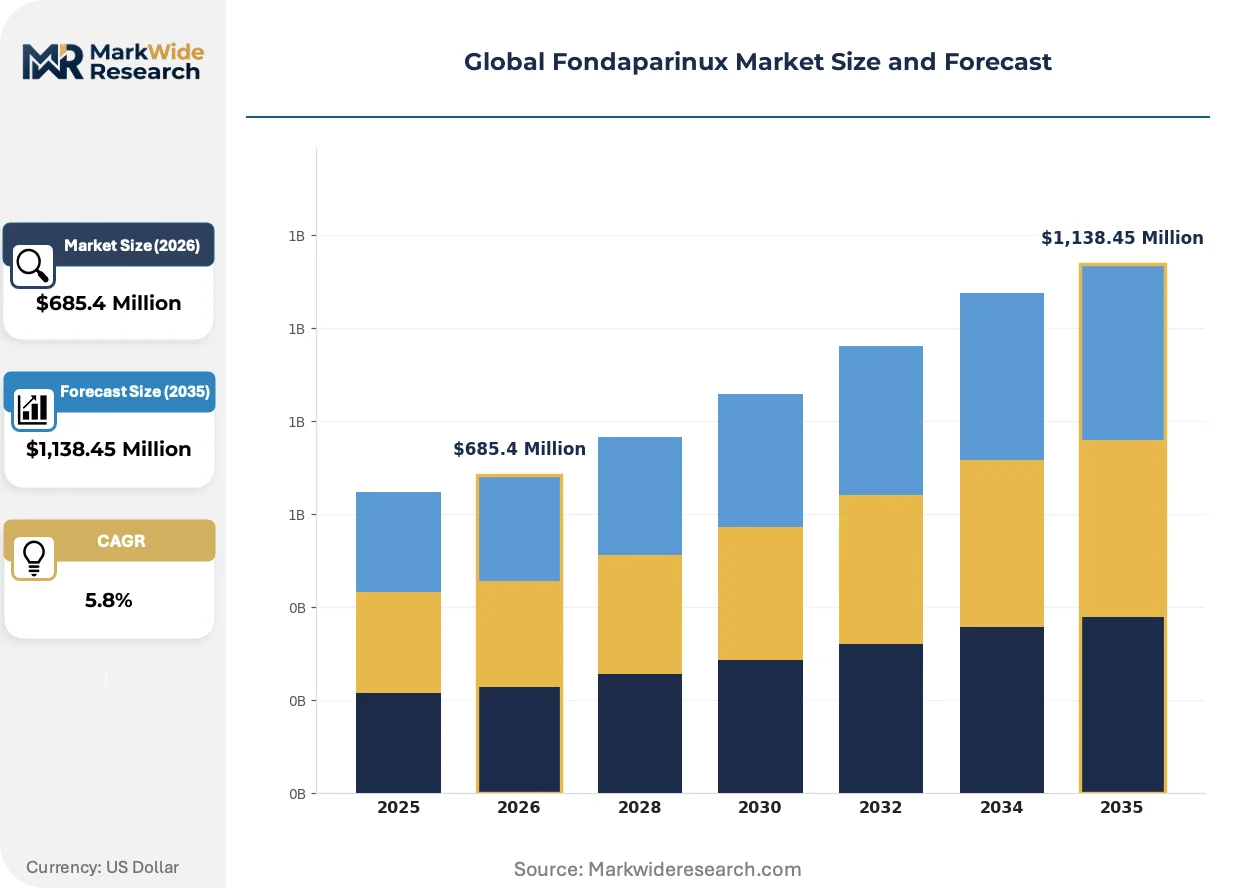
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fondaparinux Sodium Injection, Fondaparinux Generic, Fondaparinux Branded, Fondaparinux Biosimilars Application: Venous Thromboembolism, Acute Coronary Syndrome, Deep Vein Thrombosis, Pulmonary Embolism, Stroke Prevention End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Delivery Mode: Subcutaneous Injection, Intravenous Injection, Pre-filled Syringes, Vials |
| Companies Covered | Abbott Laboratories, Aurobindo Pharma, Dr. Reddy's Laboratories, Aspen Pharmacare, Jiangsu Hengrui Medicine, Viatris, Lupin Pharmaceuticals, Boehringer Ingelheim, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fondaparinux Market Shifts & Advancements
Continuous manufacturing approaches and advanced process analytical technology are displacing batch-wise synthetic paradigms in complex carbohydrate production, compressing cycle times and improving stereochemical consistency.
Continuous flow chemistry is rewriting the economics of multi-step fondaparinux synthesis by enabling real-time reaction monitoring and reduced solvent volumes. European contract manufacturers are piloting these systems for late-stage intermediate production. The technology is compressing the cost gap between originator and generic manufacturing while raising barriers for batch-dependent competitors.
EPA solvent emission standards are forcing manufacturing location decisions toward jurisdictions with compliant chemical processing infrastructure. Multi-step organic synthesis operations face capital relocation costs that favor established producers with diversified production footprints. Pre-filled syringe assembly is concentrating in FDA-registered facilities with demonstrated cGMP compliance histories.
Hospital purchasing consortiums are consolidating anticoagulant procurement around single-source contracts with guaranteed supply security. Group purchasing organizations are displacing fragmented distributor relationships with direct manufacturer agreements. This concentration is most visible in United States integrated delivery networks where formulary standardization reduces clinical variation.
Global Fondaparinux Market Segmentation
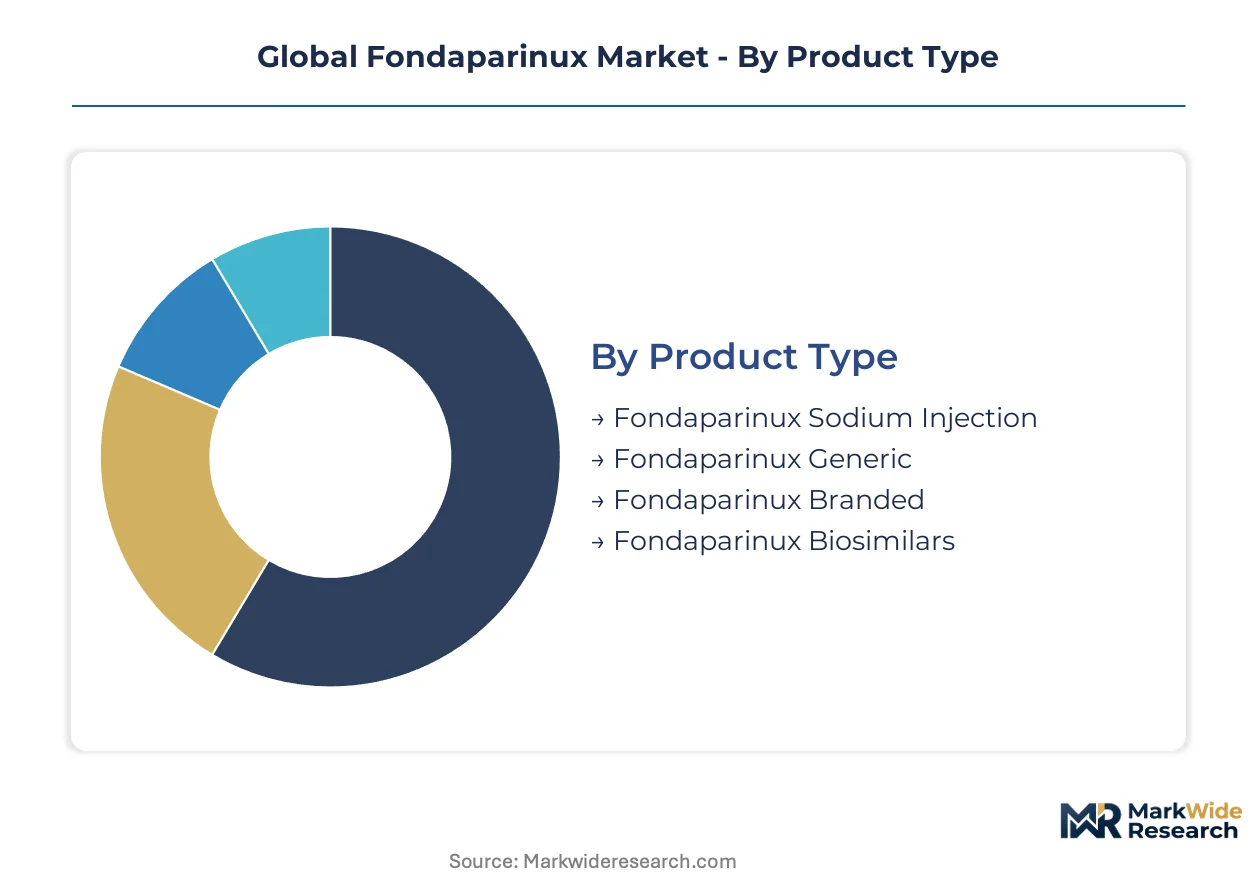
Segmentation in the fondaparinux market reveals how manufacturing complexity and regulatory validation create tiered competitive positions. Supply concentration varies dramatically across product formats and delivery modes, with pre-filled syringes commanding premium positioning due to FDA cGMP compliance requirements.
Product Type:
Supply concentration clusters around formats where synthetic chemistry expertise and regulatory pedigree create defendable positions against commodity competition.
- Fondaparinux Sodium Injection:The foundational API format requiring multi-step carbohydrate synthesis with defined stereochemistry at five anomeric centers. Hospital procurement in the United States concentrates here due to Medicare reimbursement alignment with low-molecular-weight heparin alternatives in orthopedic recovery.
- Fondaparinux Generic:Volume supply anchors through aggressive cost positioning in regulated export markets, with CDSCO accelerated approval pathways in India opening faster market access for qualified exporters facing EMA MDR compliance deadlines.
- Fondaparinux Branded:Boehringer Ingelheim leverages legacy chemistry expertise to sustain premium positioning against commoditized alternatives.
- Fondaparinux Biosimilars:Development remains structurally constrained by complex synthetic chemistry barriers that batch-dependent competitors cannot easily overcome.
Today's leader: Fondaparinux Sodium Injection. Tomorrow's challenger: Fondaparinux Generic.
Application:
Clinical indication demand maps directly to surgical volume expansion and thrombosis protocol evolution across acute care networks.
- Venous Thromboembolism:The dominant prophylaxis indication as orthopedic and cancer surgery volumes expand in aging populations. Tertiary care centers in the United States drive concentration through tightened VTE protocols.
- Acute Coronary Syndrome:Specialized anticoagulant protocols in cardiac catheterization labs favor precise dosing regimens that pre-filled syringe formats deliver.
- Deep Vein Thrombosis:Hospital formulary committees consolidate purchasing around single-source contracts with guaranteed supply security for this high-volume indication.
- Pulmonary Embolism:Emergency department protocols require rapid therapeutic intervention where subcutaneous delivery advantages apply.
- Stroke Prevention:Oncology surgery expansion creates underpenetrated demand with distinct dosing regimens separate from orthopedic applications.
Venous Thromboembolism commands current volume leadership, while Stroke Prevention in oncology settings gains share fastest.
End User:
Procurement authority concentration determines pricing power, with integrated delivery networks displacing fragmented distributor relationships.
- Hospitals:The dominant procurement channel where formulary standardization reduces clinical variation across United States integrated delivery networks. Group purchasing organizations consolidate anticoagulant purchasing around pre-filled syringe formats as liability concerns intensify.
- Ambulatory Surgical Centers:Rising joint replacement volumes in outpatient settings expand prophylactic anticoagulant protocols beyond traditional tertiary care.
- Clinics:Cancer-related thrombosis prophylaxis represents distinct dosing regimen requirements in community oncology practices.
- Diagnostic Laboratories:Heparin-induced thrombocytopenia testing protocols create pull-through demand for fondaparinux as first-line alternative in HIT-suspected patients.
Hospitals dominate procurement economics today. Ambulatory Surgical Centers represent the steepest expansion trajectory.
Delivery Mode:
Device-level validation requirements filter out marginal suppliers and concentrate volume among qualified manufacturers with demonstrated cGMP compliance histories.
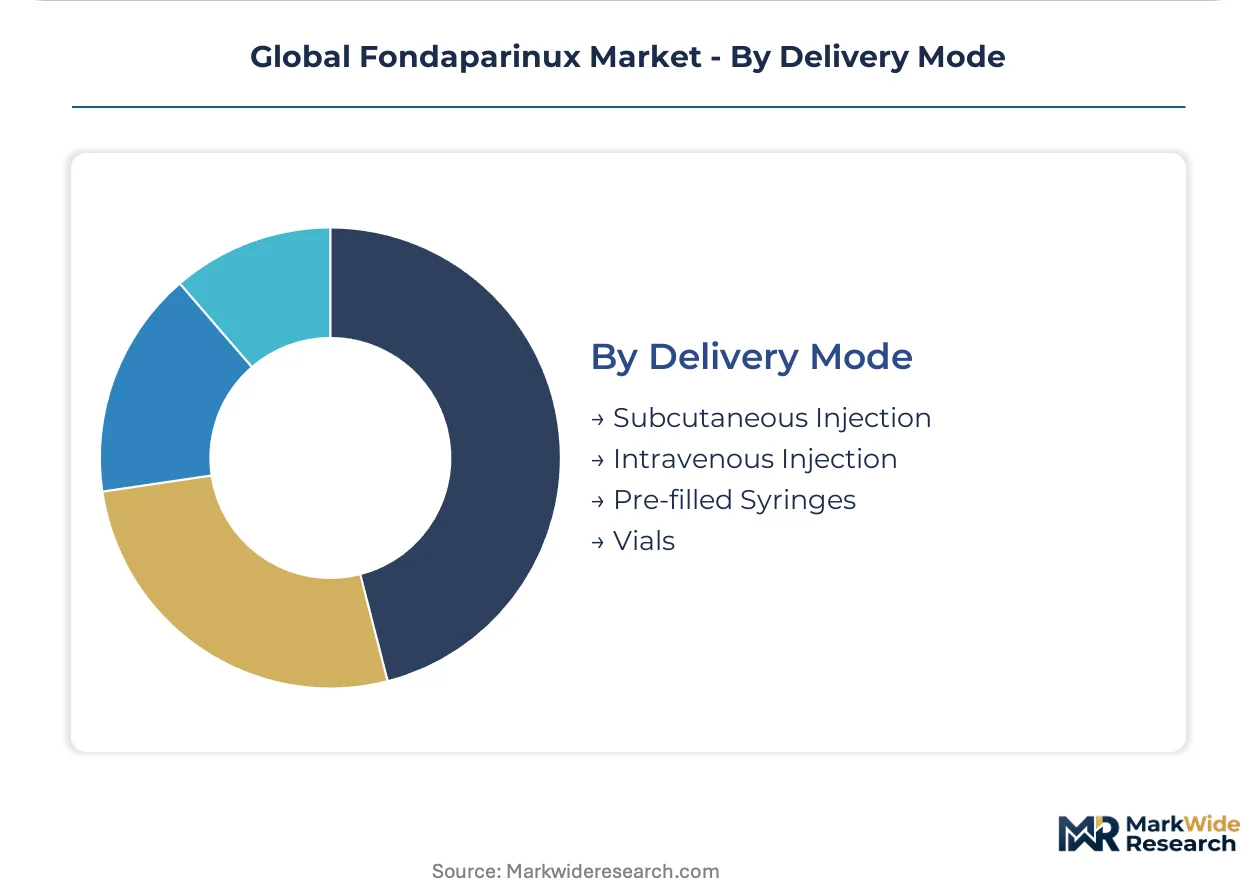
- Pre-filled Syringes:Margin pools concentrate here where delivery mode convergence reduces dosing error liability. FDA cGMP enforcement and EMA MDR requirements elevate validation burdens and extend approval timelines for new entrants.
- Subcutaneous Injection:The primary administration route for prophylactic regimens in orthopedic surgery recovery protocols.
- Intravenous Injection:Acute therapeutic applications in emergency and intensive care settings require precise concentration control.
- Vials:Multi-dose formats retain niche positioning in cost-sensitive institutional settings with dedicated pharmacy compounding capabilities.
Pre-filled Syringes anchor premium positioning now. Subcutaneous Injection formats in ambulatory settings climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic carbohydrate chemists cluster in Switzerland, Germany, and the United States, anchoring the specialized talent pools that manufacture complex pentasaccharide anticoagulants.
United States
Medicare reimbursement policies favor low-molecular-weight heparin alternatives in orthopedic surgery recovery, concentrating hospital procurement volume. FDA cGMP enforcement and post-market surveillance of generic injectables elevate manufacturing compliance costs. The Boston-Cambridge corridor hosts contract research organizations specializing in complex carbohydrate synthesis for pharmaceutical applications.
Germany
EMA MDR compliance deadlines for pre-filled injection devices filter out marginal suppliers and concentrate volume among qualified manufacturers. The EU F-Gas Regulation reshapes manufacturing location decisions for multi-step organic synthesis operations. The Rhine-Main industrial region maintains active pharmaceutical ingredient production infrastructure with solvent emission compliance capabilities.
Switzerland
Swissmedic regulatory pedigree supports premium positioning for originator manufacturers with legacy chemistry expertise. The country's pharmaceutical cluster benefits from integrated heparinoid raw material access through neighboring supply networks. Basel anchors fermentation capacity and synthetic carbohydrate production for anticoagulant supply chains.
India
CDSCO accelerated approval pathways for generic injectables open faster market access for qualified exporters facing EMA compliance deadlines. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad specialize in cost-positioned volume supply for regulated export markets. Domestic oncology surgery expansion creates pull-through demand for thrombosis prophylaxis.
China
NMPA regulatory harmonization with international standards enables domestic manufacturers to supply regulated export markets. Jiangsu Province anchors integrated heparinoid raw material access and captive fermentation capacity for pentasaccharide synthesis. The Yangtze River Delta concentrates pharmaceutical chemical processing infrastructure with expanding cGMP-compliant facilities.
Global Fondaparinux Market Competitive Landscape
Top-tier vendors anchor premium positioning through synthetic chemistry expertise and regulatory pedigree, while mid-tier generic manufacturers compete on cost positioning in regulated export markets. The competitive structure separates originator heritage players from commodity API suppliers and emerging biosimilar aspirants. Three archetypes dominate: legacy chemistry specialists with defined stereochemistry capabilities, volume-driven generic exporters leveraging accelerated regulatory pathways, and vertically integrated heparinoid producers with captive raw material access. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as manufacturers respond to solvent emission constraints and procurement consolidation.
Within the originator heritage tier, Boehringer Ingelheim exemplifies premium positioning sustained through multi-step carbohydrate synthesis expertise. Among volume-oriented generic exporters, Dr. Reddy's Laboratories occupies a position anchored by aggressive cost positioning in regulated markets, while Aurobindo Pharma represents the Indian pharmaceutical manufacturing archetype with CDSCO pathway access. Jiangsu Hengrui Medicine anchors the vertically integrated archetype through integrated heparinoid raw material control and captive fermentation infrastructure.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Aurobindo Pharma |
| Dr. Reddy's Laboratories |
| Aspen Pharmacare |
| Jiangsu Hengrui Medicine |
| Viatris |
| Lupin Pharmaceuticals |
| Boehringer Ingelheim |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Synthetic carbohydrate chemists cluster in Switzerland, Germany, and the United States, anchoring specialized talent pools that command premium compensation and widen spreads between originator and generic pricing tiers. Labor-cost differentials between Basel-based fermentation specialists and Hyderabad manufacturing clusters translate directly into three-tier pricing stratification across branded, qualified generic, and commodity injectable segments.
Pricing Analysis
Device-and-drug bundled contracts dominate hospital procurement, separating pre-filled syringe formats with EMA MDR validation from unbundled vial-and-needle alternatives. Price differentiation rests on FDA cGMP certification tier and captive heparinoid raw material access. Cost compression in the generic tier intensifies as CDSCO-approved Indian exporters flood regulated export markets with aggressive cost positioning. Ambulatory surgical centers exhibit highest price sensitivity, while United States integrated delivery networks prioritize supply security over unit cost.
Supply Chain Analysis
Carbohydrate precursor supply rests on Chinese heparinoid fermentation capacity, Swiss stereoselective synthesis expertise, and Indian API finishing infrastructure. Key inputs include porcine mucosa-derived heparin starting material, protected sugar intermediates with defined anomeric stereochemistry, and FDA-registered pre-filled syringe components. Single-source vulnerability concentrates in qualified suppliers for the 60-plus step synthesis sequence. Distribution runs through hospital group purchasing organizations with direct manufacturer agreements displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fondaparinux market represents a late-cycle quality story where procurement consolidation favors manufacturers with demonstrated regulatory pedigree over pure cost competitors. Demand is shifting toward pre-filled syringe formats with validated device-drug combinations as liability concerns intensify across acute care networks.
For Market Incumbents: Hedge against direct oral anticoagulant substitution by deepening oncology surgery indication coverage with distinct dosing regimens. Prioritize backward integration into heparinoid raw material supply through captive fermentation capacity additions in Jiangsu Province or Swiss Rhine-Main corridor expansion. Fortify FDA cGMP inspection readiness as post-market surveillance intensity extends remediation cycles.
For New Entrants and Emerging Players: Launch via CDSCO accelerated approval pathways targeting regulated export markets with EMA MDR compliance deadlines creating supply gaps. Penetrate the oncology surgery prophylaxis segment as an underpenetrated indication with distinct clinical protocols separate from orthopedic applications. Pursue contract manufacturing partnerships with European facilities piloting continuous flow chemistry to compress synthetic cost structures.
For Investors and Strategic Acquirers: Generic injectable specialists with demonstrated FDA inspection histories are the most active acquirer targets in this space. Long-term viability over a five-to-ten year window hinges on synthetic carbohydrate chemistry capabilities that resist commoditization. Monitor EMA MDR compliance deadline extensions as the critical inflection signal for supply consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Real-time reaction monitoring in flow chemistry compresses cycle times for multi-step pentasaccharide synthesis. |
| Backward Integration into Heparinoid Supply | Captive fermentation capacity insulates against porcine mucosa raw material price volatility and supply disruption. |
| EMA MDR Compliance Investment | Device-level validation for pre-filled syringes filters marginal competitors and concentrates volume among qualified manufacturers. |
| Oncology Surgery Indication Expansion | Cancer-related thrombosis prophylaxis offers distinct dosing regimens with limited direct oral anticoagulant competition. |
| Geographic Licensing Agreements | Partnerships with Indian CDSCO-registered manufacturers accelerate market access for regulated export destinations. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, India, and China, with primary inputs from each market cluster combined with secondary validation. Interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and GPO contracts managers informed demand-side dynamics. Secondary sources include FDA ANDA filings, EMA MDR submission databases, CDSCO approval records, and CMS Medicare reimbursement data. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and delivery mode segments.
Granularity-level modeling captured treatment line differentiation between prophylaxis and therapeutic dosing, dosage form variation across pre-filled syringe and vial formats, and regional regulatory cluster distinctions. CAGRs were derived through trend extrapolation anchored to surgical volume expansion and thrombosis protocol evolution across acute care networks. Industry-specific forecast inputs incorporated orthopedic surgery volume projections and heparin-induced thrombocytopenia protocol adoption curves.
Several conditions sit outside the modeled scope, including specific biosimilar development timelines and potential breakthroughs in oral pentasaccharide formulation. Forecasts reflect documented assumptions regarding regulatory pathway stability and raw material supply continuity. A small set of named triggers warrants ongoing watch: EMA MDR deadline extensions, EPA solvent emission standard revisions, and FDA cGMP inspection intensity fluctuations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market