
 Exocrine Pancreatic Insufficiency Therapeutics Market | 2026-2036
Exocrine Pancreatic Insufficiency Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Exocrine Pancreatic Insufficiency Therapeutics Market Intelligence
The high cost of clinical trials for biologic-based therapies is narrowing the field to well-capitalized firms. AbbVie leverages its extensive R&D infrastructure to develop next-generation enzyme replacement therapies. Nestlé Health Science specializes in nutritional support and medical foods that complement EPI treatment regimens. Viatris competes on the basis of its broad distribution network for established pancreatic enzyme products.
Exocrine Pancreatic Insufficiency therapeutics involve enzyme replacement therapy to correct maldigestion. These treatments typically use pancrelipase, a mixture of lipase, protease, and amylase derived from porcine pancreatic glands. Pancreatic enzyme supplements in enteric-coated micropellet form represent the dominant product type due to targeted delivery. While the cystic fibrosis indication drives significant R&D, chronic pancreatitis accounts for a larger patient volume.
Market access is governed by stringent efficacy and safety standards set by the US FDA and the European Medicines Agency (EMA). These bodies mandate specific potency assays for enzyme activity. In Japan, the PMDA imposes additional requirements for clinical trial data specific to its population. Future competition will hinge on developing non-porcine derived enzymes to address religious, cultural, and supply chain concerns.
Market Dynamics
The market's central dynamic is the tension between established porcine-derived enzyme therapies and the pressing need for alternatives. This pressure stems from supply chain vulnerabilities tied to animal sourcing, alongside cultural and religious objections, forcing a re-evaluation of long-standing production methods.
Growth Catalysts
- Favorable Regulatory Pathways:Orphan drug designations from bodies like the US FDA and EMA provide incentives, including market exclusivity and reduced fees, which accelerate the development and approval of novel therapies for exocrine pancreatic insufficiency.
- Expanding Patient Demographics:An increasing diagnostic prevalence of chronic pancreatitis globally is expanding the primary patient base beyond the traditional cystic fibrosis population, creating a larger addressable market for enzyme replacement therapies.
- Advanced Diagnostic Infrastructure:Healthcare systems in developed nations, particularly Germany and the United States, possess advanced imaging and functional testing capabilities, leading to earlier and more accurate diagnosis of EPI and subsequent treatment initiation.
Market Restraints
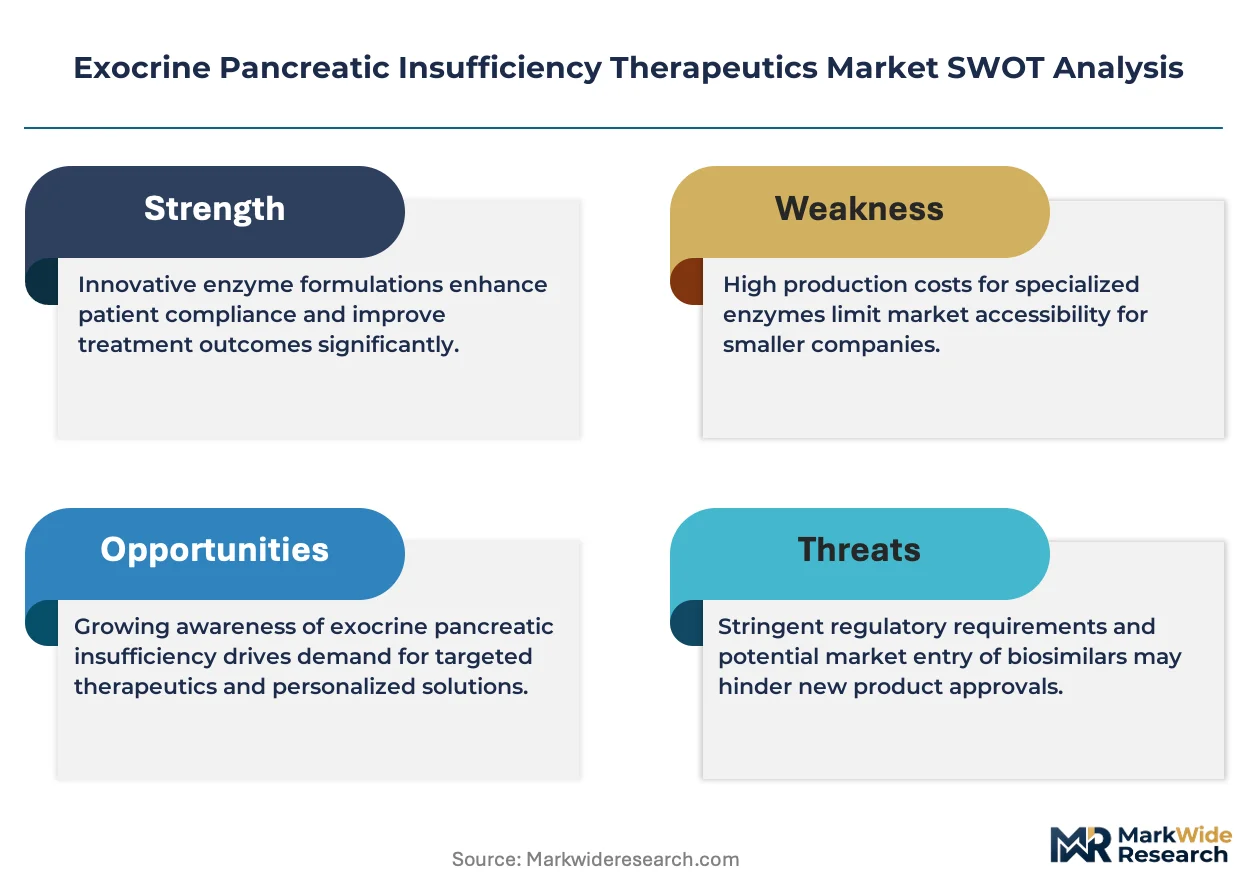
- Biological Source Dependency:The industry's heavy reliance on porcine pancreatic glands as the raw material for pancrelipase creates significant supply chain concentration risk and vulnerability to animal diseases and sourcing fluctuations.
- High Development Costs:The substantial financial investment required for conducting clinical trials for biologic-based therapies, including complex efficacy and safety studies, limits market participation to large, well-capitalized pharmaceutical companies.
- Stringent Potency Standards:Regulatory mandates from the FDA and EMA requiring strict, validated potency assays for lipase, protease, and amylase activity in each batch create a high bar for manufacturing consistency and can delay product release.
Strategic Opportunities
- Non-Porcine Enzyme Development:Investing in recombinant or microbial-derived enzymes presents a significant opportunity to address religious and cultural sensitivities, mitigate supply chain risks, and potentially improve product consistency and efficacy.
- Geographic Expansion:As diagnostic capabilities improve in markets across the Asia-Pacific region, there is a clear opportunity for market entry and expansion to serve a large, currently underdiagnosed patient population.
- Indication Expansion:Research into the efficacy of pancreatic enzyme replacement therapy for other malabsorptive conditions, such as post-pancreatic surgery or in certain gastrointestinal disorders, could open new revenue streams.
Industry Challenges
- Batch Consistency and Quality Control:A persistent operational challenge is ensuring uniform enzymatic potency across different production lots of a biologically derived product, which demands sophisticated and costly quality assurance protocols.
- Patient Adherence Complexities:Securing patient compliance with treatment regimens, which require precise timing of enzyme intake with meals and snacks, remains a significant hurdle to achieving optimal clinical outcomes.
- Specialized Talent Scarcity:The development of next-generation therapies requires highly specialized expertise in biotechnology and enzymology, and a shortage of qualified professionals can hinder innovation and scale-up efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exocrine Pancreatic Insufficiency Therapeutics Market |
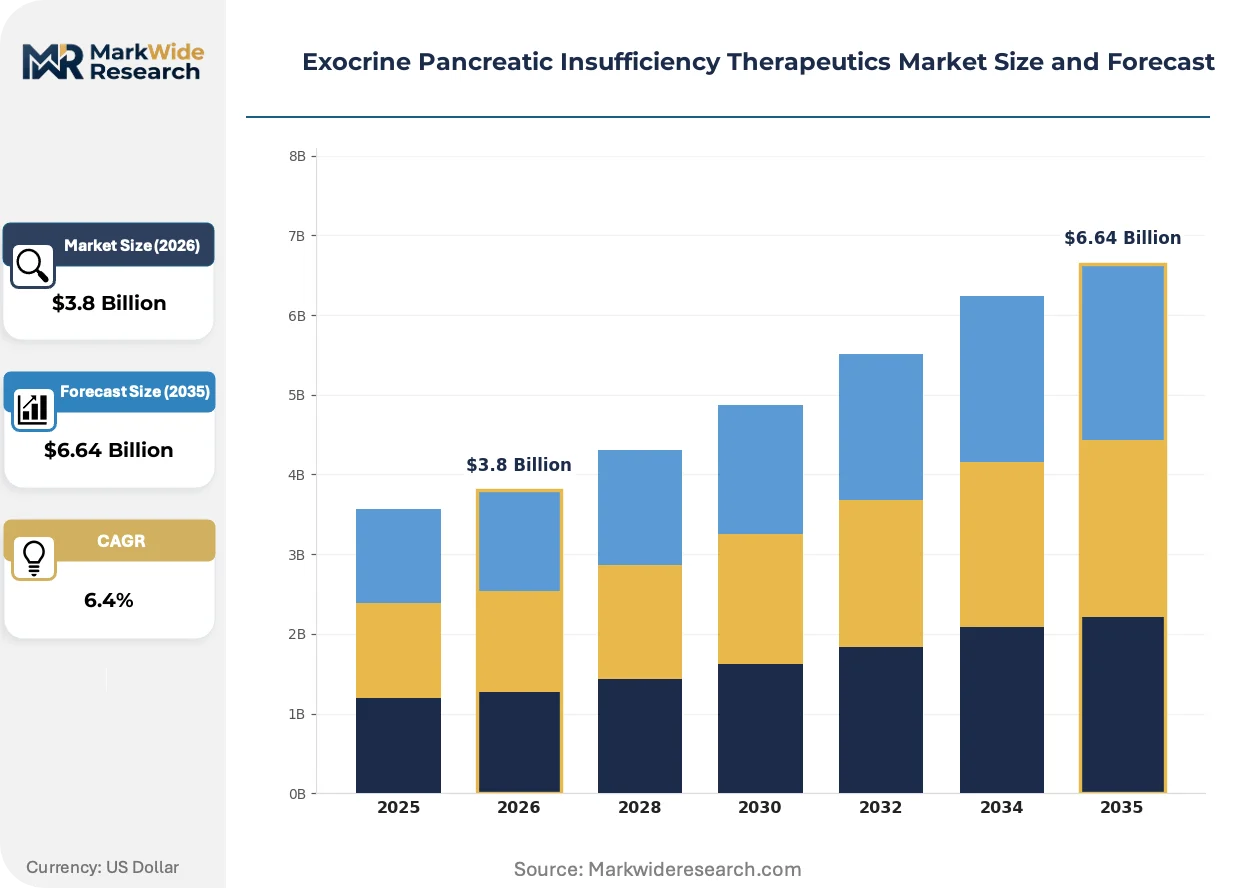
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digestive Enzymes, Acid Reducers, Proton Pump Inhibitors, Pancreatic Enzyme Supplements Indication: Cystic Fibrosis, Chronic Pancreatitis, Pancreatic Cancer, Post-Gastrointestinal Surgery End User: Specialty Clinics, Ambulatory Surgical Centers, Home Healthcare Providers, Diagnostic Laboratories Delivery Mode: Oral Capsules, Oral Tablets, Powder Formulations, Enteric-Coated Micropellets |
| Companies Covered | AbbVie, Abbott Laboratories, Nestlé Health Science, Viatris, Vivus, Chiesi Farmaceutici, Nordmark Arzneimittel, Digestive Care Inc., AzurRx BioPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exocrine Pancreatic Insufficiency Therapeutics Market Strategic Shifts & Innovations
The evolution from animal-sourced materials to biotechnologically engineered solutions is the defining trend. This shift is driven by a convergence of factors including the need for greater supply chain security, improved product consistency, and the desire to circumvent cultural or dietary restrictions associated with porcine products.
Recombinant enzyme technology enables the production of specific human lipases in controlled bioreactor environments. Biopharmaceutical developers are pursuing this avenue for patient populations with specific allergies or for whom porcine products are unsuitable. This controlled, scalable production method is rendering obsolete the industry's historical dependence on the volatile supply and inherent biological variability of animal-gland sourcing.
Guidance from the European Medicines Agency (EMA) has intensified scrutiny on the quality control of biologically-sourced active substances. This regulatory pressure compels manufacturers to adopt more advanced analytical methods to prove batch-to-batch consistency for pancrelipase. The chronic pancreatitis segment is most affected, as long-term treatment demands reliable product potency to ensure sustained efficacy and patient safety.
A notable shift is occurring from fragmented, individual gastroenterologist-led care toward integrated treatment within specialized, multidisciplinary centers. This model consolidates prescribing decisions and standardizes protocols, disrupting the traditional physician detailing approach. This centralization of patient management is most visible in the United States and parts of Western Europe, where complex cases are co-managed with nutritionists and other specialists.
Exocrine Pancreatic Insufficiency Therapeutics Market Segmentation
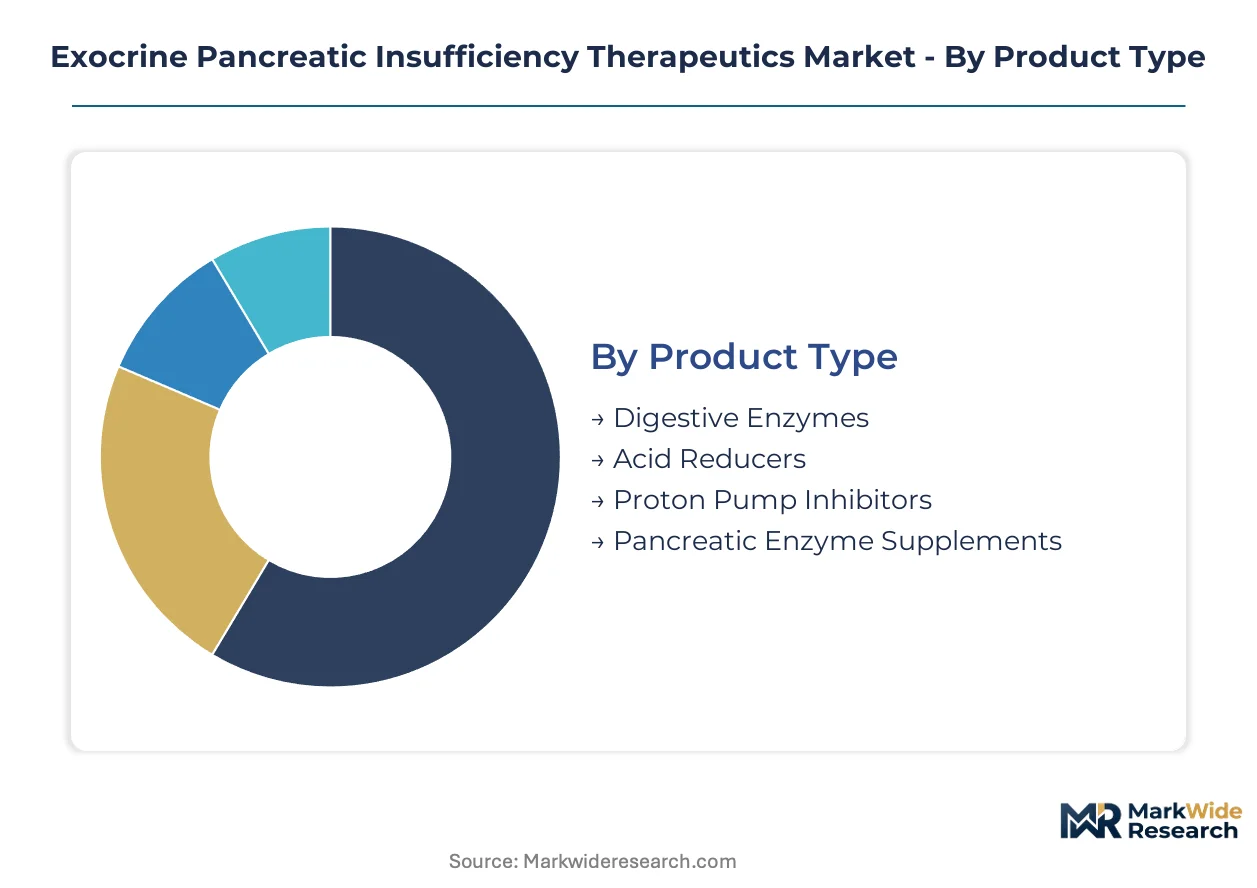
The Exocrine Pancreatic Insufficiency Therapeutics Market is segmented to provide a granular view of product types, indications, end-user settings, and delivery modes. This segmentation highlights the diverse approaches to managing maldigestion and the evolving patient care landscape. Understanding these distinct segments is crucial for identifying areas of concentrated demand and emerging therapeutic preferences.
Product Type:
The product type segment illustrates the varying turnover rates of therapeutic components, with established enzyme formulations seeing consistent, high-volume demand. Newer formulations and adjunctive therapies exhibit different adoption cycles driven by clinical guidelines and patient needs.
- Pancreatic Enzyme Supplements:These are the cornerstone of EPI treatment, primarily consisting of pancrelipase derived from porcine pancreatic glands, formulated to replace deficient digestive enzymes. Demand for these supplements is consistently high in developed healthcare systems like the United States and Germany due to established treatment protocols.
- Digestive Enzymes:This broader category includes various enzymes beyond pancrelipase, sometimes used as adjunctive therapy or for milder forms of maldigestion. Research into non-porcine derived options aims to address supply chain vulnerabilities and cultural sensitivities, influencing future product development.
- Acid Reducers:These medications, often proton pump inhibitors or H2 blockers, are prescribed to optimize the efficacy of pancreatic enzymes by reducing gastric acid degradation.
- Proton Pump Inhibitors:Specifically designed to suppress gastric acid production, these are frequently co-administered with enzyme replacement therapy to ensure enzyme stability in the stomach.
Pancreatic Enzyme Supplements dominates installed base. Digestive Enzymes is where expansion concentrates.
Indication:
This segment categorizes EPI therapeutics by the underlying condition, revealing distinct patient volumes and R&D investment priorities. Patient demographics and disease progression dictate the specific therapeutic requirements across these indications.
- Chronic Pancreatitis:This condition represents the largest patient volume for EPI therapeutics, driven by increasing diagnostic prevalence globally, particularly in developed nations. Long-term management requires reliable and consistent enzyme replacement therapy to prevent malnutrition and improve quality of life.
- Cystic Fibrosis:A genetic disorder where EPI is a common complication, this indication drives significant research and development into highly potent and stable enzyme formulations. Strict regulatory standards from the FDA and EMA ensure product quality for this vulnerable patient population.
- Pancreatic Cancer:EPI frequently develops in patients with pancreatic cancer, either due to the tumor itself or as a consequence of surgical interventions.
- Post-Gastrointestinal Surgery:Patients undergoing pancreatectomy or other complex gastrointestinal surgeries often experience iatrogenic EPI, necessitating enzyme supplementation for proper nutrient absorption.
Chronic Pancreatitis holds the largest patient base. Cystic Fibrosis attracts the most intensive research and development efforts.
End User:
The end-user segment highlights the varied settings where EPI therapeutics are prescribed and administered, reflecting different care models and patient access points. Integrated treatment within specialized centers is increasingly central to patient management.
- Specialty Clinics:These facilities, often focusing on gastroenterology or hepatology, manage the majority of EPI diagnoses and long-term treatment plans. Integrated care models in these clinics, particularly in the United States and Germany, consolidate prescribing decisions and standardize protocols.
- Home Healthcare Providers:As chronic disease management shifts towards patient-centric models, home healthcare providers play an increasing role in monitoring adherence and supporting patients with long-term EPI therapy. This trend improves patient convenience and continuity of care.
- Ambulatory Surgical Centers:These centers handle surgical procedures that may lead to EPI, such as certain pancreatic resections, initiating short-term or long-term enzyme replacement therapy post-operation.
- Diagnostic Laboratories:Essential for confirming EPI diagnoses through various functional tests, these laboratories underpin the initial identification of patients requiring therapeutic intervention.
Specialty Clinics remain the primary point of care. Home Healthcare Providers are expanding their role in long-term patient management.
Delivery Mode:
This segment differentiates therapies by their physical form and how they are administered, with a clear preference for formulations that optimize enzyme delivery and efficacy. Innovation focuses on improving bioavailability and patient compliance.
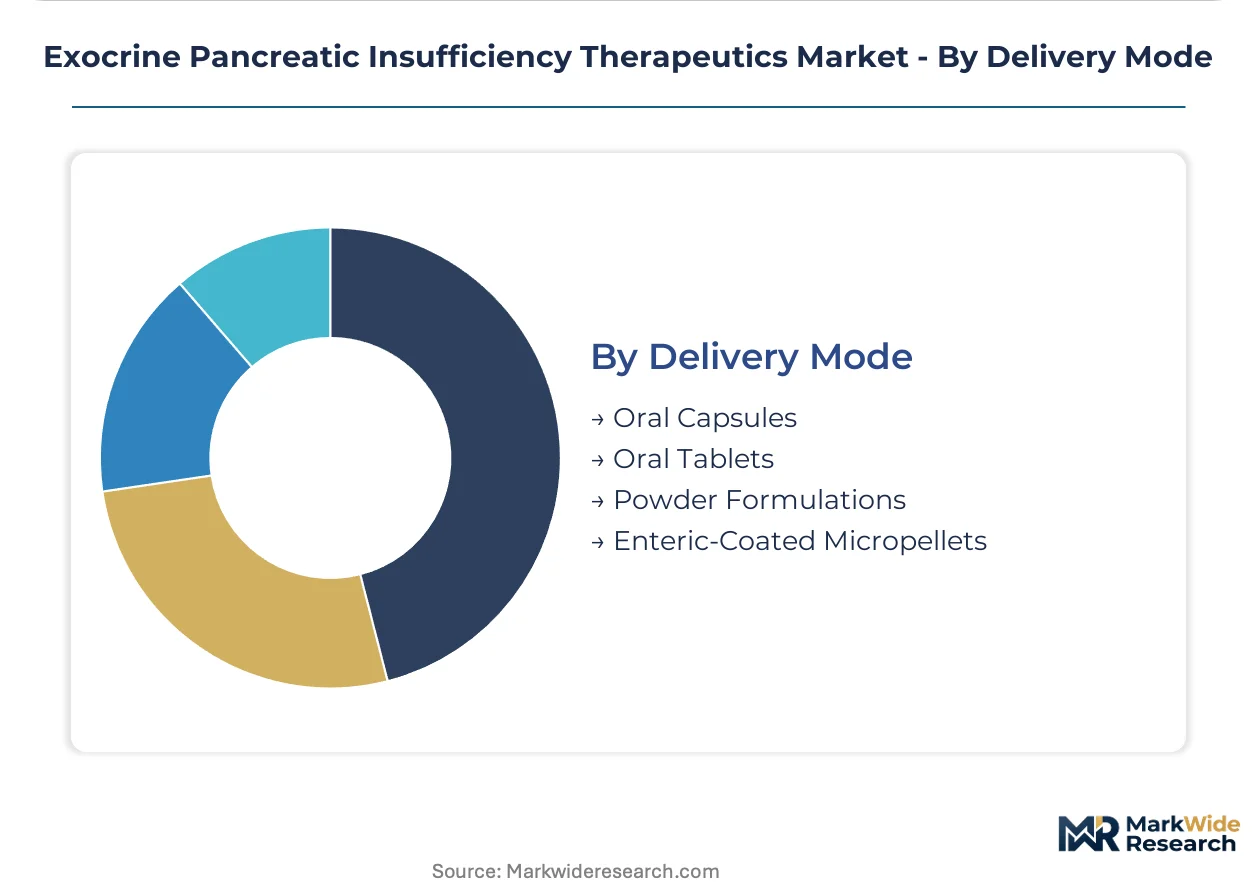
- Enteric-Coated Micropellets:These represent the dominant product type due to their targeted delivery, protecting enzymes from gastric acid and releasing them efficiently in the small intestine. This formulation ensures consistent enzyme activity, crucial for sustained therapeutic effect.
- Oral Capsules:A common delivery method for various digestive enzymes, offering ease of administration and dosage flexibility. Many pancrelipase products are available in capsule form, often containing micropellets or microspheres.
- Powder Formulations:Primarily used for pediatric patients or individuals with swallowing difficulties, these formulations can be mixed with food or liquids.
- Oral Tablets:While less common for pancrelipase due to challenges in protecting enzymes from stomach acid, some adjunctive digestive enzyme products are available in tablet form.
Enteric-Coated Micropellets are the most widely prescribed due to their efficacy. Oral Capsules offer broad patient applicability and convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Favorable regulatory pathways, particularly orphan drug designations from the US FDA and European Medicines Agency, significantly accelerate novel therapy development. These incentives drive investment across key regions with advanced healthcare infrastructure. High diagnostic rates in developed nations further expand the addressable patient base.
United States
The United States exhibits strong demand for EPI therapeutics, driven by high chronic pancreatitis diagnoses. FDA regulations, including orphan drug provisions, streamline market entry for new treatments. Major pharmaceutical clusters in states like New Jersey and Massachusetts focus on biopharmaceutical R&D.
Germany
Germany's advanced diagnostic infrastructure contributes to a significant patient volume for exocrine pancreatic insufficiency. The European Medicines Agency (EMA) sets stringent efficacy and safety standards for enzyme replacement therapies. Integrated care models in cities like Berlin and Munich centralize patient management.
Japan
Japan's market for EPI therapies is shaped by specific clinical trial data requirements from the Pharmaceuticals and Medical Devices Agency (PMDA). A growing elderly population contributes to increasing incidence of chronic pancreatitis. Research centers in Tokyo and Osaka explore non-porcine derived enzyme solutions.
China
Expanding patient demographics in China present a substantial geographic expansion opportunity for EPI therapeutics. The National Medical Products Administration (NMPA) is streamlining approval processes for essential medicines. Pharmaceutical manufacturing hubs in Shanghai and Guangzhou are scaling up local production capabilities.
India
India offers a large, currently underdiagnosed patient population, representing a clear opportunity for market entry. The Central Drugs Standard Control Organization (CDSCO) is working to standardize drug quality and accessibility. Biotechnology parks in Hyderabad and Bengaluru are attracting investment for novel enzyme development.
Exocrine Pancreatic Insufficiency Therapeutics Market Key Industry Players
On the supply side, the industry is tiered, with well-capitalized pharmaceutical firms alongside specialized nutritional support providers. Large companies leverage extensive R&D infrastructure for next-generation enzyme replacement therapies. Other players compete through broad distribution networks for established pancreatic enzyme products. Strategic partnerships and portfolio diversification are common competitive moves.
Specialists in specific therapeutic approaches anchor segments of the market. AbbVie exemplifies firms investing heavily in research and development for next-generation enzyme replacement therapies, leveraging its extensive R&D infrastructure. Nestlé Health Science represents companies focused on nutritional support and medical foods that complement EPI treatment regimens. Viatris occupies the segment focused on broad distribution networks for established pancreatic enzyme products, ensuring wide market access.
| Leading Market Players |
|---|
| AbbVie |
| Abbott Laboratories |
| Nestlé Health Science |
| Viatris |
| Vivus |
| Chiesi Farmaceutici |
| Nordmark Arzneimittel |
| Digestive Care Inc. |
| AzurRx BioPharma |
| Others |
Cost & Logistics Intelligence
Biological source dependency creates pricing tier spreads and shapes the supply chain for exocrine pancreatic insufficiency therapeutics. This reliance on animal-derived raw materials introduces volatility and influences manufacturing costs, which directly impacts product pricing across different formulations.
Pricing Analysis
FDA and EMA efficacy standards create the primary spread in pricing for EPI therapeutics. Per-unit transactional pricing dominates for established pancreatic enzyme supplements. Price differentiation drivers include formulation complexity, such as enteric-coated micropellets, and brand premium for well-known products. Pricing softness stems from generic competition for older formulations, compelling manufacturers to innovate. Healthcare systems are highly price-sensitive for established products, while specialty clinics prioritize efficacy for novel therapies.
Supply Chain Analysis
Upstream feedstock, specifically porcine pancreatic glands, forms the critical base of the EPI therapeutics supply chain. Geographic supply concentration for these glands centers on the United States and Germany, where large-scale pork production facilitates sourcing. Raw material dependencies include porcine pancreatic glands and specialized enteric coating materials. Single-source vulnerability to animal diseases or agricultural policy shifts represents a significant supply chain risk. Distribution runs through a network of pharmaceutical wholesalers and specialty pharmacy channels to reach end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment for established enzyme replacement therapies creates a defensive moat in this market. Stringent approval processes and the need for consistent efficacy ensure a stable demand base for approved products, making it less susceptible to rapid disruption.
For Market Incumbents: Entrench market position by diversifying enzyme sourcing beyond porcine glands, actively investing in recombinant or microbial-derived alternatives. Pursue advanced formulation technologies to enhance product stability and patient adherence, mitigating threats from emerging recombinant enzyme therapies. Focus R&D on next-generation enzymes and secure certification investments for novel delivery systems to maintain a competitive edge against supply chain vulnerabilities.
For New Entrants and Emerging Players: Build out specialized portfolios targeting unmet needs, particularly for patients with cultural or religious sensitivities to porcine-derived products. The Asia-Pacific region presents a significant white-space opportunity due to its large, underdiagnosed patient population. Develop non-porcine enzyme solutions and establish partnerships with local diagnostic centers for effective market penetration and patient identification.
For Investors and Strategic Acquirers: FDA orphan drug designations and EMA incentives reshape the acquisition landscape, favoring innovative biotechnology firms. The long-term viability of this market rests on sustained demand for chronic disease management. Target biotechnology companies specializing in recombinant enzyme development or firms with robust distribution networks in emerging markets. Successful Phase 3 trials for non-porcine therapies represent a critical signal to watch as an inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates approval for novel recombinant enzymes, addressing supply chain and cultural concerns. |
| Regulatory Approval Pathway | Secures market access for non-porcine therapeutics, validating their safety and efficacy. |
| Manufacturing Scale-Up | Ensures consistent, high-volume production of biotechnologically engineered enzymes. |
| Geographic Expansion | Penetrates underdiagnosed markets, particularly in the Asia-Pacific region, for patient access. |
| Strategic Partnership | Leverages specialized expertise in diagnostics and distribution, enhancing market reach. |
Research Approach
A spread of perspectives from gastroenterologists, regulatory affairs specialists, pharmaceutical R&D leads, and specialty clinic administrators converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and secondary validation from sources like FDA filings, EMA submissions, clinical trial registries, and pharmaceutical company annual reports. The approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
Demand-supply-balance modeling formed the core of the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, indication, end-user setting, delivery mode, and regional diagnostic prevalence. CAGRs were derived from historical growth trends and projected future demand drivers. Key forecast inputs incorporated chronic pancreatitis prevalence rates and orphan drug designation approvals.
Stress conditions across regulatory shifts and raw material availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding disease progression and treatment adoption, acknowledging unforeseen supply chain disruptions or changes in diagnostic protocols as potential risk factors. Cross-checking against WHO disease incidence statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Global Narcolepsy Drugs Market