
 Capecitabine Market | 2026-2036
Capecitabine Market Size, Share, and Industry Trends Forecast 2026-2036
Capecitabine Market Intelligence
A surge in generic drug manufacturing capacity in India is recalibrating the supply landscape for capecitabine active pharmaceutical ingredients (APIs). This shift benefits companies like Cipla Inc., which leverages its extensive production footprint to compete on cost. In contrast, F. Hoffmann-La Roche Ltd. sustains its position in the branded segment through long-standing clinical relationships. Teva Pharmaceutical Industries Ltd. navigates both branded and generic spaces with a diversified portfolio.
Capecitabine is an orally administered chemotherapeutic agent that acts as a prodrug of 5-fluorouracil (5-FU). It is designed for targeted activation within tumor cells, primarily for treating metastatic breast and colorectal cancers. Within therapy areas, colorectal cancer applications constitute a mature and high-volume segment. Generic tablets represent the dominant product type, primarily distributed through specialty hospitals and oncology clinics.
Market access for capecitabine is governed by stringent regulatory approvals from bodies such as the US FDA and the European Medicines Agency (EMA). These agencies enforce Good Manufacturing Practices (GMP) and define the clinical data required for both branded and generic drug applications. Navigating the landscape of patent cliffs and the subsequent influx of generic competitors remains a central strategic challenge for established pharmaceutical firms.
Market Dynamics
The influx of generic active pharmaceutical ingredients, particularly from manufacturing centers in India, is the central structural force defining the capecitabine market. This shift intensifies price competition and expands access, fundamentally altering the competitive landscape once dominated by originator brands.
Growth Catalysts
- Regulatory Pathways:Expedited approval mechanisms for generics, such as the Abbreviated New Drug Application (ANDA) process by the US FDA, lower barriers to entry and stimulate supply.
- Oncological Demand:The rising incidence of colorectal cancer in countries with advanced healthcare systems, including Japan and Germany, sustains a high-volume demand for established treatment protocols.
- API Synthesis Efficiency:Continuous improvements in chemical synthesis processes for capecitabine API in manufacturing hubs like India are reducing the cost of goods and enhancing affordability.
Market Restraints
- Adverse Effect Profile:The potential for significant side effects necessitates close patient monitoring, which increases the total cost of care and can limit adoption in healthcare systems with fewer resources.
- Therapeutic Substitution:The development and approval of novel immunotherapies and other targeted agents for metastatic cancers create a persistent threat of substitution for older chemotherapeutic agents.
- Reimbursement Complexity:Inconsistent and often restrictive reimbursement policies for oncology drugs across different national payers, particularly within the European Union, create significant market access friction.
Strategic Opportunities
- Geographic Expansion:Penetration into emerging markets, such as Brazil and Mexico, where government healthcare initiatives are improving cancer diagnosis rates and treatment infrastructure, offers new growth avenues.
- Combination Therapies:Clinical investigation into capecitabine's use as a component in combination regimens for other solid tumors, including pancreatic and gastric cancers, could expand its therapeutic utility.
- Digital Health Integration:The development of specialized digital pharmacy platforms for oral oncolytics can improve patient adherence and provide valuable real-world data on treatment outcomes.
Industry Challenges
- GMP Compliance:Maintaining consistent adherence to Good Manufacturing Practices (GMP) across a globally fragmented API supply chain presents a significant quality control and regulatory challenge for finished-dose manufacturers.
- Intellectual Property Disputes:Originator firms often employ complex legal strategies and secondary patenting to extend market exclusivity, creating prolonged uncertainty and litigation costs for generic competitors.
- Supply Chain Integrity:Ensuring the stability and quality of capecitabine tablets through complex, multi-stage global logistics networks requires robust cold chain and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capecitabine Market |
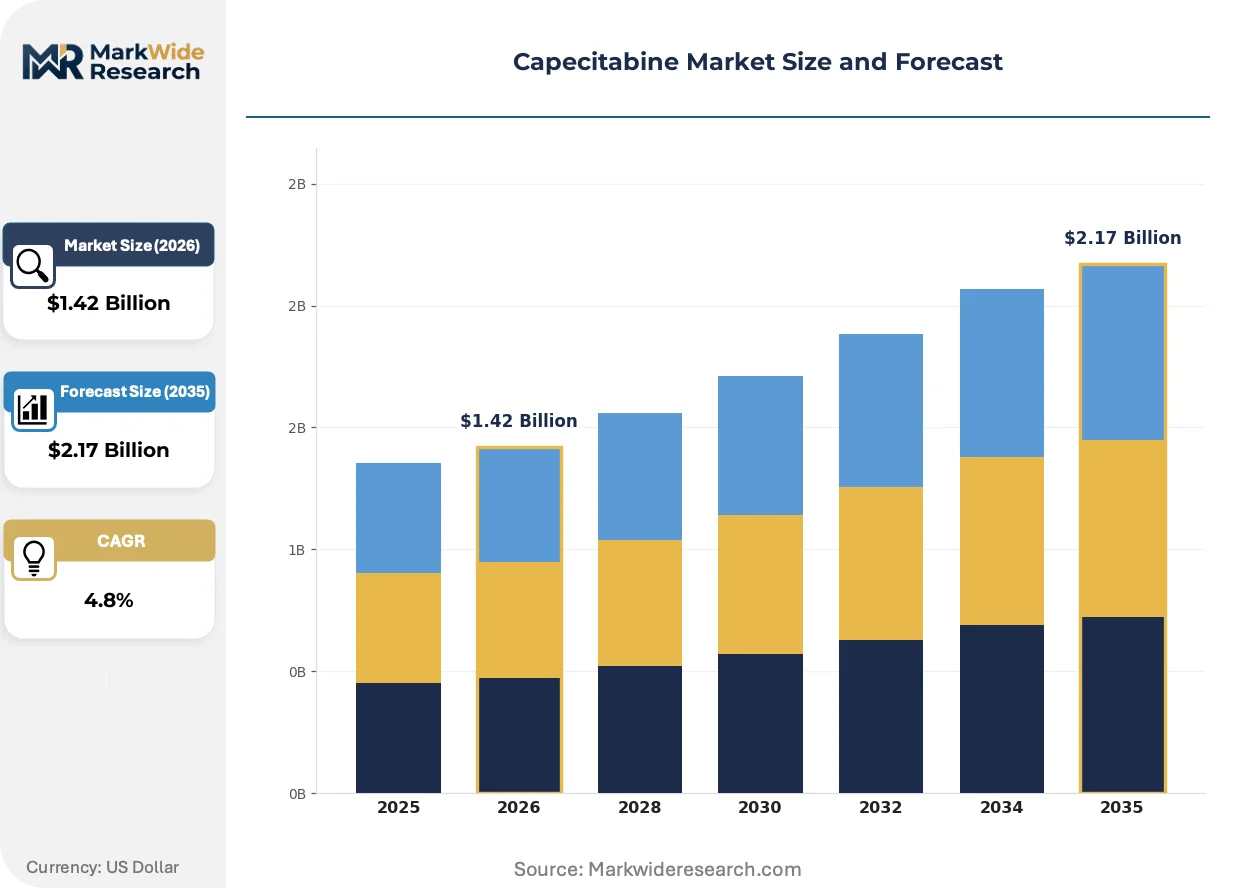
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Oral Suspension, Extended Release, Generic, Branded Therapy Area: Colorectal Cancer, Breast Cancer, Gastric Cancer, Pancreatic Neoplasm, Esophageal Cancer End User: Oncology Clinics, Cancer Research Institutes, Specialty Hospitals, Pharmaceutical Distributors Dosage Form: Film-Coated Tablet, Capsule, Powder for Suspension, Injectable |
| Companies Covered | Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Mylan N.V., Hikma Pharmaceuticals PLC, Cipla Inc., Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Fresenius Kabi AG, Aurobindo Pharma Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capecitabine Market Strategic Shifts & Innovations
Operational efficiencies and data-driven patient management are defining the next phase of the capecitabine market. The focus is shifting from originator-led discovery to optimizing the delivery and cost-effectiveness of this established therapy in a competitive generic environment.
Oral chemotherapy adherence platforms represent a key product evolution. These systems use smart packaging and mobile applications to help patients and clinicians track medication intake in real time. Oncology clinics and specialty pharmacies are adopting these tools to improve treatment efficacy. This technology is decentralizing patient management away from the clinic, enabling more effective remote monitoring and care coordination.
The European Medicines Agency's (EMA) harmonized process for granting marketing authorizations for generic medicines accelerates market access across the EU. This unified framework reduces redundant national reviews, allowing generic capecitabine manufacturers to reach multiple countries more quickly. The colorectal cancer segment in nations like France and Germany benefits most directly, as providers gain earlier access to more affordable therapeutic options.
Health systems are increasingly adopting value-based procurement models for oncology drugs, linking payment to demonstrated patient outcomes. This approach displaces traditional volume-based purchasing, compelling manufacturers to provide robust real-world evidence of their product's effectiveness and value. This trend is most visible in integrated national health systems, such as the UK's NHS, and among large Accountable Care Organizations in the United States.
Capecitabine Market Segmentation
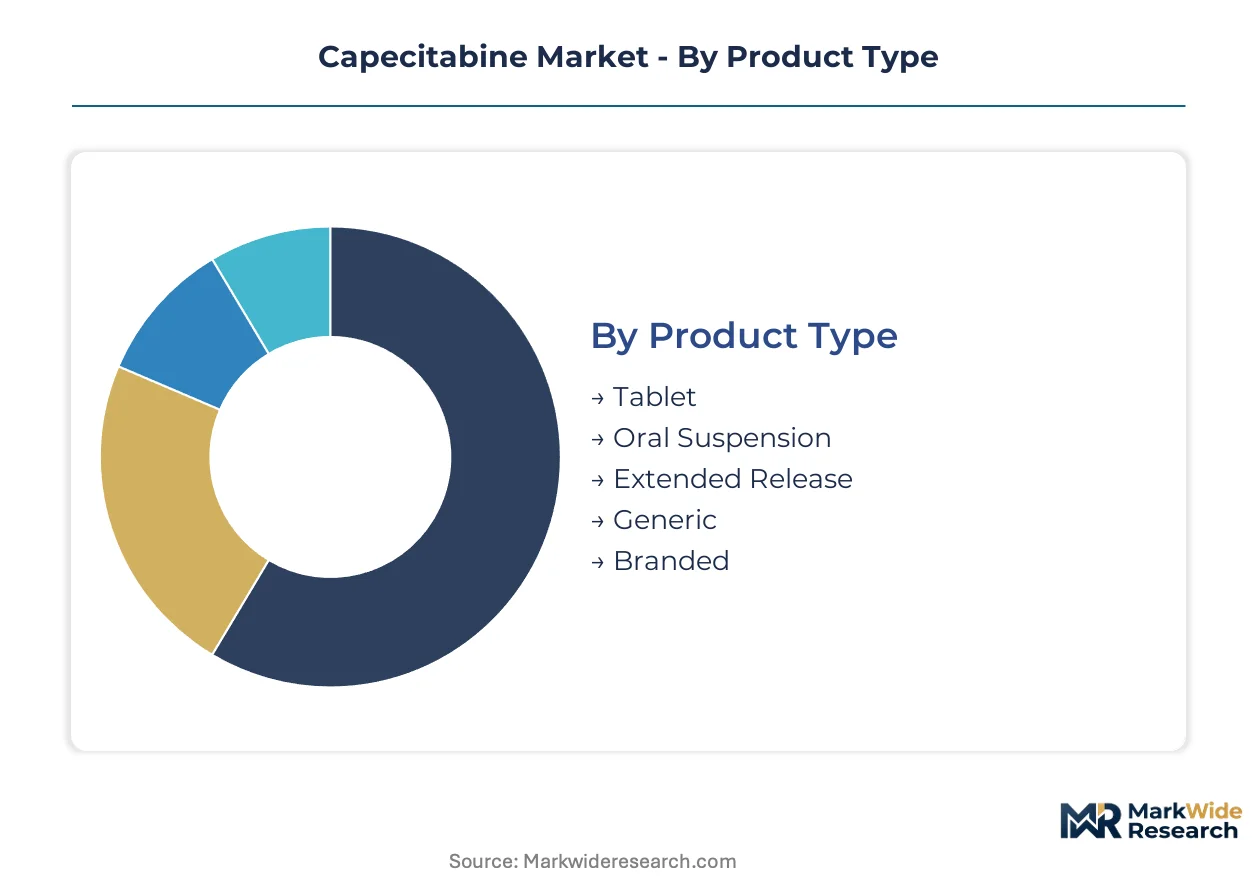
The segmentation analysis for the capecitabine market provides a granular view of product variations, therapeutic applications, and distribution channels. Understanding these distinct segments is essential for pharmaceutical manufacturers and healthcare providers to align their strategies with specific market demands and patient needs. Each category reveals unique dynamics influencing adoption rates and competitive positioning.
Product Type:
The capecitabine market's product type segmentation highlights the volume distribution between generic and branded formulations, alongside specialized delivery methods.
- Generic:This segment comprises bioequivalent versions of capecitabine, offering cost-effective treatment alternatives for patients. Demand concentrates in national healthcare systems, such as the UK's NHS and Germany's statutory health insurance, which prioritize cost containment and broad patient access.
- Branded:These are the original, innovator formulations of capecitabine, often supported by extensive clinical data and established physician relationships. Demand remains strong in markets like the United States, where brand loyalty and physician preference can still influence prescribing patterns despite generic availability.
- Tablet:The most common and widely used dosage form, offering convenience for oral administration in various cancer treatment protocols.
- Oral Suspension:This liquid formulation provides an alternative for patients who have difficulty swallowing solid tablets, improving adherence in specific patient populations.
- Extended Release:These formulations are designed to slowly release the active drug over an extended period, potentially reducing dosing frequency and improving patient compliance.
Today's leader: Generic. Tomorrow's challenger: Extended Release.
Therapy Area:
The market's therapy area segmentation reflects the primary oncological applications driving capecitabine consumption across different cancer types.
- Colorectal Cancer:This represents a mature and high-volume application for capecitabine, serving as a cornerstone in both adjuvant and metastatic treatment regimens. Demand is sustained by the rising incidence of colorectal cancer in developed economies such as Japan and France, where established treatment guidelines incorporate capecitabine.
- Breast Cancer:Capecitabine is a well-established treatment option for metastatic breast cancer, particularly in patients who have failed prior chemotherapy. Demand remains consistent in countries with comprehensive breast cancer screening programs and advanced oncology care, including the United States.
- Gastric Cancer:Capecitabine is frequently used in combination regimens for advanced gastric cancer, especially in Asian populations where the disease incidence is higher.
- Pancreatic Neoplasm:This segment involves the use of capecitabine, often in combination, for the treatment of advanced pancreatic cancer, a disease with significant unmet medical needs.
- Esophageal Cancer:Capecitabine plays a role in the multimodal treatment of esophageal cancer, particularly in locally advanced or metastatic settings.
The colorectal cancer segment commands the largest share, while therapies for pancreatic neoplasm exhibit a climbing share.
End User:
The end-user segmentation delineates the primary healthcare facilities and entities responsible for prescribing and distributing capecitabine to patients.
- Oncology Clinics:These specialized outpatient facilities focus exclusively on cancer diagnosis, treatment, and follow-up care, serving as a primary point of prescription and administration for oral oncolytics like capecitabine. Demand is concentrated in urban centers with robust healthcare infrastructure, such as those found in Germany.
- Specialty Hospitals:Hospitals with dedicated oncology departments or comprehensive cancer centers provide a full spectrum of care, including chemotherapy administration and patient management. These institutions manage a significant volume of capecitabine prescriptions, particularly in complex cases requiring inpatient care, prevalent in countries like Canada.
- Cancer Research Institutes:These institutions primarily focus on clinical trials and drug development, utilizing capecitabine in research protocols and advanced treatment studies.
- Pharmaceutical Distributors:These entities manage the supply chain logistics, ensuring capecitabine reaches pharmacies, hospitals, and clinics efficiently.
Oncology clinics are the dominant end-user category, with specialty hospitals representing a significant and consistent demand channel.
Dosage Form:
The dosage form segmentation highlights the different physical presentations of capecitabine available for patient administration.
- Film-Coated Tablet:This oral dosage form is the most prevalent, featuring a thin polymer coating that aids in swallowing and masks taste, making it highly acceptable for patients. Demand is concentrated globally due to its ease of administration and widespread availability, particularly in generic forms.
- Powder for Suspension:This form allows for reconstitution into a liquid, providing a flexible dosing option for patients who cannot swallow tablets or require precise dose adjustments. This is often preferred in pediatric oncology or for patients with dysphagia, common in long-term care settings.
- Capsule:Capsules offer another oral administration route, typically containing the active ingredient within a soluble shell for easy ingestion.
- Injectable:While capecitabine is primarily an oral agent, certain analogues or combination therapies might involve injectable components for specific clinical scenarios.
Film-coated tablets hold the largest segment share due to patient convenience, while powder for suspension is gaining share for its adaptability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks and manufacturing cost structures significantly influence the global capecitabine supply chain. Production often migrates to regions offering a cost-of-compliance advantage, while advanced healthcare systems drive demand in developed economies. This dynamic creates distinct regional market characteristics for the drug.
India
Capecitabine API synthesis efficiency drives significant manufacturing activity in India. The government's Production-Linked Incentive (PLI) scheme supports domestic pharmaceutical production. Gujarat and Telangana host major pharmaceutical manufacturing clusters, contributing to global generic supply. The Central Drugs Standard Control Organization (CDSCO) oversees drug quality.
United States
The United States sustains a strong demand for both branded and generic capecitabine formulations. The US FDA's Abbreviated New Drug Application (ANDA) process facilitates generic market entry. Major biopharmaceutical hubs in Massachusetts and California concentrate advanced oncology clinics. Physician preference often influences prescribing patterns despite generic availability.
Germany
Germany exhibits high demand for capecitabine due to a rising incidence of colorectal cancer and a comprehensive healthcare system. The European Medicines Agency (EMA) harmonizes drug approvals across the EU. Urban centers like Munich and Berlin feature advanced oncology clinics. Statutory health insurance prioritizes cost-effective treatment protocols.
Japan
Rising colorectal cancer incidence sustains high-volume demand for capecitabine in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug approvals and market access. The Tokyo and Osaka regions are centers for advanced medical research and treatment. Established treatment guidelines incorporate capecitabine as a standard therapy.
Brazil
Brazil represents an emerging market for capecitabine, driven by improving cancer diagnosis rates and government healthcare initiatives. ANVISA, the national health surveillance agency, manages drug registration and oversight. São Paulo and Rio de Janeiro possess developed pharmaceutical distribution networks. Public health programs expand access to essential cancer treatments.
Capecitabine Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cost leadership in generic formulations. The market structure reflects a tiered landscape with distinct competitive dynamics. Originator brands focus on sustained clinical relationships, while generic manufacturers compete on price and supply chain efficiency. Diversified pharmaceutical firms navigate both segments. Strategic partnerships for market access and continuous improvements in API synthesis define competitive moves.
Within this dynamic environment, F. Hoffmann-La Roche Ltd. exemplifies the originator brand archetype, sustaining its position through long-standing clinical relationships. Cipla Inc. represents a large-scale generic manufacturer, leveraging its extensive production footprint to compete on cost. Teva Pharmaceutical Industries Ltd. occupies a position as a diversified pharmaceutical firm, navigating both branded and generic spaces with a broad portfolio.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Mylan N.V. |
| Hikma Pharmaceuticals PLC |
| Cipla Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Aurobindo Pharma Ltd. |
| Others |
Cost & Logistics Intelligence
Good Manufacturing Practices (GMP) adherence, alongside stringent regulatory approvals, gates qualified supply and influences premium-tier pricing for compliant capecitabine formulations. This dynamic shapes market access and cost structures across different product segments.
Pricing Analysis
Specialty pharmacy markups and distributor margins significantly impact the final cost of capecitabine. The dominant pricing structure is tiered, separating branded innovator products from cost-effective generic alternatives. Price differentiation stems from brand premium and regulatory compliance, particularly for originator firms. Pricing softness reflects the influx of generic formulations, intensifying competition. National healthcare systems, such as the UK's NHS, represent the most price-sensitive buyers, prioritizing affordability and broad patient access.
Supply Chain Analysis
Regional pharmaceutical distribution centers facilitate the movement of capecitabine from manufacturing hubs to end-users. Geographic supply concentrates heavily in India for active pharmaceutical ingredients (APIs), while finished dosage forms are often produced closer to major consumption markets like the United States and Europe. The supply chain sources from key raw materials such as 5-fluorouracil precursors. Single-source vulnerability for specific APIs presents a structural risk. Distribution runs through specialized pharmaceutical distributors and direct channels to hospitals and oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capecitabine market offers margin expansion opportunities, driven by continuous improvements in API synthesis efficiency, particularly from manufacturing hubs in India.
For Market Incumbents: Acquire specialized digital health platforms to enhance patient adherence and real-world data collection. Invest in clinical trials for capecitabine in novel combination regimens to counter the threat of therapeutic substitution from immunotherapies. Strengthen regulatory expertise to navigate complex approval pathways for lifecycle management strategies.
For New Entrants and Emerging Players: Specialty pharmaceutical distributors offer a critical channel for market penetration. Target underpenetrated emerging markets, such as Brazil, with cost-competitive generic formulations. Focus on expedited regulatory pathways, like the US FDA's ANDA process, to achieve rapid market entry and capture market share in high-volume segments like film-coated tablets.
For Investors and Strategic Acquirers: Roll-up economics work for integrated generic manufacturers because supply chain efficiencies drive margin leverage. Long-term viability rests on the sustained demand for established oncology treatments and expanding generic access. Acquisition targets should include API manufacturers with robust GMP compliance and finished-dose producers with strong distribution networks. Watch for regulatory changes that accelerate generic approvals as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands capecitabine's therapeutic utility into new cancer types and combination regimens. |
| Regulatory Approval Pathway | Accelerates generic market entry in key geographies like the European Union and emerging markets. |
| Manufacturing Scale-Up | Reduces cost of goods for generic capecitabine, enhancing affordability and market reach. |
| Licensing Agreement | Secures access to novel drug delivery systems or specialized formulations for improved patient care. |
| Digital Health Integration | Improves patient adherence to oral oncolytics, providing valuable real-world treatment outcome data. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive view of the capecitabine market. The analysis combined primary insights from oncology specialists, pharmaceutical procurement managers, regulatory affairs experts, and API manufacturers with secondary validation. Secondary data sources included US FDA filings, EMA submissions, clinical trial registries, and company annual reports, triangulated through both bottom-up and top-down approaches.
The forecast framework anchored the projection horizon to comparable historical periods, establishing a robust baseline for future estimates. Segmentation dimensions modeled included product type, therapy area, end user, dosage form, and regional regulatory clusters. Compound annual growth rates were derived through a proprietary analytical model. Key industry-specific forecast inputs included cancer incidence rates and generic approval timelines across major markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to novel therapeutic substitutions, changes in reimbursement policies, and geopolitical supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Bone Degeneration Therapeutics Market