
 Europe Electric Vehicle Sensor Market | 2026-2036
Europe Electric Vehicle Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Sensor Market Analytics
Fleet operators and premium OEMs is rotating toward predictive battery health monitoring as the dominant buyer archetype in Europe. Robert Bosch GmbH leverages its Stuttgart R&D campus to sustain development of solid-state MEMS pressure sensors for thermal propagation detection. Continental AG anchors production of wheel-speed and current sensors at its Hanover complex, while Infineon Technologies AG dominates silicon carbide-based current sensing for 800-volt architectures in Villach.
Europe electric vehicle sensors are electromechanical transducers converting physical parameters—temperature, current, pressure, proximity—into digital signals with automotive-grade accuracy typically within ±0.5% full-scale error, purpose-built to protect battery packs and enable automated driving functions. Camera and radar sensor types lead unit shipments across autonomous driving and collision avoidance applications, though LiDAR captures disproportionate margin pools as German OEMs certify Level 3 highway systems. Short-range ultrasonic and proximity technologies remain mature segments with stable pricing, while 3D imaging arrays represent the fastest-growing technology tier as parking and low-speed maneuver automation spreads through the A-segment and compact SUV classes.
The EU Green Deal's 2035 internal combustion engine prohibition, enforced through national type-approval authorities aligned with ECE R100 battery safety standards, mandates cell-level temperature and voltage telemetry that expands sensor counts per vehicle by factors of three to five over conventional architectures. REACH and RoHS compliance from ECHA further constrains material choices for sensor housings and conductive traces, favoring European suppliers with established substance-tracking systems. Stakeholders must monitor how CSRD disclosure requirements reshape Tier 2 sourcing decisions and whether the EU AI Act's risk classifications delay deployment of camera-based driver monitoring systems already specified for 2027 model-year platforms.
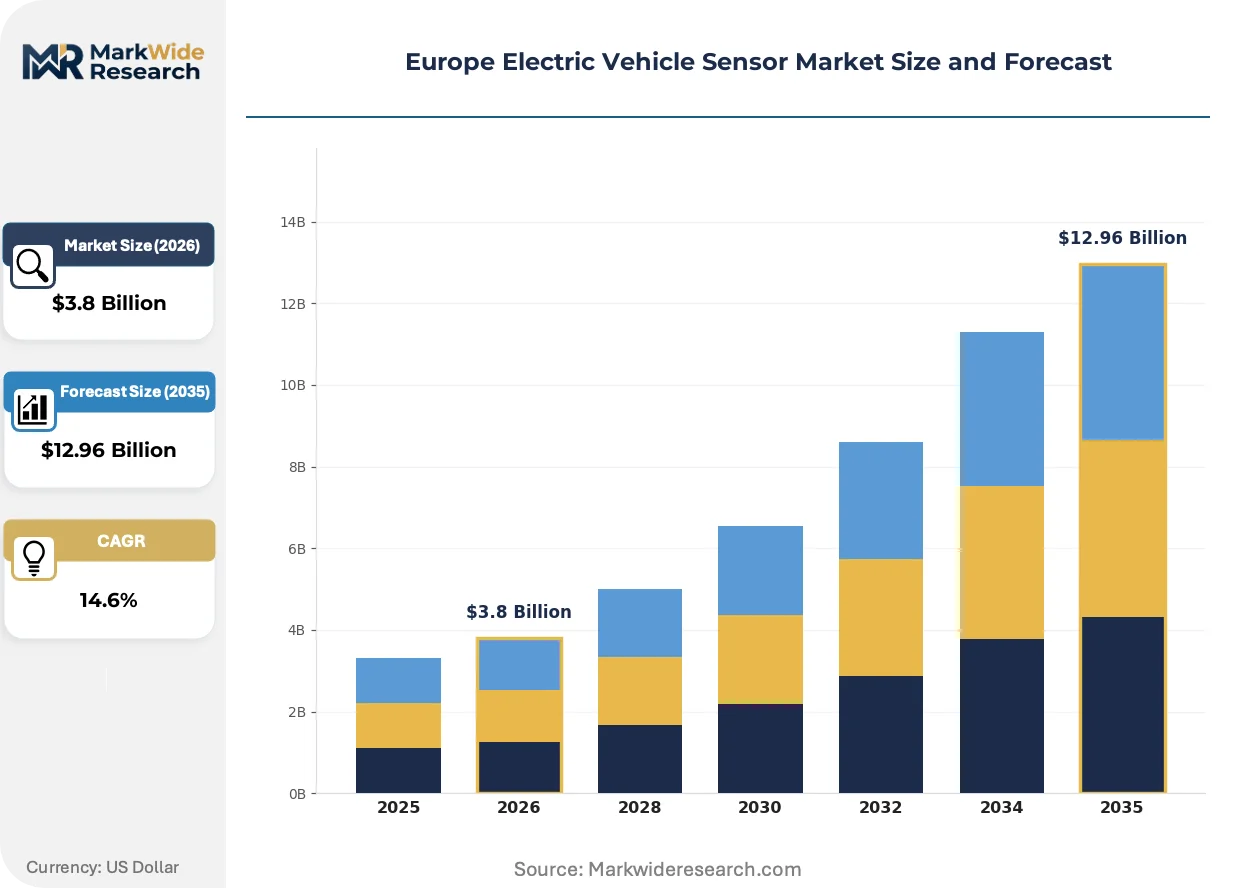
Market Dynamics
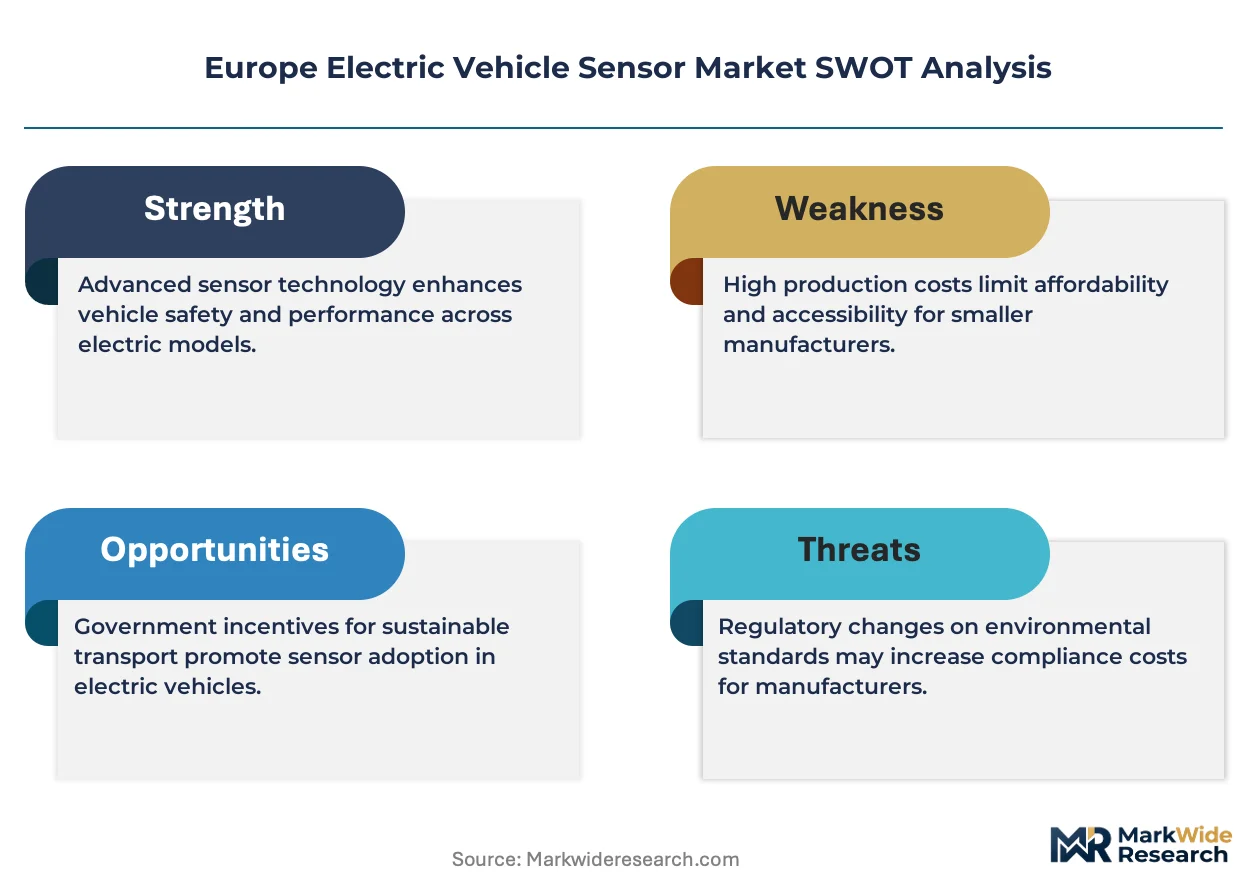
The EU Green Deal's 2035 ICE phase-out mandate is forcing OEMs to redesign vehicle architectures around native electric platforms, triggering a wholesale reconfiguration of sensor procurement specifications across European manufacturing corridors.
Growth Catalysts
- Cell-level voltage telemetry:ECE R100 battery safety standards mandate granular monitoring that multiplies sensor counts per vehicle threefold to fivefold over conventional architectures.
- 800-volt platform migration:German premium OEMs are accelerating silicon carbide-based current sensing adoption for faster charging and improved thermal efficiency.
- Baden-Württemberg manufacturing concentration:Stuttgart's tier-one supplier cluster provides integrated R&D-to-production pipelines that compress development cycles for thermal runaway detection systems.
Market Restraints
- Silicon carbide substrate costs:Wafer pricing volatility constrains margin expansion for high-voltage current sensors deployed in 800-volt battery packs.
- Hanover production concentration:Continental AG's wheel-speed sensor dominance creates single-source vulnerability for European OEMs seeking supply redundancy.
- REACH substance restrictions:ECHA compliance requirements limit conductive trace materials and sensor housing alloys, forcing reformulation of established product lines.
Strategic Opportunities
- Netherlands fleet electrification:Amsterdam's commercial vehicle mandates create concentrated demand for predictive battery health monitoring in logistics applications.
- CSRD disclosure requirements:Corporate sustainability reporting obligations are reshaping Tier 2 sourcing decisions toward European suppliers with established substance-tracking systems.
- LiDAR-camera fusion:German OEM certification of Level 3 highway automation is opening specification windows for integrated 3D imaging arrays in mid-segment SUVs.
Industry Challenges
- MEMS fabrication talent scarcity:Solid-state pressure sensor development requires specialized cleanroom expertise concentrated in Villach and Stuttgart corridors.
- EU AI Act risk classification:Camera-based driver monitoring systems face potential deployment delays for 2027 model-year platforms pending regulatory clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Sensor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: LiDAR, Radar, Ultrasonic, Camera Application: Autonomous Driving, Traffic Monitoring, Collision Avoidance, Battery Management Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses Technology: Short-Range, Long-Range, 3D Imaging, Proximity Sensors |
| Companies Covered | Robert Bosch GmbH, Continental AG, Infineon Technologies AG, STMicroelectronics NV, NXP Semiconductors NV, Valeo SA, ZF Friedrichshafen AG, TE Connectivity Ltd., Melexis NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Sensor Market Evolving Landscape
Solid-state sensing architectures are compressing form factors while expanding measurement precision, reshaping how European OEMs specify thermal and electrical monitoring systems for next-generation battery packs.
Solid-state MEMS pressure sensors for thermal propagation detection are supplanting conventional electromechanical transducers in premium battery pack designs. Robert Bosch GmbH's Stuttgart R&D campus is driving this transition through integrated fabrication processes that merge sensing elements with ASIC conditioning circuits. The technology is supplanting legacy ceramic-based alternatives by enabling sub-millisecond response times critical for runaway containment.
REACH and RoHS compliance frameworks from ECHA are constraining material choices for sensor housings and conductive traces across European supply chains. Manufacturers must reformulate established product lines using alternative alloys and polymer substrates that maintain automotive-grade accuracy within ±0.5% full-scale error. German and French tier-one suppliers are responding fastest, leveraging pre-existing substance-tracking databases to accelerate certification timelines.
Fleet operators are consolidating procurement authority around predictive battery health monitoring specifications rather than discrete component purchasing. This concentration is compressing supplier negotiation cycles and favoring integrated system providers capable of delivering cell-level voltage, temperature, and pressure telemetry through unified platforms. The Netherlands and Germany show the most pronounced buyer consolidation, with logistics operators specifying multi-year service agreements tied to uptime guarantees.
Europe Electric Vehicle Sensor Market Segmentation
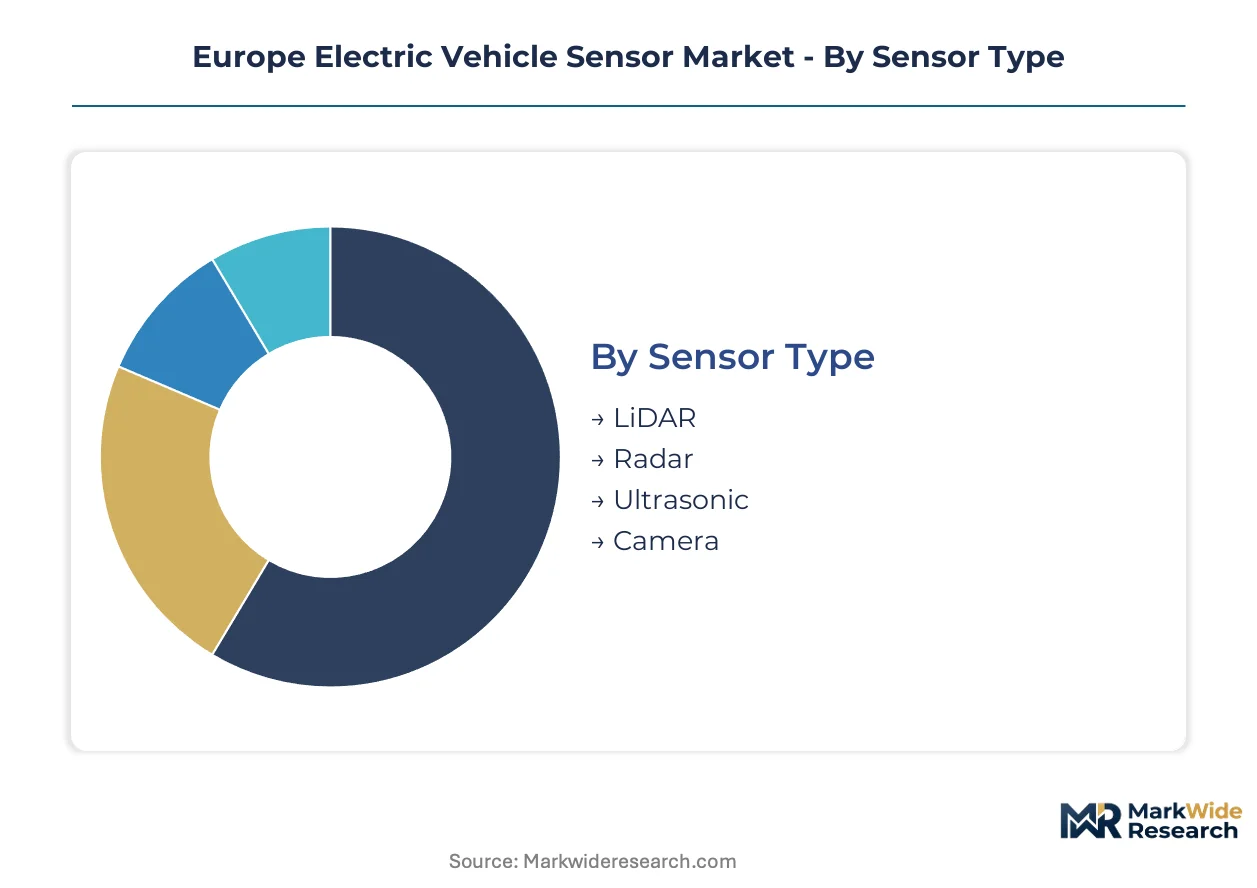
Europe Electric Vehicle Sensor procurement flows through distinct channel configurations depending on sensor complexity and integration depth. Tier-one suppliers dominate high-value LiDAR and radar contracts, while aftermarket distributors handle replacement ultrasonic and proximity modules.
Sensor Type:
Camera and radar sensors move through integrated tier-one supply chains anchored in Stuttgart and Hanover, while LiDAR and ultrasonic modules split between direct OEM contracts and specialized subsystem integrators.
- LiDAR:Solid-state architectures with MEMS beam-steering arrays deliver 300-meter range detection for highway automation. German premium OEMs in Bavaria are certifying these units for Level 3 systems, though unit costs constrain penetration below the mid-luxury segment threshold.
- Radar:77 GHz and 79 GHz frequency-modulated continuous wave designs enable adaptive cruise and blind-spot monitoring. Continental AG's Hanover production complex supplies European OEMs with integrated radar-camera fusion modules, consolidating procurement for next-generation platforms.
- Ultrasonic:Parking assistance and low-speed maneuver detection rely on mature piezoelectric transducer technology with stable unit economics.
- Camera:CMOS image sensors with HDR processing support traffic sign recognition and lane-keeping functions across A-segment through luxury vehicle classes.
By volume, camera sensors lead European EV installations. By growth pace, LiDAR is climbing the fastest as Level 3 highway systems gain regulatory clearance.
Application:
Cost tier stratification separates safety-critical autonomous functions from commodity battery monitoring, with collision avoidance commanding premium pricing and traffic monitoring settling into standard equipment tiers.
- Autonomous Driving:Multi-sensor fusion architectures combining LiDAR, radar, and camera inputs require ASIL-D functional safety certification. Stuttgart-based engineering centers coordinate specification development for German OEMs deploying highway pilot systems.
- Battery Management:Cell-level voltage and temperature telemetry under ECE R100 mandates drives sensor proliferation factors of three to five over conventional architectures. Netherlands fleet operators are consolidating procurement around predictive health monitoring platforms with uptime guarantees.
- Collision Avoidance:Forward-facing radar and camera combinations for automatic emergency braking have achieved regulatory mandate status across EU type-approval frameworks.
- Traffic Monitoring:V2X communication modules and environmental sensing for congestion management represent emerging specification territory with unsettled standardization.
By volume, battery management sensors dominate unit counts per vehicle. By margin capture, autonomous driving applications are expanding most quickly.
Vehicle Type:
Customer type concentration varies sharply, with commercial vehicle fleets demanding integrated service contracts while passenger car procurement fragments across multiple OEM platform teams.
- Passenger Cars:Premium German OEMs specify the most sensor-dense configurations, with battery electric platforms integrating 80-120 discrete sensing elements for thermal, electrical, and environmental monitoring. Baden-Württemberg manufacturing corridors concentrate development activity.
- Commercial Vehicles:Amsterdam's municipal mandates for zero-emission logistics are accelerating sensor procurement for heavy-duty battery packs with predictive maintenance requirements. Fleet operators specify multi-year service agreements tied to vehicle availability metrics.
- Buses:Urban transit electrification programs in France and the Netherlands drive demand for high-voltage isolation monitoring and thermal runaway detection in double-decker and articulated configurations.
- Two-Wheelers:Compact form factors constrain sensor counts, though EU type-approval extensions for electric motorcycles are expanding basic battery monitoring requirements.
By volume, passenger cars anchor European EV sensor demand. By specification intensity, commercial vehicles are gaining share fastest as fleet electrification accelerates.
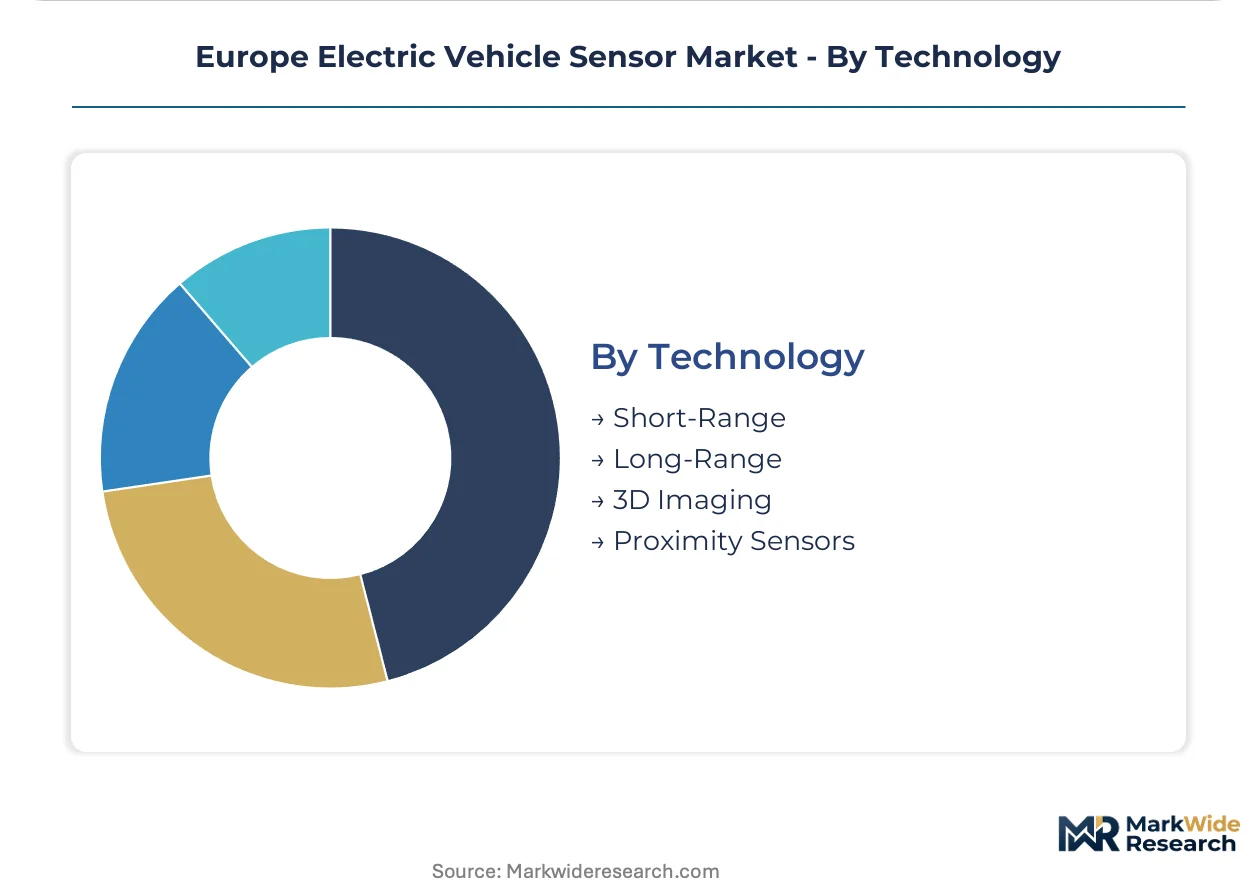
Technology:
Supply concentration for advanced 3D imaging and long-range sensing clusters in Villach and Stuttgart corridors, while short-range and proximity technologies distribute across broader European supplier bases.
- 3D Imaging:Solid-state LiDAR and time-of-flight camera arrays enable high-resolution environmental mapping for automated parking and urban navigation. Infineon Technologies AG's Villach fab anchors silicon photonics development for automotive-grade 3D sensors.
- Long-Range:77 GHz radar and 1550 nm LiDAR configurations extend detection horizons for highway automation. German OEM certification programs are validating these technologies for 130 km/h autonomous operation under EU vehicle regulation frameworks.
- Short-Range:Ultrasonic and 24 GHz radar modules for parking assistance represent mature technology tiers with compressed margins and established supplier relationships.
- Proximity Sensors:Inductive and capacitive designs for charge port detection and pedestrian warning systems occupy specification niches with limited growth trajectory.
By volume, short-range sensors lead current European EV installations. By technology transition velocity, 3D imaging arrays are expanding most quickly as parking automation penetrates compact SUV segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail electrification and Rotterdam's deep-water port infrastructure position the Netherlands as Europe's primary logistics electrification testbed. Germany's autobahn network and high-voltage grid interconnects anchor sensor-intensive premium vehicle production. France's nuclear-powered grid stability enables consistent charging infrastructure deployment.
Germany
Battery electric passenger car fleets across Baden-Württemberg and Bavaria are accelerating procurement for thermal runaway detection systems. The EU Green Deal's 2035 ICE phase-out mandate forces OEMs to redesign vehicle architectures around native electric platforms. Stuttgart's tier-one supplier cluster provides integrated R&D-to-production pipelines that compress development cycles for next-generation sensing systems.
Netherlands
Amsterdam's municipal mandates for zero-emission commercial vehicles create concentrated demand for predictive battery health monitoring in logistics applications. REACH compliance from ECHA constrains material choices for sensor housings and conductive traces. The Eindhoven Region's semiconductor fabrication base anchors silicon carbide-based current sensing development for 800-volt architectures.
France
Urban transit electrification programs in Paris and Lyon drive specification intensity for high-voltage isolation monitoring in double-decker and articulated bus configurations. RoHS directives limit conductive trace materials, forcing reformulation of established product lines. Île-de-France manufacturing corridors concentrate engineering talent for autonomous driving sensor fusion development.
Italy
Premium OEM supply relationships in Lombardy and Piedmont sustain demand for LiDAR-camera fusion modules in mid-luxury SUV segments. CE marking requirements for automotive-grade components create certification bottlenecks for non-European suppliers. Turin's engineering ecosystem specializes in radar signal processing for adaptive cruise control systems.
United Kingdom
Fleet operator consolidation around multi-year service agreements in London and the Southeast reshapes procurement toward integrated telemetry platforms. CSRD disclosure obligations are reshaping Tier 2 sourcing decisions toward suppliers with established substance-tracking systems. The Midlands automotive corridor maintains development activity for camera-based driver monitoring systems pending EU AI Act clarity.
Europe Electric Vehicle Sensor Market Competitive Landscape
Concentration sits with diversified automotive electronics conglomerates that span MEMS fabrication, ASIC design, and systems integration. The vendor base clusters around Stuttgart, Hanover, and Villach industrial corridors where cleanroom infrastructure and tier-one proximity create defensive moats. Three archetypes dominate: integrated platform providers delivering unified battery telemetry, specialized MEMS fabricators supplying solid-state pressure elements, and subsystem integrators fusing multi-sensor inputs for autonomous functions. Competitive moves center on backward integration into silicon carbide substrate supply and geographic expansion through engineering service partnerships in Eastern European manufacturing zones.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated platform archetype, anchoring procurement relationships through co-located R&D and production. Infineon Technologies AG occupies a position representing the specialized semiconductor fabricator tier, with Villach-based cleanroom operations serving as a regional capability anchor. These three entities sit within a competitive structure where proximity to Baden-Württemberg and Bavaria OEM engineering centers determines specification access.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Infineon Technologies AG |
| STMicroelectronics NV |
| NXP Semiconductors NV |
| Valeo SA |
| ZF Friedrichshafen AG |
| TE Connectivity Ltd. |
| Melexis NV |
| Others |
Value Network & Pricing Analysis
EU Green Deal certification tiers gate both supplier qualification and price differentiation simultaneously, with ECE R100 battery safety compliance separating premium thermal runaway detection systems from commodity voltage monitoring modules. REACH substance restrictions from ECHA further stratify pricing by forcing reformulation costs onto non-compliant suppliers while rewarding established European players with pre-certified material databases.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with fleet operators commanding steeper rebates than fragmented passenger car OEMs. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D functional safety certification and silicon carbide substrate grade. Cost compression in ultrasonic and proximity segments is intensifying because mature piezoelectric transducer technology faces oversupply from Asian manufacturers. Commercial vehicle fleets exhibit lowest price sensitivity due to uptime guarantee requirements, while A-segment passenger car OEMs prioritize unit cost minimization.
Supply Chain Analysis
Germany and Austria anchor MEMS fabrication and ASIC design for solid-state pressure sensors, while Taiwan and South Korea feed wafer supply for silicon carbide substrates. European sensor production draws from specialized cleanroom infrastructure concentrated in Stuttgart, Hanover, and Villach corridors. Single-source vulnerability around Continental AG's Hanover wheel-speed sensor dominance creates structural risk for OEMs seeking supply redundancy. Distribution runs through integrated tier-one supply chains for high-value LiDAR and radar, with aftermarket distributors handling replacement ultrasonic modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Vehicle Sensor Market sits in early-cycle expansion, with the 2035 ICE phase-out mandate accelerating native platform redesigns that multiply sensor counts per vehicle threefold to fivefold.
For Market Incumbents: Compound R&D-to-production integration at Stuttgart and Villach campuses to compress development cycles for thermal runaway detection systems. Threats from silicon carbide substrate cost volatility demand backward integration into wafer supply or long-term offtake agreements with Taiwanese and South Korean suppliers. Priority lever centers on ASIC-sensor fusion capabilities that lock in specification access with Bavarian premium OEMs.
For New Entrants and Emerging Players: Predictive battery health monitoring platforms represent the service-layer gap where incumbents under-serve Netherlands logistics operators seeking uptime guarantees. White-space targets cluster around commercial vehicle fleet electrification in Amsterdam and Rotterdam corridors, plus aftermarket retrofit solutions for legacy battery packs. Go-to-market angle emphasizes multi-year service contracts with availability metrics rather than discrete component sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed MEMS fabricators possessing Villach or Stuttgart cleanroom capacity but lacking OEM specification relationships. Long-term viability frames around five-to-ten year windows as 800-volt platform migration and Level 3 automation certification reshape content-per-vehicle trajectories. Signal to watch: German OEM engineering center staffing levels for thermal propagation detection and LiDAR-camera fusion programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | Captive wafer supply from Taiwan and South Korea insulates margins against pricing volatility in 800-volt architectures. |
| ASIC-Sensor Fusion Development | Integrated signal conditioning circuits at Stuttgart R&D campuses compress response times for thermal runaway detection. |
| Fleet Service Contract Expansion | Multi-year uptime agreements with Netherlands logistics operators lock in recurring revenue streams beyond component sales. |
| REACH Compliance Database Investment | Pre-existing substance-tracking systems accelerate certification timelines against ECHA restrictions on sensor housing alloys. |
| LiDAR-Camera Fusion Certification | Level 3 highway automation validation with German premium OEMs opens specification windows in mid-luxury SUV segments. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, semiconductor fabrication specialists, and fleet operator technical directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ECHA regulatory filings, EU type-approval databases, and automotive production records from Germany, France, and the Netherlands. Bottom-up sensor content-per-vehicle estimates triangulated against top-down market value projections derived from tier-one supplier revenue disclosures.
Segmentation dimensions modeled span sensor type, application, vehicle class, and technology tier across the projection horizon. The analytical framework disaggregated passenger car, commercial vehicle, bus, and two-wheeler propulsion architectures to capture specification intensity variations. CAGRs were derived from penetration curves for 800-volt platforms and Level 3 automation systems, cross-referenced with ECE R100 battery safety mandate implementation timelines. Forecast inputs incorporated silicon carbide substrate supply constraints and MEMS fabrication capacity utilization at Villach and Stuttgart corridors.
Underlying assumptions cover EU Green Deal enforcement continuity, ECHA REACH compliance stability, and OEM platform electrification commitments, with deviation risk concentrated in EU AI Act risk classification delays for camera-based driver monitoring systems. Recalibration cycles align with material shifts in battery safety regulation enforcement and 800-volt platform adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Timing Device Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market