
 Reservoir Monitoring System Market | 2026-2036
Reservoir Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Reservoir Monitoring System Market Intelligence
The divergence between premium fiber-optic distributed sensing and commodity pressure gauge tiers is realigning procurement patterns across offshore contracts. Schlumberger leverages its integrated subsurface platform to anchor premium bundled offerings, while Halliburton competes through specialized well integrity monitoring packages. Baker Hughes differentiates by dominating the permanent downhole gauge segment with manufacturing scale that sustains cost advantages.
A reservoir monitoring system comprises downhole and surface instrumentation that measures pressure, temperature, seismic activity, and acoustic signals to track fluid movement and formation behavior across producing intervals. Fiber optic sensors enable distributed temperature and strain profiling along the entire wellbore with spatial resolution down to one meter, supporting enhanced oil recovery optimization and early gas breakthrough detection. Wireless technology leads installation growth in brownfield retrofits where wellbore re-entry costs prohibit cable deployment, while seismic sensors command the highest capital allocation per well due to their role in time-lapse reservoir characterization. Oilfield operators represent the most concentrated end-user margin pool, though service providers are capturing recurring revenue through managed monitoring contracts.
The US Bureau of Safety and Environmental Enforcement mandates real-time well control monitoring for high-pressure high-temperature wells, while Norway's Petroleum Safety Authority requires continuous barrier verification that drives permanent gauge adoption. Brazil's national petroleum regulator enforces presalt field monitoring standards that shape sensor specification and certification requirements. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting wired versus wireless architectures for new developments.
Market Dynamics
Permanent downhole monitoring architectures are displacing intermittent well testing across deepwater developments, driven by subsea tieback economics and real-time barrier verification mandates from multiple national regulators.
Growth Catalysts
- Brazil's presalt monitoring standards:The national petroleum regulator mandates continuous reservoir surveillance for carbonate reservoirs, forcing permanent gauge deployment across Santos Basin developments.
- HPHT well control mandates:The US Bureau of Safety and Environmental Enforcement requires real-time pressure monitoring for high-pressure high-temperature classifications, accelerating sensor replacement cycles in the Gulf of Mexico.
- Subsea tieback proliferation:West African deepwater fields offshore Angola and Nigeria deploy distributed fiber-optic systems to eliminate surface platform requirements and reduce development capex.
Market Restraints
- Specialized electronics supply concentration:High-temperature pressure transducer manufacturing concentrates among a limited supplier base in Japan and Germany, creating procurement bottlenecks for HPHT-rated gauges.
- Downhole cable reliability limitations:Electrical conductor degradation in corrosive formation fluids limits gauge operational life to 5-7 years in sour gas environments, forcing premature workover expenditures.
- Wireless telemetry bandwidth constraints:Electromagnetic and acoustic transmission methods face signal attenuation in high-salinity brines, restricting data throughput for multizone monitoring applications.
Strategic Opportunities
- Retrofit wireless installations:Brownfield assets in the North Sea present untapped demand for cable-free pressure monitoring where wellbore re-entry costs prohibit conventional deployments.
- Carbon capture and storage surveillance:CO2 injection plume monitoring requires distributed acoustic and temperature sensing, opening adjacent demand from CCS project developers.
- Managed monitoring contracts:Service providers can capture recurring revenue streams by assuming sensor maintenance, data interpretation, and regulatory reporting obligations from capital-constrained operators.
Industry Challenges
- Downhole electronics engineering talent scarcity:The intersection of high-temperature semiconductor design and oilfield reliability engineering commands premium compensation, constraining workforce expansion for gauge manufacturers.
- Multivendor system integration complexity:Fiber-optic distributed sensing platforms from specialized vendors must interface with legacy SCADA architectures, requiring custom protocol development and extended commissioning timelines.
- Equipment qualification certification delays:API 19G and ISO 17025 validation for new gauge designs extends 18-24 months, compressing product launch windows against evolving operator specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reservoir Monitoring System Market |
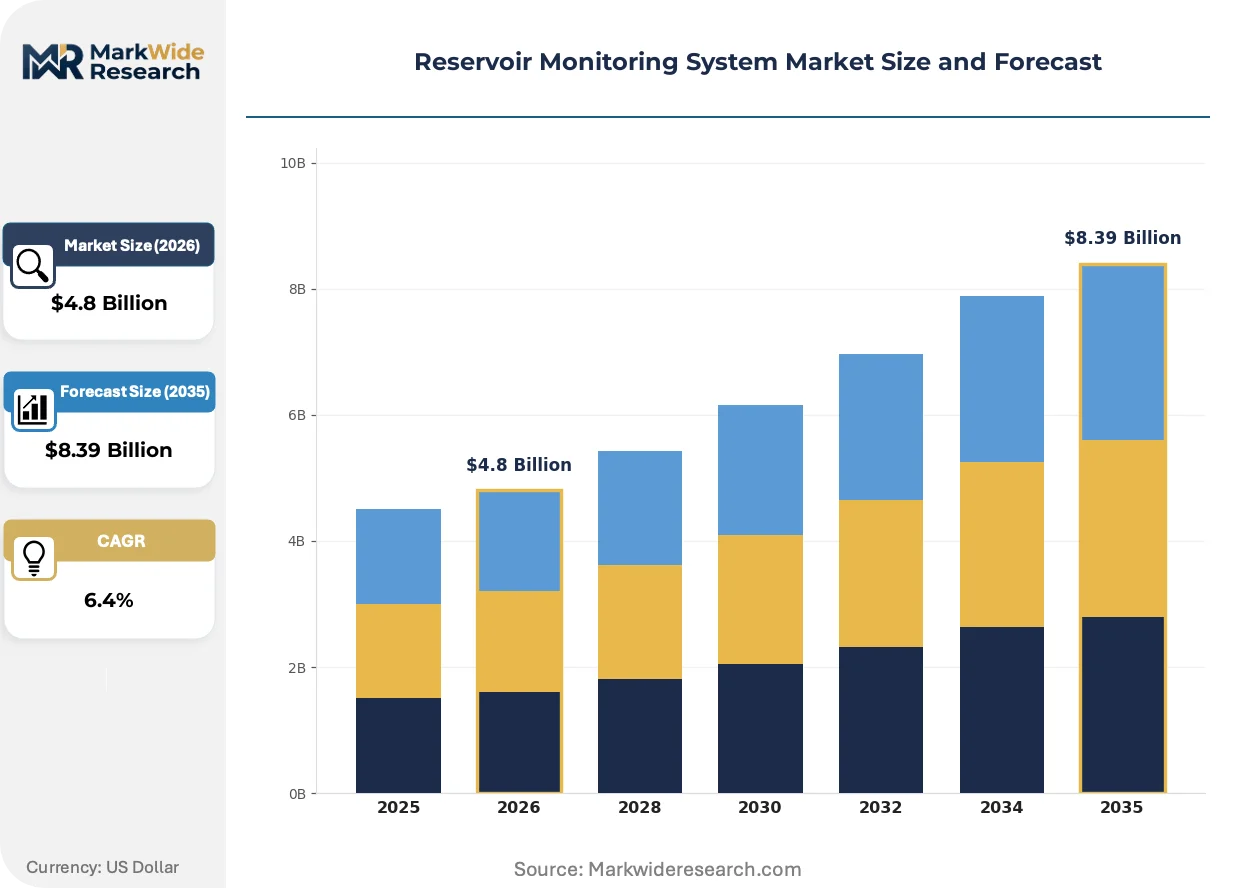
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Sensors, Pressure Gauges, Temperature Sensors, Seismic Sensors, Acoustic Sensors Technology: Wireless, Wired, Satellite, Satellite-Linked, GPS-Based, Magnetic Resonance Application: EOR Monitoring, Water Injection Control, Production Optimization, Well Integrity, Gas Injection Control End User: Oilfield Operators, Drilling Contractors, Midstream Companies, Exploration Firms, Service Providers |
| Companies Covered | CGG, Campbell Scientific, Schlumberger, Trimble Monitoring, Encardio Rite, Halliburton, Baker Hughes, OCTIO, Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reservoir Monitoring System Market Strategic Shifts & Innovations
Distributed sensing architectures are converging with edge computing capabilities, enabling downhole data processing that reduces bandwidth requirements and surface infrastructure footprint.
Fiber-optic distributed temperature sensing is automating thermal profile interpretation across steam-assisted gravity drainage operations in Canadian oil sands. Thermal operators at Suncor and Cenovus deploy single-mode fiber installations to track chamber development and optimize solvent injection timing. The technology is automating reservoir management decisions that previously required monthly wellbore logging campaigns, compressing response cycles from weeks to hours.
Norway's Petroleum Safety Authority continuous barrier verification framework is forcing permanent pressure gauge adoption across all producing wells in the Norwegian Continental Shelf. The regulation treats real-time annulus pressure monitoring as a primary well integrity defense, eliminating reliance on periodic mechanical tests. Subsea developments in the Johan Sverdrup and Snøhvit fields now specify dual-redundant gauge configurations to satisfy compliance timelines.
Integrated service contracts are displacing equipment-only procurement in deepwater developments, with operators bundling sensor supply, installation, and data interpretation under single-vendor accountability. Petrobras and TotalEnergis presalt projects favor this model to transfer operational risk and secure guaranteed uptime commitments. The shift is most pronounced in Brazil, where local content requirements complicate multivendor sourcing strategies.
Reservoir Monitoring System Market Segmentation
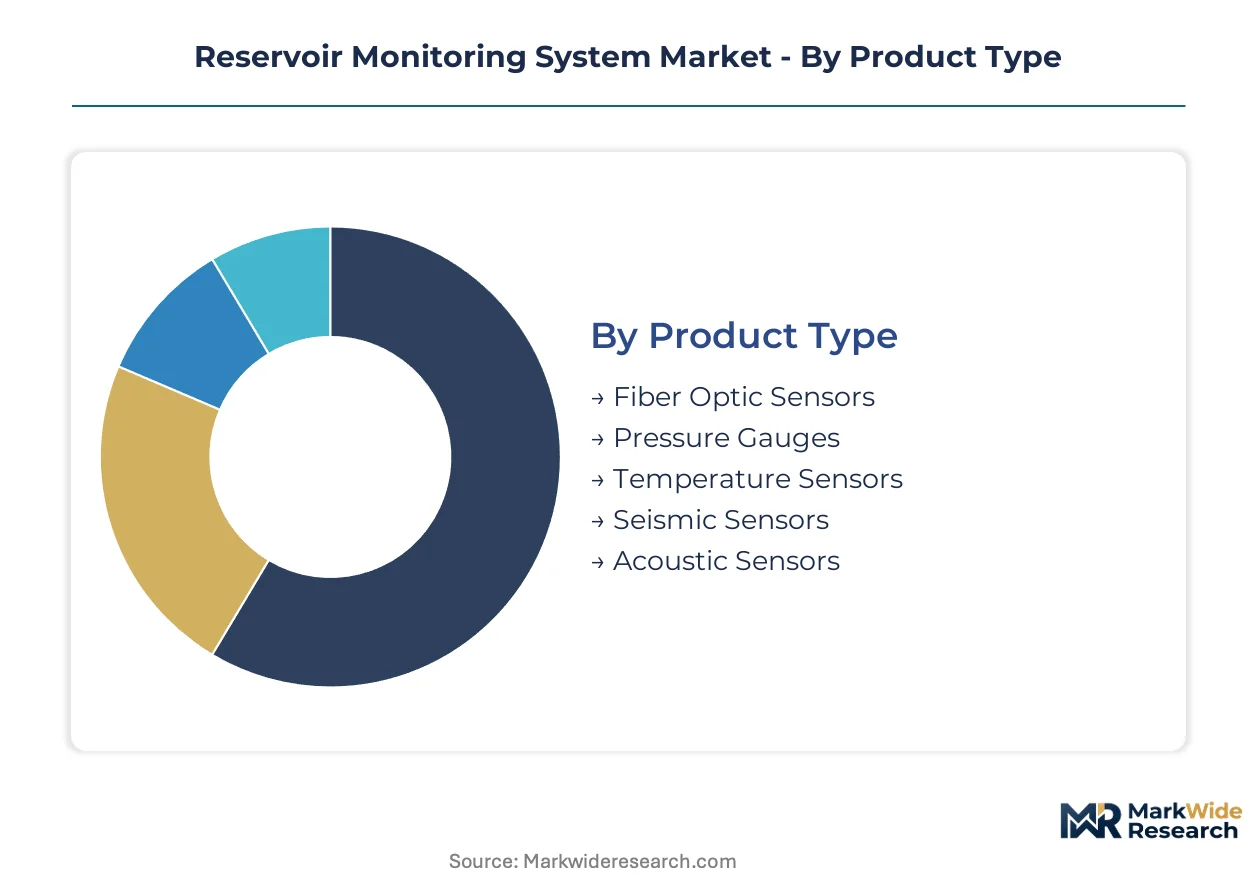
Segmentation in reservoir monitoring systems reflects the tension between standardized platform economics and field-specific engineering requirements. Procurement patterns diverge sharply between deepwater developments demanding bundled fiber-optic architectures and brownfield retrofits prioritizing wireless modularity.
Product Type:
Customization intensity varies from commodity pressure gauges to application-engineered distributed sensing arrays.
- Fiber Optic Sensors:Distributed temperature and strain profiling along single-mode fiber enables meter-scale spatial resolution across entire wellbores. Operators in Brazil's Santos Basin deploy these for continuous carbonate reservoir surveillance under presalt monitoring mandates.
- Pressure Gauges:Quartz and piezoelectric transducers measure annulus and tubing pressure in HPHT conditions exceeding 200°C and 15,000 psi. The US Bureau of Safety and Environmental Enforcement mandates these for real-time well control in Gulf of Mexico ultradeep wells.
- Temperature Sensors:Thermocouple and resistance-based probes track thermal gradients in steam-assisted gravity drainage operations.
- Seismic Sensors:Geophone and hydrophone arrays capture microseismic events for time-lapse reservoir characterization.
- Acoustic Sensors:Piezoelectric transducers detect sand production and gas breakthrough through signature frequency analysis.
Leading the category by volume: Pressure Gauges. Growing fastest: Fiber Optic Sensors.
Technology:
Deployment architecture determines capital allocation, with wired systems commanding premium pricing against wireless alternatives.
- Wireless:Electromagnetic and acoustic telemetry eliminates cable deployment costs in brownfield re-entries. North Sea operators favor these where wellbore re-entry economics prohibit conventional installations.
- Wired:Electrical conductor and fiber-optic cable architectures deliver continuous power and high-bandwidth data transmission. Deepwater subsea tiebacks off Angola and Nigeria specify wired systems for guaranteed uptime.
- Satellite:Ku-band and Ka-band links extend monitoring to remote onshore fields lacking terrestrial infrastructure.
- Satellite-Linked:Hybrid architectures combining downhole sensors with orbital data relay for offshore platform elimination.
- GPS-Based:Surface positioning synchronization for distributed seismic acquisition networks.
- Magnetic Resonance:Nuclear magnetic resonance tools provide direct fluid characterization without fluid sampling.
Wired systems dominate current installed base. Wireless configurations are expanding most quickly in mature basin retrofits.
Application:
Functional segmentation tracks the production lifecycle from injection optimization through integrity verification.
- EOR Monitoring:Thermal and chemical flood surveillance tracks front propagation and sweep efficiency. Canadian oil sands operators at Suncor and Cenovus deploy distributed temperature sensing to optimize solvent injection timing in steam-assisted gravity drainage.
- Well Integrity:Annulus pressure monitoring and barrier verification satisfies regulatory mandates. Norway's Petroleum Safety Authority treats real-time annulus monitoring as primary well integrity defense across Johan Sverdrup and Snøhvit developments.
- Production Optimization:Multizone flow allocation and choke management maximizes recovery factors.
- Water Injection Control:Profile modification and breakthrough detection manages conformance in secondary recovery.
- Gas Injection Control:Miscible flood monitoring and early breakthrough detection preserves injection efficiency.
Well Integrity commands highest regulatory-driven penetration. EOR Monitoring is gaining share fastest as thermal operations scale.
End User:
Customer segmentation reveals divergent procurement authority between capital-deploying operators and service-integrating contractors.
- Oilfield Operators:National oil companies and independents specify monitoring architectures and bear capital deployment risk. Petrobras bundles sensor supply, installation, and data interpretation under integrated service contracts for presalt developments.
- Service Providers:Drilling and completion contractors assume monitoring obligations through managed service agreements. This model transfers operational risk and secures guaranteed uptime commitments from capital-constrained operators.
- Drilling Contractors:Rig-based procurement of measurement-while-drilling and logging-while-drilling sensors.
- Midstream Companies:Pipeline and storage facility monitoring for leak detection and inventory management.
- Exploration Firms:Appraisal well testing and reservoir characterization during field delineation.
Oilfield Operators lead capital deployment. Service Providers are capturing fastest expansion through performance-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the world's densest concentration of reservoir monitoring engineering talent and subsea technology headquarters. The US Gulf of Mexico deepwater corridor drives sustained gauge replacement cycles under federal well control mandates. Norwegian Continental Shelf operators deploy redundant sensor configurations to satisfy continuous barrier verification frameworks.
United States
Ultra-deepwater developments in the Gulf of Mexico require real-time pressure monitoring for HPHT classifications under BSEE mandates. The Bureau of Safety and Environmental Enforcement accelerates sensor replacement cycles through prescriptive well integrity rules. Houston hosts the primary engineering clusters for fiber-optic distributed sensing and permanent downhole gauge manufacturing.
Brazil
Presalt carbonate reservoirs in the Santos Basin force permanent gauge deployment under ANP continuous surveillance standards. The national petroleum regulator treats real-time reservoir monitoring as mandatory for carbonate formations above salt layers. Rio de Janeiro concentrates Petrobras procurement authority and integrated service contract negotiations for subsea developments.
Norway
Johan Sverdrup and Snøhvit field operators specify dual-redundant gauge configurations to satisfy Petroleum Safety Authority compliance timelines. The regulator treats real-time annulus pressure monitoring as primary well integrity defense across all producing wells. Stavanger and Oslo anchor the engineering centers developing edge-computing downhole data processing capabilities.
Angola
West African deepwater tiebacks offshore Cabinda deploy distributed fiber-optic systems to eliminate surface platform requirements. National oil company Sonangol prioritizes wired architectures for guaranteed uptime in subsea production systems. Luanda serves as the regional procurement hub for integrated monitoring contracts spanning multiple block developments.
United Kingdom
North Sea brownfield assets present untapped demand for wireless cable-free installations where wellbore re-entry economics prohibit conventional deployments. The Oil and Gas Authority encourages asset life extension through reduced intervention technologies. Aberdeen maintains specialized engineering capacity for retrofit wireless telemetry system integration.
Reservoir Monitoring System Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration depth and bundled service scope. The market structures around three tiers: integrated subsurface platform providers, specialized well integrity monitoring houses, and component-scale gauge manufacturers. Consolidation pressures concentrate among permanent downhole gauge suppliers facing high-temperature electronics supply bottlenecks. Dominant competitive moves include integrated service contract bundling and manufacturing scale expansion for HPHT-rated transducers.
Within the integrated platform tier, Schlumberger and Halliburton occupy positions anchoring premium bundled offerings and specialized well integrity packages respectively. Baker Hughes exemplifies the manufacturing-scale archetype dominating permanent downhole gauge supply through production volume advantages. These three entities represent the competitive anchors around which procurement patterns in deepwater developments organize.
| Leading Market Players |
|---|
| CGG |
| Campbell Scientific |
| Schlumberger |
| Trimble Monitoring |
| Encardio Rite |
| Halliburton |
| Baker Hughes |
| OCTIO |
| Weatherford |
| Others |
Cost & Logistics Intelligence
Permanent downhole gauge miniaturization and fiber-optic sensing integration are compressing manufacturing cost curves while concentrating high-temperature electronics production among Japanese and German specialist suppliers. This dual shift simultaneously elevates capital barriers for new entrants and tightens procurement leverage for tier-one oilfield service companies negotiating volume commitments.
Pricing Analysis
Guaranteed uptime commitments anchor value-based pricing for integrated monitoring contracts, with Petrobras and TotalEnergies presalt developments paying premiums for single-vendor accountability. Three-tier pricing structure across premium fiber-optic distributed systems, standard wired gauge architectures, and economy wireless retrofit tiers reflects certification grade and after-sales bundling differentiation. Pricing pressure stems from Brazilian local content requirements complicating multivendor sourcing strategies. National oil companies exhibit lowest price sensitivity due to regulatory compliance mandates, while North Sea independents face acute capital constraints driving wireless adoption.
Supply Chain Analysis
Specialized semiconductor engineering talent scarcity in Tokyo and Munich manufacturing clusters constrains high-temperature pressure transducer output expansion. Quartz crystal substrates, single-mode optical fiber, and high-reliability ceramic packaging draw from concentrated Japanese, German, and US supplier bases. Single-source vulnerability pervades HPHT-rated gauge electronics due to limited qualified foundry capacity. Distribution runs through Schlumberger, Halliburton, and Baker Hughes integrated procurement networks rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reservoir monitoring system market is consolidating around integrated service contract bundling, with high-temperature electronics supply bottlenecks and extended API 19G qualification timelines forcing subscale gauge manufacturers toward exit or acquisition.
For Market Incumbents: To counter emerging wireless telemetry specialists capturing North Sea brownfield retrofits, Schlumberger and Halliburton should deepen backward integration into high-temperature semiconductor design through captive foundry partnerships in Japan. Baker Hughes must defend permanent downhole gauge manufacturing scale advantages by expanding dual-source qualification for ceramic packaging substrates.
For New Entrants and Emerging Players: Edge-computing downhole data processing capabilities present the most penetrable wedge against established fiber-optic distributed sensing incumbents. Target Norwegian Continental Shelf operators seeking reduced bandwidth requirements and surface infrastructure footprint compression. Pursue technology licensing partnerships with Stavanger engineering clusters developing autonomous thermal profile interpretation algorithms.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap wireless telemetry specialists with proven electromagnetic transmission in high-salinity brines. Long-term viability hinges on carbon capture and storage surveillance pivot readiness. Monitor US Bureau of Safety and Environmental Enforcement rulemaking on CO2 injection well integrity verification as inflection indicator for adjacent demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| HPHT Gauge Manufacturing Scale-Up | Baker Hughes expands ceramic packaging capacity to meet Gulf of Mexico replacement cycles under BSEE mandates. |
| Wireless Telemetry Product Launch | Specialist vendors target North Sea brownfield assets where wellbore re-entry economics prohibit cable deployment. |
| Integrated Service Contract Bundling | Petrobras transfers operational risk to single-vendor accountability for Santos Basin presalt developments. |
| CCS Surveillance Technology Licensing | CO2 injection plume monitoring opens adjacent demand from project developers requiring distributed acoustic sensing. |
| Edge Computing Platform Integration | Norwegian engineering centers develop downhole data processing capabilities reducing surface infrastructure requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this reservoir monitoring system analysis. Primary interviews with subsea project engineers, petroleum safety regulators, gauge procurement managers at national oil companies, and fiber-optic sensing R&D directors combined with API 19G certification databases, Norway Petroleum Safety Authority barrier verification guidelines, and Brazilian ANP presalt monitoring standards. Bottom-up sensor deployment counts and top-down oilfield service revenue triangulation validated segment splits.
Reconciliation of permanent downhole gauge installation tallies, integrated service contract values, and wireless telemetry adoption rates shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology architecture, application function, end-user procurement authority, and regional regulatory cluster stringency. CAGRs derived from slope-intercept fitting of disclosed contract values and implied sensor unit economics. Industry-specific forecast inputs encompass HPHT well classification growth trajectories and carbon capture and storage project development pipelines.
Several conditions sit outside the modeled scope, including unannounced regulatory reinterpretations by the US Bureau of Safety and Environmental Enforcement, breakthrough wireless bandwidth improvements, and abrupt shifts in Brazilian local content requirements. Forecasts reflect documented assumptions regarding qualification timeline stability and high-temperature electronics supply continuity. Material deviation in presalt monitoring mandate enforcement intensity or HPHT semiconductor foundry capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Ambient Light Sensor Market