
 Antenna Transducer and Radome Market | 2026-2036
Antenna Transducer and Radome Market Size, Share, and Industry Trends Forecast 2026-2036
Antenna Transducer and Radome Market Intelligence
The rigorous RTCA DO-160 qualification for airborne equipment is reorganizing the supply base for radomes and antenna transducers. Northrop Grumman Corporation leverages its extensive defense portfolio to secure large-scale military communication contracts. Thales Group differentiates through its strong presence in both civil aviation and defense electronics across European markets. L3Harris Technologies Inc. specializes in advanced sensor and communication systems for spaceborne and airborne platforms.
An antenna transducer converts electrical signals into electromagnetic waves, while a radome is a structural, weatherproof enclosure that protects the antenna. Radomes are often constructed from composite materials like fiberglass or quartz to minimize signal attenuation, particularly at microwave frequencies. Within technology segments, microelectromechanical systems (MEMS) are gaining traction for their miniaturization benefits in phased-array antennas. Satcom terminals and automotive radar applications represent the fastest-growing end-use categories, outpacing mature segments like traditional weather radar systems.
The U.S. Federal Aviation Administration (FAA) mandates stringent material and performance standards for radomes on commercial aircraft. Similarly, CE marking in Europe and specific military specifications (MIL-STD) dictate electromagnetic compatibility and environmental resilience for defense applications. Supplier selection will increasingly hinge on the ability to engineer solutions compliant with divergent international frequency allocation policies and material science advancements.
Market Dynamics
The transition to higher frequency bands for satellite communications and 5G infrastructure is the central force shaping the antenna transducer and radome market. This shift necessitates fundamental innovations in material science for radomes and advanced designs for transducers to manage signal integrity and power efficiency.
Growth Catalysts
- Satellite Constellation Expansion:The deployment of large-scale LEO satellite networks for global broadband internet access by commercial space ventures creates sustained demand for thousands of ground station and user terminal antennas and radomes.
- Defense Modernization:Global defense programs focused on upgrading communication, surveillance, and electronic warfare capabilities, governed by standards like MIL-STD-810, drive investment in advanced, environmentally resilient antenna systems for airborne, naval, and ground platforms.
- Automotive Radar Integration:The proliferation of advanced driver-assistance systems (ADAS) and the development of autonomous vehicles rely on multiple radar sensors, increasing the volume demand for compact, weatherproof radomes integrated into vehicle fascia.
Market Restraints
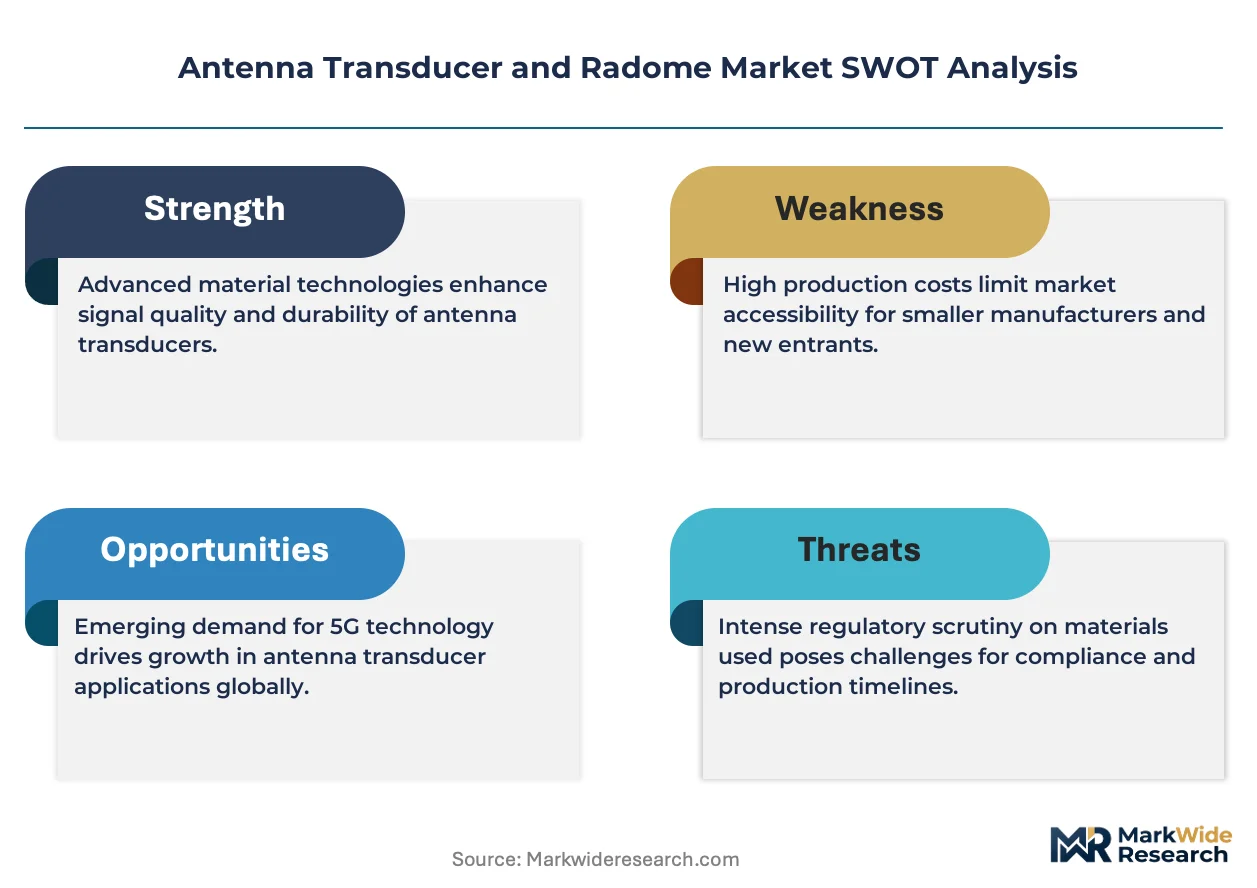
- Specialized Material Costs:High-performance radomes require materials like quartz fiber and specialized composites that have high input costs and are subject to supply chain volatility, constraining manufacturer margins.
- Signal Attenuation at High Frequencies:Designing radomes that are transparent to millimeter-wave frequencies (such as Ka, Ku, and E-bands) without significant signal loss or distortion remains a significant technical barrier, limiting performance.
- Fragmented Frequency Regulations:Manufacturers face complexity and higher development costs navigating divergent frequency allocation policies and electromagnetic compatibility standards set by national regulators like the U.S. FCC and European authorities.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging UAM and drone delivery sectors create a new market for lightweight, aerodynamically efficient radomes and compact transducers for sense-and-avoid radar and high-bandwidth communication links.
- Metamaterial Integration:Incorporating engineered metamaterials into radome construction offers the opportunity to create frequency selective surfaces (FSS) that can enhance antenna performance, reduce interference, and lower radar cross-section for defense applications.
- Underserved Broadband Markets:Expanding satellite internet services into regions with limited terrestrial infrastructure, particularly in parts of Africa and Southeast Asia, represents a significant opportunity for ground terminal antenna and radome suppliers.
Industry Challenges
- Stringent Certification Cycles:The lengthy and costly qualification process for airborne components, particularly adherence to RTCA DO-160 standards, creates high barriers to entry and extends time-to-market for new radome and antenna designs.
- RF Engineering Talent Scarcity:A shortage of radio frequency (RF) engineers and material scientists with expertise in high-frequency composite design and antenna integration hinders product development and innovation across the industry.
- Electromagnetic Interference (EMI) Mitigation:Integrating increasingly powerful and numerous antenna systems onto crowded platforms like modern aircraft and vehicles presents a major challenge in managing EMI to ensure all systems operate without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antenna Transducer and Radome Market |
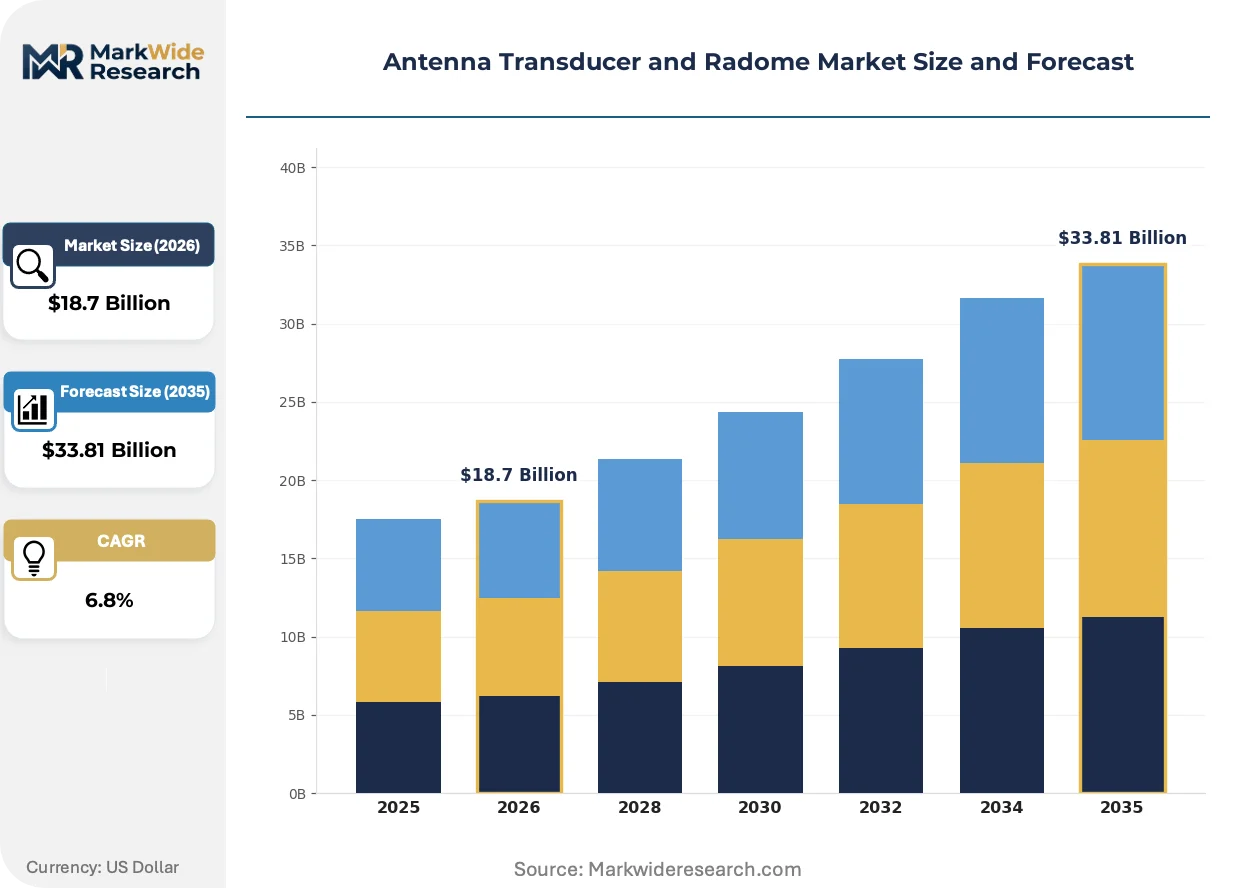
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Antennas, Horn Antennas, Parabolic Reflectors, Dielectric Resonator, Lens Antennas Technology: Piezoelectric, Capacitive, Optical Fiber, Magnetostrictive, Microelectromechanical Systems Application: Satcom Terminals, Weather Radar Systems, Military Communication, Spaceborne Sensors, Automotive Radar End User: Telecommunication Operators, Aerospace Manufactures, Defense Contractors, Satellite Service Providers |
| Companies Covered | Northrop Grumman Corporation, Thales Group, L3Harris Technologies Inc., Honeywell International Inc., BAE Systems, Raytheon Technologies, General Dynamics Mission Systems Inc., Cobham Limited, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antenna Transducer and Radome Market Strategic Shifts & Innovations
Material science and system miniaturization are redefining the performance envelope for antenna transducers and radomes. These advancements are enabling deployment on smaller platforms and in more electromagnetically complex environments, from dense urban settings to crowded satellite orbits.
Advanced Material Adoption
Microelectromechanical systems (MEMS) technology facilitates the creation of compact, low-power phase shifters, which are critical components in modern antennas. The defense and satellite communications sectors are leading the adoption of MEMS for developing agile and efficient phased-array antenna systems. This technology is miniaturizing the form factor of Satcom-on-the-move terminals and airborne radar, enabling their integration onto smaller unmanned aerial vehicles and other space-constrained platforms.
Regulatory Impact on Design
European Union CE marking, particularly compliance with the Radio Equipment Directive (RED), establishes rigorous mandates for electromagnetic compatibility and safety. This regulation compels manufacturers to invest significantly in advanced testing and simulation to ensure their antenna and radome systems do not interfere with other electronics. The automotive radar segment is heavily impacted, as engineers must guarantee flawless coexistence between multiple sensors within a single vehicle platform.
Certification-Driven Procurement
A definitive shift in buyer behavior now prioritizes suppliers with proven compliance and pre-qualification against demanding industry benchmarks like the FAA's technical standard orders (TSO). This changes procurement from a cost-centric evaluation to a risk-mitigation strategy, where certification assurance is paramount. This trend is most visible in the commercial aviation and defense sectors, where program schedules and safety are directly linked to regulatory adherence.
Antenna Transducer and Radome Market Segmentation
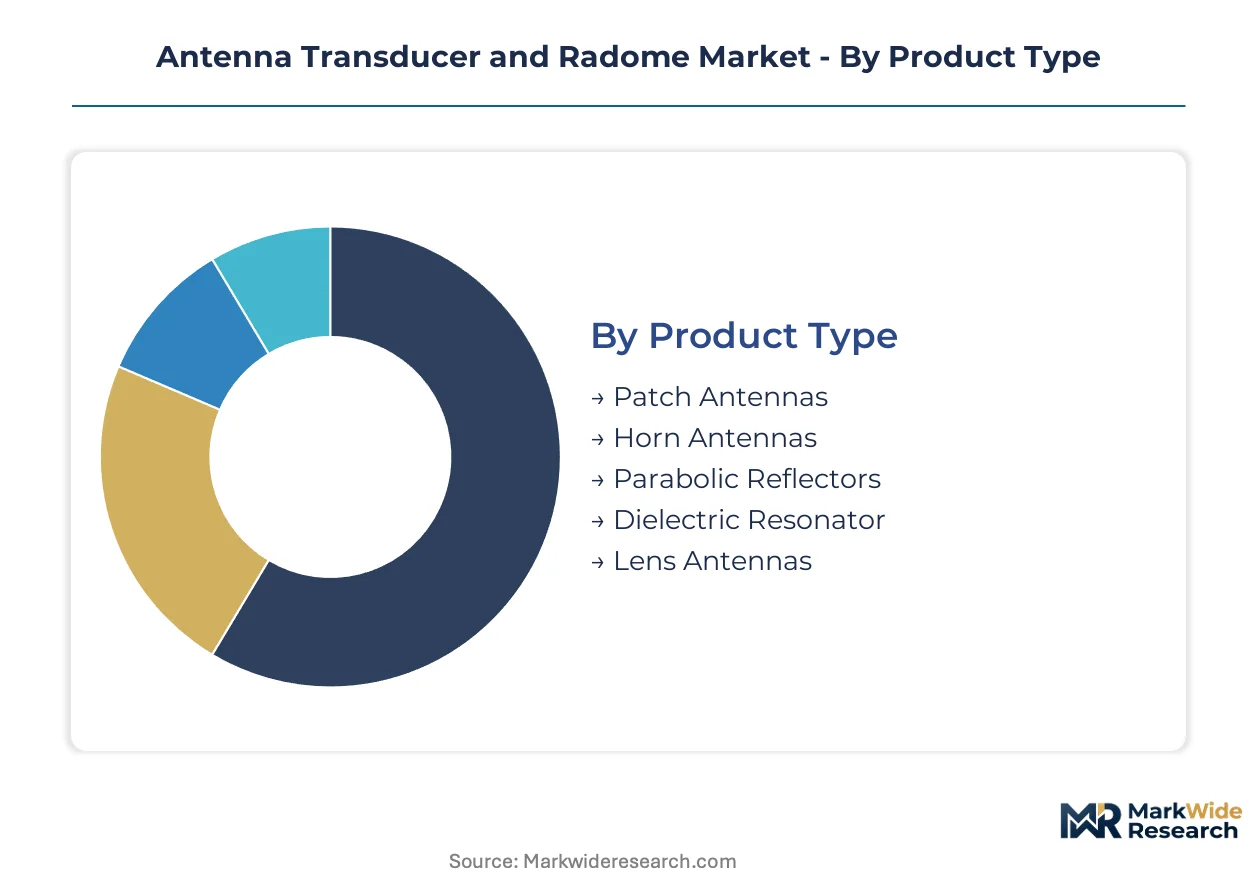
The Antenna Transducer and Radome Market segments across distinct product types, underlying technologies, operational applications, and end-user categories. Understanding these segmentations is critical for manufacturers navigating the complex interplay of regulatory compliance, performance demands, and evolving customer requirements.
Product Type:
Compliance with aviation safety standards and military specifications dictates the material composition and design of antenna product types.
- Patch Antennas:These low-profile antennas consist of a metallic patch on a dielectric substrate, offering compact form factors and ease of integration. Demand concentrates in satellite-on-the-move terminals and phased-array systems due to miniaturization benefits.
- Parabolic Reflectors:Characterized by their high gain and directional capabilities, these antennas are essential for long-range communication and deep space applications. Commercial satellite ground stations and radio astronomy observatories in the United States rely heavily on their precise signal focusing.
- Horn Antennas:These devices provide efficient radiation and impedance matching, commonly used in microwave and millimeter-wave frequency bands.
- Dielectric Resonator:These compact ceramic structures serve as resonant elements for high-frequency antenna designs, particularly in radar systems.
- Lens Antennas:These antennas utilize dielectric lenses to collimate electromagnetic waves, enhancing beamforming and gain in specialized applications.
Established volume favors Parabolic Reflectors; emerging adoption favors Patch Antennas.
Technology:
Cost efficiency and performance trade-offs define the selection of antenna transducer technologies across diverse applications.
- Microelectromechanical Systems:MEMS technology enables the development of highly miniaturized, low-power phase shifters and switches for agile beam steering in phased-array antennas. Their adoption is accelerating in defense radar systems and satellite communication terminals due to size and weight advantages.
- Piezoelectric:These transducers convert electrical energy into mechanical vibrations and vice versa, often utilized in sonar systems and specialized acoustic applications. Industrial sensing and medical imaging devices globally frequently incorporate piezoelectric elements for precise signal generation.
- Capacitive:Capacitive transducers measure changes in capacitance, finding use in pressure sensors and microphones where precise displacement detection is required.
- Optical Fiber:These transducers leverage light signals for sensing and communication, offering immunity to electromagnetic interference in harsh environments.
- Magnetostrictive:Magnetostrictive materials change shape in response to a magnetic field, serving in high-power acoustic transducers and non-destructive testing.
Technological advancements continue to drive efficiency gains in Microelectromechanical Systems, while Piezoelectric technologies maintain their niche in specialized sensing.
Application:
Specific operational environments and performance requirements shape the demand for antenna and radome applications.
- Satcom Terminals:These systems provide broadband connectivity via satellite, serving both fixed ground stations and mobile platforms across diverse geographies. The expansion of LEO constellations by companies like SpaceX and OneWeb creates sustained demand for thousands of user terminals.
- Automotive Radar:Integrated into vehicles for advanced driver-assistance systems (ADAS) and autonomous driving, these radar units require robust, compact radomes. The proliferation of ADAS features in Germany and Japan drives significant volume for these specialized sensors.
- Weather Radar Systems:These specialized radars detect precipitation and atmospheric conditions, crucial for aviation safety and meteorological forecasting.
- Military Communication:Advanced antenna systems are vital for secure and resilient communication links across land, air, and naval defense platforms.
- Spaceborne Sensors:These antennas support Earth observation, scientific research, and intelligence gathering from orbital platforms, demanding extreme reliability.
Satcom Terminals are experiencing the steepest expansion trajectory, with Automotive Radar also gaining significant market share.
End User:
The distinct operational needs and procurement cycles of various end-user segments influence antenna and radome market dynamics.
- Defense Contractors:These entities procure highly specialized, ruggedized antenna and radome solutions for military aircraft, naval vessels, and ground vehicles. Programs in the United States and the United Kingdom emphasize advanced electronic warfare and secure communication capabilities.
- Satellite Service Providers:Companies operating satellite constellations require a wide array of antennas for ground infrastructure, user terminals, and in-orbit communication. Global broadband initiatives by providers like Viasat and Hughes Network Systems drive substantial equipment procurement.
- Telecommunication Operators:These companies deploy antennas for cellular networks, 5G infrastructure, and fixed wireless access points.
- Aerospace Manufactures:Aircraft manufacturers integrate various antenna systems for navigation, communication, and weather detection on commercial and general aviation platforms.
Defense Contractors prioritize custom, rugged solutions, while Satellite Service Providers focus on scalable and cost-effective deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives across various nations are accelerating the development of advanced communication and sensing technologies. These policies stimulate investment in antenna transducer and radome solutions for defense, space, and automotive applications. Regulatory frameworks play a pivotal role in shaping market demand and technological innovation.
United States
The United States drives demand for advanced antenna systems through robust defense modernization programs and commercial space ventures. The FAA mandates stringent RTCA DO-160 qualification for airborne equipment, influencing design and materials. Silicon Valley and aerospace hubs in California concentrate research and development for satellite communication and radar technologies.
Germany
European Union CE marking and automotive safety standards propel demand for compact radomes in Germany's automotive sector. The KBA (Federal Motor Transport Authority) influences radar system integration for advanced driver-assistance systems. Bavaria and Baden-Württemberg host significant automotive and industrial electronics clusters, fostering innovation in radar sensor development.
United Kingdom
Defense programs in the United Kingdom prioritize secure military communication and electronic warfare capabilities, fueling antenna transducer procurement. The UK Ministry of Defence specifies MIL-STD requirements for environmental resilience and electromagnetic compatibility. Aerospace and defense clusters around Bristol and Farnborough lead the development of airborne radome solutions.
Japan
Japan's automotive industry leads demand for high-frequency radar systems for autonomous driving and ADAS features. METI (Ministry of Economy, Trade and Industry) promotes research into advanced materials for lightweight and transparent radomes. Industrial centers in Aichi Prefecture and the Kanto region specialize in automotive electronics and sensor manufacturing.
China
China's rapid expansion of 5G infrastructure and satellite communication networks fuels significant demand for antenna and radome components. MIIT (Ministry of Industry and Information Technology) guides the development of domestic high-frequency communication technologies. Technology hubs in Shenzhen and Shanghai are centers for manufacturing and integrating advanced antenna systems.
Antenna Transducer and Radome Market Key Industry Players
Player mix skews toward established defense contractors and specialized aerospace electronics manufacturers, reflecting the high barriers to entry in this sector. The market structure exhibits a tiered consolidation, with large integrators at the top and niche component suppliers below, often specializing in specific material science or frequency bands. Strategic archetypes include full-spectrum defense system providers, commercial aerospace specialists, and advanced material innovators focusing on high-frequency transparency. Companies frequently engage in portfolio diversification and strategic partnerships to expand market reach, alongside continuous investment in R&D for next-generation solutions.
Within the full-spectrum defense system provider archetype, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify companies leveraging extensive government contracts for advanced radar and communication systems. Thales Group, a European-based entity, represents firms with a strong presence in both civil aviation and defense electronics, spanning multiple continents. L3Harris Technologies Inc. further demonstrates the archetype of an advanced sensor and communication system specialist, particularly for spaceborne and airborne platforms. These entities often focus on integrating complex antenna and radome solutions into large-scale platforms, prioritizing stringent certification compliance and robust performance across diverse operational environments.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Group |
| L3Harris Technologies Inc. |
| Honeywell International Inc. |
| BAE Systems |
| Raytheon Technologies |
| General Dynamics Mission Systems Inc. |
| Cobham Limited |
| Lockheed Martin Corporation |
| Others |
Cost & Logistics Intelligence
Scale economies in composite manufacturing and microelectromechanical systems (MEMS) production enable competitive pricing for high-volume radome and transducer components. This efficiency shapes supply concentration and influences price floors across various application tiers.
Pricing Analysis
Certification level, such as FAA TSO and MIL-STD, creates the primary spread in antenna transducer and radome pricing. Contract-based long-term offtake agreements dominate for defense and aerospace, while automotive radar components often follow a per-unit transactional model. Performance specifications, including signal attenuation and frequency range, along with material science advancements like quartz fiber and metamaterials, justify higher prices. Cost compression in automotive radar radomes intensifies due to high volume demand and increasing competition. Automotive OEMs exhibit the highest price sensitivity for standard components, whereas defense contractors prioritize performance and certification over cost.
Supply Chain Analysis
Strategic stockpiling of specialized raw materials, rather than pure just-in-time, characterizes the antenna transducer and radome supply chain, especially for defense contracts. Supply of advanced composites and high-frequency components concentrates in the United States, Germany, and China. The industry sources critical quartz fiber, specialized resins, and MEMS components. Single-source vulnerability for niche high-performance materials poses a significant structural risk. Downstream distribution primarily occurs through direct supplier-to-OEM channels and specialized defense integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Antenna Transducer and Radome market operates with significant regulatory entrenchment as a structural advantage, creating durable competitive moats for certified suppliers. This market demands specialized expertise and high barriers to entry.
For Market Incumbents:Consolidate core technology platforms by investing in advanced material science research and development for next-generation radomes. Deepen vertical integration into specialized composite manufacturing to mitigate supply chain volatility and secure critical inputs. Expand certification capabilities across new frequency bands like E-band to counter emerging threats from less regulated competitors. Investment in FAA TSO and MIL-STD compliance remains a critical lever against rapid technological obsolescence.
For New Entrants and Emerging Players:Lead with niche innovations in metamaterial integration for frequency selective surfaces. Target underserved broadband markets in Africa and Southeast Asia for satellite internet ground terminals, which have less stringent certification requirements initially. Focus on Urban Air Mobility (UAM) and drone delivery sectors for compact, lightweight radomes. Partner with established system integrators for faster market penetration into specific application areas.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among satellite service providers and defense contractors offering long-term maintenance and upgrade contracts. The market offers strong long-term viability driven by sustained defense modernization and global satellite constellation expansion. Target specialized component manufacturers with unique intellectual property in high-frequency transducer design or advanced radome materials. Watch for increasing adoption rates of MEMS in phased-array antennas as an inflection indicator for miniaturization trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Composite R&D | This initiative enhances radome transparency and durability for millimeter-wave frequencies, critical for next-generation Satcom terminals. |
| Expand Regulatory Certification Scope | Achieving compliance with diverse standards like CE marking and MIL-STD opens access to new European and defense market segments. |
| Develop Miniaturized MEMS Transducers | This enables integration onto smaller platforms, such as unmanned aerial vehicles, addressing the demand for compact sensor systems. |
| Form Strategic Partnerships with OEMs | Collaborating with automotive manufacturers ensures early integration of radar radomes into advanced driver-assistance systems. |
| Target Underserved Satellite Broadband Regions | This strategy capitalizes on the expansion of LEO constellations to provide internet access in remote areas globally. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement leads, and regulatory affairs specialists, and refined through iterative analysis. This involved combining in-depth primary interviews with rigorous secondary validation from industry reports. Secondary data sources included FAA technical standard orders, European Radio Equipment Directive guidelines, and defense contract award databases. Bottom-up market sizing was triangulated with top-down validation to ensure data consistency.
Variance decomposition was applied to isolate the impact of key drivers, such as satellite constellation deployment and ADAS proliferation, on market growth. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, technology, application, and end-user. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included planned satellite launches and automotive radar integration rates.
The analysis sits within stated boundaries; outcomes outside significant shifts in global frequency allocation policies or material science breakthroughs would require recalibration. Forecasts reflect assumptions regarding regulatory stability and technological progression. Revision becomes warranted when major defense spending cuts or widespread supply chain disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Industrial Controllers Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
North America Pressure Sensors Market