
 RTD Temperature Sensors Market | 2026-2036
RTD Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Temperature Sensors Market Analytics
IEC 60751 compliance is rotating supplier eligibility across the RTD temperature sensors landscape, filtering out uncertified manufacturers from precision-critical contracts. Honeywell International, Inc. leverages its aerospace and industrial automation heritage to sustain long-term supply agreements with tier-one manufacturers. ABB Ltd. anchors European process industries through its Endress+Hauser Group Services AG partnership channel, while Analog Devices, Inc. competes on signal-conditioning integration for digital-output variants.
Resistance temperature detectors employ platinum, nickel, or copper wire wound or deposited on ceramic substrates, measuring temperature through predictable electrical resistance change—typically offering ±0.1°C accuracy from -200°C to 850°C for platinum elements. Wired installations dominate heavy industrial settings where electromagnetic interference demands shielded cable runs, whereas wireless configurations gain traction in remote monitoring and predictive maintenance architectures across energy and food processing applications. Digital output segments command premium positioning due to embedded calibration and bus-protocol compatibility that reduces system integration cost.
The US FDA and EPA impose validation and environmental monitoring requirements that shape sensor specifications in pharmaceutical and wastewater treatment deployments, while IEC standards govern international interchangeability. Siemens AG navigates these overlapping compliance frameworks through region-specific product certifications that streamline customer qualification timelines. Stakeholders must monitor evolving cybersecurity mandates for wireless sensor networks as industrial IoT adoption broadens attack surfaces beyond traditional process safety concerns.
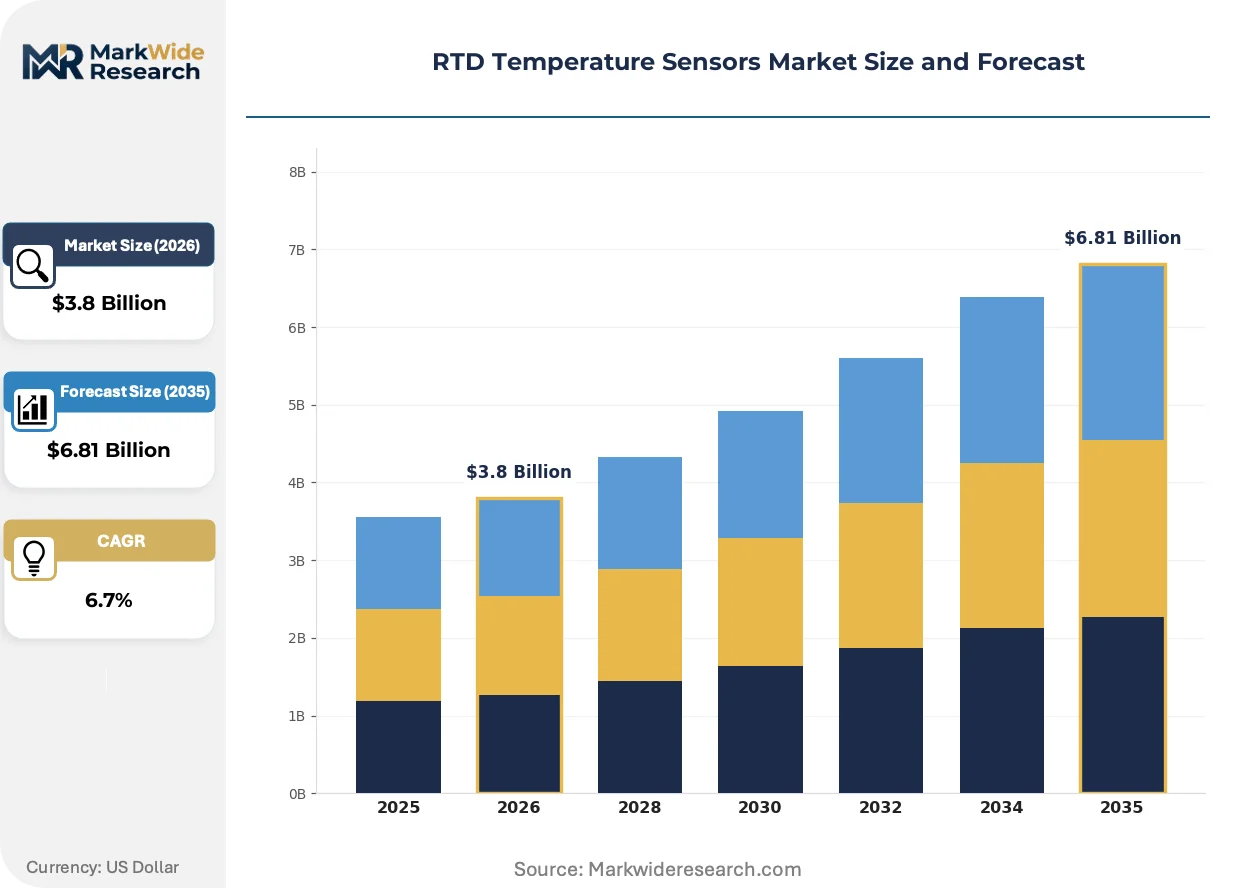
Market Dynamics
IEC 60751 calibration mandates and thin-film platinum element migration are compressing supplier eligibility while elevating precision requirements across process industries. This structural tightening favors manufacturers with captive metrology capabilities and certified production lines.
Growth Catalysts
- Industrial IoT integration:Food processing plants in Germany deploy wireless RTD arrays for continuous thermal profiling, replacing manual spot-checks with real-time data streams.
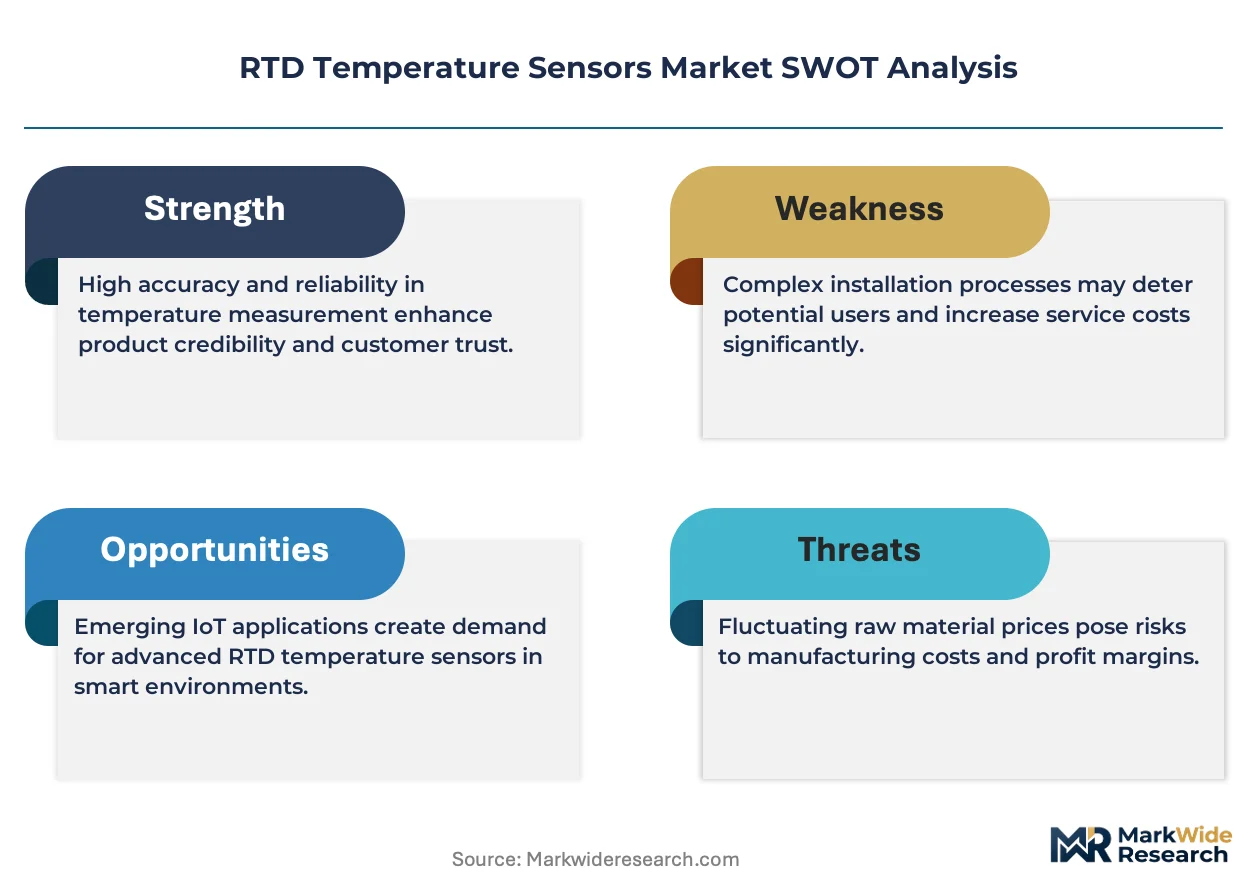
- REACH material compliance:RoHS and REACH substance restrictions are accelerating nickel and copper element substitution with platinum thin-film alternatives in European chemical processing.
- Automotive battery manufacturing:Lithium-ion cell formation protocols require ±0.1°C thermal uniformity, pulling high-precision RTD volumes into gigafactory buildouts.
Market Restraints
- Platinum price volatility:Spot metal fluctuations compress margin predictability for wire-wound element producers locked into annual supply contracts.
- Single-source ceramic substrate dependence:High-purity alumina supply concentrates among Japanese and German specialty ceramics manufacturers, creating geographic concentration risk.
- Thermocouple substitution in extreme ranges:Type K and Type N thermocouples retain cost advantages above 850°C, limiting RTD addressable market in steel and glass melting.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO validation requirements for vaccine storage create certified RTD demand in warehousing and last-mile distribution infrastructure.
- Digital-output sensor convergence:IO-Link and HART protocol integration enables direct PLC connectivity, eliminating separate transmitter hardware in brownfield automation retrofits.
- EU Green Deal process efficiency mandates:Industrial decarbonization targets drive thermal optimization investments across German and Dutch chemical clusters.
Industry Challenges
- IEC 60751 Class AA calibration capacity:Metrology-grade water baths and resistance bridges require seven-figure capital investment, constraining mid-tier manufacturer qualification.
- Legacy 4-20mA infrastructure integration:Digital-output RTD deployment demands signal conditioner replacement in installed base, extending sales cycles and complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Temperature Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Analog, Digital Application: Industrial Automation, HVAC Systems, Food Processing, Medical Equipment Installation: Surface Mount, Insertion, Immersion, Panel Mount End User: Manufacturing, Healthcare, Energy, Aerospace |
| Companies Covered | Texas Instruments Incorporated, Honeywell International, Inc., ABB Ltd., Analog Devices, Inc., Emerson Electric Company, Endress+Hauser Group Services AG, Amphenol Corporation, Siemens AG, Microchip Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Temperature Sensors Market Evolving Landscape
Thin-film deposition techniques and embedded calibration intelligence are redefining performance benchmarks while regulatory fragmentation across jurisdictions complicates product platform standardization.
Platinum thin-film elements deposited via sputtering onto ceramic substrates deliver faster thermal response and improved vibration resistance compared to traditional wire-wound constructions. Semiconductor fabrication and aerospace propulsion test facilities are adopting these variants for thermal cycling durability. Wire-wound RTDs are displacing from high-volume industrial automation as thin-film consistency and long-term stability metrics converge.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration and HVAC OEMs to redesign thermal management architectures for lower-GWP refrigerants. This regulatory pressure cascades into sensor specification changes as operating temperature ranges and pressure profiles shift. Cold chain equipment manufacturers in Germany and France are accelerating RTD qualification cycles to match compressor platform redesign timelines.
Sensor-as-a-service contracting is emerging among pharmaceutical and biotechnology end-users seeking to unbundle hardware ownership from calibration and compliance documentation obligations. Distributors and system integrators are capturing recurring revenue streams previously held by sensor manufacturers. This model concentrates in North American and Western European markets where validation paperwork carries substantial labor cost.
RTD Temperature Sensors Market Segmentation
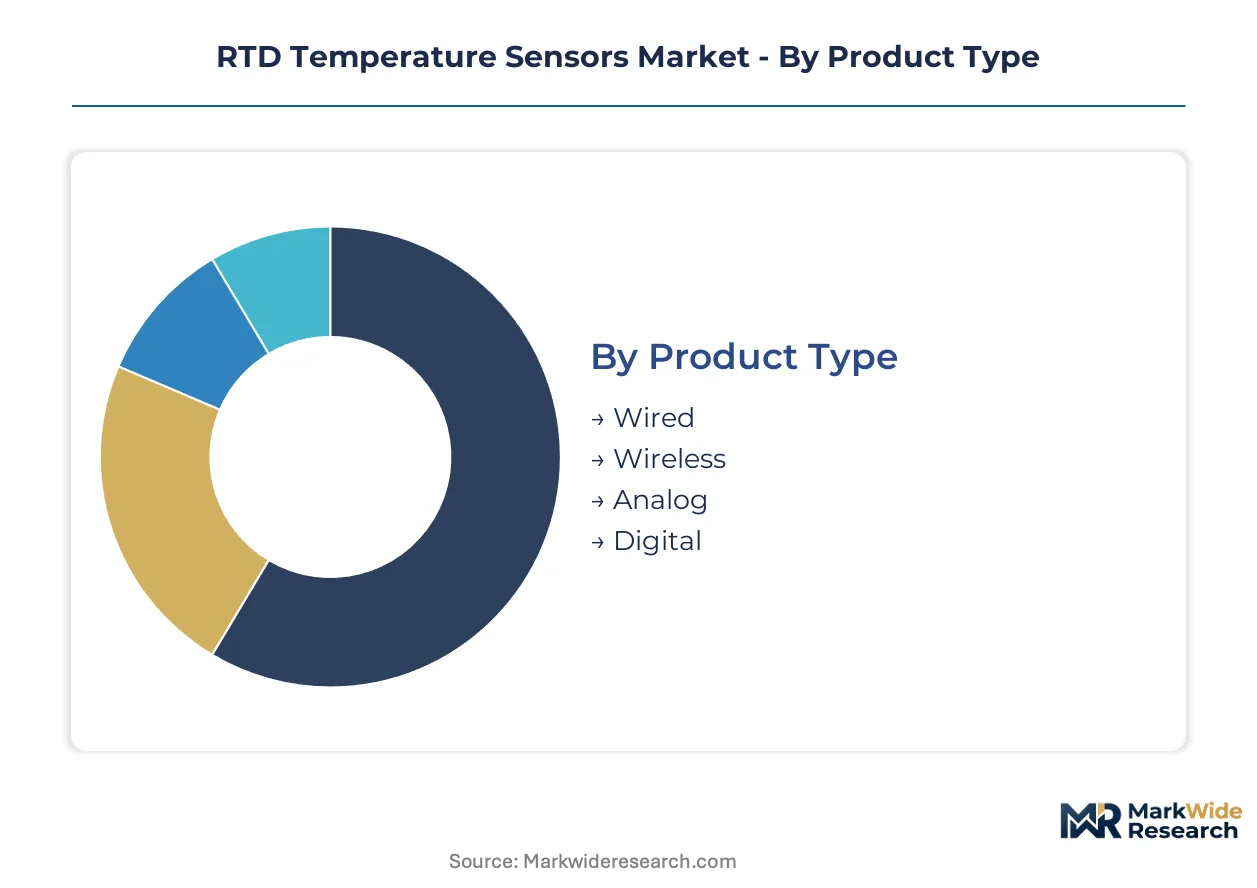
RTD temperature sensor procurement decisions hinge on installation constraints, signal architecture, and calibration requirements that vary sharply across process environments. Segment boundaries are blurring as digital-output variants absorb transmitter functions and wireless arrays displace wired infrastructure in brownfield retrofits.
Product Type:
Margin pools concentrate in digital-output variants where embedded signal conditioning and protocol compatibility command pricing premiums over analog alternatives.
- Wired:Shielded cable configurations dominate heavy industrial settings in Germany where electromagnetic interference from motor drives demands grounded conductor runs. Chemical processing clusters along the Rhine corridor specify wired RTDs for SIL-rated safety loops.
- Wireless:Battery-powered sensor networks with mesh topology are penetrating food processing plants in France for thermal profiling of continuous ovens. Elimination of conduit runs reduces installation cost by half in greenfield bakery automation projects.
- Analog:4-20mA output variants retain installed base dominance in legacy DCS architectures across US Gulf Coast refineries.
- Digital:IO-Link and HART protocol integration enables direct PLC connectivity without separate transmitters.
Wired configurations hold installed capacity. Wireless is rotating up the share rankings.
Application:
Volume concentrates in process manufacturing where thermal uniformity directly correlates with yield metrics and regulatory compliance documentation.
- Industrial Automation:PID control loops in automotive paint shops and semiconductor diffusion furnaces demand ±0.1°C stability. German OEMs specify Class AA calibrated elements for robot welding cell thermal monitoring.
- HVAC Systems:EU F-Gas Regulation phase-downs are forcing refrigerant architecture redesigns in French and Italian commercial building equipment. RTD qualification cycles compress to match compressor platform timelines.
- Food Processing:Pasteurization validation requires FDA-compliant 21 CFR Part 11 documentation in US dairy operations.
- Medical Equipment:Sterilization autoclaves and blood storage units specify medical-grade platinum elements with traceable calibration chains.
Industrial Automation anchors current procurement volumes. HVAC Systems are climbing the fastest as building decarbonization mandates accelerate equipment replacement cycles.
Installation:
Application environment dictates mechanical interface selection, with thermal response time and pressure containment requirements driving specification divergence.
- Surface Mount:Adhesive-backed thin-film elements attach to motor housings and heat exchanger surfaces in wind turbine nacelles. Offshore wind installations in the North Sea specify marine-grade stainless steel sheaths for salt spray resistance.
- Insertion:Thermowell-protected probes penetrate pressurized pipelines in Dutch chemical plants. Spring-loaded designs maintain tip contact for vibration environments.
- Immersion:Direct liquid contact configurations serve bioreactor temperature control in Swiss pharmaceutical manufacturing.
- Panel Mount:Instrument enclosure integrations dominate switchgear and control cabinet applications.
Insertion styles hold installed capacity. Surface Mount is expanding most quickly with renewable energy buildouts.
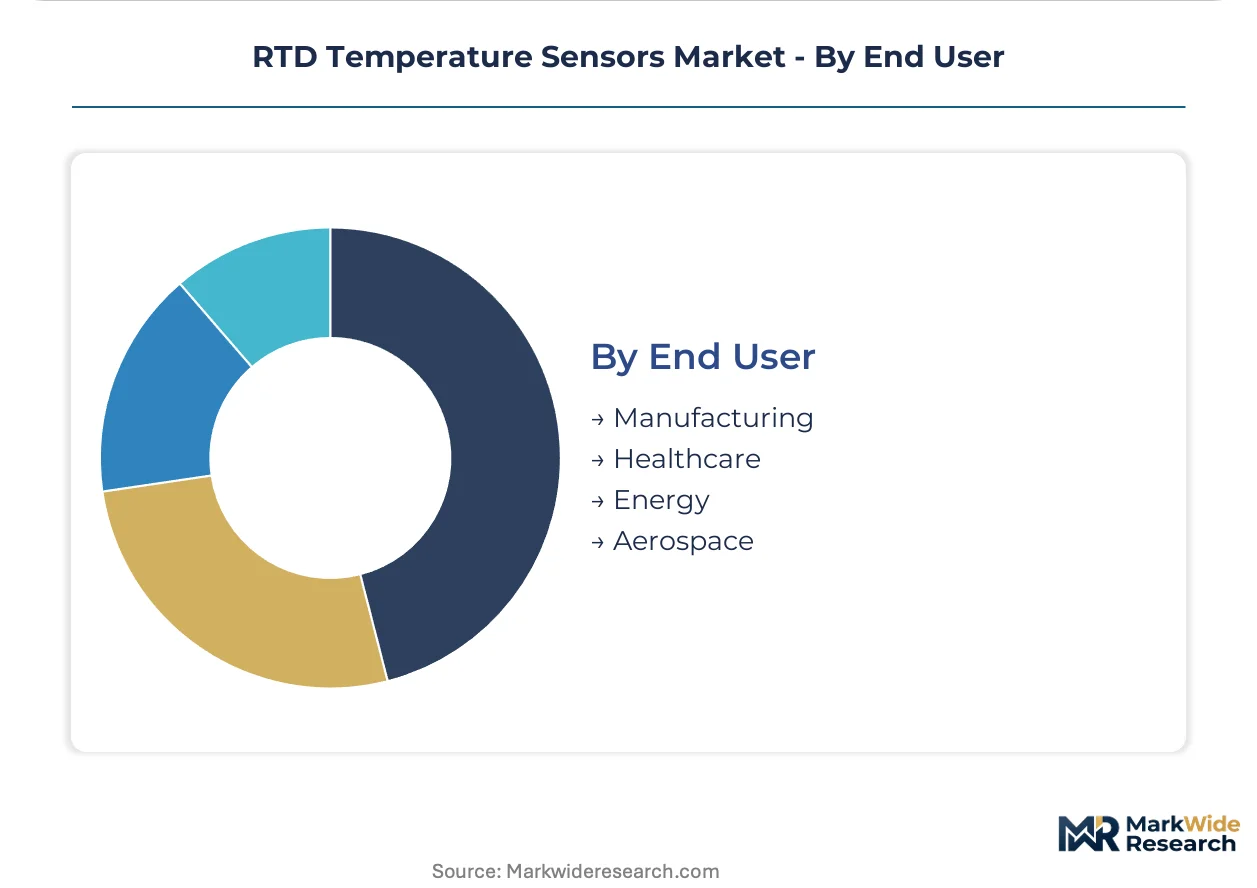
End User:
Customer procurement maturity varies, with aerospace and healthcare demanding certified supply chains that filter out uncertified manufacturers.
- Manufacturing:Automotive battery gigafactories in Germany and Hungary pull high-precision RTD volumes for lithium-ion cell formation thermal management. Cell temperature uniformity within ±0.1°C determines electrochemical performance consistency.
- Healthcare:Cold chain validation for vaccine distribution creates certified sensor demand in Indian warehousing infrastructure under CDSCO oversight. Last-mile distribution monitoring requires wireless datalogger integration.
- Energy:Combined cycle power plants specify mineral-insulated cable constructions for turbine exhaust monitoring.
- Aerospace:Propulsion test facilities adopt thin-film variants for thermal cycling durability in rocket engine qualification.
Manufacturing commands current volume leadership. Healthcare is gaining share fastest with biologics cold chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal industrial decarbonization mandates and national clean manufacturing incentives are redrawing procurement geography across high-precision temperature sensing. German chemical clusters, US battery gigafactories, and Indian pharmaceutical cold chains now anchor three distinct demand poles with diverging certification requirements.
Germany
Automotive battery formation and chemical process optimization drive Class AA calibrated RTD procurement. The EU F-Gas Regulation accelerates refrigerant system redesigns in commercial HVAC equipment. The Rhine-Main chemical corridor around Frankfurt and Ludwigshafen concentrates thin-film element qualification programs for pharmaceutical thermal uniformity.
United States
FDA 21 CFR Part 11 validation requirements and EPA environmental monitoring standards shape sensor specifications in biologics manufacturing and wastewater treatment. The Inflation Reduction Act's clean energy tax credits pull precision thermal instrumentation into lithium-ion gigafactory construction. Texas and Michigan automotive clusters specify SIL-rated wired configurations for welding robot thermal monitoring.
India
CDSCO cold chain validation mandates for vaccine distribution create certified sensor demand in warehousing infrastructure. The Production-Linked Incentive scheme for pharmaceuticals accelerates temperature-controlled storage buildouts. Maharashtra and Gujarat pharmaceutical manufacturing zones deploy wireless RTD arrays for last-mile distribution monitoring.
China
Dual carbon goals and MIIT smart manufacturing directives elevate process efficiency investments across chemical and semiconductor fabrication. GB standards compliance requirements filter supplier eligibility for domestic automation retrofits. The Yangtze River Delta semiconductor diffusion furnace cluster specifies platinum thin-film elements for ±0.1°C thermal uniformity.
Japan
METI energy efficiency regulations and JIS standard harmonization shape industrial automation sensor procurement. High-purity alumina ceramic substrate supply concentrates among domestic specialty ceramics manufacturers. The Chubu region around Nagoya anchors aerospace propulsion test facility adoption of thin-film variants for thermal cycling durability.
RTD Temperature Sensors Market Competitive Landscape
Listed leaders compete with private specialists across calibration certification and protocol integration capabilities. The vendor base organizes into three tiers: multinational industrial automation conglomerates with captive metrology facilities, semiconductor-focused signal conditioning specialists, and regional sensor fabricators with process industry relationships. Consolidation pressure concentrates among mid-tier manufacturers lacking IEC 60751 Class AA calibration capacity. Dominant competitive moves include strategic partnerships with system integrators and backward integration into thin-film element deposition.
Among diversified industrial technology conglomerates, Honeywell International, Inc. and Siemens AG exemplify archetypes combining aerospace heritage with process automation certification depth. Analog Devices, Inc. occupies a position within the signal conditioning specialist tier, leveraging semiconductor fabrication expertise for embedded calibration integration. These three anchors represent distinct competitive vectors: protocol breadth, vertical application depth, and silicon-level integration.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Honeywell International, Inc. |
| ABB Ltd. |
| Analog Devices, Inc. |
| Emerson Electric Company |
| Endress+Hauser Group Services AG |
| Amphenol Corporation |
| Siemens AG |
| Microchip Technology, Inc. |
| Others |
Value Network & Pricing Analysis
IEC 60751 Class AA calibration requirements gate both supplier qualification and price differentiation simultaneously, compressing the vendor base into certified manufacturers while stretching price spreads between metrology-grade and industrial-grade offerings. Thin-film platinum element migration and REACH substance restrictions further stratify procurement tiers as European chemical and pharmaceutical buyers demand traceable calibration chains.
Pricing Analysis
Certification level (IEC 60751 Class AA versus Class A/B) creates the primary spread across RTD temperature sensor procurement, with metrology-grade variants commanding substantial premiums over industrial-grade alternatives. Pricing stratifies across premium, standard, and economy tiers based on calibration traceability and signal conditioning integration, with digital-output variants absorbing transmitter functions to justify higher unit economics. Cost compression in wire-wound element production is intensifying because platinum spot price volatility erodes margin predictability for producers locked into annual supply contracts. Automotive battery gigafactories exhibit the least price sensitivity due to thermal uniformity requirements, while HVAC OEMs facing F-Gas Regulation redesign timelines pressure suppliers most aggressively on unit cost.
Supply Chain Analysis
Inventory cycles for high-purity alumina ceramic substrates extend lead times for thin-film element qualification programs, constraining rapid scale-up for emerging sensor fabricators. Manufacturing concentrates in Germany, Japan, and the United States, with high-purity alumina supply anchored in Japanese and German specialty ceramics producers creating geographic concentration risk. The supply chain draws from platinum group metal refiners, ceramic substrate specialists, and semiconductor-grade deposition equipment vendors, with single-source ceramic substrate dependence representing the dominant structural vulnerability. Distribution runs through industrial automation distributors and system integrators, with direct OEM relationships gaining share among high-volume automotive and pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German automotive OEMs and battery cell producers is shifting buyer power toward volume-contracting leverage, compressing margin pools for uncertified sensor fabricators. Fragmentation among mid-tier industrial automation buyers sustains niche opportunities for specialized calibration service providers.
For Market Incumbents: Consolidate calibration certification depth and captive metrology capacity to defend against thin-film specialist entrants and semiconductor signal conditioning players. Backward integration into platinum thin-film deposition reduces ceramic substrate supply risk while locking in margin capture from element to finished sensor. Prioritize IEC 60751 Class AA capacity expansion in the Rhine-Main corridor to match German chemical cluster qualification timelines. For New Entrants and Emerging Players: Sensor-as-a-service calibration documentation gaps in North American pharmaceutical markets offer white-space entry where incumbents under-serve validation-heavy procurement workflows. Target Indian pharmaceutical cold chain infrastructure under CDSCO oversight, where certified RTD demand outpaces established supplier qualification capacity. Deploy wireless datalogger integration as the primary go-to-market angle, bundling hardware with recurring compliance documentation subscriptions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IEC 60751 Class AA calibration infrastructure, favoring scaled incumbents with existing metrology-grade water bath and resistance bridge investments. Long-term viability over the next decade rests on certification moats rather than manufacturing scale alone. Acquire mid-tier sensor fabricators with process industry relationships but lacking Class AA capacity, extracting value through calibration line retrofit. Monitor platinum price volatility and ceramic substrate supply contract renegotiations as the primary inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thin-Film Deposition | Captures margin from platinum element through finished sensor assembly for German automotive OEMs. |
| IEC 60751 Class AA Calibration Capacity Expansion | Qualifies suppliers for pharmaceutical and battery formation contracts requiring ±0.1°C traceability. |
| Wireless Sensor-as-a-Service Platform Launch | Converts hardware transactions into recurring revenue with bundled FDA 21 CFR Part 11 documentation. |
| Strategic Partnership with System Integrators | Accelerates brownfield retrofit penetration through channel control over PLC integration workflows. |
| Geographic Manufacturing Footprint in India | Positions for CDSCO-certified cold chain sensor demand in vaccine distribution infrastructure buildouts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC standard documentation, trade customs records, and SEC filings from listed industrial automation conglomerates. Primary interviews engaged plant engineers at German chemical clusters, procurement leads at automotive battery gigafactories, calibration laboratory directors, and distribution channel partners across European industrial automation markets. Bottom-up sensor shipment estimates triangulate against top-down process industry capital expenditure patterns and thermal instrumentation procurement disclosures.
Segmentation dimensions modeled include product architecture (wired, wireless, analog, digital), installation configuration (surface mount, insertion, immersion, panel mount), application environment (industrial automation, HVAC, food processing, medical equipment), and end-user procurement maturity (manufacturing, healthcare, energy, aerospace). CAGRs derive from regression analysis of historical shipment volumes against process industry capacity expansion timelines and regulatory mandate implementation schedules. Forecast inputs incorporate EU F-Gas Regulation phase-down compliance deadlines and Inflation Reduction Act clean energy tax credit qualification windows.
Underlying assumptions cover sustained platinum thin-film element migration, IEC 60751 certification enforcement continuity, and industrial IoT protocol standardization, with deviation risk concentrated in ceramic substrate supply disruptions and cybersecurity mandate acceleration for wireless sensor networks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Smart Thermometer Market