
 Smart Temporal Thermometer Market | 2026-2036
Smart Temporal Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Temporal Thermometer Market Insights
ISO 13485 certification is redrawing competitive boundaries in the smart temporal thermometer sector. Exergen Corporation leverages its proprietary arterial heat balance technology to sustain leadership in clinical-grade forehead scanning. Koninklijke Philips N.V. anchors its position through deep integration with connected health ecosystems, while OMRON Corporation differentiates via manufacturing scale across Asian consumer channels.
A smart temporal thermometer measures infrared radiation emitted from the temporal artery or forehead skin to calculate core body temperature, typically operating within ±0.2°C accuracy through thermopile sensors and ambient temperature compensation algorithms. The device serves primary purposes in home health monitoring, clinical triage, and pediatric care where speed and non-invasive operation matter. Infrared product types dominate hospital procurement due to speed and hygiene protocols, while home users increasingly drive digital segment volume through pharmacy and online channels. Premium price tiers capture concentrated margin pools in North American and European clinical settings where reimbursement validates higher device costs.
FDA 510(k) premarket notification requirements govern clinical claims in the United States, while the EU Medical Device Regulation (MDR) and CE marking framework reshape conformity assessment pathways for European market access. Japan's Ministry of Economy, Trade and Industry (METI) and Pharmaceutical and Medical Devices Agency (PMDA) coordinate standards for home medical devices with data transmission capabilities. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify connected thermometers and trigger additional validation burdens.
Market Dynamics
ISO 13485 certification requirements are compressing vendor margins while simultaneously erecting entry barriers that favor established infrared sensor manufacturers with validated quality management systems.
Growth Catalysts
- Pediatric home care expansion:Parents in Germany prioritize non-invasive fever monitoring for infants, creating sustained replacement demand for connected temporal scanners with smartphone integration.
- FDA 510(k) pathway clarity:Streamlined premarket notification for infrared clinical devices accelerates time-to-market for thermopile-based thermometers targeting hospital triage workflows.
- Aging-in-place infrastructure:Japan's remote patient monitoring programs embed temporal scanning into chronic care protocols for elderly patients managing cardiovascular conditions.
Market Restraints
- Thermopile sensor supply concentration:German and Japanese precision sensor foundries control critical infrared detector output, exposing downstream assemblers to allocation risk during semiconductor cycles.
- EU MDR conformity costs:Expanded clinical evidence requirements for Class IIa medical devices extend validation timelines and force portfolio rationalization among smaller manufacturers.
- Contactless ultrasound alternatives:Emerging Doppler-based core temperature estimation threatens temporal infrared's position in critical care settings where absolute accuracy dominates purchase criteria.
Strategic Opportunities
- Software-as-a-medical-device reclassification:FDA draft guidance on connected health algorithms creates first-mover advantage for vendors with validated cloud-based temperature trend analysis.
- Pharmacy channel digitization:European retail pharmacy chains integrate smart thermometers into diagnostic service counters, shifting volume from hospital procurement to consumer-direct models.
- Ambient temperature compensation convergence:Fusion of MEMS environmental sensors with thermopile arrays enables single-chip solutions that reduce bill-of-materials complexity for Asian contract manufacturers.
Industry Challenges
- Clinical validation talent scarcity:Biostatisticians with infrared metrology expertise command premium compensation, constraining mid-tier vendors' ability to execute multi-site equivalence studies.
- Legacy health record integration:HL7 FHIR connectivity requirements force redevelopment of device firmware for US hospital systems, delaying deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Temporal Thermometer Market |
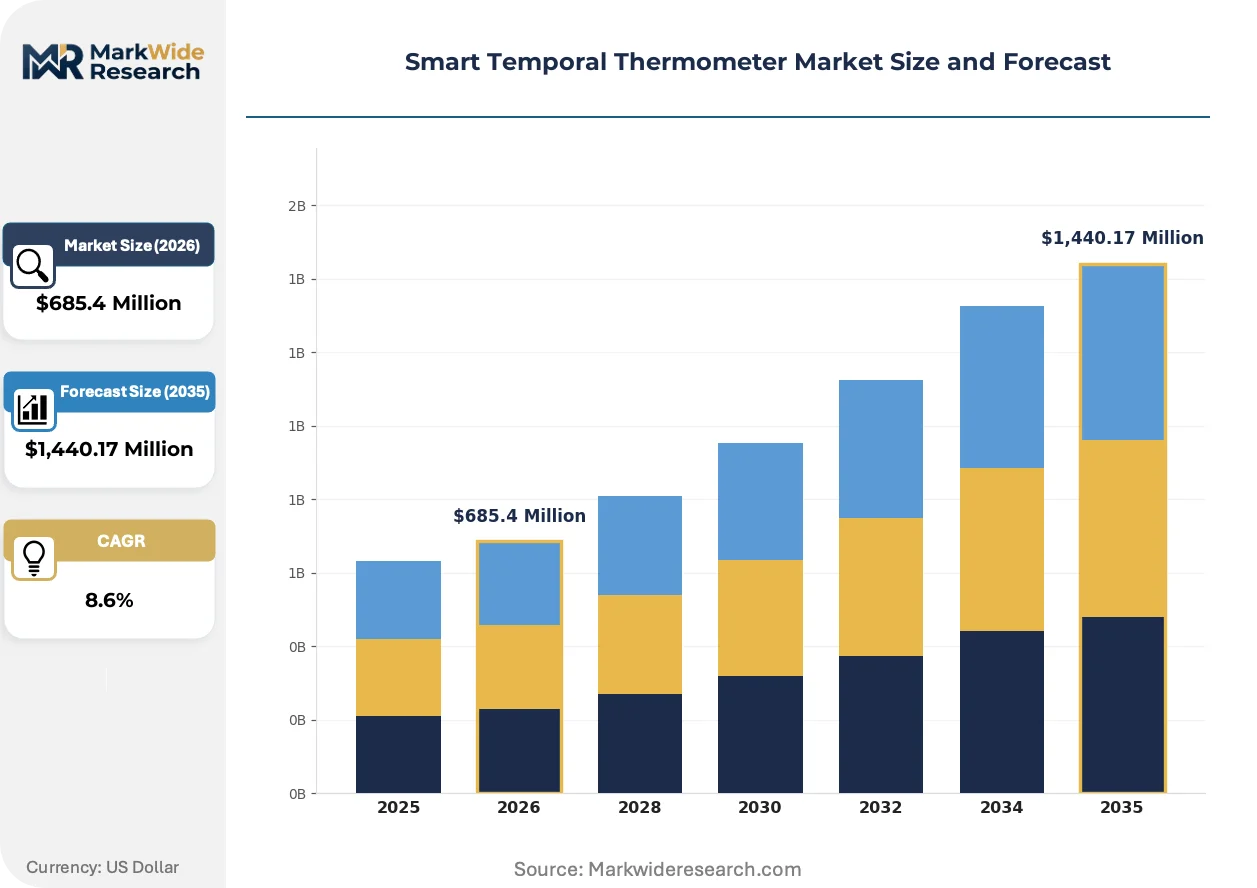
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,440.17 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Digital, Ear, Forehead End User: Home Users, Hospitals, Clinics, Laboratories Distribution Channel: Online, Retail, Distributors, Pharmacies Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Exergen Corporation, 3M Company, Welch Allyn, Koninklijke Philips N.V., Medtronic, Terumo Corporation, OMRON Corporation, Microlife Corporation, Briggs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Temporal Thermometer Market Trends and Innovations
Silicon photonics and edge computing are compressing device footprints while elevating measurement precision, fundamentally altering how temperature data flows from patient to provider.
Thermopile arrays with integrated ASIC signal conditioning are miniaturizing from discrete component assemblies to single-package solutions. Pediatric device manufacturers in Taiwan adopt these modules to halve PCB area in wearable fever monitors. This integration is miniaturizing housing dimensions while maintaining ±0.2°C clinical accuracy, enabling earbud-form-factor products that bypass traditional forehead scanning entirely.
Japan's PMDA and METI coordinate revised technical standards for home medical devices with data transmission capabilities, mandating encryption protocols for cloud-connected thermometers. Device vendors must resubmit existing registrations under the 2024 framework, favoring incumbents with established regulatory affairs infrastructure. Hospital procurement teams in Tokyo now require PMDA cybersecurity certification as a gate criterion for new vendor qualification.
Consumers increasingly purchase temporal thermometers through pharmacy subscription services rather than episodic retail transactions. Walgreens and CVS Health in the United States bundle connected devices with telehealth access, displacing standalone hardware margins with recurring service revenue. This model concentrates most rapidly in metropolitan markets where same-day delivery infrastructure supports urgent fever monitoring needs.
Smart Temporal Thermometer Market Segmentation
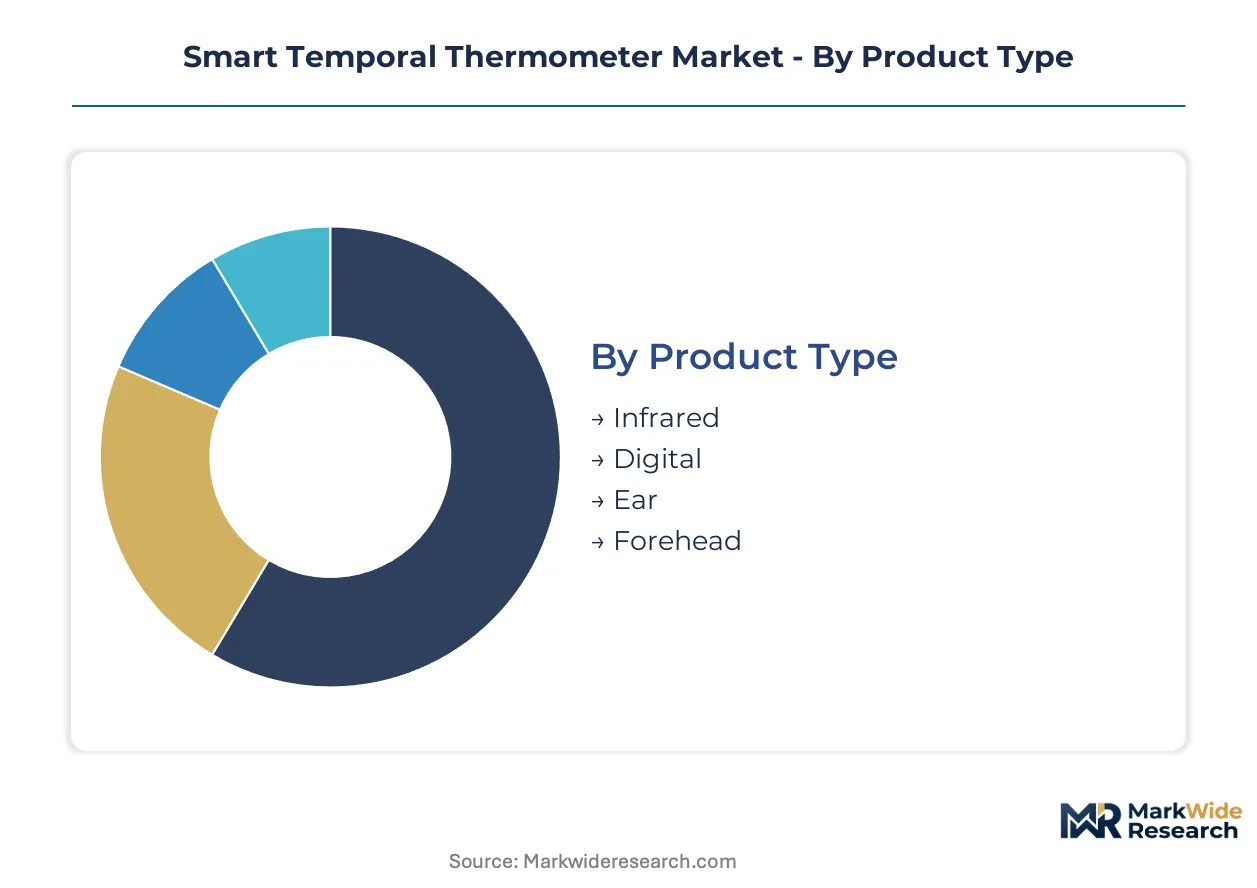
Segmentation in the smart temporal thermometer market reveals how regulatory pathways, procurement hierarchies, and reimbursement structures concentrate commercial value across distinct product configurations and customer access points.
Product Type:
Margins pool heavily in clinical-grade infrared devices where FDA 510(k) clearance and ISO 13485 certification create defensible pricing power against commodity alternatives.
- Infrared:Thermopile sensors with arterial heat balance algorithms deliver ±0.2°C accuracy for hospital triage. German hospital procurement teams specify infrared for neonatal units where non-invasive speed matters. Supply bottlenecks at Japanese and German sensor foundries constrain volume expansion.
- Digital:Liquid crystal or thermistor-based contact devices dominate pharmacy retail in price-sensitive Asian consumer channels. Taiwan contract manufacturers drive cost compression through single-chip ASIC integration.
- Ear:Tympanic membrane infrared scanning captures core temperature faster than forehead methods. Pediatric clinics in Japan prefer ear configurations for infant screening protocols.
- Forehead:Superficial temporal artery scanning enables wearable form factors. Taiwanese OEMs miniaturize these into earbud-style monitors for continuous fever tracking.
Infrared holds installed capacity. Forehead is rotating up the share rankings.
End User:
Volume concentrates in home settings where pharmacy subscription models and telehealth bundling displace episodic hardware purchases with recurring service revenue.
- Home Users:Parents in Germany prioritize connected devices with smartphone integration for infant fever monitoring. Walgreens and CVS Health bundle these with telehealth access in US metropolitan markets.
- Hospitals:Infection control protocols mandate non-contact infrared for emergency department triage. Tokyo hospital procurement now requires PMDA cybersecurity certification as vendor qualification gate.
- Clinics:Outpatient facilities balance accuracy requirements against capital constraints. European retail pharmacy diagnostic counters increasingly substitute for clinic-based temperature screening.
- Laboratories:Validation-grade thermal references support device calibration workflows. Metrology demand ties to regulatory audit cycles rather than patient volume.
Hospitals anchor premium pricing. Home users are expanding most quickly.
Distribution Channel:
Channel economics diverge sharply between institutional procurement with multi-year service contracts and consumer-direct models with thin hardware margins offset by data monetization.
- Online:Amazon and direct-to-consumer brands capture replacement demand through algorithmic targeting of new parents. Same-day delivery infrastructure supports urgent fever monitoring needs in dense urban markets.
- Retail:Big-box electronics chains move economy-tier digital devices. Price transparency compresses margins compared to pharmacy or hospital channels.
- Distributors:Medical device distributors manage FDA 510(k) documentation and hospital vendor credentialing. Concentrated distributor power in North America limits manufacturer pricing autonomy.
- Pharmacies:European chains integrate diagnostic service counters with connected thermometer placement. Subscription models here concentrate fastest where reimbursement codes validate remote monitoring.
Distributors control institutional access. Pharmacies are gaining share fastest.
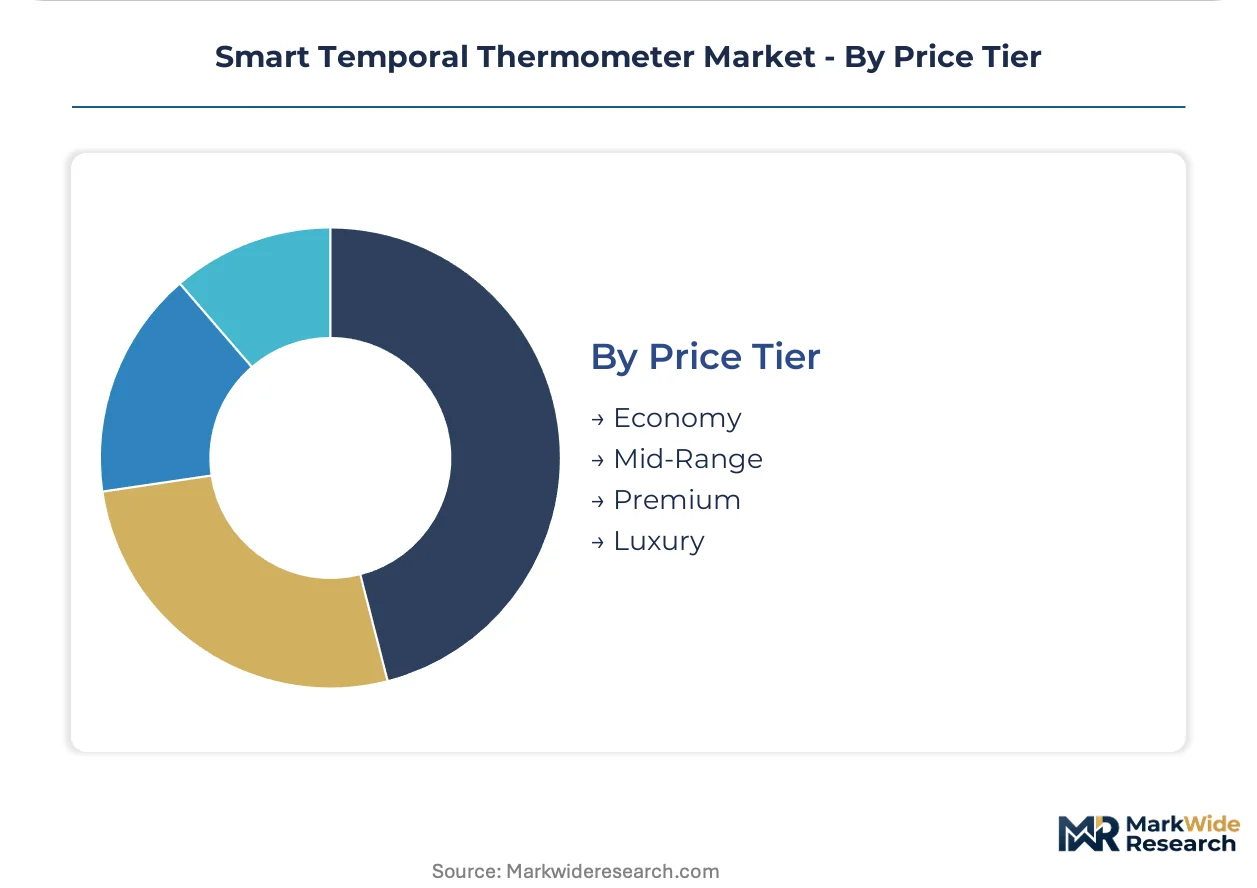
Price Tier:
Certification grade and connectivity features stratify pricing more than raw sensor cost, with clinical-grade infrared commanding 4-5x multiples over consumer digital alternatives.
- Economy:Basic digital contact thermometers target price-sensitive Asian consumer markets. Taiwan manufacturing scale enables sub-$10 retail pricing.
- Mid-Range:Connected forehead scanners with Bluetooth smartphone pairing. German parents in pediatric home care segments drive replacement cycles here.
- Premium:Clinical-grade infrared with FDA 510(k) clearance and ambient temperature compensation. Reimbursement validation in North American and European settings sustains device cost recovery.
- Luxury:Designer form factors with precious metal finishes and concierge health coaching subscriptions. Limited to gift markets and ultra-high-net-worth wellness programs.
Premium captures concentrated margin. Mid-range is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German parents purchasing pediatric home care devices and Japanese elderly patients in aging-in-place programs concentrate buyer archetypes in distinct regulatory environments. Hospital procurement teams in Tokyo and Berlin now require cybersecurity certification as a vendor qualification gate. Pharmacy subscription models in US metropolitan markets displace episodic hardware purchases with bundled telehealth access.
United States
Walgreens and CVS Health bundle connected thermometers with telehealth access in dense urban markets. FDA 510(k) premarket notification governs clinical claims for infrared devices targeting hospital triage workflows. Boston-area hospital systems require HL7 FHIR connectivity for new vendor qualification, forcing firmware redevelopment cycles.
Germany
Parents prioritize non-invasive fever monitoring for infants, creating sustained replacement demand for smartphone-integrated scanners. EU Medical Device Regulation reshapes conformity assessment pathways for Class IIa devices with expanded clinical evidence requirements. Precision sensor foundries in Baden-Württemberg control critical thermopile detector output, exposing downstream assemblers to allocation risk.
Japan
Elderly patients managing cardiovascular conditions embed temporal scanning into chronic care protocols through remote patient monitoring programs. METI and PMDA coordinate revised technical standards mandating encryption protocols for cloud-connected home medical devices. Tokyo hospital procurement teams now require PMDA cybersecurity certification as a gate criterion for new vendor onboarding.
China
Taiwan contract manufacturers drive cost compression through single-chip ASIC integration for economy-tier digital devices. NMPA medical device registration requirements govern market access for clinical-grade infrared products. Shenzhen and Dongguan electronics clusters miniaturize thermopile arrays into earbud-form-factor wearable fever monitors.
United Kingdom
Retail pharmacy diagnostic service counters increasingly substitute for clinic-based temperature screening in outpatient settings. MHRA post-Brexit regulatory framework maintains alignment with EU MDR technical standards for device conformity. London and Southeast England concentrate telehealth infrastructure supporting urgent fever monitoring delivery.
Smart Temporal Thermometer Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates with validated quality management systems. Market structure concentrates around three tiers: clinical-grade specialists with proprietary sensor algorithms, connected health platforms integrating temporal data into broader ecosystems, and Asian contract manufacturers driving cost compression through scale. Strategic archetypes include arterial heat balance technology holders, MEMS integration specialists, and pharmacy channel distributors. Dominant competitive moves center on ISO 13485 certification maintenance and software-as-a-medical-device reclassification positioning.
Within the clinical-grade specialist tier, Exergen Corporation and Welch Allyn exemplify proprietary technology anchoring. Koninklijke Philips N.V. occupies a position representing connected health ecosystem integration. OMRON Corporation and Terumo Corporation sit within the Asian manufacturing scale archetype. These named entities collectively illustrate how regulatory compliance infrastructure and sensor supply chain control separate sustainable positioning from commodity exposure.
| Leading Market Players |
|---|
| Exergen Corporation |
| 3M Company |
| Welch Allyn |
| Koninklijke Philips N.V. |
| Medtronic |
| Terumo Corporation |
| OMRON Corporation |
| Microlife Corporation |
| Briggs Healthcare |
| Others |
Pricing and Supply Chain Analysis
Thermopile sensor miniaturization replacing discrete infrared detector assemblies is redrawing procurement geography toward Taiwan single-chip foundries while compressing mid-range device pricing toward economy-tier levels.
Pricing Analysis
Cost-plus contracts with thermopile wafer indexation dominate procurement between German sensor foundries and downstream device assemblers. Three-tier pricing structure across premium clinical-grade, mid-range connected, and economy digital tiers stratifies by FDA 510(k) certification status and Bluetooth connectivity features. Pricing pressure stems from Taiwan contract manufacturers achieving single-chip ASIC integration at scale. Home users in Asian consumer channels exhibit highest price sensitivity, while North American hospital systems accepting reimbursement-validated procurement show lowest.
Supply Chain Analysis
Inventory cycles for thermopile arrays stretch lead times when German and Japanese precision sensor foundries allocate capacity to automotive lidar customers. Component supply concentrates in Taiwan for ASIC integration, Germany for infrared metrology, and Japan for MEMS environmental sensors. Raw material dependencies span indium antimonide substrates, thermoelectric materials, and medical-grade ABS housings. Single-source vulnerability at Baden-Württemberg thermopile foundries exposes assemblers to allocation risk. Distribution runs through medical device distributors managing FDA 510(k) documentation for hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmacy chains and hospital GPOs, fragmenting pricing autonomy for device manufacturers as procurement volume concentrates among fewer gatekeepers.
For Market Incumbents: Compound defensive positioning through backward integration into thermopile sensor production and accelerated ISO 13485 certification maintenance. Threat from contactless ultrasound alternatives in critical care settings demands proprietary algorithm investment. Channel control via exclusive distributor relationships anchors margin defense. For New Entrants and Emerging Players: Differentiate on software-as-a-medical-device compliance readiness ahead of FDA draft guidance finalization. White-space targets include pharmacy subscription service partnerships in US metropolitan markets and PMDA cybersecurity-certified devices for Tokyo hospital procurement. Go-to-market through telehealth platform bundling bypasses established distributor gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed connected health platforms seeking clinical-grade device anchors for reimbursement validation. Long-term viability hinges on regulatory compliance infrastructure rather than hardware differentiation alone. Watch FDA software-as-a-medical-device reclassification timing as portfolio inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks clinical-grade pricing tiers and hospital procurement eligibility. |
| ISO 13485 Certification Investment | Creates entry barriers favoring established quality management systems. |
| Single-Chip ASIC Integration | Enables Taiwan contract manufacturers to compress economy-tier pricing. |
| Pharmacy Channel Partnership | Shifts volume from hospital procurement to subscription-based recurring revenue. |
| Software Companion Development | Positions vendors for FDA software-as-a-medical-device reclassification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with device manufacturers, hospital procurement managers, pharmacy chain category buyers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, PMDA registration databases, hospital GPO contract archives, and EU MDR conformity assessment records. Bottom-up triangulation across thermopile sensor production volumes and top-down validation through connected health device shipment estimates anchored market sizing.
Across the projection horizon, the analytical framework modeled demand by product type, end user segment, distribution channel, and price tier, with regional regulatory cluster as an overlay dimension. CAGRs derived from segment-level growth rate convergence analysis incorporating pediatric home care replacement cycles, aging-in-place program expansion, and pharmacy digitization trajectories. Forecast inputs included thermopile foundry capacity utilization and telehealth bundling adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway clarity, stable thermopile sensor supply allocation, or unchanged software-as-a-medical-device classification would require recalibration. Forecasts reflect documented assumptions regarding reimbursement validation continuity and cybersecurity certification harmonization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market