
 Global Battery Free RFID Sensor Market | 2026-2036
Global Battery Free RFID Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Free RFID Sensor Market Intelligence
The divergence in R&D scale between fabless semiconductor designers and specialized sensor system integrators is unwinding the market's traditional structure. Large players like Texas Instruments Incorporated leverage vast semiconductor manufacturing capabilities. Infineon Technologies AG competes on the strength of its broad portfolio of ICs for RFID. In contrast, specialists such as Phase IV Engineering Inc. differentiate through custom-engineered sensor solutions for niche industrial applications.
A battery-free RFID sensor is a passive wireless device that harvests energy from a reader's radio frequency interrogation signal. This captured energy powers an integrated sensor to measure a physical or environmental parameter and then communicates the data via backscatter modulation. Passive RFID Tags continue to dominate the product landscape due to their low cost and simplicity. Within applications, supply chain management and asset tracking represent the largest segments, while environmental monitoring shows significant growth potential.
Market access is governed by radio frequency spectrum regulations, including those set by the US Federal Communications Commission (FCC) and China's MIIT. Conformance with standards like the European Union's CE marking for electronic devices is also mandatory for market entry. Future investment decisions will hinge on balancing the cost-effectiveness of standardized sensors against the performance advantages of custom-engineered solutions for specific industrial challenges.
Market Dynamics
The fundamental market dynamic is the rapid commoditization of core UHF RFID technology, which is shifting the basis of competition from hardware performance to the value derived from sensor data. This pressure forces vendors to either achieve massive scale in standardized tag production or develop deep expertise in custom sensor integration for specific industrial verticals.
Growth Catalysts
- Food Safety Mandates:Regulations such as the US FDA's Food Safety Modernization Act (FSMA) Rule 204 create demand for reliable, low-cost temperature and humidity tracking throughout the cold chain, a key application for battery-free sensors.
- UHF Technology Maturation:Advances in Ultra High Frequency (UHF) backscatter technology enable longer read ranges and more reliable performance in challenging environments, expanding the addressable market beyond simple portal-based tracking to large-scale area monitoring.
- Logistics Modernization in China:The country's massive investment in automating its logistics and manufacturing hubs creates sustained demand for asset tracking solutions, with battery-free RFID sensors being a preferred technology for pallet and container-level monitoring.
Market Restraints
- Signal Interference and Attenuation:The performance of passive RFID systems degrades significantly in environments with high concentrations of metal and liquids, limiting reliable use in applications like beverage logistics or tracking metal parts without specialized tag designs.
- Fragmented Spectrum Allocation:Divergent radio frequency regulations set by bodies like the US FCC, China's MIIT, and European authorities create complexity for manufacturers, requiring different hardware SKUs for different regions and hindering global product rollouts.
- High Initial System Cost:While individual tags are inexpensive, the total cost of ownership, including readers, antennas, software, and system integration services, remains a significant barrier for many potential small and medium-sized enterprise adopters.
Strategic Opportunities
- Precision Agriculture:Underpenetrated applications in agriculture for monitoring soil moisture, temperature, and nutrient levels offer a significant growth vector, enabling data-driven farming practices with low-maintenance, deploy-and-forget sensors.
- Sensor Fusion with AI:Integrating passive sensor data streams with machine learning algorithms creates opportunities for predictive maintenance services in industrial machinery and structural health monitoring for infrastructure like bridges and buildings.
- Healthcare Asset Management:The medical field presents a high-value opportunity for tracking surgical instruments through sterilization cycles, monitoring temperature-sensitive pharmaceuticals, and managing high-value mobile medical equipment within hospital environments.
Industry Challenges
- Systems Integration Complexity:A primary operational hurdle is integrating the data streams from RFID sensor systems into legacy enterprise platforms like ERP and WMS, which often requires significant custom software development and middleware.
- Interoperability Gaps:Despite the existence of standards like EPC Gen2, ensuring seamless interoperability between different vendors' tags, readers, and software remains a persistent challenge, particularly for specialized sensor data protocols.
- RF Engineering Talent Scarcity:The industry faces a shortage of engineers who possess a combination of radio frequency design expertise, sensor physics knowledge, and application-specific software development skills, slowing down custom solution development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Free RFID Sensor Market |
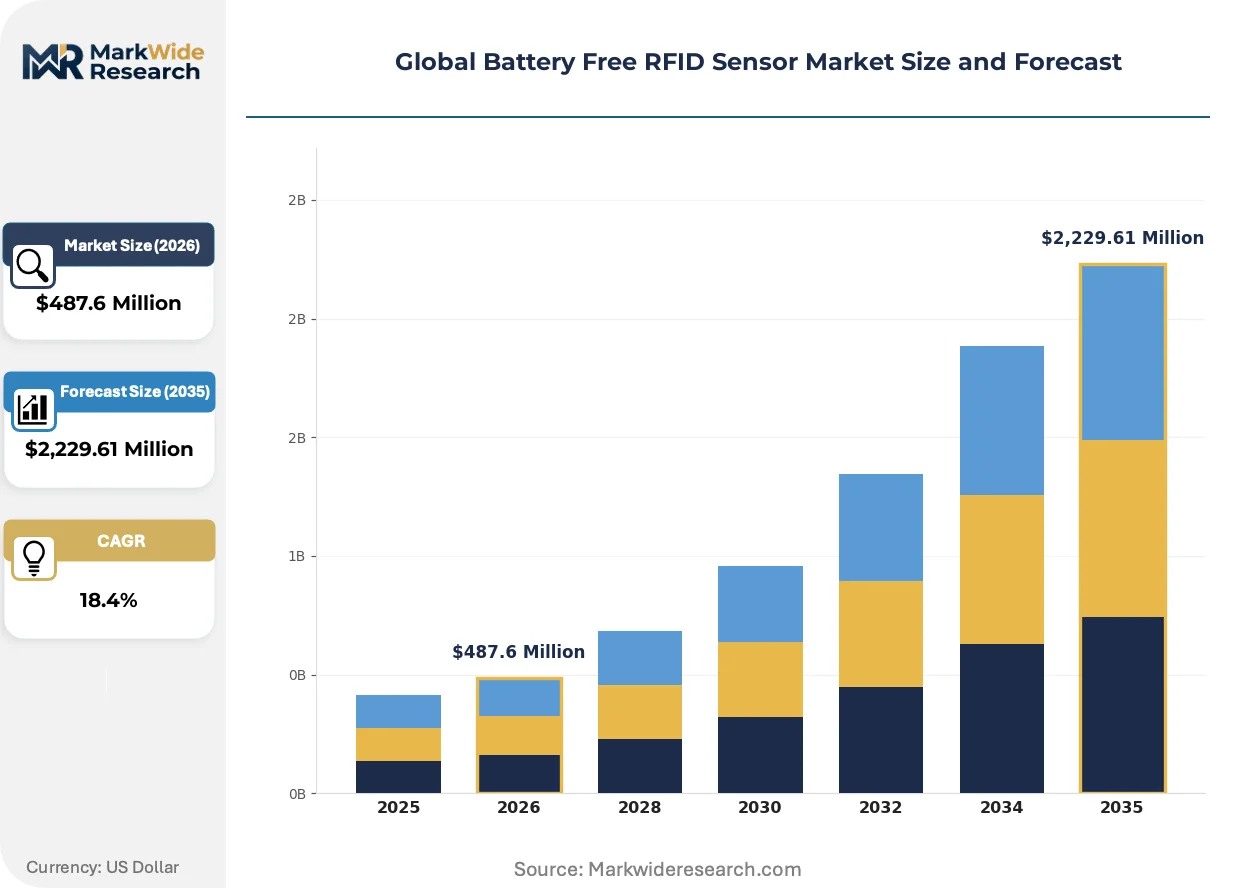
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive RFID Tags, Semi-Passive Sensors, Chipless RFID Sensors, Printable Sensors, Paper-Based Sensors Technology: Ultra High Frequency, Near Field Communication, Microwave Frequency, Magnetic Coupling, Backscatter Modulation Application: Supply Chain Management, Asset Tracking, Environmental Monitoring, Food Safety, Consumer Electronics End User: Manufacturing Plants, Logistics Providers, Agricultural Monitoring Services, Retail Chains, Smart Building Operators |
| Companies Covered | Powercast Corporation, Axzon, Farsens, Infineon Technologies AG, ON Semiconductor, Texas Instruments Incorporated, Phase IV Engineering Inc., Inductosense, Semiconductor Components Industries, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Free RFID Sensor Market Strategic Shifts & Innovations
The market is moving beyond simple identification toward dynamic, multi-parameter sensing. This evolution is driven by advancements in energy harvesting efficiency and chip-level miniaturization, transforming passive tags from static labels into active sources of environmental and operational intelligence.
On-chip integration of multiple sensing modalities is a key product evolution. These advanced passive tags can measure parameters like temperature, humidity, pressure, or strain on a single silicon die powered solely by the reader's signal. Pharmaceutical and cold chain logistics providers are adopting these for greater visibility, as the ability to capture multiple environmental parameters with a single tag read is displacing the reliance on bulkier, single-function data loggers for shipment monitoring.
Regulatory frameworks focused on sustainability are creating new compliance-driven demand. The European Union’s Ecodesign for Sustainable Products Regulation (ESPR) is mandating Digital Product Passports for certain product categories, requiring lifecycle data to be accessible. This forces manufacturers in sectors like electronics and apparel to embed persistent, low-cost identifiers. Consequently, battery-free RFID is being evaluated as a foundational technology to meet these traceability and circular economy requirements.
A notable shift in consumption patterns involves the move away from one-time hardware purchases toward data-centric service models. End-users in industrial and retail settings are increasingly adopting Sensor-Data-as-a-Service (SDaaS) subscriptions. This model bundles the sensors, readers, and analytics platform into an operational expense, removing the barrier of high upfront capital investment. This trend is most prominent in large-scale inventory management where clients pay per data point or tracked asset.
Global Battery Free RFID Sensor Market Segmentation
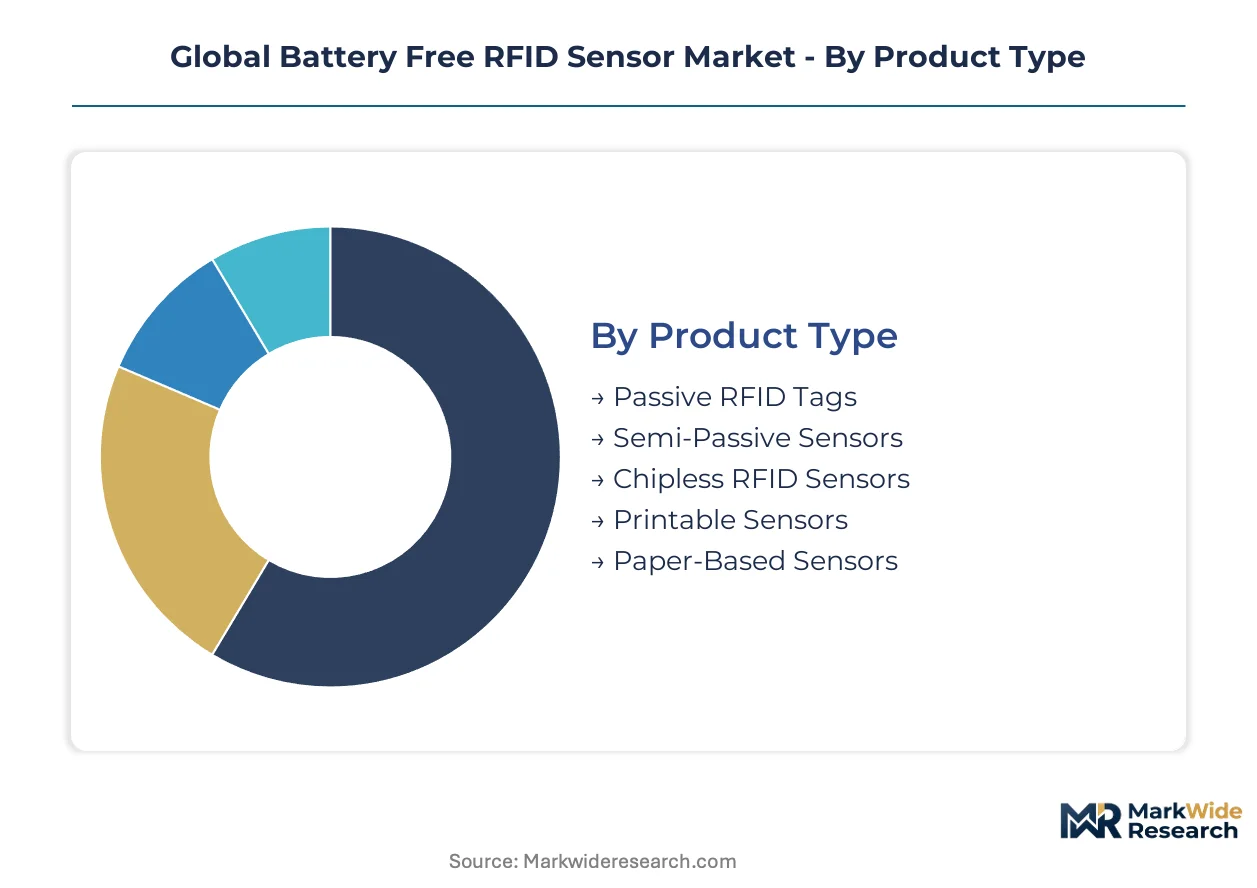
The segmentation of the Global Battery Free RFID Sensor Market reveals how diverse end-user requirements and technological advancements are shaping product development and adoption. Understanding these distinct segments is crucial for identifying areas of competitive intensity and emerging growth opportunities.
Product Type:
The battery-free RFID sensor market faces ongoing substitution pressure from traditional wired sensors and active RFID solutions across various product types.
- Passive RFID Tags:These devices harvest energy from the reader's signal to power an integrated chip for identification and basic sensing. Their low cost and simplicity make them indispensable for high-volume inventory management in retail logistics.
- Semi-Passive Sensors:Incorporating a small battery for sensor operation but relying on the reader for communication, these sensors offer enhanced functionality and data logging capabilities. Pharmaceutical cold chain monitoring frequently employs them for precise temperature tracking.
- Chipless RFID Sensors:These tags utilize material properties to reflect unique radio frequency signatures without needing an integrated circuit. They find use in anti-counterfeiting applications and basic product authentication.
- Printable Sensors:Manufactured using conductive inks on flexible substrates, these cost-effective sensors facilitate large-scale integration into packaging and smart labels. Food safety applications benefit from their disposable nature.
- Paper-Based Sensors:Constructed from eco-friendly paper materials, these sensors provide a sustainable and low-cost solution for single-use environmental monitoring. They are gaining traction in smart packaging for perishable goods.
Passive RFID Tags retain volume leadership; Semi-Passive Sensors hold the steepest expansion curve.
Technology:
Technological differentiation within battery-free RFID sensors centers on optimizing read range, data transfer rates, and operational reliability in diverse environments.
- Ultra High Frequency:This technology operates in the 860-960 MHz range, enabling longer read distances and faster data acquisition for large-scale asset tracking. Logistics providers in China are increasingly adopting UHF for pallet and container monitoring.
- Near Field Communication:NFC operates at 13.56 MHz over short distances, facilitating secure data exchange and direct interaction with consumer devices. Healthcare asset management utilizes NFC for tracking surgical instruments and medical equipment.
- Microwave Frequency:Operating at higher frequencies (e.g., 2.45 GHz), microwave RFID offers enhanced performance in specific industrial environments. It provides robust data transmission for specialized manufacturing processes.
- Magnetic Coupling:This technology uses magnetic fields for short-range communication, often suitable for applications involving metal or liquids. It supports identification in challenging industrial settings.
- Backscatter Modulation:A fundamental principle where the tag reflects and modulates the reader's signal to transmit data, it underpins most passive RFID systems. This technique allows for energy-efficient data communication.
Ultra High Frequency technology maintains dominance in supply chain operations, while Near Field Communication is expanding its reach in consumer-facing interactions.
Application:
End-user adoption patterns for battery-free RFID sensors are largely dictated by the immediate operational efficiencies and compliance requirements each application offers.
- Supply Chain Management:This application involves tracking goods from origin to destination, optimizing inventory, and reducing losses. Large manufacturing centers leverage battery-free sensors for real-time visibility across their vast networks.
- Asset Tracking:Focusing on monitoring the location and status of high-value equipment, tools, or vehicles within a defined area. Major logistics hubs in China rely on these sensors for efficient management of their mobile assets.
- Environmental Monitoring:This segment involves sensing parameters like temperature, humidity, and pressure in sensitive environments. Precision agriculture benefits from low-maintenance sensors for soil condition assessment.
- Food Safety:Critical for ensuring product integrity, this application uses sensors to monitor conditions throughout the cold chain. US FDA mandates drive demand for reliable temperature and humidity tracking.
- Consumer Electronics:Integration into electronic devices for authentication, pairing, or personalized user experiences represents a developing application area. This segment provides enhanced device interaction and security features.
Supply Chain Management continues to be driven by efficiency mandates, with Environmental Monitoring showing considerable potential due to sustainability initiatives.
End User:
Investment priorities among end-users of battery-free RFID sensors are shifting towards solutions that offer both operational cost savings and enhanced data-driven decision-making capabilities.
- Manufacturing Plants:These facilities deploy battery-free sensors for work-in-progress tracking, equipment monitoring, and inventory management on the production floor. Automation initiatives in China's manufacturing sector fuel this demand.
- Logistics Providers:Companies specializing in transportation, warehousing, and distribution utilize these sensors for pallet tracking, container identification, and shipment visibility. Modernization efforts in global logistics networks prioritize passive RFID integration.
- Agricultural Monitoring Services:Providers in this sector use battery-free sensors for monitoring soil conditions and crop health. These services enable data-driven farming practices and resource optimization.
- Retail Chains:Retailers implement RFID sensors for inventory accuracy, loss prevention, and enhancing customer experience. This application supports efficient stock management and faster checkout processes.
- Smart Building Operators:These operators integrate sensors for environmental control, occupancy monitoring, and asset location within commercial and residential structures. Smart building solutions benefit from low-power, maintenance-free sensing.
Manufacturing Plants prioritize efficiency gains, while Agricultural Monitoring Services are increasingly recognized for long-term value creation through data insights.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for battery-free RFID sensors varies significantly across global geographies, with some regions prioritizing cost-effective asset tracking while others focus on high-value environmental monitoring applications. Demand patterns reflect diverse regulatory environments and industrial modernization priorities, influencing technology adoption rates and application focus.
China
China's massive logistics modernization initiatives drive substantial demand for UHF battery-free sensors in supply chain management and asset tracking. The Ministry of Industry and Information Technology (MIIT) regulations support the widespread deployment of RFID technologies in manufacturing and logistics. Major logistics hubs in cities like Shenzhen and Shanghai continue to integrate passive RFID for efficient container and pallet identification.
United States
The United States market is largely influenced by food safety mandates and healthcare asset management requirements for battery-free RFID sensors. US FDA's Food Safety Modernization Act (FSMA) Rule 204 creates specific demand for temperature and humidity tracking in the cold chain. Technology companies and logistics providers in Silicon Valley and along the East Coast are developing advanced sensor integration platforms.
Germany
Germany exhibits strong adoption of battery-free RFID sensors within its advanced manufacturing sectors for work-in-progress tracking and industrial automation. European Union's CE marking for electronic devices ensures product quality and interoperability across member states. The automotive and machinery manufacturing clusters in Bavaria and Baden-Württemberg actively implement these sensors for process optimization.
Japan
Japanese industries utilize battery-free RFID sensors for precision agriculture and high-value asset management in its sophisticated electronics and automotive sectors. METI (Ministry of Economy, Trade and Industry) promotes smart factory initiatives that incorporate advanced sensing technologies. Research and development centers in Tokyo and Osaka are pioneering miniaturized, multi-parameter passive sensors.
India
India's growing agricultural sector and expanding logistics infrastructure create opportunities for low-cost battery-free sensors, particularly for environmental monitoring and supply chain visibility. The Bureau of Indian Standards (BIS) establishes guidelines for electronic goods, influencing RFID product development. Agricultural technology parks in states like Maharashtra and Karnataka are experimenting with soil moisture and temperature sensors.
Global Battery Free RFID Sensor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for battery-free RFID sensors. This structure reflects a market where foundational semiconductor capabilities underpin a diverse ecosystem of application-specific solutions. Two predominant strategic archetypes emerge: large-scale semiconductor manufacturers and niche sensor system integrators. Companies frequently engage in strategic partnerships to expand their application reach and technology portfolios.
Large semiconductor manufacturers, such as Texas Instruments Incorporated and Infineon Technologies AG, anchor the market with their extensive R&D resources and broad portfolio of integrated circuits for RFID. These firms leverage their silicon expertise to produce high-performance, energy-efficient chips. In contrast, specialists like Phase IV Engineering Inc. exemplify companies that differentiate through custom-engineered sensor solutions for niche industrial applications, often focusing on unique material properties or challenging environmental conditions. These specialized players often target specific vertical markets with tailored offerings.
| Leading Market Players |
|---|
| Powercast Corporation |
| Axzon |
| Farsens |
| Infineon Technologies AG |
| ON Semiconductor |
| Texas Instruments Incorporated |
| Phase IV Engineering Inc. |
| Inductosense |
| Semiconductor Components Industries, LLC |
| Others |
Cost & Logistics Intelligence
Substitution pressure from battery-free RFID sensors displacing traditional wired solutions simultaneously reshapes global manufacturing geography and pricing economics. This shift incentivizes localized production of specialized components while driving down the cost of standardized tags.
Pricing Analysis
Sensor-Data-as-a-Service (SDaaS) subscriptions drive lifetime value by bundling hardware, software, and analytics into operational expenses. Pricing stratifies across performance tiers based on customization level for niche industrial applications and certification level, such as CE marking. Pricing pressure stems from the rapid commoditization of core UHF RFID technology. Small and medium-sized enterprises are most price-sensitive due constrained capital; large enterprises prioritize performance and integration capabilities.
Supply Chain Analysis
China anchors global manufacturing of integrated circuits and conductive inks for printable sensors, supporting its massive logistics and manufacturing sectors. Key raw material dependencies include silicon wafers for RFID chips and specialized polymers for flexible substrates. Fragmented radio frequency spectrum allocation creates a structural risk, requiring different hardware SKUs for global product rollouts. Distribution runs through direct sales channels to large industrial end-users and specialized system integrators for complex, bespoke projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Battery Free RFID Sensor Market represents a significant service-attach opportunity. Sensor-Data-as-a-Service (SDaaS) subscriptions, bundling hardware and analytics, are expanding faster than standalone hardware sales, generating predictable recurring revenue streams.
For Market Incumbents: Consolidate market position by acquiring niche sensor system integrators that possess deep vertical expertise in areas like precision agriculture or healthcare asset management. This strategy mitigates the threat of commoditization in core UHF RFID technology. Invest in advanced RF engineering talent and R&D focused on energy harvesting efficiency to maintain a performance edge against emerging entrants.
For New Entrants and Emerging Players: Certification fast-tracks, such as accelerated CE marking for specialized industrial sensors, enable quicker market entry into regulated European sectors. Target underpenetrated applications like precision agriculture for soil monitoring or healthcare asset management for surgical instruments. Partner with existing enterprise resource planning (ERP) and warehouse management system (WMS) providers to offer seamless integration as a go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialized sensor system integrators that have proven solutions in specific industrial verticals. Long-term viability over the next decade is supported by sustainability regulations like the EU’s Digital Product Passports driving traceability demand. The signal to watch is increased M&A activity among large semiconductor firms acquiring software and analytics capabilities to bolster their SDaaS offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Niche Integrators | Expands application reach into specialized industrial verticals for semiconductor firms. |
| Investment in RF Engineering R&D | Enhances sensor performance and energy harvesting efficiency for next-generation products. |
| Strategic Partnership with ERP/WMS Vendors | Facilitates seamless data integration for end-users in supply chain management. |
| Development of Multi-Parameter Sensors | Addresses demand for comprehensive environmental monitoring in cold chain logistics. |
| Geographic Expansion into Emerging Logistics Hubs | Captures sustained demand for asset tracking in rapidly modernizing regions like China. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, company financial filings, and industry association reports. Primary interviews engaged logistics managers, plant engineers, supply chain directors, and regulatory compliance officers across various regions. This approach employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing consistency.
Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory frameworks over the projection horizon. Compound annual growth rates were derived from historical growth patterns and projected technology adoption rates. Key forecast inputs included investment in logistics modernization initiatives and evolving food safety mandates.
Decision-makers should treat outputs as directional under current technological adoption rates and regulatory stability; material deviation would warrant model refresh. Forecasts reflect base assumptions regarding market dynamics and competitive intensity. Unforeseen shifts in radio frequency spectrum allocation or disruptive advancements in competing sensor technologies represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
China Sensors Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
United States Scintillator Market