
 Silicon Photomultiplier (Sipm) Market | 2026-2036
Silicon Photomultiplier (Sipm) Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Photomultiplier (Sipm) Market Intelligence
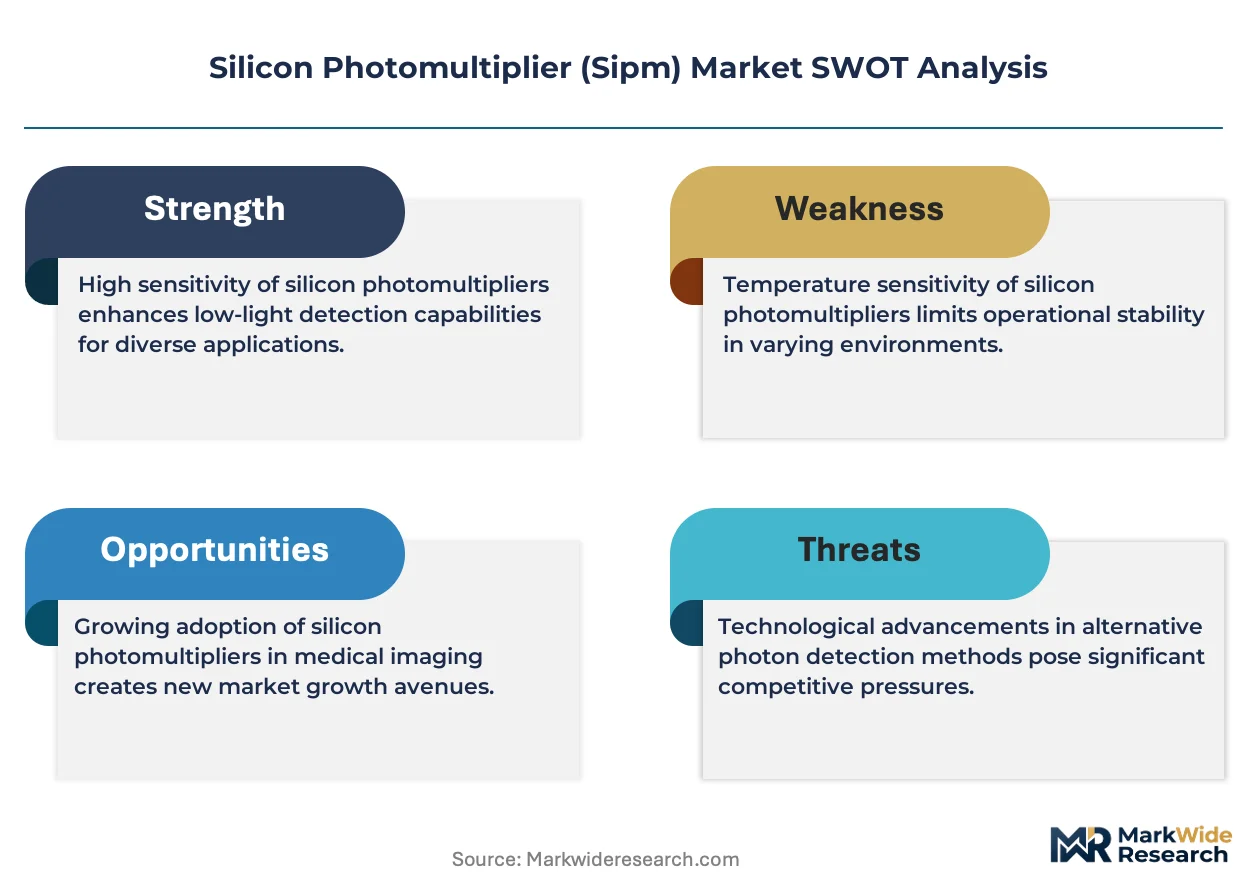
The gap between premium single-photon sensors and commodity avalanche photodiodes is expanding as healthcare imaging demands sub-nanosecond timing resolution that standard devices cannot deliver. Hamamatsu Photonics K.K. leverages its vertical integration across crystal growth to module assembly to sustain pricing power in nuclear medicine. onsemi competes through foundry-scale manufacturing of digital readout arrays, while KETEK GmbH specializes in custom multi-pixel sensors for particle physics detectors at CERN and DESY.
A silicon photomultiplier is a solid-state photodetector comprising an array of Geiger-mode avalanche photodiodes operating above breakdown voltage, capable of detecting single photons with timing resolution below 100 picoseconds and photon detection efficiency exceeding 50% at peak wavelengths. Its primary purpose spans low-light signal detection in medical imaging, high-energy physics calorimetry, and radiation monitoring where photomultiplier tubes prove too bulky or magnetically sensitive. Single-photon sensors command the steepest premium due to integration complexity, while digital readout technology captures the fastest growth trajectory as system architects abandon analog front-ends for FPGA-based timestamping. Multi-pixel sensors anchor margin pools in radiation detection, where military and environmental agencies specify hardened configurations resistant to neutron damage.
FDA 510(k) pathways and EU MDR conformity assessment shape product development cycles, with EMA notified bodies demanding clinical evidence for SiPM-based diagnostic devices that earlier CE-marking regimes accepted on bench testing alone. Japan's PMDA aligns with ICH Q5D guidelines for biopharmaceutical manufacturing traceability, extending to positron emission tomography quality control protocols. Stakeholders must monitor how REACH substance restrictions on lead-bearing solders intersect with RoHS exemptions for high-reliability aerospace and defense applications, as these material constraints ripple through packaging choices across the supply base.
Market Dynamics
The transition from analog to digital readout architectures is compressing development cycles and forcing module suppliers to absorb FPGA programming costs that previously sat with system integrators.
Growth Catalysts
- EU MDR conformity assessment:Tightened performance verification standards for PET-CT hybrid scanners are accelerating replacement demand across European medical facilities.
- Sub-nanosecond timing resolution:Healthcare imaging protocols now mandate single-photon precision that legacy avalanche photodiodes cannot deliver, widening the performance gap.
- Germany's precision instrumentation cluster:Concentrated R&D activity around Munich and Jena is generating spillover demand for custom multi-pixel configurations.
Market Restraints
- Crystal growth supply concentration:Lutetium-based scintillator substrate production clusters in three Asian suppliers, exposing module assemblers to input volatility.
- REACH substance restrictions:Lead-bearing solder exemptions for aerospace applications are narrowing, forcing packaging redesigns before RoHS compliance deadlines.
- Photomultiplier tube residual demand:Magnetically shielded PMTs retain cost advantages in non-portable radiation monitoring installations above 400mm form factors.
Strategic Opportunities
- Environmental radiation networks:Hardened multi-pixel sensors for neutron-resistant military and environmental agency deployments command durable margin pools.
- Japan's PMDA alignment with ICH Q5D:Biopharmaceutical manufacturing traceability extensions to PET quality control protocols open service contract revenue.
- FPGA-based timestamping convergence:System architects abandoning analog front-ends create entry points for digital readout specialists without crystal growth capabilities.
Industry Challenges
- Geiger-mode APD fabrication talent:Cleanroom process engineers with breakdown voltage calibration expertise are concentrated at legacy CMOS foundries.
- FDA 510(k) clinical evidence requirements:SiPM-based diagnostic devices now require patient studies that earlier submissions satisfied with bench testing alone.
- Legacy analog integration:Hybrid scanner OEMs maintain proprietary front-end architectures that complicate third-party module certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Photomultiplier (Sipm) Market |
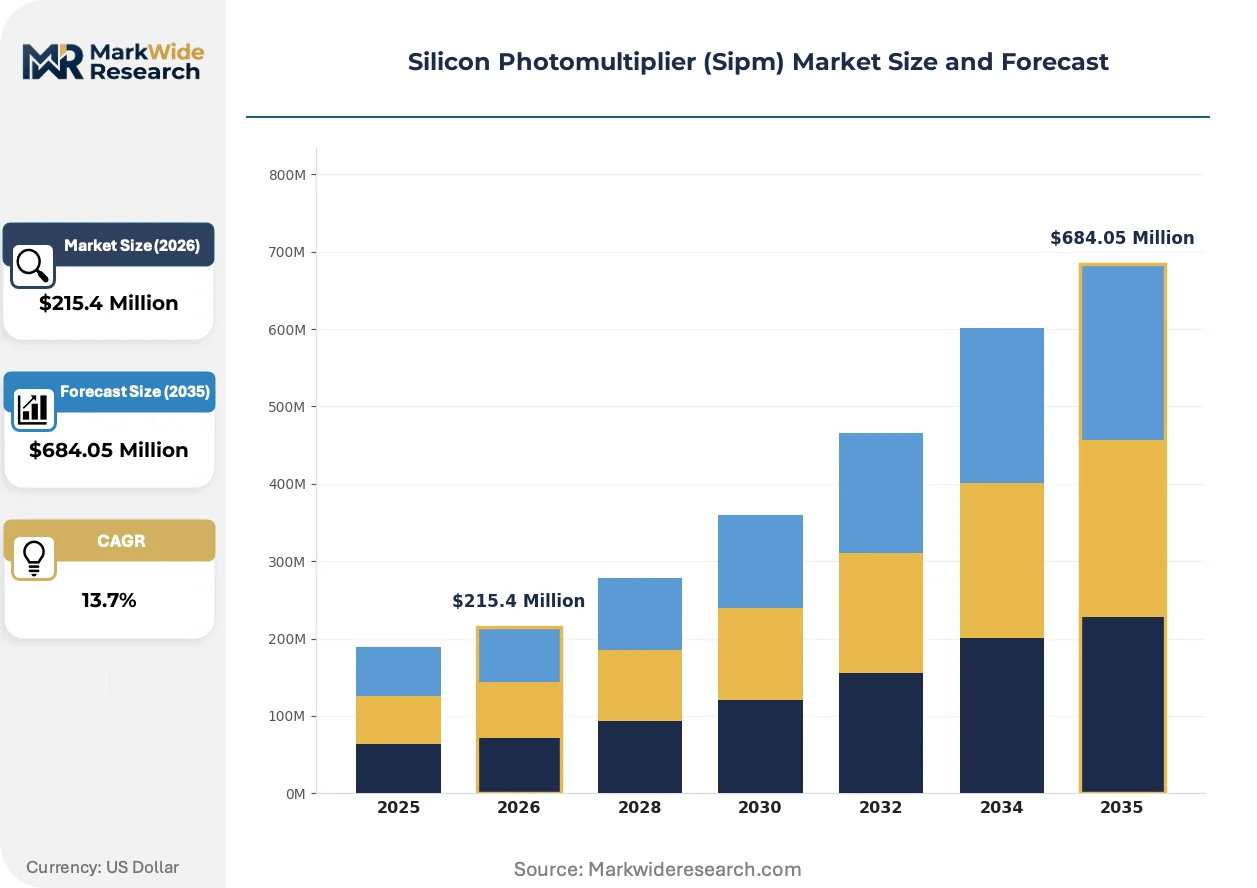
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $684.05 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avalanche Photodiodes, Photon Counting Modules, Single-Photon Sensors, Multi-Pixel Sensors Application: Healthcare Imaging, Particle Physics, Nuclear Medicine, Radiation Detection End User: Research Institutions, Medical Facilities, Industrial Laboratories, Educational Institutes Technology: Analog Readout, Digital Readout, Hybrid Systems, Array Configurations |
| Companies Covered | Hamamatsu Photonics K.K., onsemi, Broadcom Inc., Excelitas Technologies Corp., KETEK GmbH, First Sensor AG, AdvanSiD, Cremat Inc., Radiation Monitoring Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Photomultiplier (Sipm) Market Strategic Shifts & Innovations
Digital signal processing is collapsing the traditional boundary between photodetector and data acquisition hardware, redistributing value capture toward firmware-capable suppliers.
Digital SiPM arrays with integrated time-to-digital converters are overtaking analog-output predecessors in nuclear medicine installations. Siemens Healthineers and GE Healthcare have shifted procurement specifications to require on-chip timestamping for new PET-CT platforms. This compression is eliminating the historical tier of discrete amplifier board suppliers and concentrating margin in foundry-scale device manufacturers.
REACH substance restrictions on lead-bearing solders are intersecting with RoHS exemptions for high-reliability aerospace applications. Packaging engineers must now qualify alternative metallurgies for radiation-hardened multi-pixel sensors without sacrificing neutron damage resistance. European defense contractors are delaying procurement decisions until ECHA publishes clarified guidance on high-reliability exemptions.
Japanese academic medical centers are consolidating SiPM procurement through METI-funded imaging consortia that standardize performance benchmarks. University hospitals in Osaka and Tokyo now require PMDA-aligned traceability documentation that extends from crystal growth lots through module serial numbers. This behavioral shift is compressing vendor qualification timelines and favoring suppliers with captive scintillator production.
Silicon Photomultiplier (Sipm) Market Segmentation
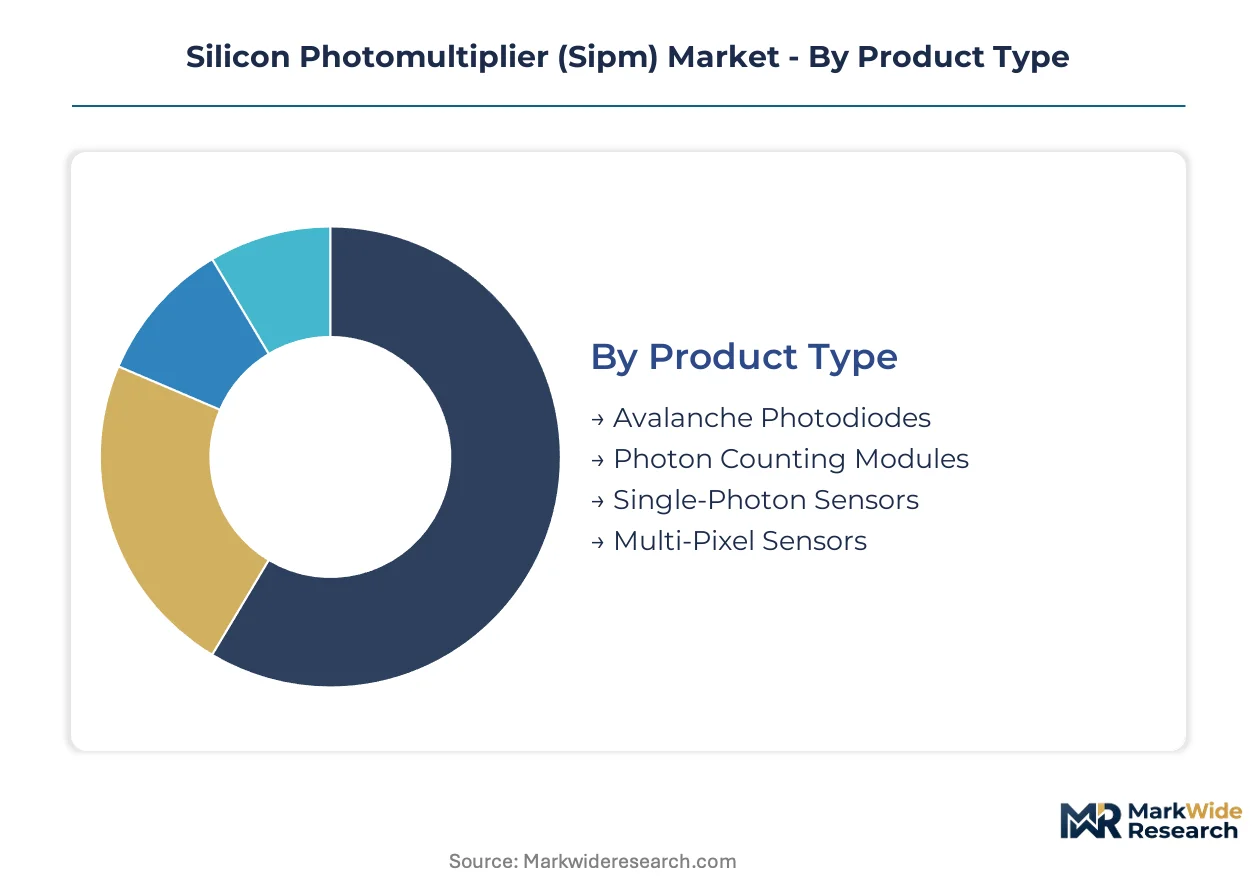
SiPM procurement patterns diverge sharply between standardized volume contracts for healthcare OEMs and bespoke configurations for particle physics installations. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economies dominate competitive positioning.
Product Type:
Standardized die formats serve radiation detection agencies through catalog distributors, while custom multi-pixel arrays require direct engineering engagement with CERN or DESY specification teams.
- Single-Photon Sensors:Geiger-mode APD arrays with sub-100 picosecond timing resolution and peak detection efficiency exceeding 50%. PET-CT hybrid scanner procurement in Germany's Munich-Jena corridor concentrates demand as EU MDR tightens performance verification standards.
- Multi-Pixel Sensors:Hardened configurations resistant to neutron damage, fabricated with custom metallization for military and environmental radiation networks. Margin durability exceeds commodity categories due to qualification barriers and lot-level traceability requirements.
- Avalanche Photodiodes:Linear-mode devices serving cost-sensitive applications where Geiger-mode sensitivity is unnecessary.
- Photon Counting Modules:Integrated detector-amplifier assemblies for research laboratories lacking in-house front-end design capability.
Most installed capacity flows through Single-Photon Sensors. Expansion is steepest in Multi-Pixel Sensors.
Application:
End-use economics range from reimbursement-governed healthcare procurement to grant-funded academic physics programs with multi-year capital cycles.
- Healthcare Imaging:Sub-nanosecond timing resolution mandates SiPM adoption in PET-CT platforms as legacy avalanche photodiodes fail clinical protocols. FDA 510(k) pathways and EU MDR conformity assessment now require patient studies rather than bench testing alone.
- Particle Physics:Calorimetry and time-of-flight detectors at CERN and DESY specify custom sensor geometries with decade-long procurement horizons. Funding volatility from national research councils creates lumpy demand patterns distinct from commercial healthcare.
- Nuclear Medicine:Radioisotope imaging and therapy monitoring applications requiring scintillator-SiPM coupling expertise.
- Radiation Detection:Environmental monitoring and security screening deployments with hardened operational specifications.
Revenue concentration sits with Healthcare Imaging. Particle Physics is climbing the fastest as next-generation collider projects advance procurement timelines.
End User:
Procurement sophistication varies from centralized university hospital consortia to fragmented industrial laboratory purchasing.
- Medical Facilities:Japanese academic medical centers consolidate procurement through METI-funded imaging consortia standardizing performance benchmarks. Osaka and Tokyo university hospitals now require PMDA-aligned traceability from crystal growth lots through module serial numbers.
- Research Institutions:CERN and DESY drive specification evolution for multi-pixel configurations with direct vendor engineering relationships. Grant funding cycles create predictable replacement demand distinct from commercial capital equipment.
- Industrial Laboratories:Quality control and materials analysis applications with moderate volume requirements.
- Educational Institutes:Teaching and basic research deployments prioritizing cost over performance margins.
Medical Facilities channel the dominant volume share. Research Institutions are gaining share fastest as particle physics capital programs accelerate.
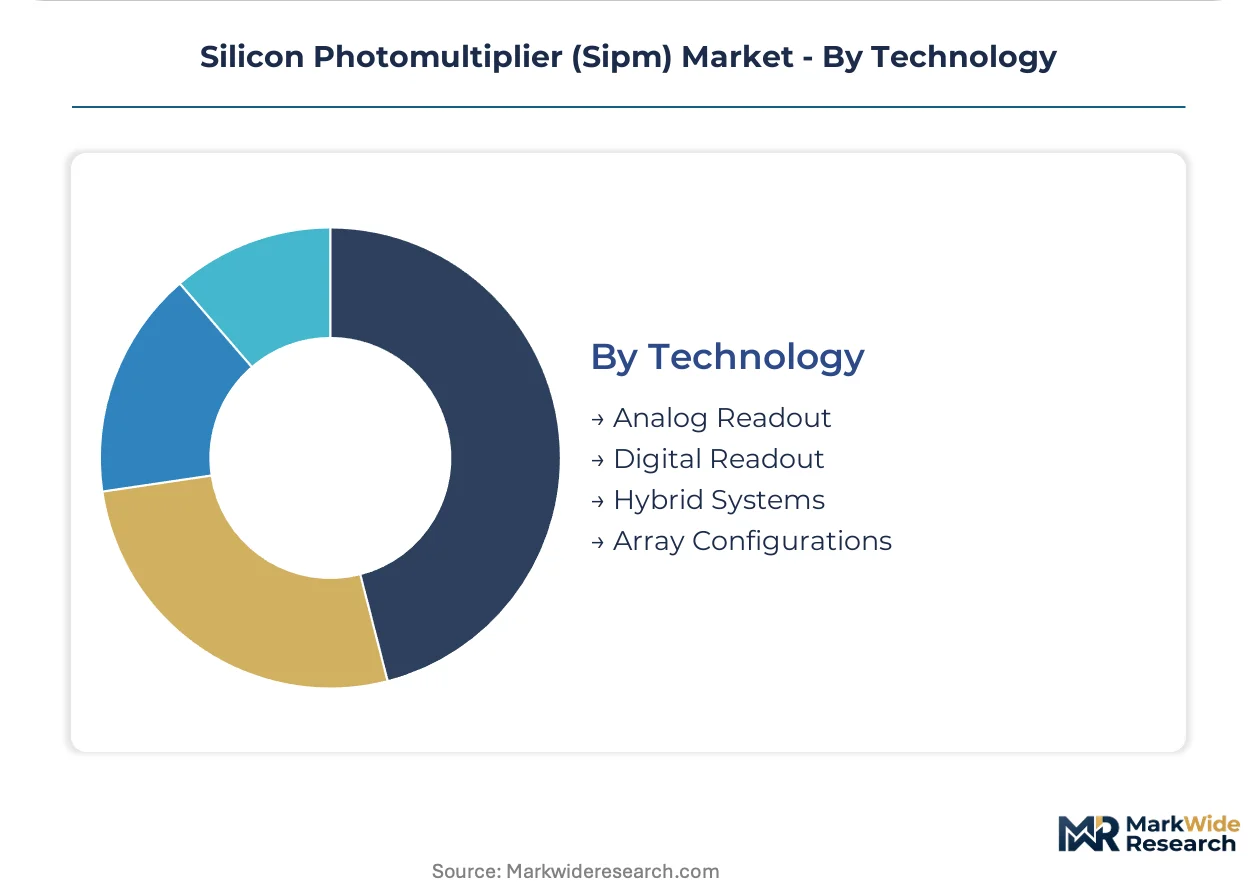
Technology:
Architecture choice determines whether value capture remains with device foundries or shifts toward firmware-capable system integrators.
- Digital Readout:Integrated time-to-digital converters with on-chip timestamping now specified by Siemens Healthineers and GE Healthcare for new PET-CT platforms. This displacement eliminates discrete amplifier board suppliers and concentrates margin in foundry-scale manufacturers with FPGA programming expertise.
- Analog Readout:Legacy front-end architectures maintained by hybrid scanner OEMs with proprietary certification requirements that complicate third-party module integration.
- Hybrid Systems:Mixed-signal approaches bridging analog detector outputs with digital acquisition hardware.
- Array Configurations:Tiled sensor arrangements for large-area detection surfaces in radiation monitoring installations.
Deployment scale favors Analog Readout legacy infrastructure. Digital Readout shows the steepest expansion trajectory as system architects abandon analog front-ends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleanroom process engineers with Geiger-mode APD fabrication expertise concentrate at legacy CMOS foundries in Japan, Germany, and the United States, anchoring regional capability distribution.
Japan
Japanese academic medical centers consolidate procurement through METI-funded imaging consortia standardizing performance benchmarks. PMDA alignment with ICH Q5D guidelines extends traceability requirements from crystal growth lots through module serial numbers. University hospitals in Osaka and Tokyo now compress vendor qualification timelines.
Germany
Precision instrumentation demand concentrates in the Munich-Jena corridor where medical facilities expand SiPM procurement for PET-CT hybrid scanners. EU MDR conformity assessment tightens performance verification standards beyond earlier CE-marking regimes. Research institutions at DESY drive custom multi-pixel sensor specifications with direct vendor engineering relationships.
United States
FDA 510(k) pathways now demand clinical evidence for SiPM-based diagnostic devices that earlier submissions satisfied with bench testing alone. Hybrid scanner OEMs maintain proprietary front-end architectures complicating third-party module certification. Defense contractors specify hardened configurations for radiation-hardened multi-pixel sensors.
China
Domestic foundries scale digital readout array production as system architects abandon analog front-ends for FPGA-based timestamping. NMPA regulatory pathways for diagnostic device registration create compliance barriers for imported modules. Industrial laboratories in the Yangtze River Delta region drive moderate volume requirements for quality control applications.
Switzerland
CERN procurement specifications for calorimetry and time-of-flight detectors shape custom sensor geometry evolution with decade-long capital horizons. Swissmedic alignment with EU MDR streamlines cross-border device certification for medical imaging suppliers. Geneva-area research consortia generate predictable replacement demand distinct from commercial capital equipment cycles.
Silicon Photomultiplier (Sipm) Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the SiPM value chain. Foundry-scale device manufacturers absorb FPGA programming costs that previously sat with system integrators. The vendor base stratifies into three archetypes: vertically integrated photonics houses with captive crystal growth, fabless digital readout specialists, and custom sensor fabricators for particle physics. Dominant competitive moves include backward integration into scintillator substrate production and strategic partnerships with hybrid scanner OEMs.
Among Japanese photonics houses, Hamamatsu Photonics K.K. exemplifies the vertically integrated archetype spanning crystal growth to module assembly. Onsemi occupies a position among foundry-scale manufacturers competing through digital readout array production. KETEK GmbH represents the custom fabrication specialist tier serving research institutions with multi-pixel configurations.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| onsemi |
| Broadcom Inc. |
| Excelitas Technologies Corp. |
| KETEK GmbH |
| First Sensor AG |
| AdvanSiD |
| Cremat Inc. |
| Radiation Monitoring Devices, Inc. |
| Others |
Cost & Logistics Intelligence
Performance-grade divergence between sub-nanosecond timing sensors and commodity avalanche photodiodes manifests in pricing premiums exceeding threefold and supply chain configurations that concentrate high-reliability die production in German and Japanese foundries while pushing standard devices toward catalog distribution.
Pricing Analysis
Bundled FPGA programming services versus unbundled die-only procurement defines the pricing split in this market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Cost compression in standard avalanche photodiodes is intensifying because foundry-scale manufacturers from China are flooding research laboratory segments. University hospital consortia in Japan exhibit the lowest price sensitivity due to METI-funded procurement standardization.
Supply Chain Analysis
Lutetium-based scintillator substrate supply rests on Japanese, Chinese, and German specialty chemical producers with captive crystal growth operations. Geiger-mode APD fabrication draws from silicon wafer feedstocks, rare-earth dopants, and precision metallization chemistries. Single-source vulnerability concentrates in neutron-hardened packaging materials where REACH substance restrictions are forcing qualification delays. Distribution runs through direct OEM contracts for healthcare imaging and catalog distributors for radiation detection agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR conformity assessment tightening for PET-CT hybrid scanners generates replacement demand that outpaces underlying equipment depreciation cycles.
For Market Incumbents: Extend captive scintillator production through backward integration into lutetium crystal growth to neutralize input volatility from Asian suppliers. Fortify FPGA programming capabilities as digital readout specifications from Siemens Healthineers and GE Healthcare eliminate discrete amplifier board tiers. Digital readout specialists without crystal growth capabilities represent the primary emerging threat to module assembly margins.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in photon counting modules opens white-space at mid-tier research laboratory segments lacking in-house front-end design capability. Particle physics grant-funded procurement at CERN and DESY offers the most penetrable entry vector given decade-long capital horizons and direct engineering relationship protocols. A service-contract revenue model aligned with PMDA traceability documentation requirements differentiates against component-only suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where foundry-scale digital readout manufacturers lack scintillator coupling expertise and face margin compression from FPGA programming cost absorption. Fabless digital readout specialists with hospital system partnerships represent the optimal acquisition archetype over five-to-ten year holding periods. Watch FDA 510(k) clinical evidence requirement enforcement intensity as the inflection signal for diagnostic device vendor viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scintillator Production | Crystal growth captive supply neutralizes lutetium substrate volatility from Asian suppliers. |
| Digital Readout Array Foundry Scale-Up | On-chip timestamping specifications from Siemens Healthineers displace discrete amplifier tiers. |
| PMDA-Aligned Traceability Documentation | Biopharmaceutical manufacturing protocol extensions open service contract revenue in Japan. |
| Neutron-Hardened Packaging Qualification | REACH alternative metallurgy certification unlocks defense contractor procurement decisions. |
| Hospital System Partnership Development | Osaka and Tokyo university hospital consortia compress vendor qualification timelines. |
Research Approach
Bottom-up PET-CT procurement modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and particle physics specification teams at CERN and DESY combined with secondary validation from FDA 510(k) filings, EMA notified body guidance documents, METI consortium procurement databases, and customs records for scintillator substrate trade flows. Triangulation between demand-side installation tracking and supply-side cleanroom capacity announcements ensures dimensional consistency.
Input-output matrix framing maps SiPM die production volumes through module assembly stages to end-use deployment across healthcare imaging, particle physics, and radiation detection segments. Segmentation dimensions include product type, application, end user, and technology architecture across the modeling period. CAGRs derive from fitted growth curves against historical procurement patterns and regulatory milestone timing. Forecast inputs incorporate EU MDR implementation velocity and digital readout specification adoption rates from major hybrid scanner OEMs.
Caveats apply where REACH substance restriction enforcement delays or photomultiplier tube residual demand persistence could materially shift the outlook. Forecasts reflect assumptions about clinical evidence requirement stability and foundry-scale manufacturing yield progression. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Europe Smart Glove Market