
 United States Pressure Transmitter Market | 2026-2036
United States Pressure Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pressure Transmitter Market Intelligence
ISA/IEC 61508 functional safety certification is redrawing competitive boundaries for suppliers serving hazardous process environments. Emerson Electric Co. leverages its Rosemount manufacturing footprint in Minnesota to sustain domestic calibration traceability. Honeywell International Inc. competes through its distributed control system integration, anchoring transmitter sales within larger automation packages. ABB differentiates via its Ability digital platform, extending hardware margins into recurring software services.
A pressure transmitter converts fluid or gas pressure into a standardized electrical signal, typically 4-20 mA or digital protocols, using sensing elements such as piezoresistive silicon or capacitive ceramic diaphragms to enable real-time process monitoring and control. Differential pressure transmitters dominate revenue contribution due to their ubiquity in flow and level measurement applications across hydrocarbon processing. Piezoresistive technology leads unit volume given its cost efficiency and compatibility with silicon microfabrication, while resonant sensing occupies the premium tier where stability specifications below 0.025% span command price premiums. Oil and gas end users concentrate procurement in supermajor maintenance cycles, whereas pharmaceutical demand follows FDA validation requirements that favor established suppliers with documented calibration histories.
FDA 21 CFR Part 11 electronic records requirements shape pharmaceutical transmitter specifications, while EPA Clean Air Act enforcement drives oil and gas operator investment in leak detection instrumentation. OSHA Process Safety Management standards mandate redundant pressure monitoring in covered chemical facilities, creating qualified supplier lists that exclude uncertified entrants. Stakeholders must weigh capital allocation between expanding IIoT-enabled transmitter portfolios and defending position in replacement-driven conventional installations.
Market Dynamics
Upstream oil and gas operators are replacing legacy mechanical pressure gauges with smart transmitters capable of continuous methane monitoring, driven by EPA Clean Air Act enforcement timelines and the operational imperative to reduce unplanned shutdowns across Permian Basin gathering systems.
Growth Catalysts
- EPA Methane Emissions Mandates:The Clean Air Act compels Permian Basin operators to install digitally-integrated pressure transmitters for real-time leak detection, accelerating instrument replacement cycles.
- Piezoresistive Silicon Microfabrication:Advances in MEMS manufacturing reduce unit costs while maintaining accuracy specifications, expanding addressable applications into mid-tier process industries.
- Texas-Louisiana Petrochemical Cluster Density:Concentrated refining and chemical processing capacity drives bulk procurement of differential pressure transmitters for flow measurement infrastructure.
Market Restraints
- ISA/IEC 61508 Certification Barriers:Functional safety qualification costs and extended validation timelines exclude smaller suppliers from hazardous environment contracts.
- Stainless Steel and Semiconductor Input Volatility:Pressure transmitter housings and sensing element substrates face price instability from concentrated raw material supply chains.
- Mechanical Gauge Substitution in Low-Criticality Applications:Basic analog instruments retain cost advantage in non-safety process monitoring where digital integration offers marginal value.
Strategic Opportunities
- Software-Enabled Service Revenue:Digital platform integration allows hardware suppliers to capture recurring margins through predictive calibration and remote diagnostics.
- FDA 21 CFR Part 11 Pharmaceutical Validation:Electronic records requirements create qualified supplier preference for established transmitter manufacturers with documented calibration histories.
- Gulf Coast Hydrogen Hub Development:Emerging carbon capture and hydrogen production facilities require specialized high-pressure measurement instrumentation for novel process chemistries.
Industry Challenges
- Fieldbus Protocol Fragmentation:Proprietary communication standards complicate integration with existing distributed control systems, extending commissioning timelines.
- Silicon Resonant Sensor Talent Scarcity:Specialized expertise in high-stability sensing element design concentrates within a limited pool of experienced engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pressure Transmitter Market |
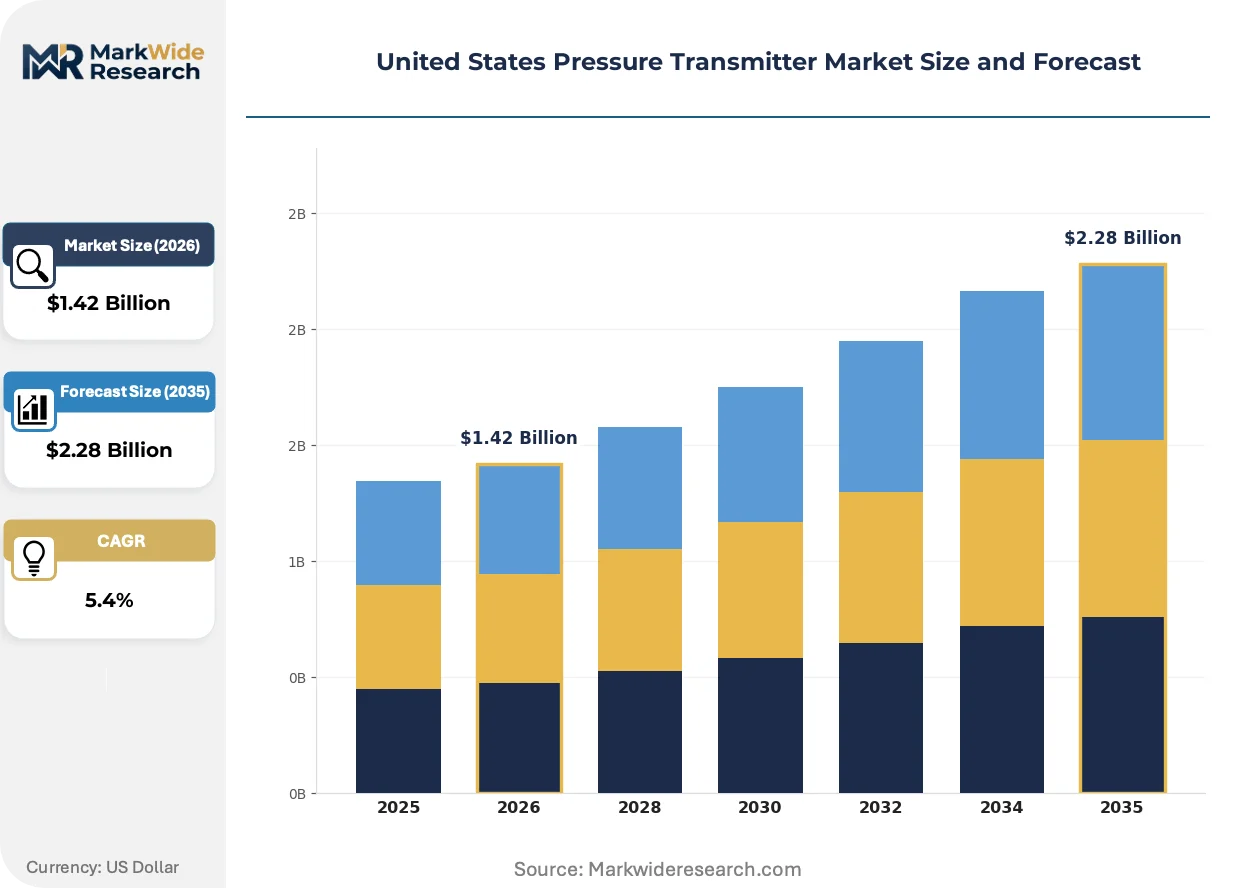
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Differential, Gauge, Sealed End User: Oil & Gas, Pharmaceuticals, Food & Beverage, Wastewater Treatment Technology: Piezoresistive, Capacitive, Strain Gauge, Resonant Installation: In-line, Flange Mounted, Threaded, Clamp-on |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., ABB, Yokogawa Electric Corporation, Siemens, Endress+Hauser, Schneider Electric, WIKA Alexander Wiegand SE & Co. KG, Dwyer Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pressure Transmitter Market Strategic Shifts & Innovations
Pressure transmitter architecture is converging toward edge-computing capability, with sensing elements now hosting local diagnostic algorithms that preempt calibration drift before control system notification.
Silicon carbide MEMS pressure sensing is miniaturizing transducer footprints while extending operational temperature ranges beyond traditional piezoresistive limits. Aerospace and downhole oil and gas applications are adopting these ceramic-substrate devices for hostile environment durability. The technology is miniaturizing package dimensions sufficiently for integration into compact subsea wellhead monitoring systems.
OSHA Process Safety Management standards are mandating redundant pressure monitoring architectures in covered chemical facilities, compelling facility-wide instrument upgrades. The regulation requires documented proof of independent measurement channels for critical control loops. Chemical processors in Louisiana and Texas are responding with phased replacement programs that prioritize high-consequence equipment.
Maintenance procurement is consolidating under integrated service contracts that bundle transmitter supply with calibration management and spare parts logistics. End users in hydrocarbon processing are displacing transactional component purchasing with multi-year performance agreements. This shift is most visible among supermajor operators executing synchronized turnaround schedules across Gulf Coast refining assets.
United States Pressure Transmitter Market Segmentation
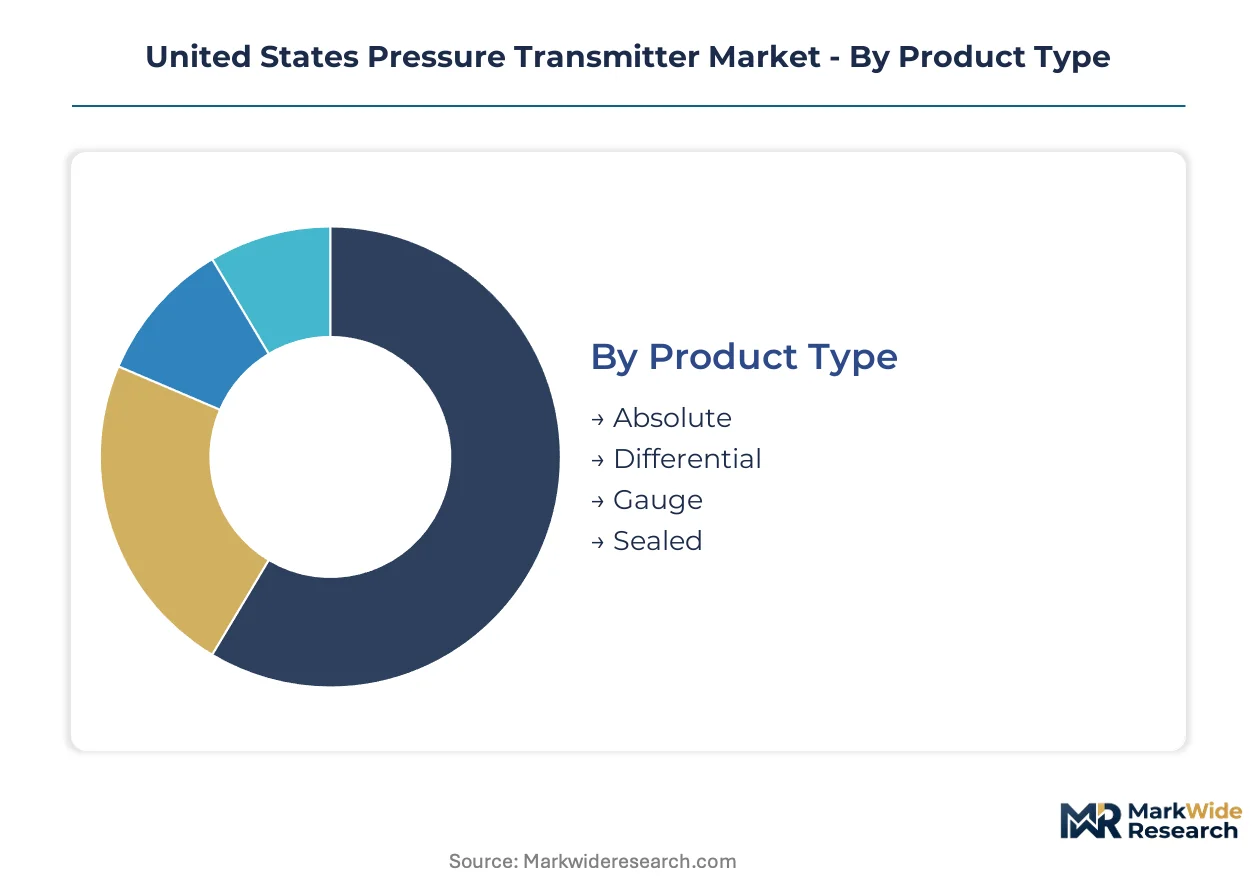
Pressure transmitter procurement patterns in the United States diverge sharply across measurement technology and installation topology. Segment boundaries determine supplier qualification requirements, calibration protocols, and service revenue potential for domestic manufacturers.
Product Type:
Margin pools concentrate in differential pressure architectures where flow-derived applications command premium pricing over static pressure measurement.
- Differential:Measures pressure difference between two process points using dual diaphragm isolation, essential for orifice plate flow calculations and liquid level inference in distillation columns. Permian Basin gathering systems and Texas Gulf Coast refineries deploy these for custody transfer metering where accuracy specifications below 0.1% span justify unit costs exceeding absolute alternatives.
- Absolute:References sealed vacuum chamber for barometric-independent measurement critical to vacuum distillation and semiconductor process chambers. Pharmaceutical lyophilization and aerospace altitude simulation in California and Massachusetts facilities drive qualification-intensive procurement.
- Gauge:Vents to atmospheric pressure for general process monitoring where local indication suffices.
- Sealed:Protects sensing element from corrosive media via isolation fluid, common in chemical injection skids.
The dominant share belongs to Differential, while Absolute is closing the gap fastest.
End User:
Customer concentration patterns reflect regulatory enforcement intensity and capital cycle synchronization across industrial clusters.
- Oil & Gas:Upstream operators in Texas, Louisiana, and North Dakota replace legacy instrumentation under EPA methane monitoring mandates, with smart transmitter adoption accelerating in Permian Basin pad drilling operations. Downstream refineries synchronize procurement with five-year turnaround schedules.
- Pharmaceuticals:FDA 21 CFR Part 11 validation requirements favor suppliers with documented calibration histories, concentrating demand among established manufacturers serving New Jersey and Massachusetts biopharma corridors.
- Food & Beverage:USDA sanitary standards govern clean-in-place transmitter selection for dairy processing in Wisconsin and brewing operations in Colorado.
- Wastewater Treatment:Municipal utilities in California and Florida prioritize corrosion-resistant submersible level transmitters for lift station monitoring.
Oil & Gas maintains volume leadership, though Pharmaceuticals shows the steepest expansion trajectory as biologics manufacturing capacity multiplies.
Technology:
Silicon microfabrication scale economies have restructured cost tiers across sensing element architectures.
- Piezoresistive:Boron-doped silicon strain elements fabricated through MEMS processes deliver cost efficiency at moderate accuracy, dominating mid-tier process applications. Texas Instruments and Honeywell sourcing strategies for automotive-qualified silicon wafers have spilled into industrial transmitter supply chains.
- Resonant:Quartz or silicon resonant structures achieve stability specifications below 0.025% span for fiscal metering and custody transfer where calibration intervals extend beyond five years. North Sea technology transfer has limited domestic engineering talent pools.
- Capacitive:Ceramic diaphragm capacitance detection suits high-overpressure and corrosive media.
- Strain Gauge:Bonded foil elements persist in ruggedized applications with extreme vibration.
Piezoresistive sensing commands unit volume leadership, while Resonant technology gains share fastest in premium hydrocarbon processing contracts.
Installation:
Mounting topology selection determines seal compatibility, maintenance accessibility, and piping modification costs.
- Flange Mounted:ASME B16.5 or API 6A flange connections dominate high-pressure hydrocarbon processing where process isolation valves enable hot-swapped replacement without line shutdown. Louisiana chemical facilities specify these for reactor pressure monitoring.
- In-line:Direct pipe insertion with compression fittings suits water and steam applications in pulp mills and power plants.
- Threaded:NPT or BSPP connections serve lower-pressure utility monitoring.
- Clamp-on:Non-invasive ultrasonic alternatives avoid process penetration in food-grade and high-purity lines.
Flange Mounted configurations retain the largest installed base, though Clamp-on installations are expanding most quickly in sanitary process retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators and petrochemical processors concentrate procurement in states with dense hydrocarbon infrastructure and stringent environmental enforcement timelines.
Texas
Permian Basin pad drilling operations and Gulf Coast refining corridors drive differential pressure transmitter demand for custody transfer and flow measurement applications. EPA Clean Air Act methane monitoring mandates compel operators to replace legacy mechanical gauges with smart, digitally-integrated instruments. Houston and Beaumont petrochemical clusters synchronize bulk procurement with five-year turnaround schedules.
Louisiana
Chemical facilities along the Mississippi River Industrial Corridor upgrade redundant pressure monitoring architectures to satisfy OSHA Process Safety Management standards. The state's concentration of high-consequence equipment drives flange-mounted transmitter specifications for reactor pressure monitoring. Baton Rouge and Lake Charles processors execute phased replacement programs prioritizing ISA/IEC 61508 certified suppliers.
California
Pharmaceutical lyophilization and semiconductor process chamber applications favor absolute pressure transmitters with vacuum-reference specifications. FDA 21 CFR Part 11 electronic records requirements shape validation-intensive procurement in San Francisco Bay Area biopharma corridors. Municipal wastewater utilities in Los Angeles and San Diego prioritize corrosion-resistant submersible level transmitters for lift station infrastructure.
North Dakota
Bakken Formation upstream operators face EPA enforcement timelines for methane emissions monitoring across gathering systems. Harsh winter operating conditions drive demand for temperature-resilient sensing elements in remote wellhead installations. Williston Basin producers concentrate instrument replacement programs to reduce unplanned shutdowns.
Massachusetts
Biologics manufacturing capacity expansion in Greater Boston corridors accelerates pharmaceutical-grade pressure transmitter procurement. FDA validation requirements favor established suppliers with documented calibration histories for sterile process applications. Cambridge and Worcester facilities specify piezoresistive technology for cost-efficient mid-tier measurement points.
United States Pressure Transmitter Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with established automation platforms and functional safety certifications. The vendor base stratifies across three tiers: integrated automation suppliers bundling transmitters within distributed control systems, specialized instrumentation manufacturers with deep calibration service networks, and emerging MEMS-focused entrants exploiting silicon microfabrication scale economies. Dominant competitive moves include strategic partnerships for IIoT platform integration and geographic expansion through regional calibration facility investments.
Among diversified automation conglomerates, Emerson Electric Co., Honeywell International Inc., and ABB occupy positions defined by their respective platform strategies. Emerson leverages its Rosemount manufacturing footprint to sustain domestic calibration traceability for hazardous environment contracts. Honeywell competes through distributed control system integration, anchoring transmitter sales within larger automation packages. ABB differentiates via its Ability digital platform, extending hardware margins into recurring software services for predictive calibration and remote diagnostics.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| ABB |
| Yokogawa Electric Corporation |
| Siemens |
| Endress+Hauser |
| Schneider Electric |
| WIKA Alexander Wiegand SE & Co. KG |
| Dwyer Instruments |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for ISA/IEC 61508 certified sensing elements concentrate pricing power among domestic calibration houses with Rosemount-class traceability, while spot-market stainless steel volatility feeds back into contract indexation clauses across Permian Basin procurement.
Pricing Analysis
Cost-plus contracts with London Metal Exchange stainless steel indexation dominate multi-year transmitter agreements between Gulf Coast petrochemical operators and tier-one automation suppliers. Three-tier pricing structure across premium, standard, and economy levels separates resonant-sensing fiscal metering units from piezoresistive process instruments and basic gauge configurations. Pricing pressure stems from MEMS microfabrication scale economies eroding mid-tier margins, though ISA/IEC 61508 certification premiums defend value in Louisiana chemical facilities. Municipal wastewater utilities exhibit highest price sensitivity due to budget-constrained procurement protocols, while pharmaceutical lyophilization applications show least sensitivity given FDA validation lock-in effects.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Minnesota-based calibration facilities serving hazardous environment contracts, though strategic stockpiling of ceramic diaphragm substrates buffers against Taiwan semiconductor foundry lead time volatility. Silicon wafer sourcing draws from Texas Instruments and Honeywell automotive-qualified supply chains, with boron-doped strain elements and capacitive ceramic diaphragms anchoring input dependencies. Single-source vulnerability concentrates in resonant sensor quartz crystal supply from Japanese and Swiss specialty manufacturers. Distribution runs through authorized distributor networks with field service engineering attachment, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure transmitter architecture is approaching a platform-economics inflection as Fieldbus protocol fragmentation gives way to OPC UA interoperability standards, collapsing hardware margin pools into software-enabled service ecosystems.
For Market Incumbents: Fortify calibration service network density across Texas and Louisiana chemical corridors to defend against MEMS-focused entrants exploiting silicon microfabrication scale economies. Deepen backward integration into ceramic substrate supply through captive sourcing agreements with Japanese specialty manufacturers. Prioritize ISA/IEC 61508 certification maintenance as qualification barriers exclude uncertified competitors from OSHA-mandated redundant monitoring architectures.
For New Entrants and Emerging Players: Anchor in clamp-on ultrasonic retrofit opportunities across Wisconsin dairy processing and Colorado brewing operations where sanitary process modifications favor non-invasive measurement. Target FDA 21 CFR Part 11 validation services as attach revenue to piezoresistive hardware sales in Greater Boston biopharma corridors. Pursue integrated service contract positioning to displace transactional component purchasing among supermajor operators.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because predictive calibration and remote diagnostics software margins compound hardware replacement cycles. Acquisition candidates include specialized instrumentation manufacturers with deep calibration service networks and documented FDA validation histories. Monitor Gulf Coast hydrogen hub development timelines as inflection indicator for high-pressure measurement instrumentation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OPC UA interoperability collapses Fieldbus fragmentation, enabling software service attachment to hardware sales. |
| Backward Integration | Captive ceramic substrate sourcing from Japanese manufacturers buffers resonant sensor supply vulnerability. |
| Certification Investment | ISA/IEC 61508 qualification maintenance excludes uncertified entrants from OSHA-mandated chemical facility contracts. |
| Geographic Expansion | Calibration facility density in Texas-Louisiana corridors defends incumbent position against MEMS-focused entrants. |
| Strategic Partnership | FDA validation service alliances with established pharmaceutical manufacturers lock in biopharma procurement preference. |
Research Approach
A standing panel of plant engineers, maintenance directors at Permian Basin upstream operators, OEM procurement teams, and aftermarket service heads provided ongoing calibration against secondary validation through EPA enforcement timelines, OSHA Process Safety Management filings, FDA 21 CFR Part 11 guidance documents, and customs trade data. Bottom-up transmitter unit estimates triangulated against top-down petrochemical capital expenditure patterns across Texas and Louisiana refining corridors.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning differential versus absolute versus gauge measurement topologies, piezoresistive versus resonant versus capacitive sensing technologies, and flange-mounted versus in-line versus clamp-on installation configurations. CAGRs derived from instrument replacement cycle analysis incorporating EPA methane monitoring mandate compliance timelines and supermajor turnaround schedule synchronization.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Clean Air Act enforcement intensity and stable stainless steel input pricing; material deviation in regulatory timelines or commodity volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Smart Thermometer Market