
 Lactose-Free Sour Cream Market | 2026-2036
Lactose-Free Sour Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose-Free Sour Cream Market Foresight
Supermarket dairy aisles is narrowing as retailers consolidate shelf space for premium lactose-free lines. Green Valley Creamery leverages its dedicated lactose-free facility network to sustain consistent supply across conventional and natural channels. Arla Foods anchors its competitive position through specialized enzyme technology that preserves traditional sour cream texture. Danone competes by extending its plant-based and dairy-free expertise into cultured product formats with broad European distribution.
Lactose-free sour cream denotes cultured cream treated with lactase enzyme to hydrolyze lactose into glucose and galactose, yielding a product with sweetness comparable to conventional sour cream but digestible for lactose-intolerant consumers. The fermentation process typically employs Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus at controlled temperatures, producing the characteristic tangy flavor and viscous consistency essential for both cold applications and heat-stable cooking. The cream and cooking ingredient segments dominate current volume, with tubs as the leading packaging format in household channels. Online retailers represent the fastest-growing distribution pathway, driven by subscription replenishment models and direct-to-consumer sampling programs that reduce trial barriers for first-time buyers.
The FDA enforces dairy identity standards under 21 CFR 131 that govern sour cream composition and labeling, while the USDA's National Organic Program certifies organic claims that command price premiums in specialty retail. The EU's Regulation (EU) No 1169/2011 mandates allergen labeling for lactose-containing products, creating compliance complexity for exporters but also market transparency that builds consumer trust. Stakeholders must monitor evolving enzyme patent expirations and clean-label formulation trends that could reshape competitive differentiation without regulatory mandate.
Market Dynamics
Enzyme patent expirations are redistributing competitive advantage from proprietary lactase formulations toward process-scale manufacturing efficiency, compressing margins for technology licensors while expanding access for regional dairy processors.
Growth Catalysts
- Digestive wellness positioning:Health-conscious urban households in the United States treat lactose-free sour cream as a functional cooking ingredient rather than a medical necessity, expanding addressable demand beyond diagnosed intolerance populations.
- Menu standardization mandates:Large restaurant chains operating across North America now require lactose-free alternatives for core dairy ingredients to accommodate diverse dietary needs without operational complexity.
- Clean-label fermentation protocols:Advances in controlled-temperature culturing with Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus preserve traditional texture without artificial stabilizers, satisfying natural-channel retail requirements.
Market Restraints
- Cream input cost volatility:Fluid dairy commodity markets expose processors to margin pressure when butterfat prices spike, particularly affecting smaller facilities without forward-contracting capabilities.
- Supply concentration in enzyme manufacturing:Lactase production clusters among a limited set of European and North American biotechnology suppliers, creating vulnerability to geopolitical trade friction or production interruptions.
- Refrigerated distribution infrastructure gaps:Cold-chain limitations in secondary markets restrict product reach, as lactose-free sour cream requires uninterrupted temperature control from production through retail display.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer platforms with auto-replenishment algorithms capture recurring household purchases while reducing customer acquisition costs through sampling programs.
- Heat-stable formulation expansion:Modified enzyme treatment protocols enable sour cream performance in high-temperature cooking applications previously dominated by conventional products, opening foodservice volume.
- Organic certification layering:USDA National Organic Program standards command price premiums in specialty retail when combined with lactose-free claims, differentiating commodity-adjacent products.
Industry Challenges
- Dual-label compliance complexity:Simultaneous adherence to FDA dairy identity standards under 21 CFR 131 and EU Regulation (EU) No 1169/2011 allergen labeling creates formulation and packaging versioning burdens for exporters.
- Skilled fermentation technician scarcity:Precision culturing operations require specialized expertise in microbial management and temperature control that outpaces vocational training program output in dairy-producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose-Free Sour Cream Market |
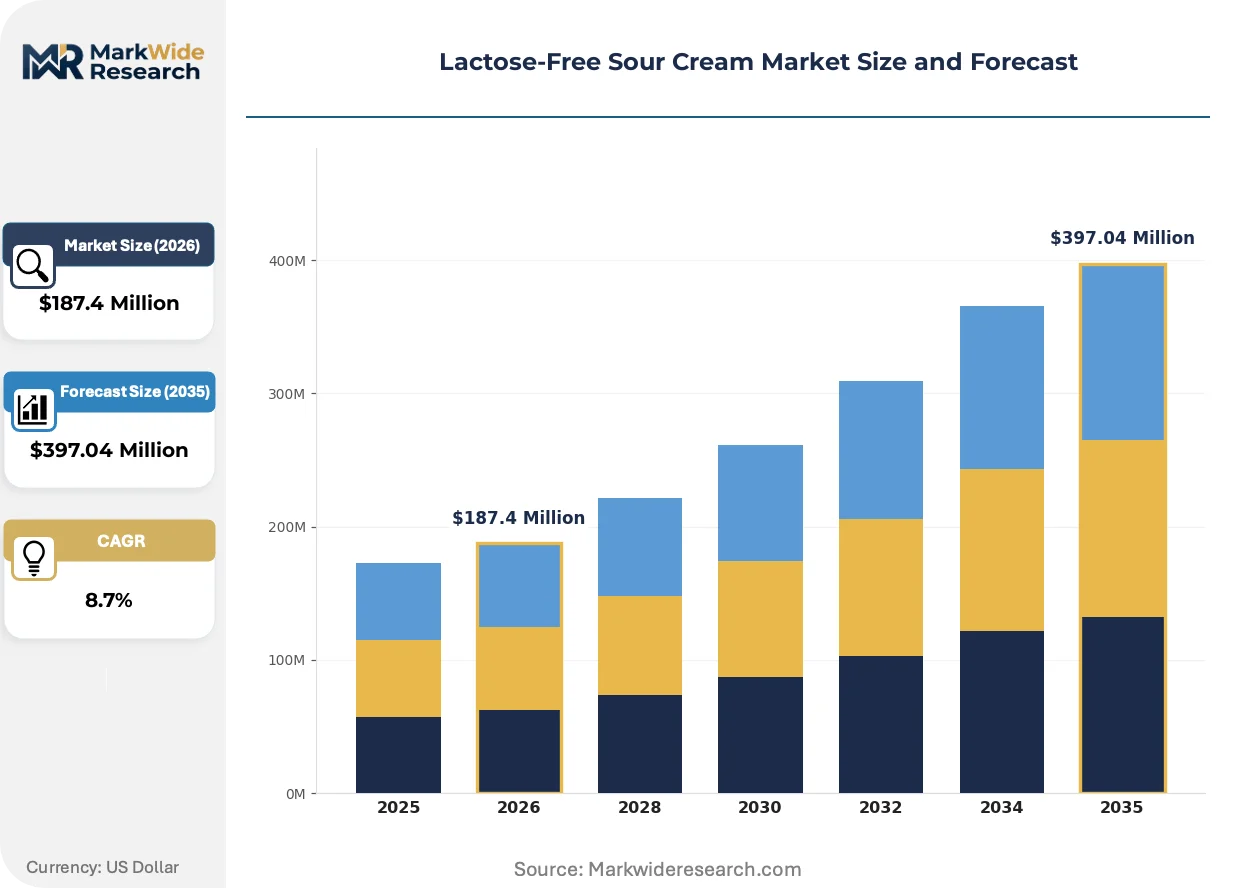
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Dip, Cooking Ingredient, Spread Packaging Type: Tubs, Pouches, Squeeze Bottles, Jars End User: Households, Restaurants, Bakeries, Cafés Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesalers |
| Companies Covered | Green Valley Creamery, Prairie Farms Dairy, Hiland Dairy, Daisy Brand, Organic Valley, Arla Foods, Danone, Lactalis, Valio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose-Free Sour Cream Market Shifts & Advancements
Formulation science and distribution architecture are converging to redefine how lactose-free sour cream reaches end-users, with implications for shelf stability, regulatory positioning, and purchasing behavior across retail and foodservice channels.
Precision lactase dosing technology is hybridizing traditional batch hydrolysis with continuous-flow enzyme treatment, enabling real-time adjustment of glucose and galactose conversion rates. Mid-scale dairy processors in the United States and Germany are piloting these systems to reduce holding tank requirements and accelerate production cycles. The structural consequence is compression of minimum efficient scale, allowing regional facilities to achieve cost parity with integrated national networks.
The FDA's updated dairy labeling standards under 21 CFR 131 are tightening identity requirements for enzyme-modified cultured cream products, mandating clearer distinction between traditional sour cream and lactose-free variants. This regulatory tightening forces reformulation of legacy products that previously relied on ambiguous ingredient statements. Organic and natural-channel brands face the steepest compliance timelines, as their consumer bases exhibit highest label scrutiny.
Restaurant procurement departments are consolidating supplier relationships around full-line dairy partners capable of delivering both conventional and lactose-free sour cream under unified purchase agreements. Foodservice distributors are responding by bundling enzyme-treated products with standard SKUs, reducing the operational friction of managing separate inventory streams. This consolidation pattern is most visible in metropolitan markets of the United States, where large chain accounts drive volume concentration.
Lactose-Free Sour Cream Market Segmentation
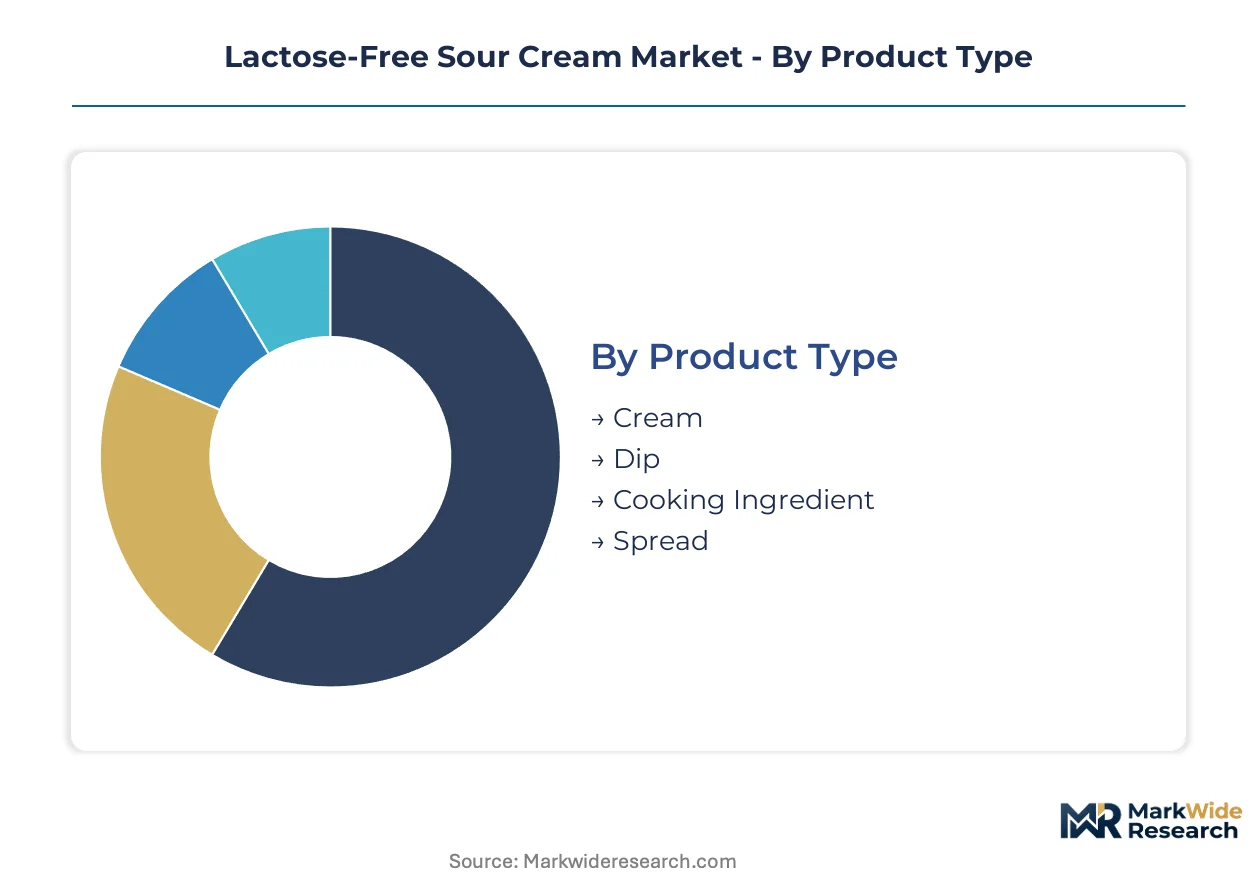
Segmentation in the lactose-free sour cream market reveals distinct service and replenishment patterns across channels. Household subscribers require predictable delivery cadences, while foodservice operators demand technical support for formulation integration. Understanding these divergent needs shapes packaging, distribution, and customer success investments.
Product Type:
After-sales intensity varies sharply across product formats, with cooking ingredient applications requiring chef training and recipe development support that cream formats rarely need.
- Cream:Traditional cultured cream base with lactase hydrolysis delivers the foundational tangy profile and viscous body for both direct consumption and recipe incorporation. United States urban households concentrate demand here, driven by digestive wellness positioning that treats lactose-free options as functional kitchen staples rather than medical substitutes.
- Cooking Ingredient:Heat-stabilized formulations using modified enzyme protocols maintain emulsion integrity at high temperatures for sauces and baked applications. Restaurant chains across North America standardize procurement around this segment to accommodate diverse dietary needs without operational complexity.
- Dip:Pre-seasoned cultured cream products with flavor inclusions for immediate serving occasions.
- Spread:Viscosity-adjusted formulations optimized for direct application on breads and crackers.
By volume, Cooking Ingredient leads. By growth pace, Cream is ahead.
Packaging Type:
Cost tier stratification separates premium-positioned formats from economy options, with material specifications and convenience features driving price architecture.
- Tubs:Injection-molded polypropylene containers with tamper-evident lids dominate household channel economics through established dairy case placement. United States supermarkets consolidate shelf space around this format, prioritizing premium lactose-free lines as conventional sour cream facings narrow.
- Pouches:Flexible film structures with spout fitments reduce shipping cube and refrigeration load for direct-to-consumer distribution. Online retailers represent the fastest-expanding pathway here, with subscription replenishment algorithms capturing recurring purchases.
- Squeeze Bottles:Controlled-dispense packaging for foodservice portion control and reduced contamination risk.
- Jars:Glass or rigid PET containers targeting specialty retail and gift-oriented purchase occasions.
Tubs command the largest volume position. Pouches are climbing the fastest.
End User:
Customer type determines technical service depth, with commercial accounts requiring formulation guidance that household consumers bypass entirely.
- Households:Individual consumers purchasing through retail channels for home cooking and direct consumption. Health-conscious urban centers in the United States concentrate demand, where lactose-free sour cream functions as a digestible alternative for everyday recipe substitution.
- Restaurants:Multi-unit operators requiring consistent supply and menu integration support for standardized recipes. Large chains now mandate lactose-free alternatives for core dairy ingredients, consolidating supplier relationships around full-line dairy partners.
- Bakeries:Artisan and commercial producers incorporating cultured cream into frostings, fillings, and laminated doughs.
- Cafés:Coffee-focused operators using sour cream in specialty beverages and plated desserts.
Households generate the highest absolute volume. Restaurants are expanding most quickly.
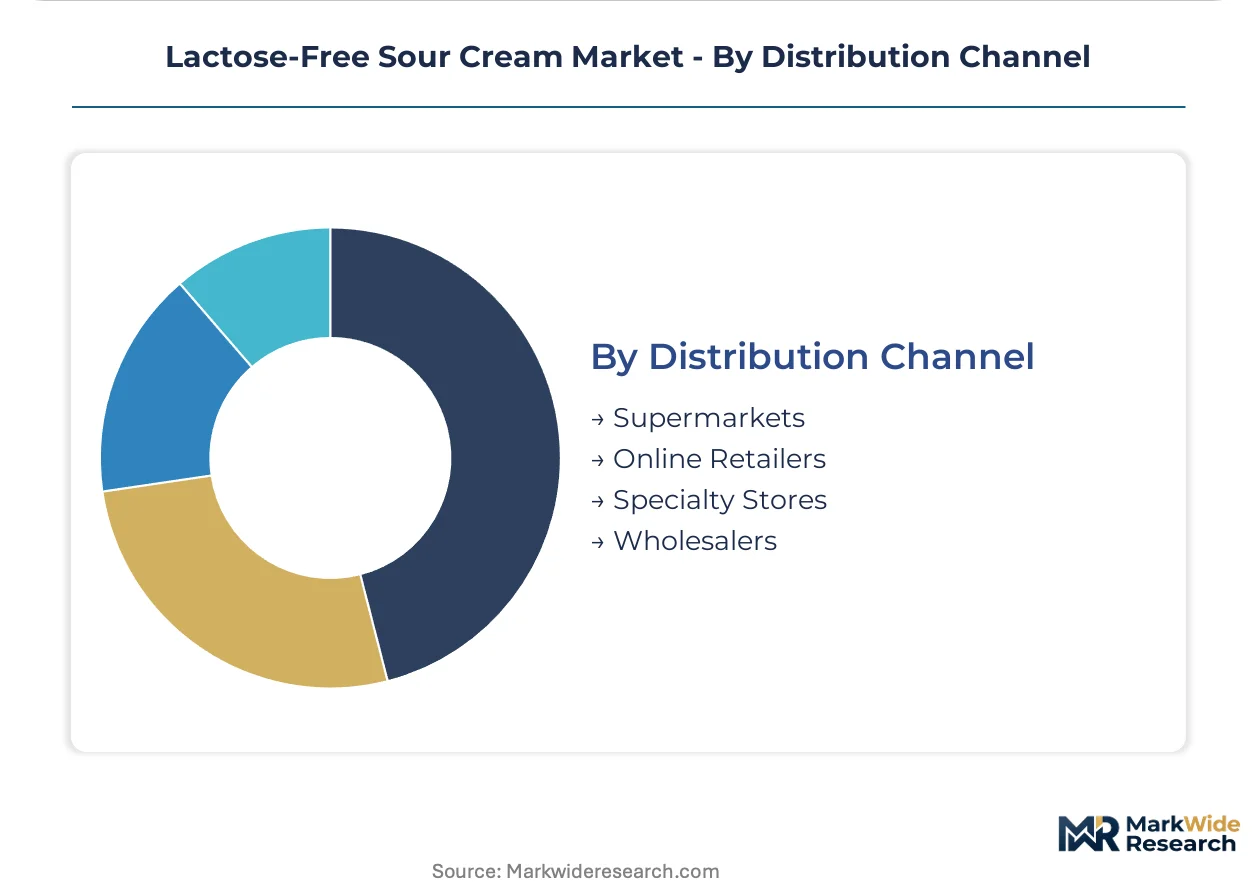
Distribution Channel:
Supply concentration among channel types creates divergent margin profiles, with direct-to-consumer platforms capturing recurring revenue streams that wholesale relationships cannot replicate.
- Supermarkets:Conventional and natural-channel grocers with dedicated dairy case placement and promotional programming. Retailers consolidate shelf space for premium lactose-free lines, compressing conventional sour cream facings.
- Online Retailers:E-commerce platforms and brand-direct storefronts with subscription auto-replenishment capabilities. Sampling programs reduce trial barriers for first-time buyers while algorithm-driven reordering captures lifetime value.
- Specialty Stores:Natural products retailers and gourmet food shops emphasizing organic certification and clean-label positioning.
- Wholesalers:Broadline foodservice distributors bundling lactose-free SKUs with conventional dairy for unified procurement.
Supermarkets maintain volume leadership. Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European distribution reach for enzyme-treated dairy exports, while Union Pacific's refrigerated rail network connects Midwest production clusters to coastal population centers.
United States
Health-conscious urban households in metropolitan markets treat lactose-free sour cream as functional kitchen staples rather than medical substitutes. FDA enforcement of dairy identity standards under 21 CFR 131 mandates clearer distinction between traditional and enzyme-modified variants. Greater Chicago's dairy processing corridor concentrates mid-scale facilities piloting continuous-flow lactase dosing systems.
Germany
Mid-scale dairy processors advance precision fermentation protocols with Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus for clean-label positioning. EU Regulation (EU) No 1169/2011 allergen labeling requirements create compliance frameworks that build consumer transparency. Bavaria's dairy technology cluster hosts biotechnology suppliers developing next-generation lactase formulations.
Canada
Restaurant procurement departments consolidate supplier relationships around full-line dairy partners capable of unified conventional and lactose-free delivery. Health Canada's food labeling regulations align with international standards while permitting organic certification layering. Ontario's Golden Horseshoe region anchors production capacity serving cross-border foodservice accounts.
France
Artisan producers incorporate cultured cream into premium positioned frostings and laminated doughs for specialty retail channels. ANSM oversight of food enzyme safety assessments shapes formulation approval timelines for novel lactase treatments. The Brittany dairy basin maintains traditional fermentation expertise while adapting to enzyme-hydrolyzed product lines.
Australia
Subscription replenishment platforms capture recurring household purchases through direct-to-consumer sampling programs that reduce trial barriers. TGA alignment with international food standards facilitates import approval for European enzyme technologies. Victoria's Gippsland region concentrates organic-certified production serving Asia-Pacific export markets.
Lactose-Free Sour Cream Market Competitive Landscape
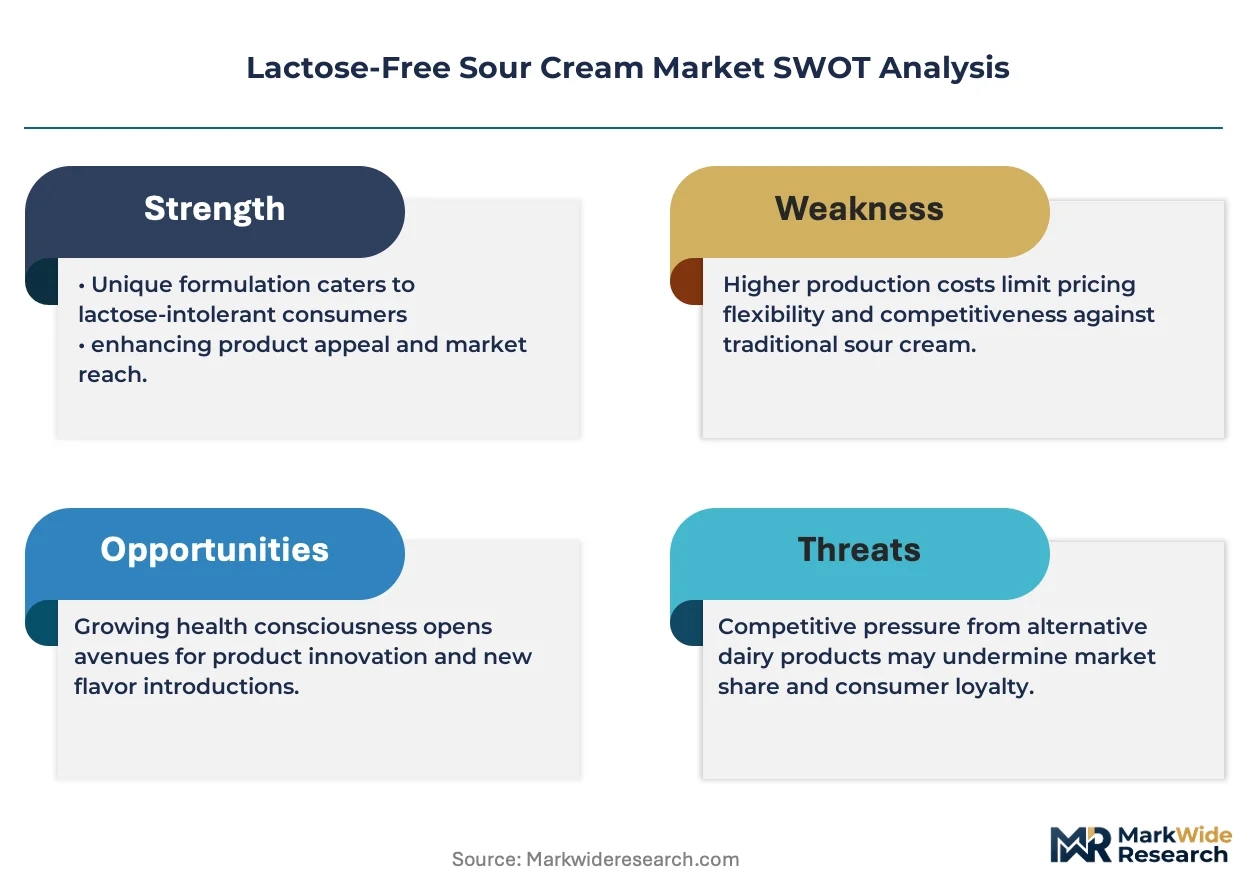
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between national dairy cooperatives with integrated enzyme-treatment capabilities and regional processors licensing third-party lactase technology. Three archetypes dominate: full-line dairy platforms with dedicated lactose-free facilities, biotechnology licensors monetizing proprietary enzyme formulations, and organic-certified specialists commanding specialty retail premiums. Competitive moves concentrate on strategic partnerships between enzyme suppliers and regional processors, plus capacity expansion in cold-chain-advantaged production zones.
Within the cooperative platform tier, Green Valley Creamery and Organic Valley exemplify facility-dedicated strategies that sustain consistent supply across conventional and natural channels. Arla Foods anchors the European technology-licensor segment, while Danone occupies a position bridging plant-based expertise with cultured dairy formats. These three represent divergent strategic postures: facility network depth, specialized enzyme preservation of traditional texture, and cross-format portfolio extension respectively.
| Leading Market Players |
|---|
| Green Valley Creamery |
| Prairie Farms Dairy |
| Hiland Dairy |
| Daisy Brand |
| Organic Valley |
| Arla Foods |
| Danone |
| Lactalis |
| Valio |
| Others |
Supply & Pricing Matrix
Mid-scale facility undercapacity in the United States Midwest is compressing spot cream procurement costs while simultaneously elevating price premiums for organic-certified lactose-free lines. This utilization asymmetry rewards processors with dedicated lactose-free infrastructure while forcing commodity-adjacent competitors into margin-defensive positioning.
Pricing Analysis
Volume-discount tiering structures separate national foodservice contracts from household subscription replenishment channels, with the latter capturing algorithm-driven lifetime value through auto-replenishment cadences. Price differentiation rests on organic certification layering under USDA National Organic Program standards and heat-stable formulation premiums for restaurant procurement. Pricing pressure stems from enzyme patent expirations redistributing competitive advantage toward process-scale efficiency. Foodservice operators exhibit lowest price sensitivity due to menu standardization mandates, while price-conscious household segments in secondary markets drive private-label substitution.
Supply Chain Analysis
Export-control regimes on precision fermentation biotechnology limit lactase enzyme flows from Bavaria's dairy technology cluster to non-EU processors, constraining supply expansion. Manufacturing concentrates in the United States, Germany, and Canada, with raw material dependencies on fluid dairy commodities, specialized enzyme formulations, and cold-chain packaging materials. Supply chain risk centers on single-source vulnerability in European biotechnology suppliers for next-generation lactase treatments. Distribution runs through refrigerated rail networks connecting Midwest production clusters to coastal population centers, with direct-to-consumer platforms bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where subscription replenishment algorithms and chef training programs for cooking ingredient applications expand faster than commodity tub formats. Recurring revenue layers in direct-to-consumer channels and foodservice technical support outpace hardware-like product margins.
For Market Incumbents: Build dedicated facility networks as a moat against margin compression from licensed-enzyme competitors. Green Valley Creamery's multi-facility lactose-free infrastructure exemplifies this defensive posture. Incumbents should consolidate backward integration into cold-chain logistics while investing in continuous-flow enzyme dosing patents before expiration waves democratize access. Threat substitution from plant-based cultured alternatives demands texture-preservation R&D investment.
For New Entrants and Emerging Players: Secondary United States markets with refrigerated distribution infrastructure gaps present white-space entry points where national brands lack cold-chain reach. Subscription replenishment platforms with sampling programs offer the most penetrable go-to-market angle, reducing customer acquisition costs through algorithm-driven reordering. Target heat-stable formulation segments where restaurant procurement departments seek unified conventional and lactose-free supplier relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-scale continuous-flow enzyme dosing installations, enabling regional processors to achieve national-network cost parity. Long-term viability favors acquisition targets with organic certification infrastructure and established foodservice technical support capabilities. The signal to watch is consolidation patterns among enzyme biotechnology licensors as patent cliffs approach.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Enzyme Dosing Installation | Mid-scale United States and German facilities reduce holding tank requirements while accelerating production cycles. |
| Subscription Replenishment Platform Launch | Direct-to-consumer algorithms capture recurring household purchases while reducing trial barriers through sampling. |
| Organic Certification Layering Investment | USDA National Organic Program standards command specialty retail price premiums when combined with lactose-free claims. |
| Foodservice Technical Support Expansion | Chef training and recipe development support for cooking ingredient segments differentiates from commodity cream formats. |
| Cold-Chain Distribution Partnership | Union Pacific refrigerated rail network access connects Midwest production to coastal metropolitan demand centers. |
Research Methodology
A standing panel of dairy processing plant managers, enzyme technology procurement leads, restaurant chain menu development directors, and natural-channel retail category buyers provided ongoing calibration. Primary interviews combined with secondary validation from FDA 21 CFR 131 filings, USDA National Organic Program certification databases, EU Regulation (EU) No 1169/2011 compliance records, and customs trade data. Bottom-up facility capacity assessments and top-down retail audit data triangulated volume estimates.
Scenario-bracketing framed projections across enzyme patent expiration timelines and cold-chain infrastructure buildout trajectories. Segmentation dimensions modeled include product type, packaging format, end user archetype, and distribution channel, with organic certification status and heat-stability formulation as industry-specific layers. CAGRs derived from historical volume trajectories adjusted for regulatory milestone impacts and foodservice procurement consolidation patterns. Forecast inputs incorporated cream commodity price volatility indices and subscription platform adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based cultured alternative entrants would shift outcomes. Material shifts in FDA dairy identity standard enforcement timelines or enzyme biotechnology export control expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
North America A2 Milk Market
Dairy Products
China Milk Protein Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Cream Powder Market
Dairy Products
United States Yogurt Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Camel Dairy Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Table Butter Market